
 Rail Mounted Gantry Crane Market | 2026-2036
Rail Mounted Gantry Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Mounted Gantry Crane Market Outlook
The gap between premium automated systems and commodity manual configurations is expanding as terminal operators face diverging throughput requirements. Konecranes leverages its automation portfolio to command positions in high-volume port installations. EMH, Inc. competes through specialized engineering for heavy-lift industrial applications. Gorbel, Inc. differentiates with ergonomic handling systems that extend into lighter-capacity warehouse segments.
A rail mounted gantry crane traverses fixed ground rails to position hoisting machinery over containers or bulk loads, typically achieving spans exceeding thirty meters and lifting heights above fifteen meters for intermodal operations. Double girder architectures dominate port installations where load ratings above fifty tons prove essential for post-Panamax vessel servicing. Single girder systems anchor warehouse and distribution center deployments where twenty-to-fifty-ton capacities balance capital efficiency with material throughput. Hybrid configurations are gaining traction in marine applications seeking diesel-electric flexibility during grid connectivity transitions.
OSHA crane standards, EU machinery directives with CE marking requirements, and ISO 4309 wire rope inspection protocols collectively shape equipment certification cycles and maintenance obligations for operators. Compliance with these frameworks determines market access timelines and influences replacement demand across aging installed bases. Stakeholders must monitor electrification mandates and automation interoperability standards as procurement criteria shift toward integrated terminal operating systems.
Market Dynamics
Terminal operators face a structural squeeze between vessel scale inflation and berth productivity mandates, forcing capital allocation toward automation-capable crane architectures that reconcile throughput density with electrification compliance.
Growth Catalysts
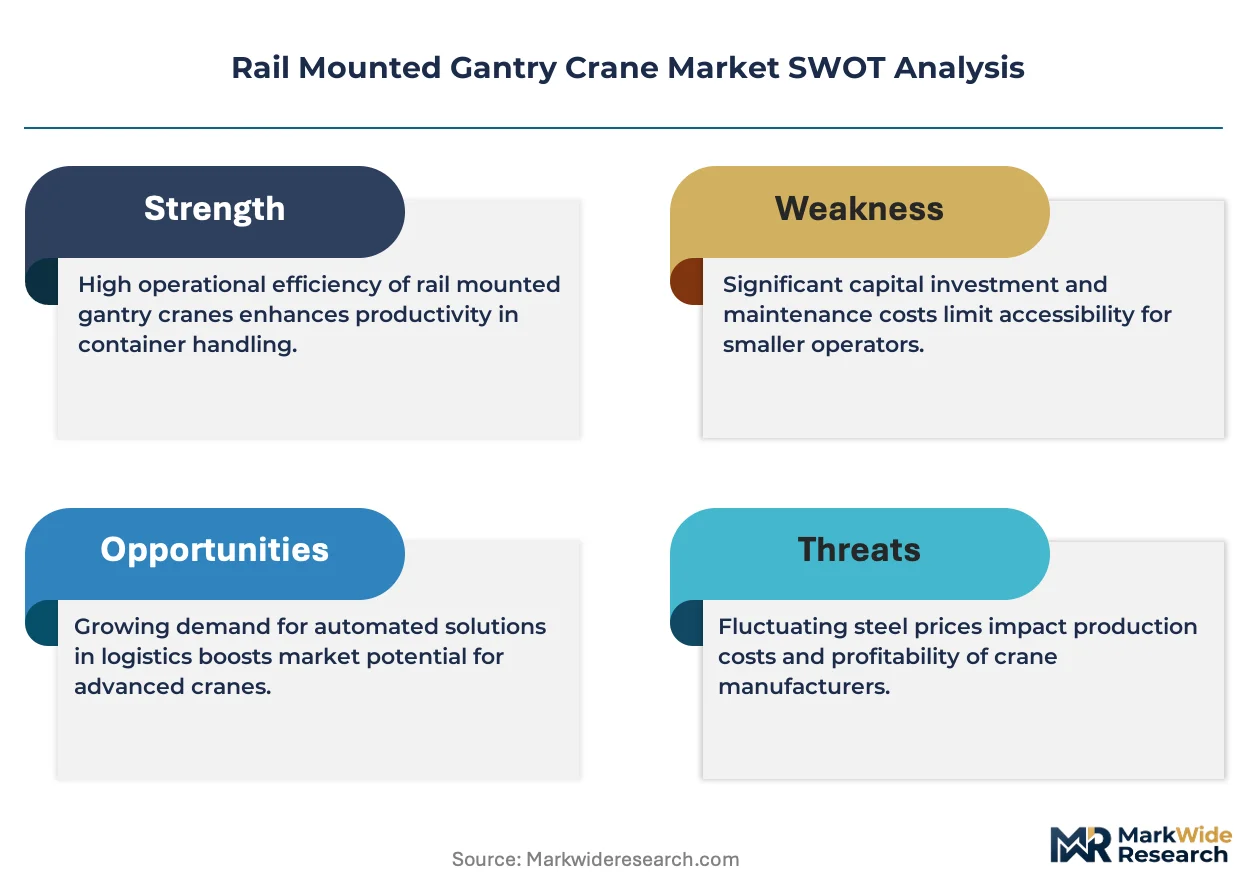
- EU Machinery Directive compliance cycles:CE marking requirements and updated safety protocols under the directive accelerate replacement of pre-2010 crane installations across European port authorities.
- Post-Panamax vessel servicing:Container lines deploying 24,000+ TEU vessels demand crane outreach beyond seventy meters and twin-lift capability, reshaping procurement specifications.
- China port modernization:Ningbo-Zhoushan, Shanghai Yangshan, and Qingdao port clusters drive double-digit annual crane orders as intermodal throughput targets tighten.
Market Restraints
- Steel price volatility:Structural steel constitutes 35-45% of crane bill-of-materials, exposing manufacturers to input cost swings that compress tender margins.
- Specialized bearing supply concentration:Slewing ring and rail wheel assemblies concentrate among German and Japanese suppliers, creating single-source vulnerability for large-span systems.
- Grid infrastructure lag:All-electric crane deployment outpaces shore power availability at secondary ports, forcing hybrid configurations that dilute operational efficiency gains.
Strategic Opportunities
- India Sagarmala port expansion:Jawaharlal Nehru Port Trust and Visakhapatnam Port Authority tender greenfield container terminal equipment with automation-ready specifications.
- Remote operator station convergence:Integration of 5G low-latency networks with augmented reality interfaces enables centralized crane control across multi-terminal footprints.
- US Inflation Reduction Act port electrification incentives:Tax credits for zero-emission cargo handling equipment accelerate all-electric procurement timelines at Los Angeles, Long Beach, and Savannah.
Industry Challenges
- Automation systems integration:Terminal operating system vendors and crane OEMs maintain proprietary communication protocols, forcing costly middleware development for unified fleet management.
- Certification timeline compression:OSHA crane inspection standards and ISO 4309 wire rope protocols demand documentation intensity that extends factory acceptance test periods by 15-20%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Mounted Gantry Crane Market |
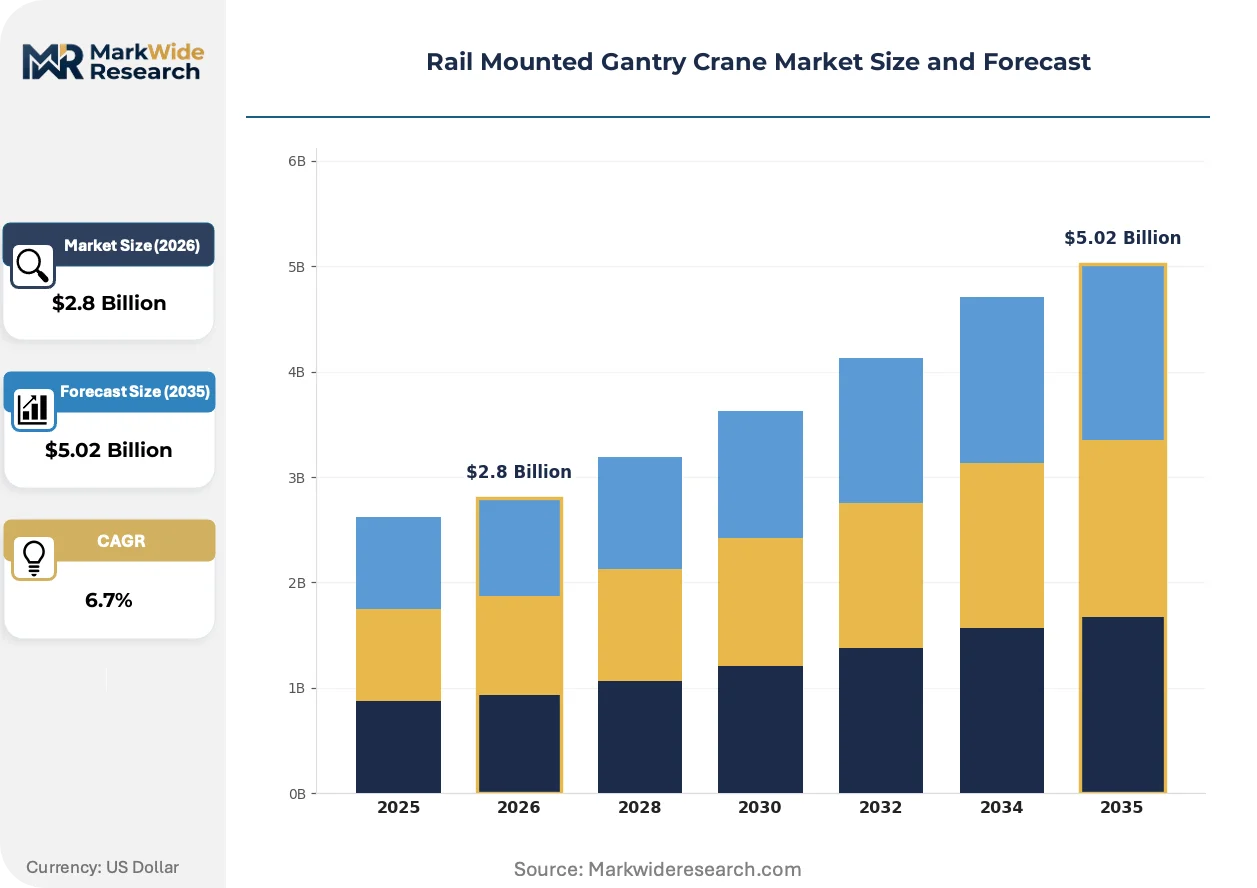
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Girder, Double Girder, Hybrid, Others Load Capacity: Up to 20 Tons, 20-50 Tons, 50-100 Tons, Above 100 Tons Application: Shipping Ports, Industrial Warehouses, Construction Sites, Distribution Centers End User: Manufacturing, Logistics, Marine, Infrastructure |
| Companies Covered | EMH, Inc., Gorbel, Inc., Konecranes, Heco Pacific MFG, T & M Equipment Co., Inc., NUCLEON, American Crane & Equipment Corp., Wallace Cranes, Columbus McKinnon Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Mounted Gantry Crane Market Strategic Shifts
Electrification pathways and digital twin architectures are redefining crane lifecycle economics, compressing the gap between mechanical reliability and software-defined performance optimization.
Regenerative drive systems with active front-end converters are absorbing kinetic energy from hoist and trolley deceleration, feeding recovered power back to terminal grids. Port operators in Rotterdam and Hamburg are retrofitting existing fleets with this technology to reduce peak demand charges. The structural consequence is a shift in total-cost-of-ownership calculations that favors electrified configurations even where diesel parity remains technically viable.
OSHA crane safety standards now mandate proximity detection and anti-collision systems for all new installations, extending compliance obligations to software update protocols. Terminal operators must integrate these systems with legacy fleet management platforms, creating integration service opportunities for automation specialists. US Gulf Coast and Pacific Northwest ports are experiencing the steepest compliance cost inflation as they consolidate older manual crane fleets.
Outcome-based maintenance contracts are displacing time-based service agreements as crane OEMs assume availability risk in exchange for performance-linked fees. Major container terminal operators in Singapore and Dubai are piloting these arrangements for critical-path quay crane fleets. The model concentrates most rapidly in high-throughput hubs where unplanned downtime costs exceed $100,000 per hour.
Rail Mounted Gantry Crane Market Segmentation
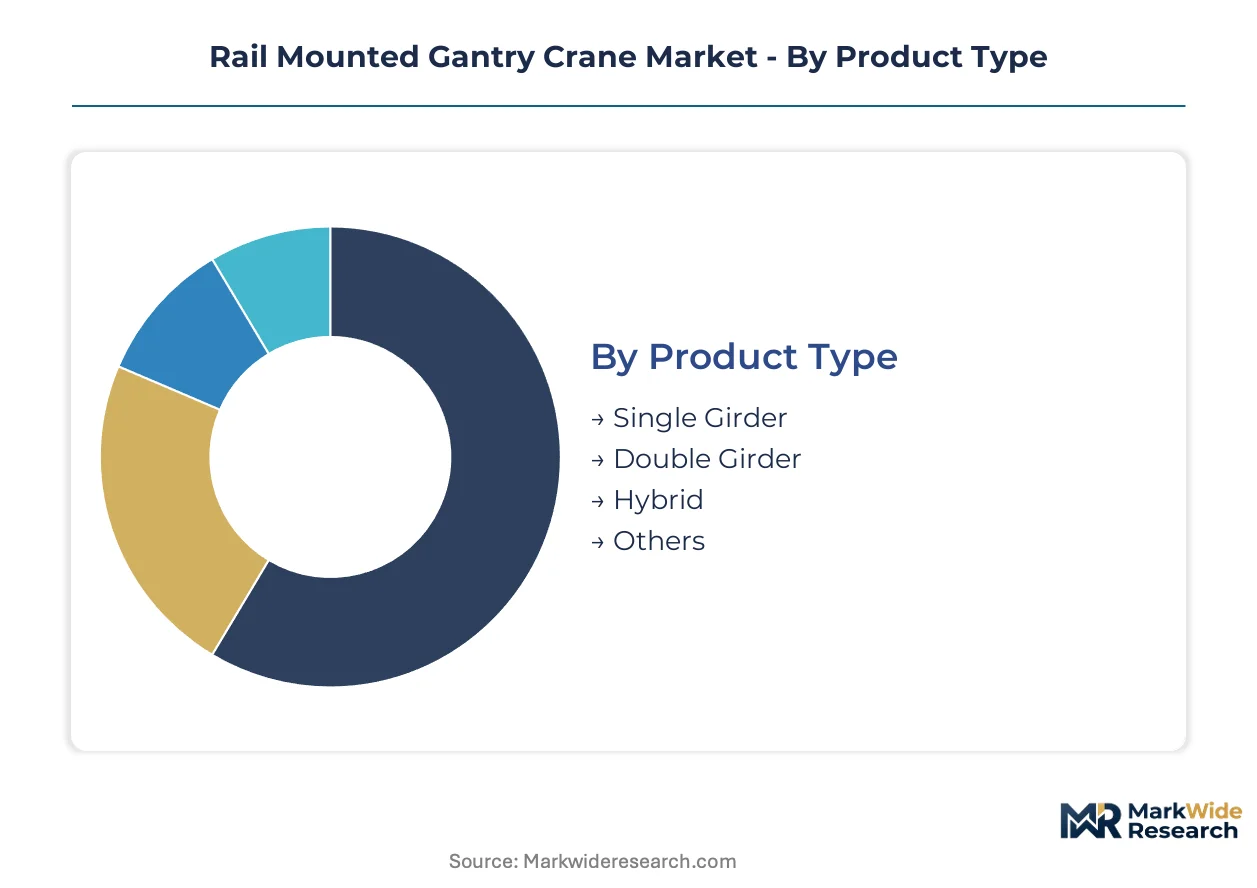
Rail mounted gantry crane procurement splits sharply between high-throughput port automation and cost-constrained warehouse handling. Specification divergence across product architecture, load rating, and end-use environment creates distinct competitive arenas with diverging margin structures and technology requirements.
Product Type:
Double girder systems command premium positioning through structural capacity, while single girder variants dominate volume procurement in lighter-duty installations.
- Double Girder:Twin-beam architectures achieve spans exceeding fifty meters with load ratings above fifty tons. Demand concentrates at Shanghai Yangshan and Rotterdam port terminals where post-Panamax vessel servicing mandates twin-lift capability and seventy-meter outreach.
- Single Girder:Mono-beam configurations optimize capital efficiency for twenty-to-fifty-ton applications. Warehouse operators in Germany and the United States specify these systems where ceiling height constraints and throughput density requirements favor compact footprints.
- Hybrid:Diesel-electric flexibility addresses grid infrastructure lag at secondary ports transitioning from fossil fuel dependency.
- Others:Specialized cantilever and underslung variants serve narrow-aisle manufacturing environments with non-standard building envelopes.
Mature deployment sits with double girder systems at established container terminals. Newer deployment is concentrated in hybrid configurations at ports navigating electrification timelines.
Load Capacity:
Capacity segmentation tracks the operational physics of intermodal handling, with vessel scale inflation pushing specification thresholds upward.
- Above 100 Tons:Ultra-heavy-lift architectures serve bulk commodity terminals and specialized breakbulk operations. Chinese port authorities at Ningbo-Zhoushan anchor demand as iron ore and coal throughput targets tighten.
- 50-100 Tons:Mid-heavy configurations balance structural investment against cargo mix flexibility. European port operators under EU machinery directive compliance cycles favor this tier for fleet standardization.
- 20-50 Tons:Light-intermediate ratings dominate distribution center and light manufacturing procurement where palletized cargo and container stuffing operations predominate.
- Up to 20 Tons:Compact systems serve workshop maintenance bays and small-scale warehousing with intermittent duty cycles.
Above 100-ton installations carry the steepest expansion trajectory as bulk commodity flows concentrate at deepwater terminals. Up to 20-ton systems face margin compression from commoditized supply.
Application:
Application segmentation reflects the fundamental divergence between marine cargo handling and land-based logistics infrastructure.
- Shipping Ports:Quay and yard crane installations face the most stringent automation and electrification mandates. Los Angeles and Long Beach terminal operators leverage US Inflation Reduction Act incentives to accelerate all-electric procurement.
- Distribution Centers:Intermodal rail yards and cross-dock facilities prioritize cycle time optimization over maximum lift capacity. German logistics hubs specify single girder systems with automated positioning for high-velocity container stripping.
- Industrial Warehouses:Manufacturing-integrated handling requires flexibility for non-containerized loads with frequent reconfiguration.
- Construction Sites:Temporary installations demand rapid deployment and modular transportability for prefabricated component placement.
Shipping port applications absorb the majority of OEM automation development investment. Distribution center specifications are climbing fastest as e-commerce fulfillment drives intermodal volume.
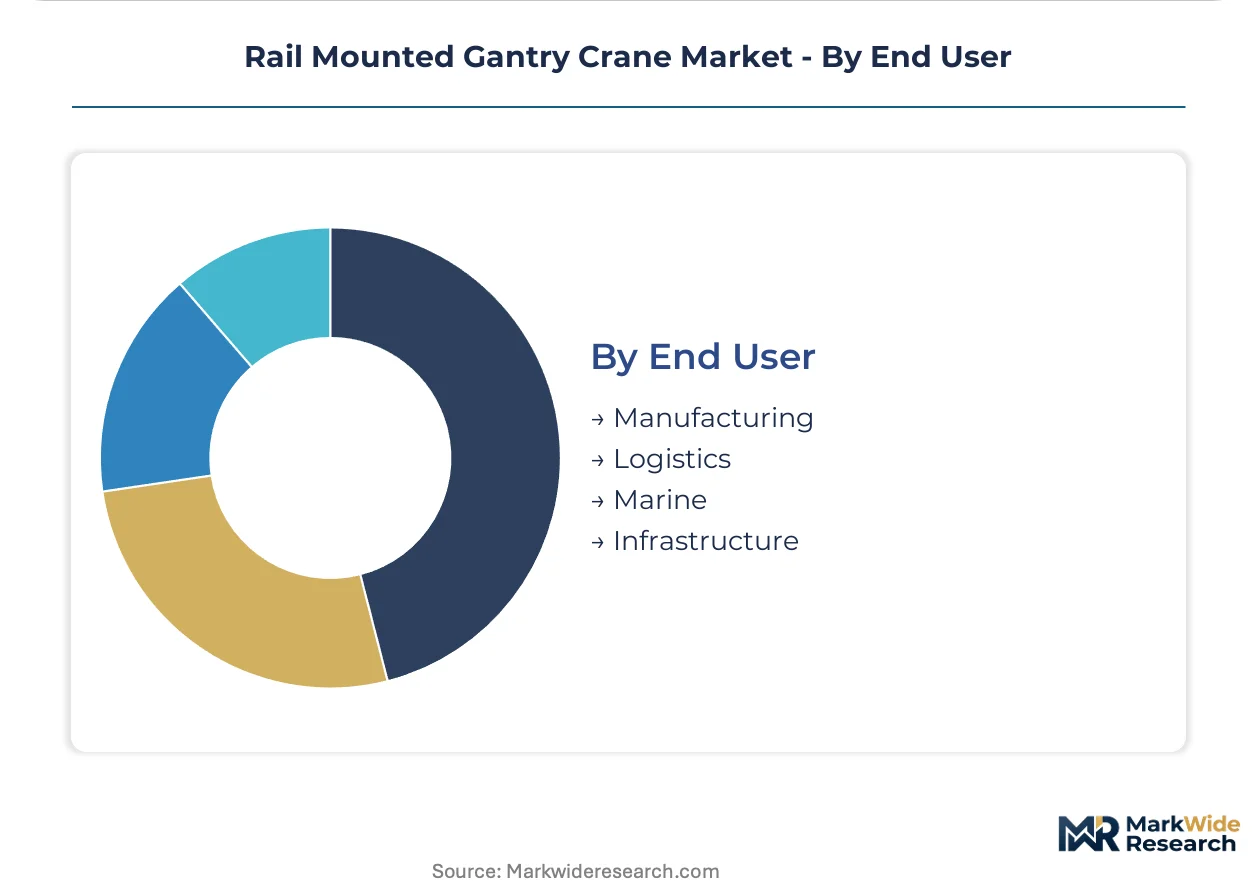
End User:
End user segmentation maps crane procurement to the capital allocation priorities of distinct industrial sectors.
- Marine:Terminal operating companies face berth productivity mandates that force automation-capable capital deployment. Singapore and Dubai port authorities pilot outcome-based maintenance contracts for critical-path crane fleets.
- Logistics:Third-party logistics providers optimize total-cost-of-ownership across multi-site fleets with standardized specifications.
- Manufacturing:Heavy industrial producers prioritize availability guarantees and integration with production scheduling systems.
- Infrastructure:Public port authorities balance procurement compliance transparency against long-term operational efficiency targets.
Marine end users command the deepest OEM engagement through integrated terminal operating system requirements. Infrastructure procurement is gaining sophistication as public-private partnership structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai Yangshan anchors the most intensive crane deployment activity as Chinese port clusters absorb the bulk of global container throughput expansion. Terminal operators across Rotterdam, Los Angeles, and Hamburg are simultaneously retrofitting electrification systems to meet tightening emission mandates.
China
Ningbo-Zhoushan and Qingdao port clusters drive double-digit annual crane orders as intermodal throughput targets tighten under national dual carbon goals. SAMR certification requirements and GB standards for heavy machinery accelerate replacement cycles for pre-2015 installations. Shanghai Yangshan terminal operators specify seventy-meter outreach systems for post-Panamax vessel servicing.
Germany
Hamburg and Bremerhaven port authorities face EU machinery directive compliance cycles that accelerate fleet modernization. CE marking requirements and updated safety protocols under the directive force replacement of pre-2010 crane installations. German bearing suppliers concentrate slewing ring and rail wheel assembly production, creating single-source vulnerability for large-span systems.
United States
Los Angeles and Long Beach terminal operators leverage IRA tax credits for zero-emission cargo handling equipment to accelerate all-electric procurement. OSHA crane inspection standards and proximity detection mandates extend factory acceptance test periods by 15-20%. Savannah port authorities are consolidating older manual crane fleets under steepest compliance cost inflation.
India
Jawaharlal Nehru Port Trust and Visakhapatnam Port Authority tender greenfield container terminal equipment with automation-ready specifications under Sagarmala port expansion. BIS certification timelines for imported heavy machinery compress procurement windows for foreign OEMs. Mumbai and Chennai industrial corridors are absorbing warehouse-grade single girder systems for distribution center buildouts.
Netherlands
Rotterdam terminal operators retrofit existing fleets with regenerative drive systems to reduce peak demand charges. EU Green Deal electrification mandates and F-Gas Regulation compliance shape equipment specification for all new installations. Eindhoven-based automation specialists are integrating 5G low-latency networks with augmented reality interfaces for centralized crane control.
Rail Mounted Gantry Crane Market Competitive Environment
Capital-heavy producers compete with asset-light engineering specialists across diverging procurement specifications. The market structure consolidates around three tiers: premium automation providers serving high-volume port installations, mid-market fabricators optimizing capital efficiency for warehouse segments, and regional specialists capturing heavy-lift industrial niches. Strategic archetypes include integrated terminal system vendors, component-focused bearing and drive suppliers, and aftermarket service consolidators. Dominant competitive moves center on automation interoperability partnerships and electrification retrofit service expansion.
Within the premium automation tier, Konecranes and Columbus McKinnon Corp. occupy positions emphasizing integrated control systems. EMH, Inc. and Gorbel, Inc. exemplify the specialized engineering archetype, with the former representing heavy-lift industrial applications and the latter anchoring ergonomic handling configurations for lighter-capacity warehouse segments. Chinese fabricators including NUCLEON and Zhengzhou-based specialists compete on capital efficiency for emerging market port authorities. American Crane & Equipment Corp. and Wallace Cranes sit within the regional service-intensive tier, emphasizing aftermarket availability and rapid deployment capabilities for construction and temporary installations.
| Leading Market Players |
|---|
| EMH, Inc. |
| Gorbel, Inc. |
| Konecranes |
| Heco Pacific MFG |
| T & M Equipment Co., Inc. |
| NUCLEON |
| American Crane & Equipment Corp. |
| Wallace Cranes |
| Columbus McKinnon Corp. |
| Others |
Value Chain & Pricing Dynamics
Post-Panamax vessel specifications mandating seventy-meter outreach and twin-lift capability are compressing procurement timelines for European and Chinese terminal operators, forcing crane OEMs to absorb steel price volatility and concentrate sourcing among qualified bearing suppliers with proven large-span track records.
Pricing Analysis
Availability-linked pricing anchors crane procurement as terminal operators in Singapore and Dubai pilot outcome-based maintenance contracts where OEMs assume uptime risk for performance-linked fees. Three-tier pricing structure across premium automation, mid-market fabricator, and economy-grade warehouse configurations separates Konecranes' integrated control systems from NUCLEON's capital-efficient offerings. Cost compression in the sub-fifty-ton warehouse segment is intensifying as Chinese fabricators expand export capacity. Third-party logistics providers exhibit the sharpest price sensitivity due to multi-site fleet standardization pressures, while marine terminal operators prioritize automation interoperability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for slewing ring and rail wheel assemblies are mandating parallel supplier qualification among German and Japanese bearing specialists, though production gravity still centers on these two geographies for large-span systems. Structural steel draws from Chinese and South Korean mills, while drive systems and active front-end converters source from German and Japanese electrical component manufacturers. Single-source vulnerability in specialized bearing supply creates procurement risk for seventy-meter outreach systems. Distribution runs through direct OEM-terminal operator relationships for port installations, with regional fabricator networks serving warehouse and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized bearing and drive component supply concentrates among qualified German and Japanese suppliers, propping pricing power for OEMs with established supplier relationships and certified large-span delivery records.
For Market Incumbents: Hedge against steel price volatility through long-term offtake agreements with Chinese and South Korean mills while securing captive capacity at German bearing suppliers for post-Panamax crane architectures. Automation systems integration complexity threatens margin compression for fleet management platform development; backward integration into control system engineering preserves specification-setting authority. For New Entrants and Emerging Players: Digital-channel retrofit services for regenerative drive installation offer the most penetrable entry path, targeting Rotterdam and Hamburg terminal operators seeking peak demand charge reduction without full fleet replacement. India's Sagarmala port expansion tenders present automation-ready greenfield opportunities with compressed BIS certification timelines favoring foreign OEMs with established certification pathways. Partner with Eindhoven-based automation specialists for 5G-integrated remote operator station deployment. For Investors and Strategic Acquirers: The window for entry favors component-focused bearing and drive suppliers with proven seventy-meter outreach delivery records, as crane OEMs seek to secure captive supply for post-Panamax specifications. Long-term viability hinges on electrification retrofit service capabilities expanding across secondary ports with grid infrastructure lag. Watch US Inflation Reduction Act port electrification incentive utilization rates at Los Angeles and Long Beach as inflection indicators for all-electric procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Supply | Secures captive capacity for seventy-meter outreach systems amid German-Japanese supplier concentration. |
| Regenerative Drive Retrofit Service Launch | Captures Rotterdam and Hamburg demand for peak demand charge reduction without full replacement. |
| Automation Interoperability Partnership | Resolves terminal operating system protocol fragmentation forcing costly middleware development. |
| India Greenfield Certification Pathway Investment | Compresses BIS timelines for Jawaharlal Nehru Port Trust and Visakhapatnam tenders under Sagarmala. |
| Outcome-Based Maintenance Contract Pilot | Shifts availability risk to OEMs in exchange for performance-linked fees at Singapore and Dubai hubs. |
Study Parameters
Trade publications, customs databases, and OEM technical documentation formed the secondary backbone, supplemented by primary interviews with terminal operations directors, port authority procurement leads, crane maintenance heads, and automation systems integrators. Bottom-up unit economics triangulated against top-down port throughput projections validated volume estimates across the analysis window.
Bottom-up modeling anchored forecasts in individual terminal operator capex disclosures and port authority tender documentation, while top-down verification cross-checked against intermodal throughput targets at Ningbo-Zhoushan, Shanghai Yangshan, and Rotterdam. Segmentation dimensions included product architecture, load capacity tier, application environment, and end-user capital allocation priority. CAGRs derived from equipment replacement cycles under OSHA and EU machinery directive compliance timelines, with electrification mandate acceleration and vessel scale inflation as key demand shapers.
The model holds under stable regulatory compliance timelines and continued post-Panamax vessel deployment; deviation in shore power infrastructure buildout pace or steel price volatility spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Global Lifting Columns Market