
 Broaching Machine Market | 2026-2036
Broaching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Broaching Machine Market Analysis
The shift from single-source to multi-source broaching tool procurement is hardening across North American and European supply chains. Colonial Tool Group Inc. leverages its Canadian manufacturing base to serve cross-border automotive programs with reduced tariff exposure. MITSUBISHI HEAVY INDUSTRIES, LTD. anchors its broaching division within a broader machine tool portfolio that sustains R&D spending through captive aerospace demand. American Broach & Machine Company differentiates through dedicated pull broaching expertise for heavy truck transmission producers.
A broaching machine is a metal-cutting machine tool that uses a toothed tool, or broach, to remove material through linear motion, typically achieving tolerances of ±0.025 mm and surface finishes down to 0.4 micrometers Ra in a single pass. Its primary industrial purpose is producing precision internal and external profiles—splines, keyways, gears, and contoured surfaces—in high-volume manufacturing environments where milling or grinding would require multiple operations. Horizontal broaching machines dominate automotive transfer lines for their ergonomic loading and chip evacuation advantages, while pull broaching machines capture the fastest growth trajectory as EV gearboxes demand finer pitch accuracy and harder cutting loads. Electric broaching technology is displacing hydraulic systems in cleanroom-sensitive aerospace applications, though hydraulic units retain margin pools in heavy construction equipment where force requirements exceed 50 tons.
OSHA machine guarding standards in the United States, CE marking requirements under the EU Machinery Directive, and ISO 230-1 geometric accuracy test codes collectively shape product design cycles and market access timelines for broaching equipment manufacturers. Japan's METI energy-efficiency benchmarks for machine tools are pushing Japanese builders toward servo-electric ball-screw drives that reduce idle power draw. Stakeholders must weigh whether to prioritize electric actuation investments for regulatory compliance or preserve hydraulic platforms for emerging-market cost sensitivity.
Market Dynamics
Pull broaching systems are capturing disproportionate investment as electric vehicle powertrains demand finer pitch accuracy and harder cutting loads than conventional internal combustion architectures require. This technology migration is compressing the viable lifecycle of hydraulic platforms while elevating servo-electric ball-screw architectures.
Growth Catalysts
- ISO 230-1 geometric accuracy test codes:Tightening international standards for machine tool verification are disqualifying legacy mechanical broaching systems from Tier 1 automotive supplier qualification lists.
- EV gearbox complexity:Electric vehicle powertrains require helical gear sets with 40% tighter tolerance bands than conventional transmissions, mandating CNC-controlled pull broaching for volume production.
- Southern Germany automotive corridor:Concentrated demand from BMW, Mercedes-Benz, and Volkswagen assembly networks is sustaining above-average capacity utilization for precision broaching service providers.
Market Restraints
- Specialized alloy input costs:High-speed steel and cobalt-based broach materials face price volatility tied to mining supply concentration in the Democratic Republic of Congo and Russia.
- Single-source broach geometry risk:Proprietary tooth profiles locked to original equipment manufacturer specifications create supply concentration exposure when sole-source tooling suppliers face capacity constraints.
- Hydraulic fluid environmental compliance:EPA spill prevention requirements and EU REACH substance restrictions are adding compliance overhead to legacy hydraulic broaching installations.
Strategic Opportunities
- India automotive component manufacturing:PLI scheme incentives for advanced automotive technology are attracting broaching capacity investments to serve export-oriented gear producers near Chennai and Pune.
- Aerospace cleanroom broaching:Electric broaching technology eliminates hydraulic fluid contamination risks, opening precision titanium and nickel alloy machining contracts for engine disk and structural component suppliers.
- Retrofit servo-electric conversion kits:Machine tool integrators are packaging ball-screw actuation and CNC control upgrades to extend hydraulic broaching asset life while meeting METI energy-efficiency benchmarks.
Industry Challenges
- CNC broaching programming expertise:The transition from mechanical to servo-electric platforms requires process engineers capable of optimizing cutting parameters across variable workpiece hardness and geometry complexity.
- CE marking conformity assessment timelines:EU Machinery Directive compliance documentation for new broaching installations extends market access lead times by four to eight months for non-European builders.
- Legacy hydraulic system integration:Mixed-fleet manufacturers face synchronization challenges when connecting pre-2010 hydraulic broaching cells to modern manufacturing execution systems and quality data pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broaching Machine Market |
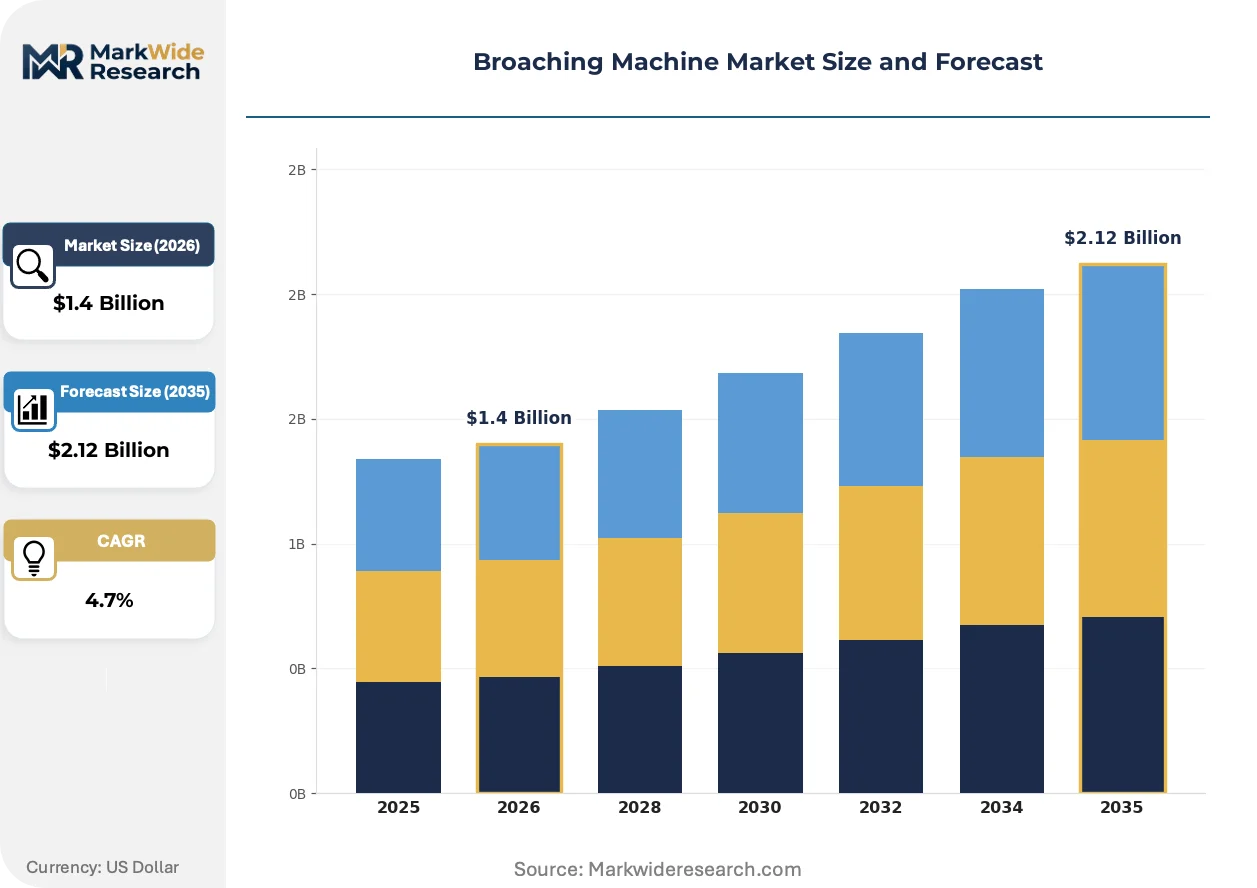
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Broaching Machines, Vertical Broaching Machines, Push Broaching Machines, Pull Broaching Machines End User: Automotive Manufacturing, Aerospace Industry, Construction Equipment, Tool and Die Making Technology: Electric Broaching, Hydraulic Broaching, Pneumatic Broaching, Manual Broaching Application: Gear Production, Keyway Cutting, Hole Sizing, Surface Finishing |
| Companies Covered | The Ohio Broach & Machine Co., Colonial Tool Group Inc., MITSUBISHI HEAVY INDUSTRIES, LTD., American Broach & Machine Company, General Broach Company, Apex Broaching Systems, Pioneer Broach Co., Axisco Precision Machinery Co., Ltd., Broaching Machine Specialties, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broaching Machine Market Emerging Trajectories
Broaching equipment architecture is bifurcating between cleanroom-compatible electric systems and force-dense hydraulic platforms, with control system intelligence becoming the decisive competitive variable rather than mechanical design alone.
Adaptive tool wear compensation algorithms are integrating real-time spindle load monitoring with automatic feed rate adjustment to maintain dimensional stability across extended cutting cycles. Japanese and German automotive suppliers are deploying these systems at scale for helical gear broaching operations where tooth profile deviation must stay within 5 micrometers across 10,000-piece production runs. This capability is integrating quality assurance directly into the cutting process, reducing post-machining inspection overhead and enabling unattended overnight production.
Japan's METI energy-efficiency benchmarks for machine tools are mandating idle power draw reductions that hydraulic systems cannot achieve without extensive redesign. Builders are responding with servo-electric ball-screw drives that cut standby consumption by 60-80% compared to continuously circulating hydraulic power units. Aerospace machining facilities in Nagoya and Fukuoka prefectures are prioritizing electric broaching platforms for new capacity despite 15-25% higher capital outlays.
Automotive tier-one suppliers are consolidating broaching tool procurement from single-source to approved-vendor lists with synchronized geometry certification. This pattern compresses supplier qualification timelines while elevating technical service expectations, favoring tooling houses with captive metallurgy laboratories and rapid regrind turnaround. The shift is most visible in southern Germany, where BMW and Mercedes-Benz powertrain divisions now mandate dual-source redundancy for all critical spline and gear broaching operations.
Broaching Machine Market Segmentation
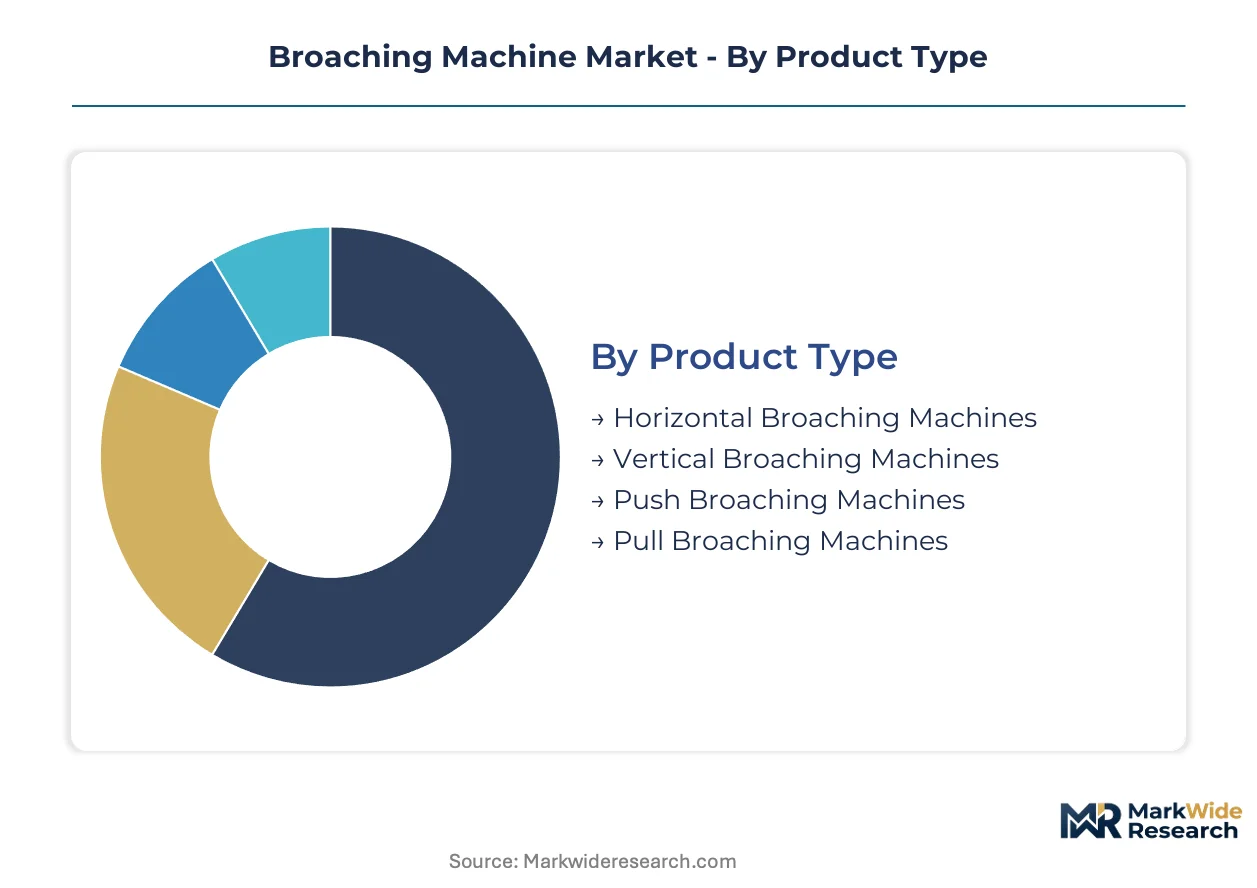
Broaching machine segmentation reveals how technology choices cascade through manufacturing economics. Product architecture, powertrain specifications, and end-use precision requirements create distinct competitive arenas with diverging margin structures and equipment lifecycles.
Product Type:
Machine orientation and tool engagement mechanics define capital allocation patterns across automotive and aerospace production networks.
- Horizontal Broaching Machines:These systems position the broach horizontally for ergonomic workpiece loading and efficient chip evacuation. Demand concentrates in German automotive transfer lines serving BMW and Mercedes-Benz powertrain divisions, where continuous production cycles favor horizontal configurations for operator safety and throughput.
- Pull Broaching Machines:Tensile tool engagement achieves finer pitch accuracy through reduced deflection under cutting loads. Electric vehicle gearbox producers in Japan's Aichi prefecture are prioritizing CNC-controlled pull systems for helical gear sets requiring 40% tighter tolerance bands than conventional transmissions.
- Vertical Broaching Machines:Gravity-assisted chip removal suits heavy-duty applications with large workpiece envelopes.
- Push Broaching Machines:Compressive tool engagement remains cost-effective for short-run keyway operations in maintenance shops.
Mature deployment sits with horizontal platforms in established automotive corridors. Newer deployment is concentrated in pull broaching systems for EV powertrain manufacturing.
End User:
Industry-specific precision requirements and production volumes shape equipment specification priorities across buyer segments.
- Automotive Manufacturing:High-volume spline, gear, and shaft production for transmissions and drivelines demands automated loading and statistical process control integration. Southern Germany's tier-one supplier cluster—feeding Volkswagen, BMW, and Mercedes-Benz assembly networks—sustains above-average capacity utilization for precision broaching service providers.
- Aerospace Industry:Titanium and nickel alloy machining for engine disks and structural components requires electric broaching platforms that eliminate hydraulic fluid contamination risks. METI energy-efficiency benchmarks are accelerating electric platform adoption in Nagoya and Fukuoka prefectures despite 15-25% capital premiums.
- Construction Equipment:Heavy transmission and axle component production retains hydraulic platforms where force requirements exceed 50 tons.
- Tool and Die Making:Low-volume, high-variety work favors flexible manual and pneumatic systems for prototype and repair operations.
Capital intensity peaks in automotive with dedicated transfer lines. Aerospace procurement is climbing fastest as electric platforms penetrate cleanroom-sensitive applications.
Technology:
Actuation architecture determines regulatory compliance pathways and operating cost structures across installed base decisions.
- Electric Broaching:Servo-electric ball-screw drives cut standby power consumption by 60-80% versus hydraulic systems. Japan's METI energy-efficiency mandates are pushing builders toward electric platforms that satisfy idle power draw requirements hydraulic units cannot meet without extensive redesign.
- Hydraulic Broaching:Force density advantages persist in heavy construction equipment applications. EPA spill prevention requirements and EU REACH substance restrictions are adding compliance overhead to legacy hydraulic installations.
- Pneumatic Broaching:Compressed air actuation serves light-duty applications with lower capital barriers.
- Manual Broaching:Hand-operated systems retain niche positions in toolroom and maintenance environments.
Regulatory pressure is compressing the viable lifecycle of hydraulic platforms. Electric architectures are capturing disproportionate investment in ISO 230-1 compliance-focused supplier qualifications.
Application:
Workpiece geometry complexity and tolerance specifications determine equipment selection and process integration requirements.
- Gear Production:Helical and spur gear broaching for transmissions demands CNC-controlled systems with adaptive tool wear compensation. Japanese and German automotive suppliers deploy real-time spindle load monitoring with automatic feed rate adjustment to maintain 5-micrometer tooth profile deviation across 10,000-piece production runs.
- Keyway Cutting:Internal slot machining for shafts and hubs represents high-volume, standardized work. Pull broaching systems capture this application fastest as EV powertrains multiply splined component counts per vehicle.
- Hole Sizing:Precision bore finishing achieves tight cylindrical tolerances in a single pass.
- Surface Finishing:Contour broaching generates complex external profiles for specialized mechanical components.
Gear production commands the highest equipment specification intensity. Keyway cutting is expanding most quickly alongside electric vehicle powertrain complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-speed steel and cobalt-based broach material supply chains anchor geographic demand concentration in mining-adjacent manufacturing corridors. Regulatory pressure on machine tool energy efficiency and precision standards is redistributing capacity investments across established automotive clusters and emerging component manufacturing zones.
Germany
Precision gear production for BMW, Mercedes-Benz, and Volkswagen powertrain divisions drives sustained horizontal broaching capacity utilization. CE marking requirements under the EU Machinery Directive extend qualification timelines for non-European equipment suppliers. The southern Germany automotive corridor, particularly around Stuttgart and Munich, concentrates tier-one supplier broaching operations feeding final assembly networks.
Japan
Helical gear broaching for electric vehicle powertrains demands CNC-controlled pull systems with adaptive tool wear compensation. METI energy-efficiency benchmarks mandate idle power draw reductions that favor servo-electric ball-screw architectures over hydraulic platforms. Nagoya and Fukuoka prefectures prioritize electric broaching installations for aerospace titanium and nickel alloy machining despite capital premiums.
United States
Heavy truck transmission producers sustain demand for dedicated pull broaching expertise in the Midwest manufacturing belt. OSHA machine guarding standards shape product design cycles and market access timelines for domestic and imported equipment. The Ohio-Michigan automotive corridor anchors American Broach & Machine Company's specialized operations serving commercial vehicle powertrain manufacturers.
India
PLI scheme incentives for advanced automotive technology attract broaching capacity investments targeting export-oriented gear producers. The country's national industrial policy regulator channels subsidies toward precision component manufacturing clusters near Chennai and Pune. These emerging hubs supply European and North American automotive OEMs with splined shafts and transmission gears requiring ISO 230-1 compliant machining.
Canada
Cross-border automotive program servicing benefits from reduced tariff exposure through integrated North American supply chains. Health Canada's machinery safety standards align with OSHA frameworks while maintaining distinct documentation requirements. Colonial Tool Group leverages its Ontario manufacturing base to serve US-based OEM qualification lists with synchronized geometry certification protocols.
Broaching Machine Market Vendor Landscape
Capacity expansion dominates the current landscape as electric vehicle powertrain complexity forces retooling decisions across installed bases. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive aerospace demand, specialized broaching houses with dedicated pull system expertise, and cross-border fabricators leveraging geographic positioning for tariff optimization. M&A activity and strategic partnerships concentrate among tier-one automotive supplier qualification requirements, while technology licensing agreements accelerate servo-electric platform diffusion.
Among North American specialists, The Ohio Broach & Machine Co. and American Broach & Machine Company occupy positions within the dedicated broaching house archetype, with the latter exemplifying pull system specialization for heavy commercial vehicle applications. Colonial Tool Group represents the cross-border fabricator model, anchoring Canadian manufacturing capacity to serve integrated automotive programs. MITSUBISHI HEAVY INDUSTRIES, LTD. sits within the diversified conglomerate tier, sustaining equipment development through broader machine tool and aerospace portfolio synergies.
| Leading Market Players |
|---|
| The Ohio Broach & Machine Co. |
| Colonial Tool Group Inc. |
| MITSUBISHI HEAVY INDUSTRIES, LTD. |
| American Broach & Machine Company |
| General Broach Company |
| Apex Broaching Systems |
| Pioneer Broach Co. |
| Axisco Precision Machinery Co., Ltd. |
| Broaching Machine Specialties |
| Others |
Supply Flow & Price Mechanics
Skilled CNC programming labor concentrated in Japan's Aichi prefecture and southern Germany feeds labor-cost differentials that widen pricing spreads between premium servo-electric platforms and standard hydraulic configurations.
Pricing Analysis
Warranty and service-bundling arrangements separate premium-tier builders from value-oriented competitors, with extended maintenance contracts and rapid regrind guarantees bundled into Japanese and German OEM quotations while North American suppliers unbundle these for à-la-carte procurement. Pricing stratifies across premium CNC-controlled pull systems, standard horizontal hydraulic platforms, and economy-grade push broaching equipment for maintenance shops. Cost compression in mid-tier hydraulic segments intensifies as METI energy-efficiency mandates accelerate electric platform preference among Japanese automotive suppliers. Tier-one automotive procurement teams exhibit lowest price sensitivity, prioritizing ISO 230-1 compliance and dual-source redundancy over capital expenditure minimization.
Supply Chain Analysis
High-speed steel and cobalt-based broach material supply rests on mining concentration in the Democratic Republic of Congo and Russia, with secondary refining capacity anchored in Germany and Japan. Broaching machine builders draw from these concentrated alloy streams for cutting tool production, while servo-electric ball-screw actuation components source primarily from Japanese and German precision motion suppliers. Single-source vulnerability in specialty alloy procurement creates exposure when sole-source tooling suppliers face capacity constraints. Distribution runs through direct OEM qualification programs for automotive tier-one suppliers, with aftermarket service parts flowing through authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The broaching machine market sits in a technology-transition phase as servo-electric ball-screw architectures displace hydraulic platforms under regulatory pressure from Japan's METI energy-efficiency benchmarks.
For Market Incumbents: Hedge against hydraulic platform obsolescence by accelerating servo-electric R&D investment while maintaining legacy service revenue through retrofit conversion kits. Defensive consolidation of captive metallurgy laboratories preserves tooling qualification advantages as BMW and Mercedes-Benz procurement teams mandate dual-source redundancy for critical spline operations. For New Entrants and Emerging Players: Maintenance shops and independent gear producers in India's PLI-subsidized Chennai and Pune corridors represent an underserved buyer archetype with unmet demand for ISO 230-1 compliant pull broaching at capital expenditure levels below German and Japanese premium tiers. White-space capture demands localized technical service partnerships and rapid regrind turnaround capabilities rather than equipment-only sales. For Investors and Strategic Acquirers: Re-rating potential sits with specialized broaching houses possessing dedicated pull system expertise given electric vehicle powertrain complexity forcing retooling decisions across installed bases. Long-term viability favors acquisition targets with captive aerospace demand sustaining R&D through cyclical downturns. Watch Japanese automotive supplier qualification list expansion as the inflection indicator for platform technology preference consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Servo-Electric Conversion | Extends hydraulic asset life while satisfying METI idle power draw mandates for Japanese suppliers. |
| Dual-Source Tooling Qualification | Meets BMW and Mercedes-Benz procurement redundancy requirements for critical spline operations. |
| India Manufacturing Footprint | Captures PLI scheme incentives serving export-oriented gear producers near Chennai and Pune. |
| Aerospace Cleanroom Certification | Opens precision titanium machining contracts for engine disk suppliers in Nagoya and Fukuoka. |
| Captive Metallurgy Laboratory | Accelerates broach regrind turnaround for approved-vendor list synchronization with automotive OEMs. |
Methodological Framework
Independent corroboration across plant engineers at tier-one automotive suppliers, maintenance directors at heavy truck transmission producers, and aftermarket service heads at broaching equipment distributors underwrites the qualitative findings. Primary fieldwork combined structured interviews with OEM procurement teams and CNC programming specialists with secondary validation from SEC 10-K filings, customs and trade data for high-speed steel and cobalt alloy flows, and ISO 230-1 certification databases. Bottom-up equipment shipment tallies triangulate against top-down automotive production forecasts for transmission and driveline component counts.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product architecture, actuation technology, end-use industry, and regional production cluster. The modeling framework incorporates electric vehicle powertrain penetration assumptions, METI energy-efficiency compliance timelines, and ISO 230-1 geometric accuracy standard adoption curves. CAGRs derive from installed base replacement cycles, capacity utilization rates at precision broaching service providers, and supplier qualification list expansion patterns.
Revisions become necessary when Japanese automotive OEMs accelerate electric platform mandates, when cobalt alloy supply disruptions extend broach material lead times, or when CE marking conformity assessment timelines shift under EU Machinery Directive updates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Boring Bar Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Boom Cranes Market
Construction Equipment
Europe Ground Penetrating Radar Market