
 Australia Mobile Cranes Rental Market | 2026-2036
Australia Mobile Cranes Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Mobile Cranes Rental Market Outlook
High-strength steel is recalibrating mobile crane boom economics across Australian rental fleets, reducing weight while extending reach specifications. Mammoet Australia leverages its heavy-lift engineering pedigree to dominate energy sector contracts. Kennards Hire sustains national coverage through branch density in metropolitan and regional hubs. Boom Logistics Ltd anchors its position in resources infrastructure via specialized maintenance services.
Australia mobile cranes rental encompasses short-term and long-term provision of self-propelled lifting equipment with telescopic or lattice booms, typically rated from under 30 tons to over 100 tons capacity, deployed across construction sites, mining operations, and energy facilities where capital ownership is uneconomical. All terrain cranes command premium rental rates due to their dual-road-and-site mobility, while rough terrain cranes capture volume in mining applications where ground conditions preclude conventional truck-mounted units. Short-term rental generates the highest transaction frequency, though long-term rental and lease-to-purchase structures lock in margin stability for fleet operators serving multi-year infrastructure timelines.
Safe Work Australia administers crane licensing and inspection protocols under the Work Health and Safety Act, while state-based occupational regulators in Queensland and Western Australia enforce site-specific compliance that shapes equipment specification requirements. TGA-equivalent machinery standards and Australian Design Rules for vehicle-mounted cranes create technical barriers that filter rental fleet composition toward certified configurations. Stakeholders must monitor how proposed federal infrastructure pipeline commitments and state-level planning reforms recalibrate regional crane demand before committing fleet expansion capital.
Market Dynamics
Western Australia's mining automation push is forcing rental fleet operators to reconfigure crane specifications for autonomous haulage maintenance, while Queensland's LNG megaproject pipeline locks in multi-year lifting demand that favors lease structures over spot rentals.
Growth Catalysts
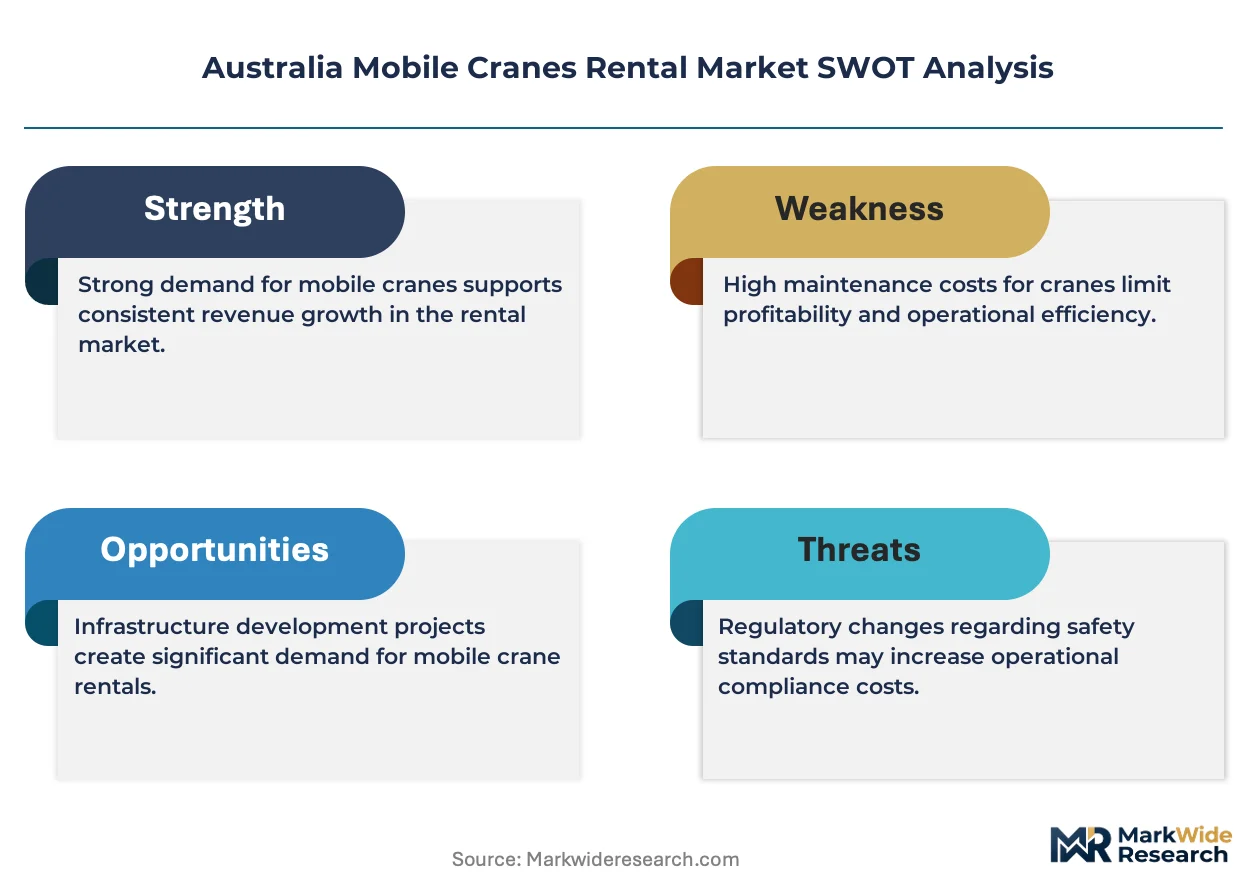
- Work Health and Safety Act mandates:Independent equipment certification requirements tighten compliance standards, filtering out subscale operators and consolidating demand toward certified rental providers with documented inspection protocols.
- High-strength steel boom technology:Weight reduction and extended reach specifications enable single-crane solutions where tandem lifts were previously required, improving utilization rates across construction and energy sites.
- Gladstone LNG precinct concentration:Megaproject timelines near Queensland's liquefied natural gas facilities require flexible lifting capacity that capital ownership cannot match, sustaining premium rental rates.
Market Restraints
- Specialized operator certification costs:Safe Work Australia's crane licensing protocols and state-based occupational regulator requirements in Western Australia create fixed compliance burdens that compress margins for short-term rentals.
- All-terrain crane supply concentration:Premium dual-mobility units face limited domestic manufacturing, forcing reliance on imported European and Japanese equipment exposed to currency volatility and extended lead times.
- Rough terrain unit technical limitations:Mining ground conditions in Pilbara and Bowen Basin sites restrict conventional truck-mounted deployment, segmenting fleet investment toward lower-utilization specialized configurations.
Strategic Opportunities
- Lease-to-purchase structures:Multi-year infrastructure timelines in New South Wales and Victoria enable margin-locked contracts that convert rental relationships into equipment sales, capturing value from contractor capital constraints.
- Maintenance service bundling:Resources infrastructure operators in Western Australia seek integrated lifting and mechanical services, creating scope for rental providers to expand into specialized maintenance contracts.
- Branch density in regional hubs:Metropolitan saturation pushes fleet deployment toward Queensland mining towns and South Australian renewable energy zones where local crane availability remains constrained.
Industry Challenges
- Certified rigger and dogger talent pipeline:High-risk work licensing requirements under Safe Work Australia create recruitment bottlenecks that limit fleet expansion velocity regardless of equipment availability.
- Australian Design Rules compliance timelines:Vehicle-mounted crane certification processes extend equipment commissioning periods, compressing effective rental windows during peak construction seasons.
- Fleet reconfiguration capex intensity:Transition toward high-strength steel booms and autonomous-compatible specifications demands concentrated capital deployment amid uncertain federal infrastructure commitment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Mobile Cranes Rental Market |
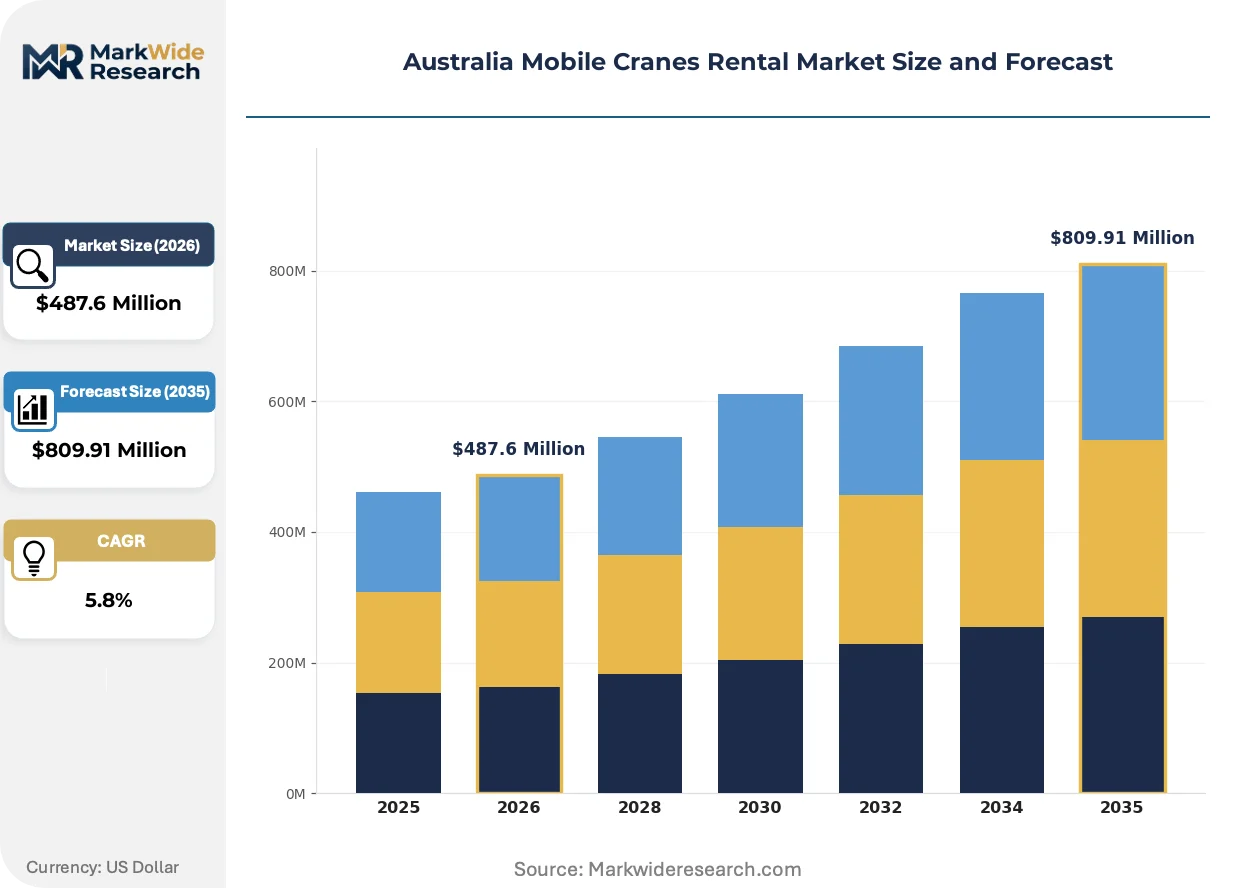
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Cranes, Rough Terrain Cranes, Truck Mounted Cranes, All Terrain Cranes End User: Construction, Oil & Gas, Mining, Infrastructure Service Type: Short-Term Rental, Long-Term Rental, Lease-to-Purchase, Maintenance Services Capacity: Under 30 Tons, 30-50 Tons, 51-100 Tons, Over 100 Tons |
| Companies Covered | Mammoet Australia, Kennards Hire, Boom Logistics Ltd, Borger Cranes, Premier Cranes & Rigging, Tutt Bryant Group, WGC Cranes, MARR Contracting, Freo Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Mobile Cranes Rental Market Strategic Shifts
Telematics-enabled fleet management and predictive maintenance protocols are compressing equipment downtime and reshaping how rental operators price availability guarantees across Australian construction and resources sites.
High-strength steel alloys in telescopic boom construction are integrating advanced metallurgy with computer-aided design to extend reach-to-weight ratios. Mining contractors in Western Australia's Pilbara region are specifying these configurations for autonomous haulage maintenance tasks. The technology is integrating single-crane lifting solutions where engineered tandem lifts were previously mandatory, reducing site labor requirements and insurance exposure.
Safe Work Australia's harmonized crane licensing framework under the Work Health and Safety Act is tightening operator qualification standards and inspection documentation requirements. Queensland and Western Australian state regulators are enforcing site-specific compliance protocols that exceed federal baselines. Energy sector contractors in Gladstone's LNG precincts are responding by mandating third-party certification from rental providers, creating preference segmentation toward accredited fleet operators.
Contracting models are evolving from daily rate structures toward availability-based agreements with performance penalties for downtime. Major resources operators in Bowen Basin coal and Pilbara iron ore are unbundling crane services from broader construction packages to secure direct supplier relationships. This pattern concentrates procurement authority with site engineering teams rather than tier-one construction contractors, compressing vendor selection cycles and favoring rental providers with demonstrated regional response capability.
Australia Mobile Cranes Rental Market Segmentation
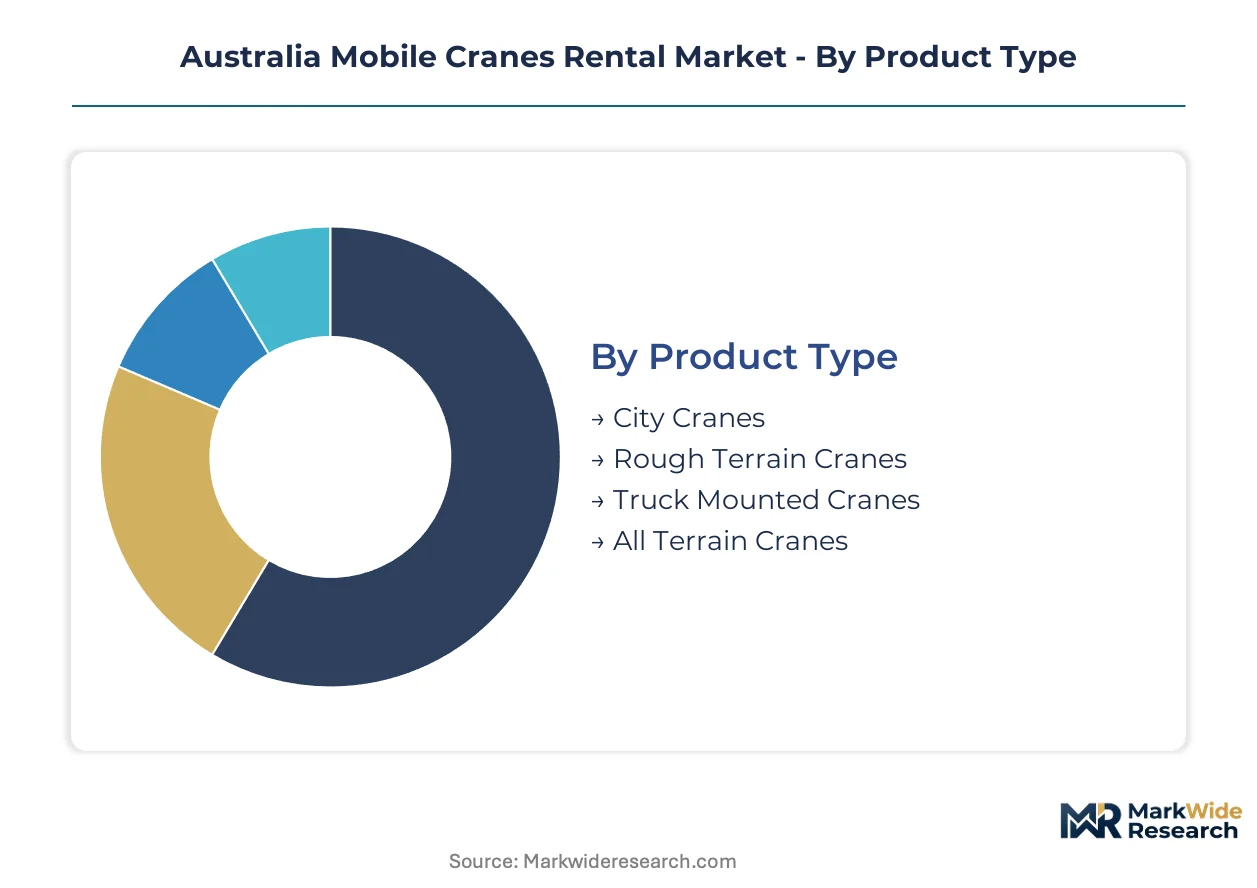
Mobile crane rental economics in Australia diverge sharply across equipment specifications and contract structures. Fleet operators configure holdings around state-level demand density and project duration patterns rather than uniform national coverage.
Product Type:
Supply concentration among specialized mobility configurations shapes competitive positioning across Australian rental fleets.
- All Terrain Cranes:Dual-road-and-site mobility enables rapid deployment between metropolitan depots and remote construction sites without disassembly. Queensland LNG contractors in Gladstone specify these units for multi-location megaproject logistics where highway transit and rough-terrain positioning alternate daily.
- Rough Terrain Cranes:Outrigger-stabilized chassis and four-wheel drive handle unimproved Pilbara and Bowen Basin ground conditions where truck-mounted units cannot operate. Western Australian mining automation maintenance contracts lock in long-term deployment cycles for these configurations.
- City Cranes:Compact turning radius and reduced tail-swing suit constrained urban construction zones in Sydney and Melbourne high-density precincts.
- Truck Mounted Cranes:Highway-speed transit between regional hubs supports rapid-response rental models across New South Wales and Victorian infrastructure corridors.
Today's leader: All Terrain Cranes. Tomorrow's challenger: Rough Terrain Cranes.
End User:
Application-driven specification requirements fragment fleet deployment across Australia's resource and built environment sectors.
- Mining:Autonomous haulage maintenance in Western Australia's Pilbara region demands specialized boom configurations for precision component replacement at remote pit locations. Rio Tinto and BHP rental contracts specify crane-plus-technician bundled services that extend engagement duration beyond equipment-only terms.
- Oil & Gas:Queensland's Curtis Island and Gladstone LNG precincts require heavy-lift capacity for module installation and turnaround maintenance. Lease-to-purchase structures predominate given multi-year construction-to-operations timelines.
- Construction:Residential and commercial building activity in Sydney, Melbourne, and Brisbane generates high-frequency short-term rental demand with seasonal concentration.
- Infrastructure:Federal and state transport projects across Victoria's Big Build and New South Wales infrastructure pipeline sustain medium-term rental cycles with performance-penalty contracting.
Mining commands premium rate structures. Infrastructure offers volume scaling potential.
Service Type:
Margin stability varies directly with contract duration and capital conversion mechanics across rental business models.
- Long-Term Rental:Multi-year infrastructure and resources engagements lock in utilization guarantees and reduce fleet rebalancing costs. Queensland LNG contractors favor 24-36 month terms with extension options that match project phase transitions.
- Lease-to-Purchase:Capital-constrained contractors in New South Wales and Victoria convert rental relationships into equipment ownership over 3-5 year amortization schedules, capturing margin from financing spreads and residual value realization.
- Short-Term Rental:Spot market transactions generate highest transaction frequency but compress margins through mobilization costs and idle period risk.
- Maintenance Services:Bundled mechanical and lifting support expands addressable spend per customer in Western Australian mining maintenance contracts.
Long-Term Rental anchors revenue predictability. Lease-to-Purchase expands fastest as contractor capital constraints deepen.
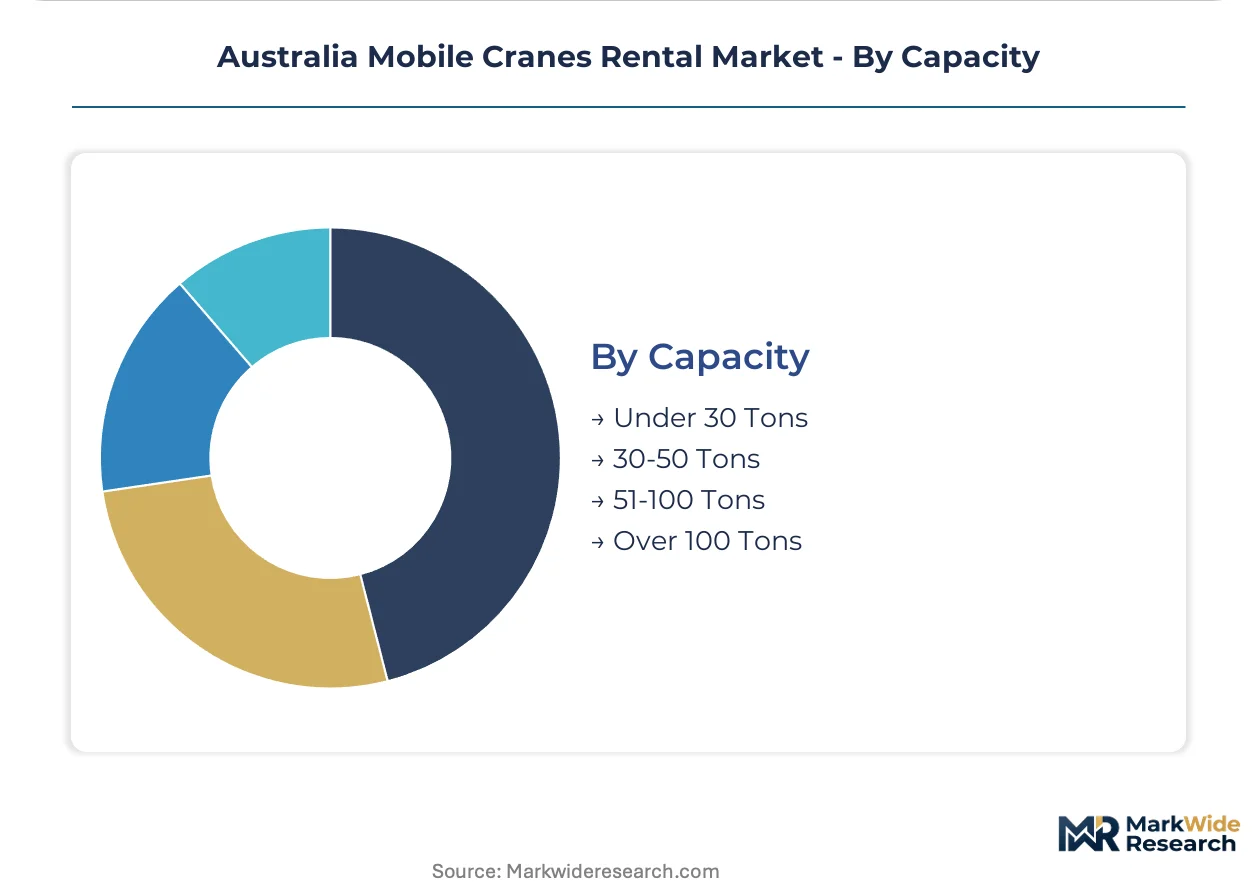
Capacity:
Fleet investment intensity escalates non-linearly with rated lifting capacity, segmenting competitive participation.
- Over 100 Tons:Lattice boom and heavy-lift telescopic configurations serve energy sector module installation and mining infrastructure replacement. Limited domestic supply concentrates procurement authority with Mammoet and specialized national operators.
- 51-100 Tons:Extended-reach telescopic booms in high-strength steel reduce tandem-lift requirements for mid-scale industrial construction. Victorian renewable energy zone wind turbine assembly contracts specify these units for nacelle and blade placement.
- 30-50 Tons:Volume segment for commercial construction and general infrastructure maintenance across metropolitan Australian markets.
- Under 30 Tons:City crane and compact rough-terrain configurations dominate residential construction and facility maintenance applications.
Over 100 Tons segment commands rate premiums. 51-100 Tons segment shows steepest expansion trajectory from energy transition infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara mining corridor anchors national crane rental demand through autonomous haulage maintenance contracts. Queensland's Gladstone LNG precinct and New South Wales infrastructure pipeline concentrate multi-year lifting requirements across distinct state regulatory environments.
New South Wales
Sydney's high-density construction and Victoria's Big Build spillover sustain metropolitan crane deployment. Safe Work NSW enforces crane licensing protocols that exceed federal baselines, tightening operator qualification standards. The WestConnex and Sydney Metro corridors generate medium-term rental cycles with performance-penalty contracting structures.
Victoria
Renewable energy zone wind turbine assembly and Melbourne rail infrastructure expansion drive 51-100 ton crane specifications. The state's occupational regulator mandates site-specific compliance documentation beyond Work Health and Safety Act requirements. Gippsland and Western District wind farms concentrate nacelle placement contracts requiring extended-reach telescopic configurations.
Queensland
Gladstone's Curtis Island LNG facilities and Bowen Basin coal operations lock in premium rental rates for rough-terrain and all-terrain units. The Queensland government enforces resources sector safety protocols that shape equipment certification requirements. Brisbane's urban density and regional mining towns create bifurcated demand between city cranes and heavy-lift configurations.
Western Australia
Pilbara iron ore autonomous haulage maintenance demands specialized boom configurations for precision component replacement. The Western Australian Department of Mines, Industry Regulation and Safety administers site-specific crane deployment rules for remote pit locations. Perth's metropolitan depot network feeds fly-in-fly-out maintenance contracts with Rio Tinto and BHP.
South Australia
Renewable energy zone development and Olympic Dam mining operations generate emerging crane demand outside traditional eastern state concentration. SafeWork SA aligns with federal harmonized standards while enforcing regional inspection intervals. Port Augusta and Whyalla industrial corridors attract fleet deployment from Adelaide-based rental operators seeking utilization beyond metropolitan saturation.
Australia Mobile Cranes Rental Market Competitive Environment
Capacity expansion dominates the current landscape as rental operators reconfigure fleets toward high-strength steel boom specifications and autonomous-compatible configurations. The market structures around three tiers: national fleet operators with branch density, specialized heavy-lift engineering providers, and regional maintenance-integrated service bundlers. Strategic archetypes include energy sector contract specialists, mining maintenance integrators, and metropolitan rapid-response providers. Competitive intensity concentrates on lease-to-purchase structuring and maintenance service bundling rather than spot rate competition.
Within the heavy-lift engineering tier, Mammoet Australia occupies a position exemplifying energy sector contract concentration. Kennards Hire represents the national coverage archetype through metropolitan and regional branch density. Boom Logistics Ltd anchors the resources infrastructure maintenance integration model. These three operators collectively illustrate how fleet configuration, geographic presence, and service bundling separate competitive positioning across Australian state markets.
| Leading Market Players |
|---|
| Mammoet Australia |
| Kennards Hire |
| Boom Logistics Ltd |
| Borger Cranes |
| Premier Cranes & Rigging |
| Tutt Bryant Group |
| WGC Cranes |
| MARR Contracting |
| Freo Group |
| Others |
Value Chain & Pricing Dynamics
High-strength steel boom technology is compressing per-lift operating costs while simultaneously concentrating procurement leverage among fleet operators with capital access for premium equipment configurations. Australian rental providers face divergent cost economics between imported European all-terrain units and domestically sourced rough-terrain configurations, fragmenting pricing power across equipment mobility tiers.
Pricing Analysis
Input-cost pass-through from high-strength steel alloys and European crane chassis imports shapes rate-setting across Australian rental fleets. Three-tier pricing structure across premium-certified, standard-compliant, and economy-limited tiers separates Mammoet Australia's energy-sector contracts from metropolitan rapid-response providers. Cost compression in the economy tier is intensifying because subscale operators absorb currency volatility without volume buffers. Mining contractors in Western Australia's Pilbara region exhibit lowest price sensitivity due to bundled technician requirements, while residential construction developers in Sydney and Melbourne drive spot-market rate competition.
Supply Chain Analysis
Dual-sourcing requirements from Queensland LNG contractors and Western Australian mining operators mandate qualification of both European and Japanese equipment suppliers, extending procurement cycles. Manufacturing concentration in Germany, Japan, and Finland feeds Australian fleet expansion, with boom fabrication drawing from Swedish and South Korean steel mills. Single-source vulnerability in all-terrain crane chassis supply exposes rental operators to euro and yen exchange rate swings. Distribution runs through Perth and Brisbane metropolitan depots with fly-in-fly-out logistics to remote Pilbara and Bowen Basin sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's mobile crane rental market functions as a geographic-arbitrage play where fleet deployment toward Western Australia's mining automation maintenance commands rate premiums unavailable in metropolitan construction markets, exploiting the cost differential between Pilbara site premiums and eastern-state competitive saturation.
For Market Incumbents: Deepen maintenance service bundling in Western Australian mining contracts to lock out specialized mechanical competitors encroaching on crane-plus-technician engagements. Expand high-strength steel boom capacity in Queensland ahead of Curtis Island LNG turnaround cycles, securing multi-year lease structures that convert spot-rental competitors into marginal players. For New Entrants and Emerging Players: Enter via South Australian renewable energy zones where Olympic Dam mining and Port Augusta wind farm development outpaces local fleet availability. Target 51-100 ton telescopic configurations for Victorian wind turbine assembly where established operators underweight extended-reach specifications. Pursue direct contracting with site engineering teams rather than tier-one construction contractors to compress vendor selection cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional maintenance-integrated service bundlers with proven Western Australian mining relationships but limited eastern-state coverage. Long-term viability hinges on lease-to-purchase contract velocity as contractor capital constraints deepen across New South Wales and Victorian infrastructure pipelines. Monitor federal infrastructure commitment announcements as inflection indicators for fleet utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| High-Strength Steel Fleet Conversion | Reduces tandem-lift labor costs for Gladstone LNG module installation contracts. |
| Lease-to-Purchase Contract Structuring | Captures financing spreads from capital-constrained Victorian infrastructure contractors. |
| Western Australian Maintenance Integration | Bundles crane deployment with autonomous haulage technician services for BHP contracts. |
| Queensland Regional Branch Expansion | Positions fleet availability ahead of Bowen Basin coal automation maintenance cycles. |
| Third-Party Certification Investment | Satisfies Safe Work Australia mandates that filter subscale competitors from LNG precinct procurement. |
Study Parameters
Coverage spans New South Wales, Victoria, Queensland, Western Australia, and South Australia, with primary inputs from each state market. The analysis combines interviews with fleet operations directors, mining maintenance managers, LNG project procurement leads, and construction contractor equipment planners with secondary validation from Safe Work Australia licensing databases, Australian Bureau of Statistics construction activity indices, and state-level infrastructure pipeline disclosures. Bottom-up equipment deployment estimates triangulate against top-down rental market value reconstruction.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include equipment mobility type, end-use sector, contract duration structure, and rated capacity tier. CAGRs derive from fleet expansion trajectories matched against project pipeline commitments. Industry-specific forecast inputs incorporate Western Australian mining automation maintenance schedules and Queensland LNG turnaround cycles.
Inputs from state occupational regulators and major resources operator procurement teams were available through the study window; gaps in forward infrastructure commitment timelines introduce uncertainty bands around long-term fleet utilization assumptions. Deviation in federal infrastructure spending authorization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Winch Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Laser Cladding Systems Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Laser Cladding Equipment Market