
 Europe Air Compressor Market | 2026-2036
Europe Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Compressor Market Analytics
Variable speed drive integration is rewriting compressor system architecture across European industrial facilities. Atlas Copco leverages its digital compressor monitoring platforms to anchor aftermarket service revenue. Kaeser Kompressoren sustains manufacturing depth at its Coburg headquarters, dominating regional supply chains for oil-lubricated units. Siemens Energy competes on electrification interfaces, positioning its compressor trains for hydrogen economy applications.
An air compressor mechanically compresses atmospheric air to elevated pressures, typically ranging from 100 to 175 psi for industrial rotary screw units, to store kinetic energy for pneumatic power transmission. The device converts electrical or mechanical energy into pressurized airflow for tool actuation, process automation, and material handling across factory floors. Rotary screw compressors lead the product type landscape due to continuous-duty reliability in manufacturing environments, while oil-free technology commands premium positioning in pharmaceutical and food-grade applications where contamination risks are non-negotiable. Medical end users represent a concentrated margin pool, as hospital gas systems and dental clinics require certified clean air compliance that standard industrial units cannot satisfy.
The Ecodesign Directive and EU Green Deal efficiency standards mandate minimum performance thresholds for compressors above 75 kW, forcing equipment replacement cycles and redesign of legacy portfolios. CE marking under the Machinery Directive governs safety integration, while REACH compliance shapes material selection for seals, lubricants, and surface coatings in compressor manufacturing. Stakeholders must monitor how F-Gas phase-down schedules interact with refrigerant-based dryer systems commonly paired with compressed air installations, as this regulatory intersection will determine next-generation product configurations and service model economics.
Market Dynamics
The EU Green Deal's efficiency mandates and F-Gas Regulation phase-down schedules are compressing replacement cycles for legacy compressor fleets while elevating oil-free and variable-speed architectures across pharmaceutical, food-grade, and precision manufacturing installations.
Growth Catalysts
- Ecodesign Directive thresholds:Minimum performance requirements for units above 75 kW force industrial operators toward energy-efficient rotary screw and centrifugal replacements, accelerating equipment turnover in Germany's chemical processing belt.
- Pharmaceutical cleanroom expansion:Certified oil-free compressor demand intensifies as EU pharmaceutical manufacturing scales sterile production capacity for biologics and aseptic filling lines.
- Hydrogen economy interface development:Compressor trains configured for hydrogen blending and high-pressure fueling applications attract capital allocation from energy infrastructure developers preparing continental hydrogen backbone networks.
Market Restraints
- Permanent magnet motor cost volatility:Rare earth element price swings for neodymium and dysprosium concentrate in Chinese processing facilities transmit directly to variable-speed drive compressor manufacturing economics.
- Technical limitation in heat recovery:Low-grade thermal energy capture from compressed air systems remains thermodynamically constrained, limiting total cost of ownership reductions for energy-intensive continuous-duty applications.
- F-Gas refrigerant phase-down friction:Refrigerant-based dryer systems paired with compressor installations face supply uncertainty and retrofit complexity as EU F-Gas Regulation tightens hydrofluorocarbon availability.
Strategic Opportunities
- Polish and Romanian industrial catch-up:Manufacturing reshoring and EU cohesion fund infrastructure investments create greenfield demand for integrated compressed air systems in Central European automotive and electronics assembly corridors.
- Service unbundling and predictive maintenance:IoT-enabled condition monitoring platforms allow compressor OEMs to capture recurring revenue through performance-based contracts displacing traditional break-fix service models.
- Carbon border adjustment mechanism alignment:CBAM compliance requirements for imported industrial goods incentivize European manufacturers to document embedded emissions from compressed air energy consumption, favoring audited efficient equipment procurement.
Industry Challenges
- Compressed air system auditor certification scarcity:Qualified energy assessors capable of ISO 50001-aligned compressed air leak detection and demand-side optimization remain concentrated in Germany and Benelux, constraining efficiency program rollout.
- Legacy pneumatic infrastructure integration:Brownfield facilities with decades-old fixed-speed compressor installations face control architecture incompatibility when retrofitting variable-speed drives and master control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Compressor Market |
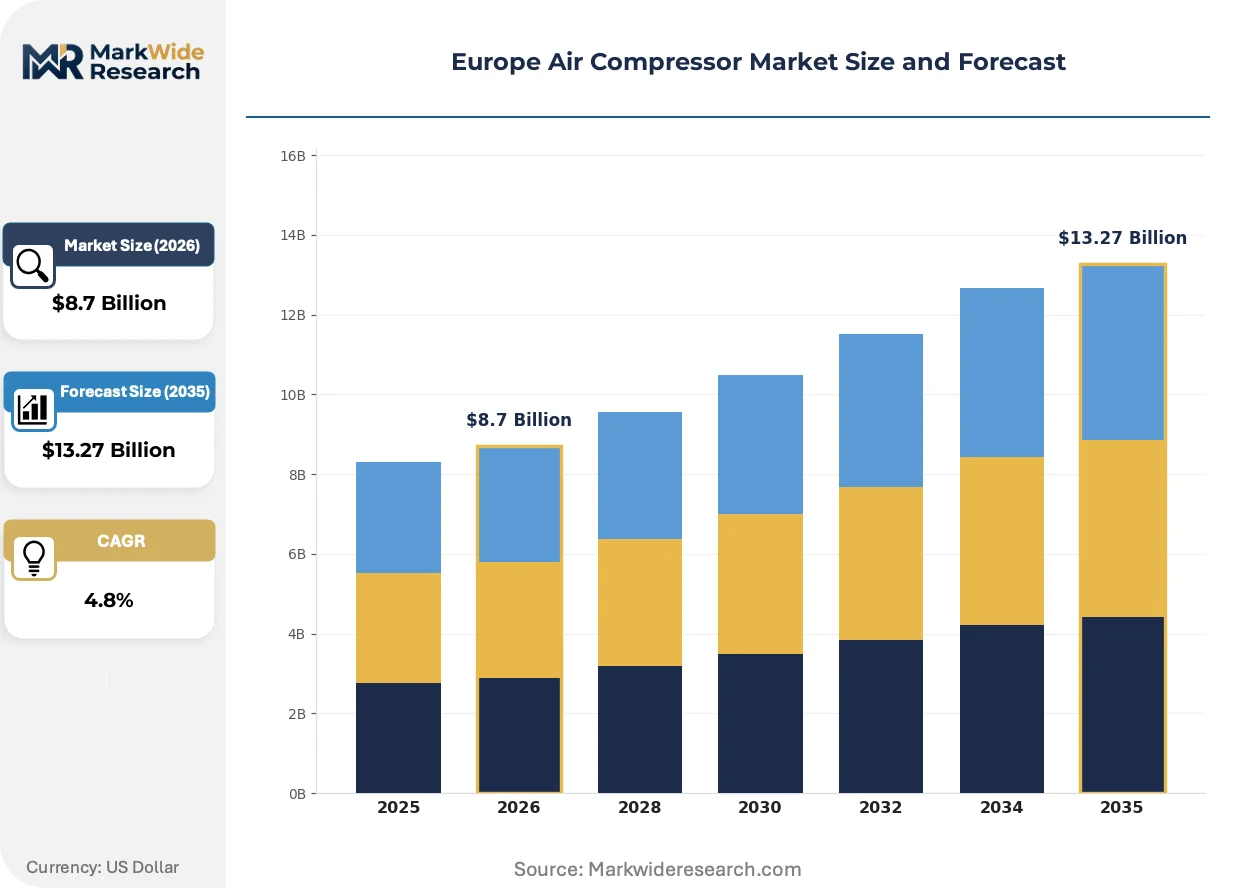
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Scroll End User: Manufacturing, Construction, Automotive, Medical Technology: Oil-lubricated, Oil-free, Variable Speed Drive, Portable Application: Pneumatic Tools, Painting, Blowing, Drying |
| Companies Covered | Sullair, Boge Kompressoren, Atlas Copco, Siemens Energy, Gardner Denver, Kaeser Kompressoren, CompAir, Hitachi, Ingersoll Rand, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Compressor Market Evolving Landscape
Digital compressor monitoring platforms and high-speed permanent magnet motor integration are restructuring how European industrial operators procure, operate, and maintain compressed air infrastructure across fragmented manufacturing footprints.
High-speed permanent magnet motor technology is collapsing the physical footprint and mechanical complexity of oil-free compressor airends. Pharmaceutical and electronics manufacturers in the Netherlands and Switzerland are specifying these compact architectures for cleanroom installations where floor space commands premium value. The elimination of gearbox stages and reduction in rotating mass is compressing maintenance intervals and enabling modular redundancy configurations previously uneconomical at smaller capacity points.
REACH compliance enforcement is tightening material selection protocols for compressor seals, lubricants, and surface coatings across European manufacturing. ECHA substance of very high concern listings now restrict specific phthalate plasticizers and chromium VI compounds in elastomer formulations, forcing reformulation of legacy oil-lubricated compressor fluid circuits. Food-grade and medical air compressor segments face the most acute compliance timeline pressure, with notified body re-certification cycles extending procurement lead times.
Compressed air auditing practices are migrating from episodic consultancy engagements toward continuous monitoring subscriptions. Industrial operators in France and Italy are displacing annual leak detection surveys with permanently installed acoustic sensor networks feeding cloud-based analytics platforms. This instrumentation shift is most visible in automotive assembly plants where compressed air constitutes fifteen to twenty percent of total electricity consumption and real-time visibility supports demand-response participation in national grid balancing markets.
Europe Air Compressor Market Segmentation
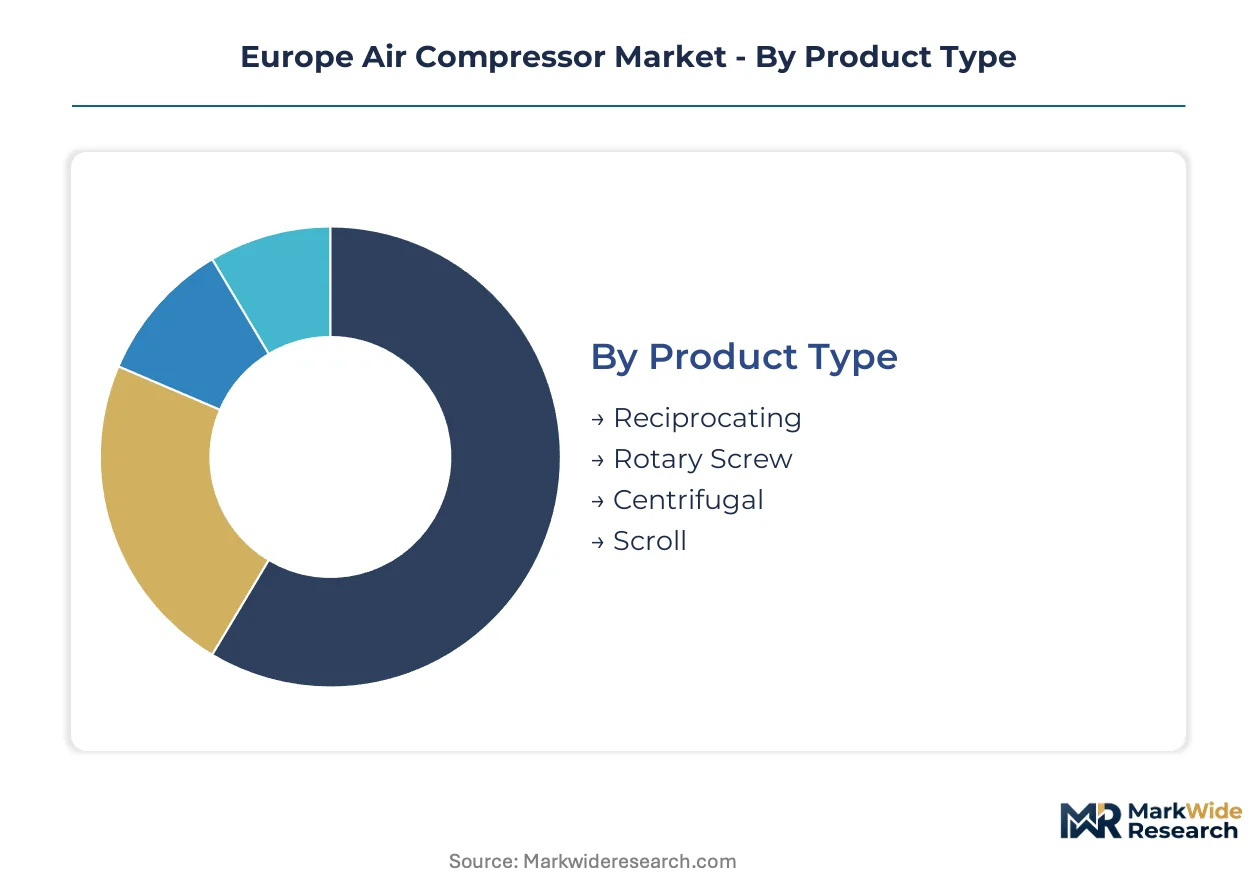
Compressed air system procurement across Europe fragments along technical specifications, contamination tolerance, and duty cycle intensity. Each segment carries distinct aftermarket service profiles and regulatory compliance burdens that reshape total cost of ownership calculations for industrial operators.
Product Type:
After-sales service intensity varies sharply across compressor architectures, with continuous-duty designs demanding predictive maintenance contracts and intermittent-use configurations relying on break-fix models.
- Rotary Screw:Twin helical rotors mesh without contact to deliver pulsation-free airflow at 100-175 psi for 24/7 manufacturing duty. German chemical processing clusters and automotive assembly plants in Spain specify these units for their compressed air baseload, though permanent magnet motor retrofits are compressing maintenance windows.
- Centrifugal:Dynamic compression through impeller acceleration serves high-volume, oil-free applications above 500 kW. Netherlands pharmaceutical sterile filling lines and Italian food packaging corridors concentrate demand here, driven by EU Green Deal efficiency mandates on large installed bases.
- Reciprocating:Piston-driven intermittent compression suits workshop and backup duty cycles with lower capital outlay.
- Scroll:Orbiting spiral elements provide oil-free, quiet operation for medical and laboratory scale applications.
Rotary Screw holds the largest share; momentum sits with Centrifugal as hydrogen economy infrastructure scales.
End User:
Margin profiles diverge across customer verticals based on contamination sensitivity, uptime requirements, and certification complexity.
- Manufacturing:Factory automation, robotics, and process control systems constitute the volume core. Polish and Romanian electronics assembly corridors are expanding procurement of integrated compressed air systems through EU cohesion fund investments.
- Medical:Hospital gas systems, dental clinics, and diagnostic equipment require certified clean air compliance that standard industrial units cannot satisfy. Swiss and French healthcare procurement concentrates margin here due to ISO 7396-1 medical gas pipeline standards and notified body re-certification cycles.
- Construction:Mobile and temporary compressed air for demolition, drilling, and surface preparation operates on rental and short-ownership models.
- Automotive:Paint shops, assembly line tooling, and tire inflation systems demand high reliability with moderate oil tolerance.
Manufacturing commands the revenue base; Medical is climbing the fastest on certification premiums and replacement cycle compression.
Technology:
Regulatory pressure on energy consumption and refrigerant chemistry is restructuring technology adoption curves across European industrial estates.
- Oil-free:Dry-running airends and water-injected designs eliminate hydrocarbon contamination for pharmaceutical cleanrooms and food-grade packaging. Benelux and Swiss electronics manufacturers specify these architectures where product integrity is non-negotiable, though initial capital outlay runs 40-60% above lubricated equivalents.
- Variable Speed Drive:Permanent magnet motors with integrated frequency converters match output to fluctuating demand, cutting energy consumption 25-35% in partial-load scenarios. Ecodesign Directive thresholds for units above 75 kW are accelerating retrofit and replacement cycles in Germany's industrial belt.
- Oil-lubricated:Conventional splash and pressure-fed lubrication dominates legacy installed bases and cost-sensitive applications.
- Portable:Trailer-mounted and skid-mounted configurations serve construction sites and emergency backup with diesel or electric prime movers.
Oil-lubricated retains the installed base majority; Variable Speed Drive is gaining share fastest on efficiency audit compliance.
Application:
Demand-side optimization and leak detection priorities vary by end-use, shaping how operators instrument and maintain distribution networks.
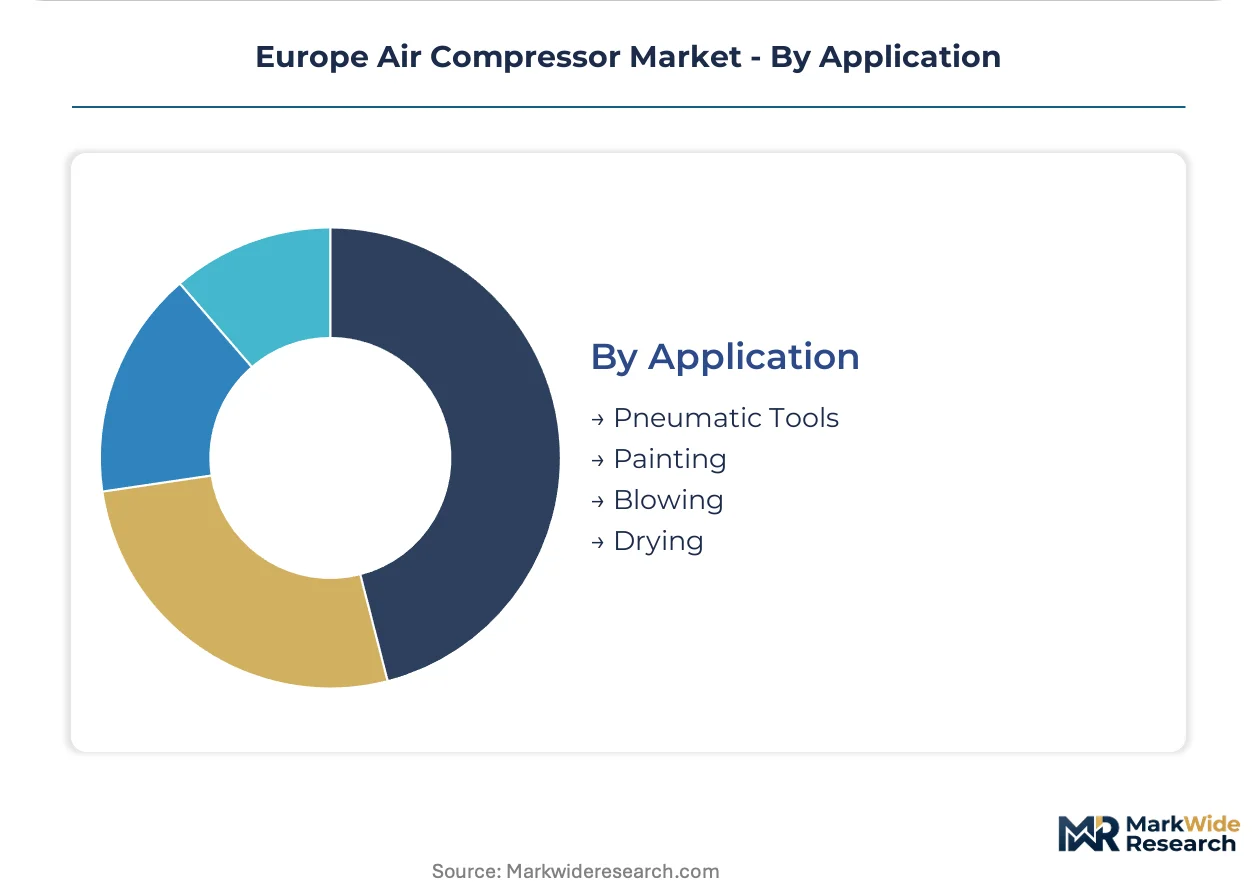
- Pneumatic Tools:Impact wrenches, grinders, and actuators consume intermittent high-flow bursts across automotive and general manufacturing. French assembly plants are deploying permanent acoustic sensor networks for continuous leak monitoring where compressed air constitutes 15-20% of electricity consumption.
- Drying:Desiccant and refrigerated dryers remove moisture to protect downstream equipment and product quality. F-Gas Regulation phase-down schedules are forcing refrigerant transitions and thermal mass dryer retrofits in Italian and Spanish processing facilities.
- Painting:Spray booths and coating lines require particulate and oil filtration to surface finish specifications.
- Blowing:Part ejection, debris removal, and packaging inflation represent low-pressure, high-volume demand segments.
Pneumatic Tools anchors procurement volume; Drying shows the steepest expansion trajectory on F-Gas compliance-driven replacement waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial procurement across Europe concentrates in Germany's precision engineering belt, where chemical processing clusters and automotive assembly plants anchor compressed air demand. The EU Green Deal efficiency mandates and F-Gas Regulation phase-down schedules are restructuring equipment replacement cycles continent-wide.
Germany
Chemical processing complexes in North Rhine-Westphalia and automotive assembly corridors in Bavaria drive rotary screw compressor procurement for continuous-duty manufacturing. Ecodesign Directive thresholds for units above 75 kW force industrial operators toward variable-speed replacements. The Coburg manufacturing cluster sustains regional supply chain dominance for oil-lubricated units serving precision engineering applications.
France
Automotive assembly plants and aerospace manufacturing facilities in the Île-de-France and Auvergne-Rhône-Alpes regions constitute concentrated demand for pneumatic tool infrastructure. Acoustic sensor networks for continuous leak monitoring are displacing annual surveys where compressed air represents 15-20% of electricity consumption. Hospital gas systems in Paris and Lyon medical clusters require ISO 7396-1 certified oil-free compressor compliance.
Italy
Food packaging corridors in Emilia-Romagna and pharmaceutical sterile filling lines in Lombardy elevate centrifugal compressor demand for high-volume oil-free applications. F-Gas Regulation phase-down schedules force refrigerant transitions in thermal mass dryer retrofits across processing facilities. The Milan-Turin industrial axis anchors procurement for integrated compressed air systems serving precision manufacturing.
Netherlands
Electronics manufacturers in the Eindhoven region and pharmaceutical cleanrooms in the Randstad specify compact high-speed permanent magnet motor architectures where floor space commands premium value. REACH compliance enforcement tightens material selection protocols for seals and lubricants in food-grade applications. Port-related logistics and hydrogen economy infrastructure development attract capital allocation for compressor trains configured for high-pressure fueling.
Poland
Manufacturing reshoring and EU cohesion fund infrastructure investments create greenfield demand for integrated compressed air systems in automotive and electronics assembly corridors around Warsaw and Kraków. Variable-speed drive retrofits accelerate as industrial operators align with EU Green Deal efficiency benchmarks. The Silesian manufacturing belt anchors regional procurement volume for cost-sensitive oil-lubricated configurations.
Europe Air Compressor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by service network density and technology integration depth. The vendor base organizes around three strategic archetypes: full-line manufacturers with predictive maintenance platforms, regional specialists with manufacturing depth at single locations, and energy infrastructure developers positioning compressor trains for hydrogen applications. Dominant competitive moves include portfolio diversification into oil-free architectures and geographic expansion through EU cohesion fund corridor penetration.
Among Sweden-based full-line manufacturers, Atlas Copco anchors the aftermarket service revenue tier through digital compressor monitoring platforms. Kaeser Kompressoren, a GmbH-structured German fabricator, exemplifies regional specialist positioning with manufacturing depth concentrated at its Coburg headquarters. Siemens Energy occupies the energy infrastructure developer archetype, competing on electrification interfaces for hydrogen economy applications.
| Leading Market Players |
|---|
| Sullair |
| Boge Kompressoren |
| Atlas Copco |
| Siemens Energy |
| Gardner Denver |
| Kaeser Kompressoren |
| CompAir |
| Hitachi |
| Ingersoll Rand |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's rare earth processing facilities for neodymium and dysprosium feeds directly into permanent magnet motor cost volatility, compressing variable-speed drive compressor margins while forcing European OEMs toward long-term offtake contracts and alternative sourcing architectures.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement of rare earth-dependent components, with pricing stratifying across oil-free certified premium tiers, standard rotary screw configurations, and economy-grade reciprocating units. Price differentiation hinges on ISO 8573-1 purity class certification and bundled predictive maintenance subscriptions. Cost compression in the economy tier intensifies as Polish and Romanian manufacturing reshoring attracts low-cost Chinese OEM entrants. Hospital gas system procurement shows lowest price sensitivity due to ISO 7396-1 compliance mandates and notified body re-certification requirements.
Supply Chain Analysis
Contract manufacturing for compressor airends and motor assemblies concentrates in Germany, China, and Italy, with Kaeser Kompressoren and Atlas Copco retaining in-house production at Coburg and Stockholm facilities respectively. Supply chains draw from rare earth element processing in China, specialty steel forging in Sweden, and precision machining in Switzerland. Single-source vulnerability in neodymium supply from Chinese processing facilities poses structural risk. Distribution runs through authorized dealer networks for aftermarket service capture and direct OEM relationships for large industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EU Ecodesign Directive thresholds and F-Gas Regulation phase-down schedules create compliance barriers that entrench incumbents with certified product portfolios and established notified body relationships.
For Market Incumbents: Build switching-cost moats through IoT-enabled predictive maintenance platforms that embed compressor performance data into customer operations, displacing break-fix service relationships. Deepen backward integration into high-speed permanent magnet motor production to offset rare earth price volatility. Anchor capacity expansion in Poland and Romania to capture EU cohesion fund corridor demand while defending against Chinese OEM price pressure in the economy tier. For New Entrants and Emerging Players: Mid-market food packaging facilities in Italy and Spain represent the most penetrable entry point, where F-Gas-driven dryer retrofits create equipment replacement windows without incumbent service lock-in. Target hydrogen economy infrastructure developers seeking compressor trains for high-pressure fueling applications, where electrification interface expertise outweighs manufacturing scale. Pursue white-label partnerships with established German component suppliers to bypass certification timeline barriers. For Investors and Strategic Acquirers: Capital is best deployed toward predictive maintenance platform operators with established sensor network density and recurring revenue contracts, as aftermarket service multiples exceed equipment manufacturing economics. Monitor Ecodesign Directive threshold expansion announcements as the critical inflection signal for accelerated replacement cycle timing and retrofit demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captures value from rare earth cost volatility while securing Ecodesign-compliant VSD supply. |
| Predictive Maintenance Platform Deployment | Atlas Copco's digital monitoring architecture demonstrates recurring revenue potential displacing break-fix models. |
| Hydrogen Economy Compressor Train Development | Siemens Energy positions for continental hydrogen backbone infrastructure capital allocation. |
| EU Cohesion Fund Corridor Penetration | Polish and Romanian automotive assembly expansion creates greenfield demand for integrated compressed air systems. |
| Oil-Free Certification Portfolio Expansion | Pharmaceutical cleanroom and food-grade packaging procurement concentrates margin in certified architectures. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base, triangulated against secondary validation from Ecodesign Directive implementation reports, F-Gas Regulation phase-down schedules, REACH substance restriction databases, and customs trade data for compressor component flows. Bottom-up equipment procurement modeling and top-down industrial energy consumption analysis converged on segment-level demand estimates.
Scenario-bracketing around EU Green Deal acceleration timelines and hydrogen economy infrastructure deployment shaped the analytical framework across the projection horizon, with segmentation modeling by product type, technology architecture, end-use vertical, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and efficiency mandate compliance deadlines incorporated rare earth price trajectory assumptions and manufacturing reshoring investment flows.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, rare earth export quotas, or EU cohesion fund disbursement rates would shift the trajectory. Quarterly review of Ecodesign Directive threshold expansion proposals, F-Gas refrigerant availability indices, and hydrogen backbone project financing announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crane Buffer Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Casting Equipment Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Excavator Wheels Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Press Brakes Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Piling Machine Market