
 France Construction Equipment Market | 2026-2036
France Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
France Construction Equipment Market Insights
The France construction equipment sector is restructuring around a widening gap between premium precision machinery and commodity-grade units serving price-sensitive contractors. Caterpillar leverages its dealer network density to dominate high-margin segments in urban infrastructure, while Volvo Construction Equipment sustains technology leadership through integrated telematics and emission-optimized powertrains. JCB anchors the mid-market with versatile loader and excavator portfolios tailored to French regional contractors.
France construction equipment encompasses powered machinery engineered for earthmoving, material handling, and vertical lifting at construction sites, typically featuring hydraulic systems rated from 50 to 500+ horsepower and operating weights spanning 1.5 to 100+ metric tons, designed to execute grading, excavation, lifting, and compaction tasks under variable soil and weather conditions. Excavators command the largest equipment-type share due to versatility across residential and infrastructure applications, while electric and hybrid solutions represent the fastest-expanding technology segment as contractors face tightening emission zones in Paris, Lyon, and Marseille. Roadwork applications concentrate mature demand tied to state-funded highway maintenance, whereas telematics-enabled fleet management creates margin pools for manufacturers offering subscription-based uptime services.
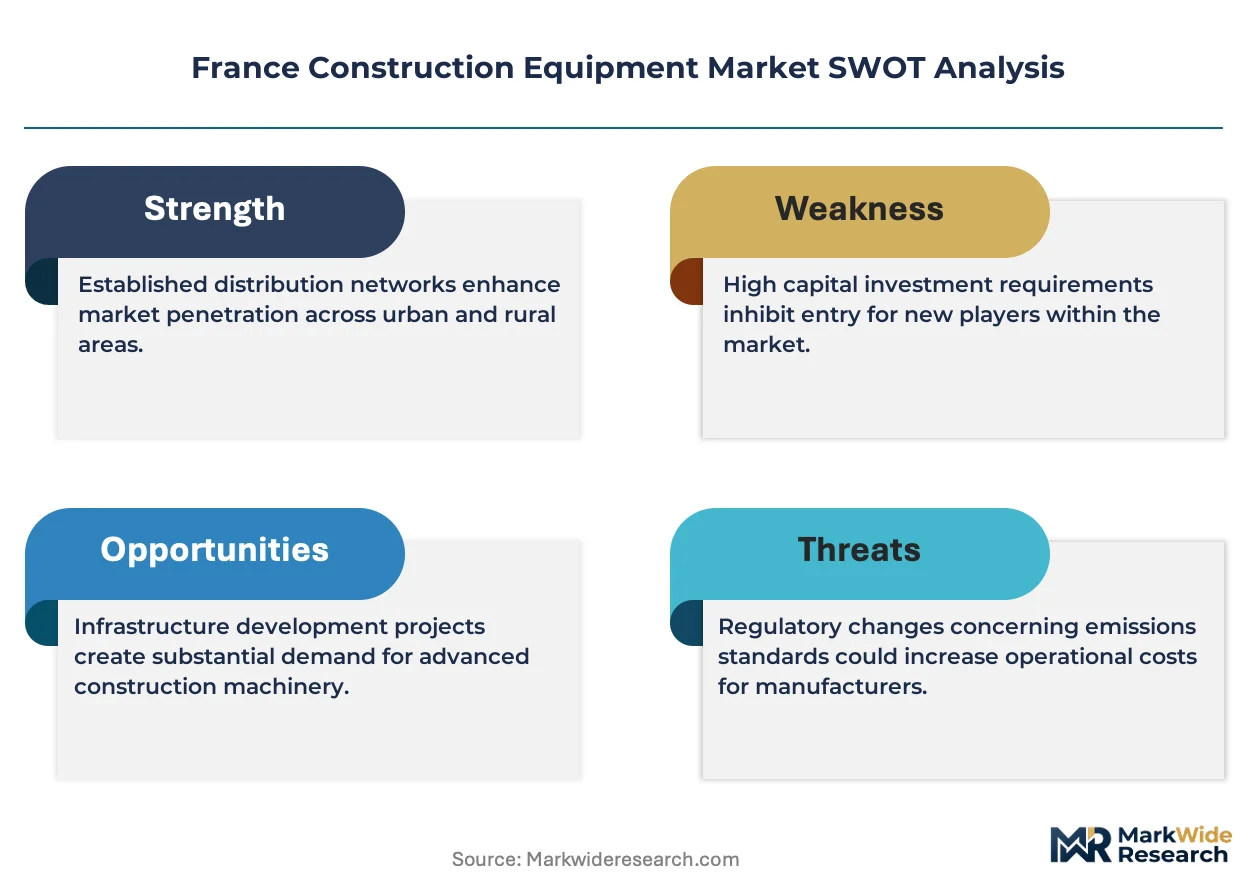
France's Ministry of Ecological Transition enforces RE2020 building standards that mandate lower-carbon construction methods, pushing contractors toward electric and hybrid equipment certified for urban low-emission zones. ANSM and CNIL frameworks govern worker safety data and connected-machine privacy, respectively, adding compliance layers to telematics deployment. Stakeholders must weigh total cost of ownership against stricter carbon thresholds when selecting fleet composition for the next investment cycle.
Market Dynamics
France's construction equipment sector is bifurcating around RE2020 compliance costs, forcing contractors to choose between premium electrified fleets and extended depreciation cycles for diesel assets in rural zones.
Growth Catalysts
- RE2020 Building Standards:France's Ministry of Ecological Transition mandates lower-carbon construction methods, accelerating demand for electric excavators and hybrid loaders certified for urban low-emission zones in Paris, Lyon, and Marseille.
- Île-de-France Infrastructure Concentration:Public investment flows disproportionately to the Paris metropolitan region, concentrating fleet renewal demand among contractors serving state-funded transit and utility projects.
- Telematics Integration:Connected fleet management systems enable predictive maintenance and uptime guarantees, creating subscription revenue pools for equipment vendors serving large-scale earthmoving contractors.
Market Restraints
- Battery Cost Volatility:Lithium-ion cell prices fluctuate with raw material markets, compressing margins on electric compact equipment where powertrain costs dominate total manufacturing expense.
- Supply Concentration in Germany:Critical hydraulic components and emission control systems originate from a narrow base of German suppliers, exposing French distributors to lead time volatility and currency risk.
- Technical Limitation in Cold Climates:Electric equipment experiences range and charging efficiency degradation in Alpine construction zones, limiting addressable market share for battery-powered solutions in southeastern France.
Strategic Opportunities
- Auvergne-Rhône-Alpes Regional Expansion:Lyon and Grenoble corridor infrastructure projects remain underserved by electrified rental fleets, creating first-mover advantage for contractors deploying zero-emission compact equipment.
- Rental Channel Digitalization:Platform-based equipment sharing and on-demand leasing models reduce capital barriers for small contractors in Normandy and Brittany peripheral markets.
- EU Green Deal Alignment:France's national recovery plan channels subsidies toward sustainable construction machinery, lowering effective acquisition costs for contractors purchasing EU-certified low-carbon equipment.
Industry Challenges
- Electrification Skill Gap:Maintenance technicians require retraining on high-voltage systems and battery diagnostics, straining dealer service networks in rural Grand Est and Nouvelle-Aquitaine regions.
- CNIL Data Compliance:Connected machine telematics must satisfy France's data protection authority requirements for worker privacy and cross-border data flows, adding implementation complexity for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Construction Equipment Market |
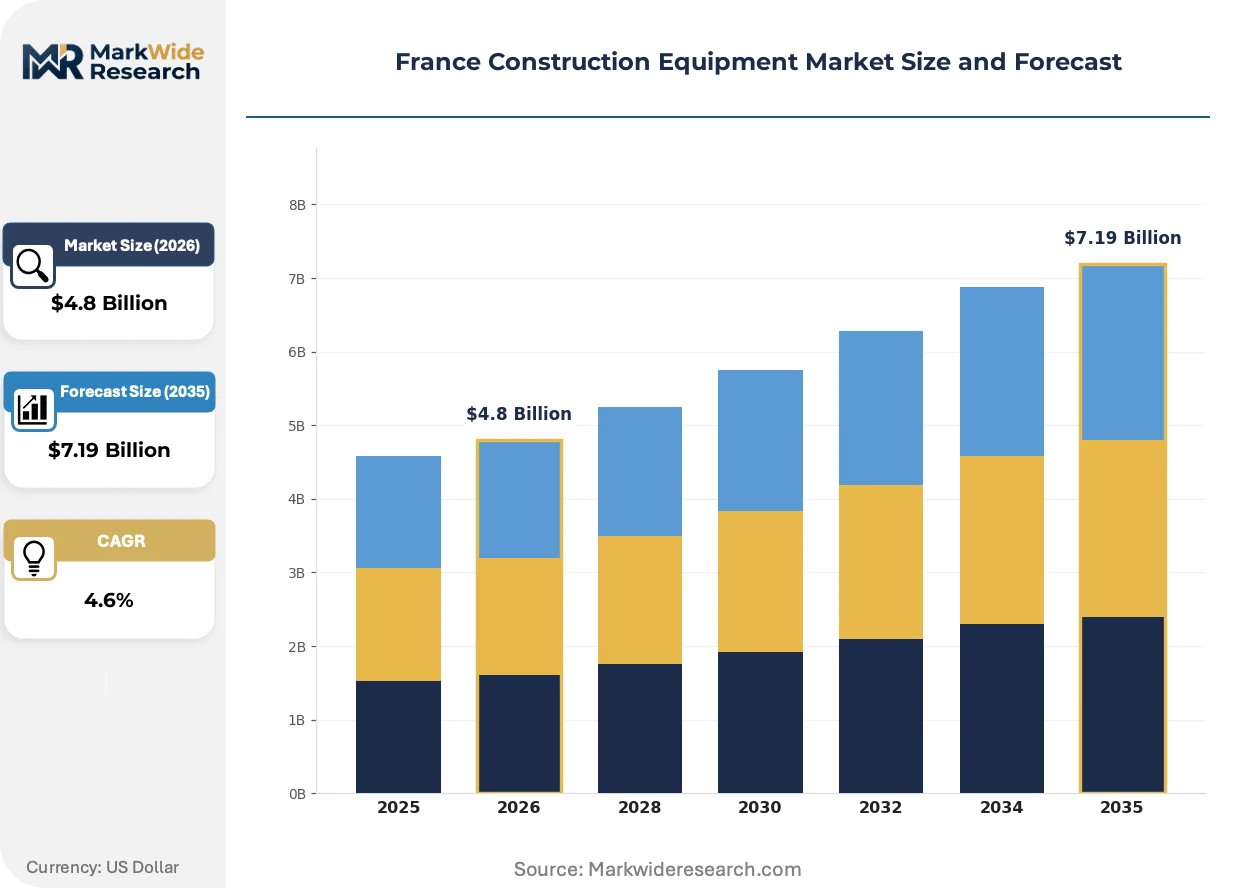
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders Application: Residential Construction, Commercial Construction, Infrastructure Development, Roadwork End User: Contractors, Construction Firms, Government Agencies, Developers Technology: Telematics, Automated Machinery, Electric Equipment, Hybrid Solutions |
| Companies Covered | Caterpillar, Komatsu, Volvo Construction Equipment, Kobelco, Liebherr, Hitachi Construction Machinery, JCB, XCMG, Hyundai Construction Equipment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Construction Equipment Market Trends and Innovations
Equipment intelligence and powertrain electrification are restructuring competitive advantage in French construction machinery, compressing the traditional technology adoption cycle from decades to single investment cycles.
Hybrid-electric powertrains are converging with regenerative hydraulics to deliver fuel consumption reductions without full battery dependency. Regional contractors in Provence-Alpes-Côte d'Azur are piloting these systems for intermittent-duty applications. The convergence is enabling mid-market fleet operators to satisfy emission zone requirements while preserving operational flexibility across dispersed job sites.
France's ANSM safety frameworks now extend to autonomous machine operation protocols, mandating fail-safe systems and operator override capabilities. Equipment manufacturers must certify sensor arrays and control logic before urban deployment. Earthmoving contractors in dense metropolitan zones face the steepest compliance timelines and certification costs.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-size French construction firms. Rental platforms and manufacturer finance arms now bundle maintenance, telematics, and upgrade rights into per-hour usage agreements. This shift concentrates most visibly in the Occitanie region where contractor fragmentation amplifies preference for operational expenditure structures.
France Construction Equipment Market Segmentation
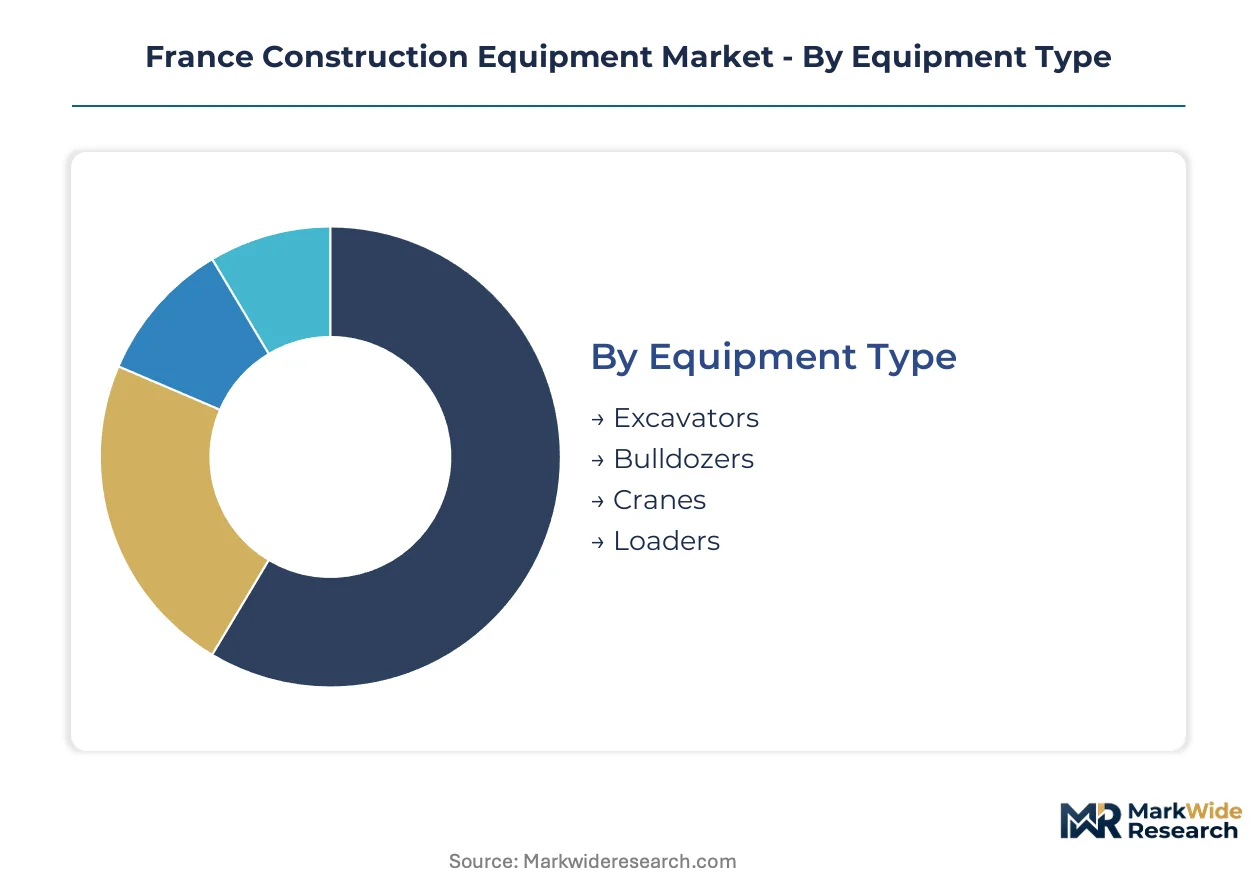
Equipment buyers in France face divergent cost pressures across urban emission zones and rural diesel-dependent sites. Segmentation reveals how RE2020 compliance and regional infrastructure investment reshape fleet composition decisions.
Equipment Type:
Buyers differentiate primarily by versatility versus specialization needs, with urban contractors prioritizing multi-function units and rural operators favoring single-purpose durability.
- Excavators:Hydraulic machines with operating weights from 1.5 to 100 metric tons and bucket capacities spanning 0.1 to 5 cubic meters enable trenching, demolition, and material handling from a single chassis. Demand concentrates in Île-de-France residential and transit projects where RE2020 standards push contractors toward electric compact models for Parisian low-emission zones.
- Loaders:Articulated or rigid-frame units with lift capacities from 1 to 25 metric tons move aggregates and backfill materials across dispersed job sites. Earthmoving contractors in Auvergne-Rhône-Alpes favor mid-size wheel loaders with regenerative hydraulics for intermittent-duty Alpine applications where full electrification faces cold-climate constraints.
- Bulldozers:Tracked tractors with blade widths exceeding 3 meters and engine ratings above 200 horsepower grade terrain and push bulk materials.
- Cranes:Mobile and tower configurations with lifting capacities from 20 to 1,000+ metric tons execute vertical material placement.
Excavators lead volumes today; electric equipment variants are gaining share fastest.
Application:
Project funding sources and regulatory exposure split demand between state-backed infrastructure and private development.
- Infrastructure Development:State-funded transit, utility, and public building projects require sustained equipment utilization over multi-year timelines. Contractors serving Grand Paris Express and Lyon-Turin rail corridors concentrate fleet investment in telematics-enabled excavators and cranes for coordinated site logistics.
- Residential Construction:Single-family and multi-unit housing developments drive demand for compact equipment with rapid site-to-site mobility. Developers in Île-de-France face the strictest RE2020 carbon thresholds, accelerating specification of electric compact excavators and hybrid loaders for urban infill projects.
- Commercial Construction:Office, retail, and industrial building projects favor mid-size equipment with precision grading capabilities.
- Roadwork:Highway maintenance and expansion programs tied to state budgets concentrate demand in mature diesel-powered pavers and compactors.
Infrastructure Development commands the largest equipment deployment; Residential Construction shows the steepest technology transition trajectory.
End User:
Capital availability and fleet scale separate procurement patterns across contractor tiers and public entities.
- Contractors:Independent earthmoving and specialty trade operators with fleets under 50 units prioritize equipment versatility and financing flexibility. Regional contractors in Occitanie and Nouvelle-Aquitaine increasingly adopt equipment-as-a-service contracts to convert capital expenditure into operational expenditure structures.
- Construction Firms:Large integrated builders with national project portfolios specify premium equipment with integrated telematics and predictive maintenance guarantees.
- Government Agencies:Public works departments and state-owned infrastructure operators procure through centralized tender processes with extended depreciation timelines.
- Developers:Real estate investment and project development entities influence equipment selection through sustainability scoring and ESG-linked financing requirements.
Contractors represent the largest addressable base; Construction Firms are expanding electrified fleet share most aggressively.
Technology:
Powertrain architecture and data connectivity now determine equipment eligibility for urban deployment and total cost of ownership calculations.
- Electric Equipment:Battery-powered excavators, loaders, and compactors with zero tailpipe emissions and 4-8 hour operating ranges satisfy Paris, Lyon, and Marseille low-emission zone requirements. Municipal contractors in these metropolitan areas face mandatory electrification timelines for new fleet additions.
- Hybrid Solutions:Diesel-electric powertrains with regenerative braking and engine-downsizing deliver emission reductions without full battery dependency. Regional contractors in Provence-Alpes-Côte d'Azur pilot these systems for intermittent-duty applications where charging infrastructure remains sparse.
- Telematics:Connected fleet management systems transmit location, utilization, and diagnostic data to enable predictive maintenance and uptime optimization.
- Automated Machinery:Semi-autonomous grading and excavation systems with GPS guidance and sensor-based obstacle detection reduce operator skill requirements.
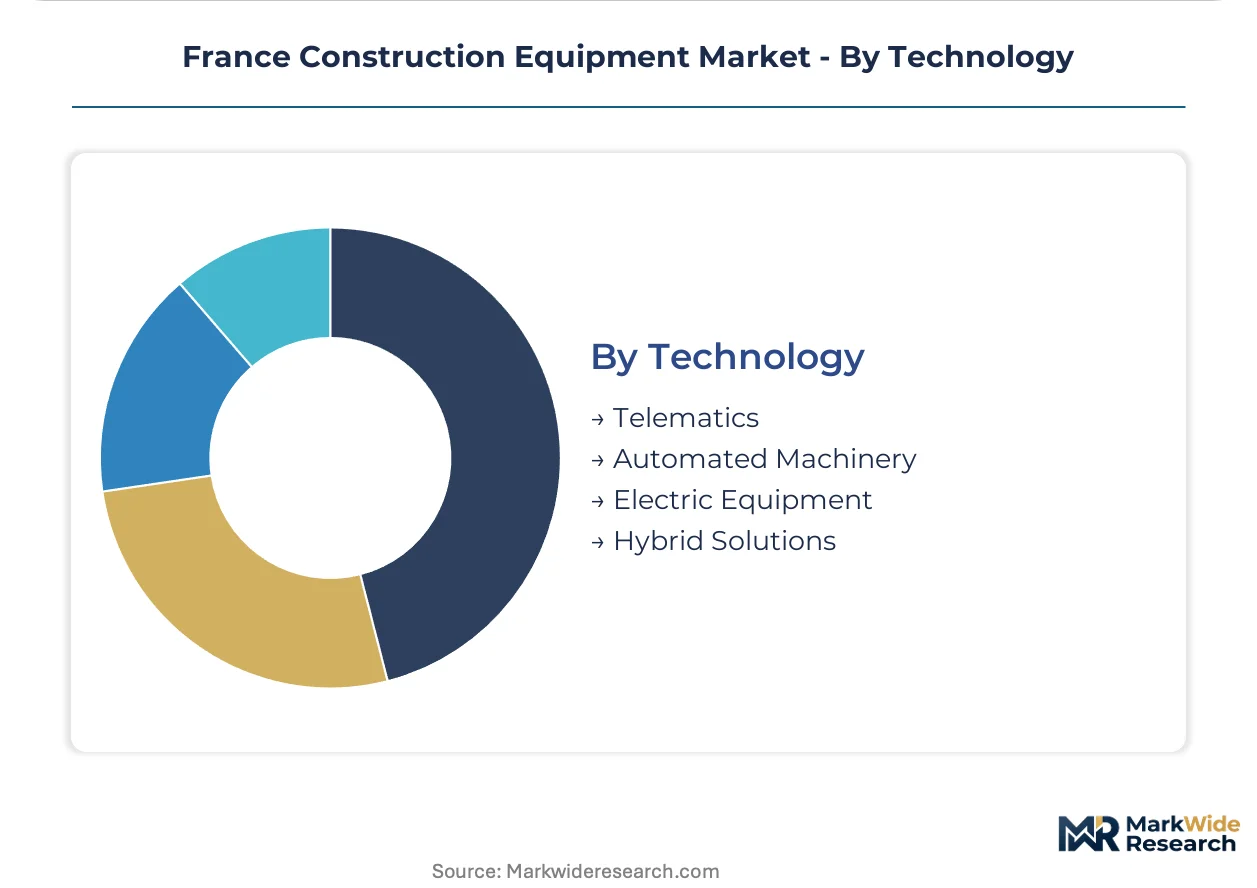
Telematics penetration leads current technology deployment; Electric Equipment is climbing the fastest as emission zones tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled equipment operators and maintenance technicians concentrate in France's industrial corridors, anchoring regional demand patterns across metropolitan construction zones and peripheral markets.
Île-de-France
Grand Paris Express transit expansion and urban renewal projects drive sustained fleet investment. ANSM safety protocols govern autonomous equipment trials in dense metropolitan worksites. Equipment distributors cluster in Paris-Saclay and Seine-et-Marne logistics corridors to serve state-funded infrastructure contractors.
Auvergne-Rhône-Alpes
Lyon-Turin rail corridor and Grenoble technology campus construction sustain mid-size equipment demand. RE2020 building standards accelerate specification of hybrid loaders for Alpine climate conditions. Contractors in the Lyon metropolitan area pilot regenerative hydraulic systems for intermittent-duty applications.
Provence-Alpes-Côte d'Azur
Marseille port modernization and coastal tourism infrastructure concentrate crawler crane and excavator deployment. CNIL data protection frameworks shape telematics implementation for connected fleet management. Equipment rental platforms expand in Aix-Marseille-Provence to serve fragmented regional contractors.
Hauts-de-France
Cross-Channel logistics hub development and wind farm construction drive heavy-lift crane demand. EU Green Deal subsidies lower acquisition costs for contractors purchasing low-carbon certified machinery. Lille metropolitan contractors specialize in equipment-as-a-service contracts for infrastructure maintenance fleets.
Nouvelle-Aquitaine
Bordeaux metropolitan expansion and Atlantic port modernization sustain earthmoving equipment utilization. RE2020 compliance timelines push urban contractors toward electric compact excavators for infill residential projects. Regional equipment distributors in Gironde and Landes prioritize financing flexibility for small-scale construction operators.
France Construction Equipment Market Competitive Landscape
Capital-heavy integrated manufacturers compete with asset-light regional assemblers for position in France's bifurcated equipment market. The vendor base separates into three tiers: premium precision machinery suppliers, mid-market versatility specialists, and price-focused commodity producers. Strategic archetypes include telematics-enabled fleet solution providers, electrification-first technology leaders, and rental-channel volume players. Competitive intensity centers on M&A consolidation of dealer networks and strategic partnerships for battery supply security.
Among premium-tier integrated manufacturers, Caterpillar, Volvo Construction Equipment, and JCB occupy positions exemplifying contrasting strategic archetypes. Caterpillar anchors the high-margin urban infrastructure segment through dense dealer coverage. Volvo Construction Equipment represents the telematics-integrated electrification path. JCB sits within the mid-market versatility tier, serving regional French contractors with loader and excavator portfolios. These three companies illustrate how equipment vendors segment around compliance cost pressures and fleet scale requirements.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Volvo Construction Equipment |
| Kobelco |
| Liebherr |
| Hitachi Construction Machinery |
| JCB |
| XCMG |
| Hyundai Construction Equipment |
| Others |
Pricing and Supply Chain Analysis
RE2020 building standards act as the primary gating mechanism for qualified supply access and premium-tier pricing power, with contractors seeking certified low-carbon equipment facing constrained vendor pools and elevated acquisition costs compared to conventional diesel alternatives serving price-sensitive rural operators.
Pricing Analysis
Bundled equipment-as-a-service contracts now compete against traditional unbundled capital purchases across the French market. Three-tier pricing structure across premium, standard, and economy levels separates telematics-integrated electric excavators from mid-market hybrid loaders and commodity-grade diesel units. Pricing pressure stems from battery cost volatility compressing margins on compact electric equipment. Small regional contractors in Normandy and Brittany exhibit highest price sensitivity, while large construction firms with national portfolios accept premium positioning for uptime guarantees and predictive maintenance inclusion.
Supply Chain Analysis
Freight costs from German manufacturing clusters to French distribution hubs add meaningful landed cost premiums on hydraulic systems and emission control components. Critical powertrain and hydraulic components concentrate in Germany, with supplemental sourcing from Italy and Poland for specialized attachments. French distributors depend on German suppliers for Tier 4 final emission systems and high-pressure hydraulic pumps. Single-source vulnerability around lithium-ion cell supply creates exposure to raw material price swings. Distribution runs through authorized dealer networks with regional service centers, supplemented by emerging platform-based rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion potential through electrification-driven premium tiering and aftermarket service bundling that converts capital expenditure into recurring revenue streams.
For Market Incumbents: Deploy telematics-enabled fleet solution bundling to defend against rental-platform disintermediation. Incumbents should consolidate dealer service networks in Grand Est and Nouvelle-Aquitaine to capture maintenance revenue on high-voltage systems. Battery supply security agreements with Korean and Chinese cell manufacturers represent critical defensive positioning against emerging electric-first competitors. For New Entrants and Emerging Players: EU Green Deal subsidies in France open a window for zero-emission compact equipment deployment in underserved Auvergne-Rhône-Alpes corridors. New entrants should target Lyon-Grenoble infrastructure contractors with hybrid loader offerings suited to Alpine climate constraints. Platform-based rental partnerships offer the most penetrable go-to-market angle for capital-constrained regional contractors. For Investors and Strategic Acquirers: Roll-up economics work for regional equipment distributors with captive service capabilities because maintenance skill scarcity on high-voltage systems creates local moats. Acquisition targets should demonstrate RE2020-certified inventory positions and established municipal contractor relationships. Watch electrification subsidy renewal announcements as the primary inflection signal for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Consolidation | Captures maintenance revenue pools as electric equipment raises service complexity barriers. |
| Battery Supply Partnership | Secures cell allocation priority from Korean manufacturers amid raw material competition. |
| Telematics Platform Launch | Enables subscription-based uptime guarantees for Grand Paris Express contractors. |
| Rental Channel Digitalization | Reduces capital barriers for fragmented Occitanie contractors through on-demand access. |
| RE2020 Certification Investment | Qualifies equipment for municipal procurement tenders with mandatory low-carbon specifications. |
Research Methodology
Bottom-up contractor fleet modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with equipment procurement managers at regional construction firms, aftermarket service directors at dealer networks, and municipal fleet supervisors informed demand-side assumptions. Secondary validation drew from French customs trade data, equipment registration databases, and Ministry of Ecological Transition subsidy disbursement records. Cross-referencing bottom-up project pipeline analysis with top-down OEM revenue disclosures ensured segmentation consistency.
Historical trendline analysis across equipment type, powertrain technology, and regional deployment patterns established baseline growth trajectories. The projection framework models demand across excavator, loader, and crane categories; electric, hybrid, and diesel powertrains; and Île-de-France versus peripheral regional clusters. CAGRs derive from regression-adjusted trend extrapolation incorporating RE2020 compliance phase-in schedules and public infrastructure investment commitments. Battery cost learning curves and telematics adoption S-curves provide industry-specific forecast inputs.
Revisions become necessary when lithium-ion raw material markets experience sustained volatility, German supplier lead times extend beyond contractual windows, or French municipal electrification mandates accelerate beyond current trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Bale Openers Market
Construction Equipment
Backhoes Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
GCC Crane Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
North America Drilling Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Snow Pushers Market