
 Europe Drilling Rig Market | 2026-2036
Europe Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Drilling Rig Market Foresight
Aftermarket service revenue is fragmenting across the Europe drilling rig landscape as operators extend asset life cycles rather than commission newbuilds. Maersk Drilling AS sustains fleet competitiveness through advanced harsh-environment jack-up specifications purpose-built for North Sea conditions. Saipem SpA leverages integrated engineering-to-drilling contracts that bundle subsea installation with rig deployment, capturing margin pools that pure equipment lessors cannot access. Schlumberger Limited anchors its European position through digital drilling automation platforms that reduce non-productive time on legacy assets.
A drilling rig is a mobile or fixed structure housing hoisting, rotating, and circulation systems capable of boring wells from surface to target depth, typically rated by maximum hook load, horsepower, and water-depth capability for offshore variants. Its primary commercial purpose is the penetration of geological formations to extract hydrocarbons, minerals, or geothermal resources. Offshore rigs, particularly semi-submersible and jack-up configurations, command the dominant share of European capital allocation as mature North Sea fields require complex extended-reach drilling. Directional drilling technology is displacing conventional vertical approaches in basin redevelopment campaigns where multiple targets are accessed from single surface locations, concentrating margin capture among service providers with proprietary steerable systems.
The EU F-Gas Regulation and REACH frameworks restrict fluorinated greenhouse gas use in rig HVAC and refrigeration systems, compelling fleet-wide retrofit investments that alter total cost of ownership calculations for operators. Norway's Petroleum Safety Authority and the UK's North Sea Transition Authority impose progressively stringent well integrity and blowout prevention standards that filter market access toward contractors with certified management systems. ECHA chemical authorization requirements affect drilling fluid formulations, pushing demand toward synthetic-based systems with lower environmental persistence profiles. Stakeholders must monitor how the EU AI Act's risk classification rules apply to autonomous drilling control systems before committing to next-generation automation roadmaps.
Market Dynamics
EU Green Deal methane regulations and the EU F-Gas framework are forcing fleet-wide electrification retrofits across the North Sea rig fleet, compressing contractor margins while filtering market access toward capitalized players with certified low-emission systems.
Growth Catalysts
- Energy Security Mandates:Norway's government-directed field redevelopment programs sustain rig demand through 2035 as domestic production targets displace import dependency. Operators secure long-term contracts under national petroleum directives.
- REACH Chemical Authorization:Synthetic-based drilling fluid formulations replace oil-based systems in UK and Dutch waters, creating replacement demand for compliant mud systems and associated rig reconfiguration services.
- Extended-Reach Drilling:Directional drilling technology penetrates multiple reservoir targets from single North Sea platform locations, concentrating rig utilization on high-specification jack-ups with advanced steerable capabilities.
Market Restraints
- Steel Input Volatility:Rig construction and major refurbishment depend on specialized high-grade steel plate subject to energy-intensive production constraints and carbon border adjustment exposure under EU CBAM.
- Contractor Concentration:Fleet ownership concentrates among a handful of North Sea-accredited drilling contractors, limiting price competition and extending tender timelines for operator procurement teams.
- EU AI Act Classification:Autonomous drilling control systems face pending high-risk algorithmic system designation, delaying automation roadmaps and freezing capital allocation for next-generation rig retrofits.
Strategic Opportunities
- Geothermal Co-Utilization:Existing North Sea jack-up platforms repurpose for deep geothermal drilling in the Netherlands and Denmark, leveraging established supply chains for renewable heat extraction projects.
- Hybrid Power Retrofits:Battery-hybrid energy storage integration on legacy semi-submersibles captures EU Innovation Fund subsidies while reducing fuel consumption during station-keeping operations.
- CSRD Disclosure Requirements:Mandatory sustainability reporting under the EU Corporate Sustainability Reporting Directive creates demand for emissions monitoring instrumentation and verified low-carbon rig certification services.
Industry Challenges
- Subsea BOP Certification:Norway's Petroleum Safety Authority mandates progressively stringent blowout preventer testing protocols, extending maintenance windows and compressing available drilling days during peak seasons.
- Automation Integration Complexity:Digital drilling platforms from Schlumberger and similar vendors require retrofitting onto mechanical legacy systems with incompatible data architectures, inflating commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Drilling Rig Market |
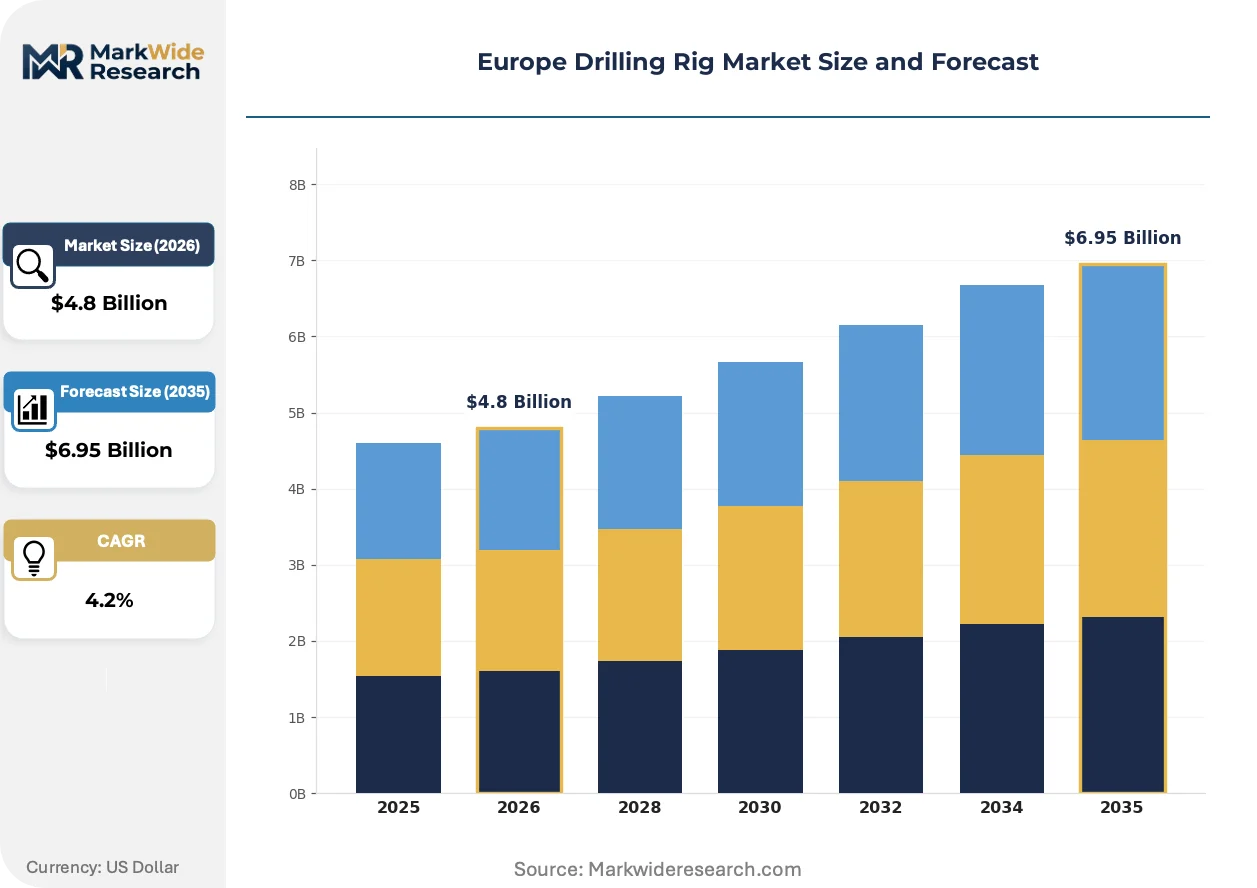
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Rigs, Offshore Rigs, Jack-up Rigs, Semi-submersible Rigs Technology: Rotary Drilling, Directional Drilling, Hydraulic Fracturing, Underbalanced Drilling End User: Oil & Gas Companies, Mining Industries, Service Providers, Government Agencies Installation: Permanent Installation, Temporary Installation, Mobile Installation, Fixed Installation |
| Companies Covered | Aker Solutions ASA, Maersk Drilling AS, Saipem SpA, Dril-Quip Inc., Seadrill Ltd, Noble Corporation PLC, Keppel Corporation Limited, Stena Drilling, Schlumberger Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Drilling Rig Market Shifts & Advancements
Rig automation and emissions compliance are converging to reshape contractor competitive positioning across the North Sea and Norwegian continental shelf, with technology adoption pace now determined by regulatory certification timelines rather than operator preference alone.
Integrated drilling automation platforms are collapsing non-productive time on legacy jack-up assets by orchestrating real-time downhole measurements with surface equipment response loops. North Sea operators with mature field portfolios deploy these systems most aggressively, prioritizing wells with complex geological uncertainty. The structural consequence is margin compression for pure equipment lessors unable to bundle digital services with rig provision.
The EU F-Gas Regulation imposes phasedown quotas on hydrofluorocarbon refrigerants used in rig HVAC and cooling systems, compelling fleet-wide equipment replacement before 2030. Contractors face stranded asset risk on vessels with non-compliant climate systems, redirecting maintenance budgets toward retrofit programs. UK-flagged rigs and Norwegian-registered units in the North Sea cluster experience the most concentrated compliance pressure, with operators now screening HVAC specifications during tender evaluation.
Service unbundling is fragmenting traditional integrated drilling contracts as European operators separate rig hire from directional drilling, mud engineering, and logging services. Procurement teams at majors now run parallel tenders for discrete work scopes, eroding the margin capture that bundled contractors previously enjoyed. This pattern is most advanced in the UK North Sea, where field equity partnerships with divergent cost-recovery positions drive contract structure negotiations toward modularization.
Europe Drilling Rig Market Segmentation
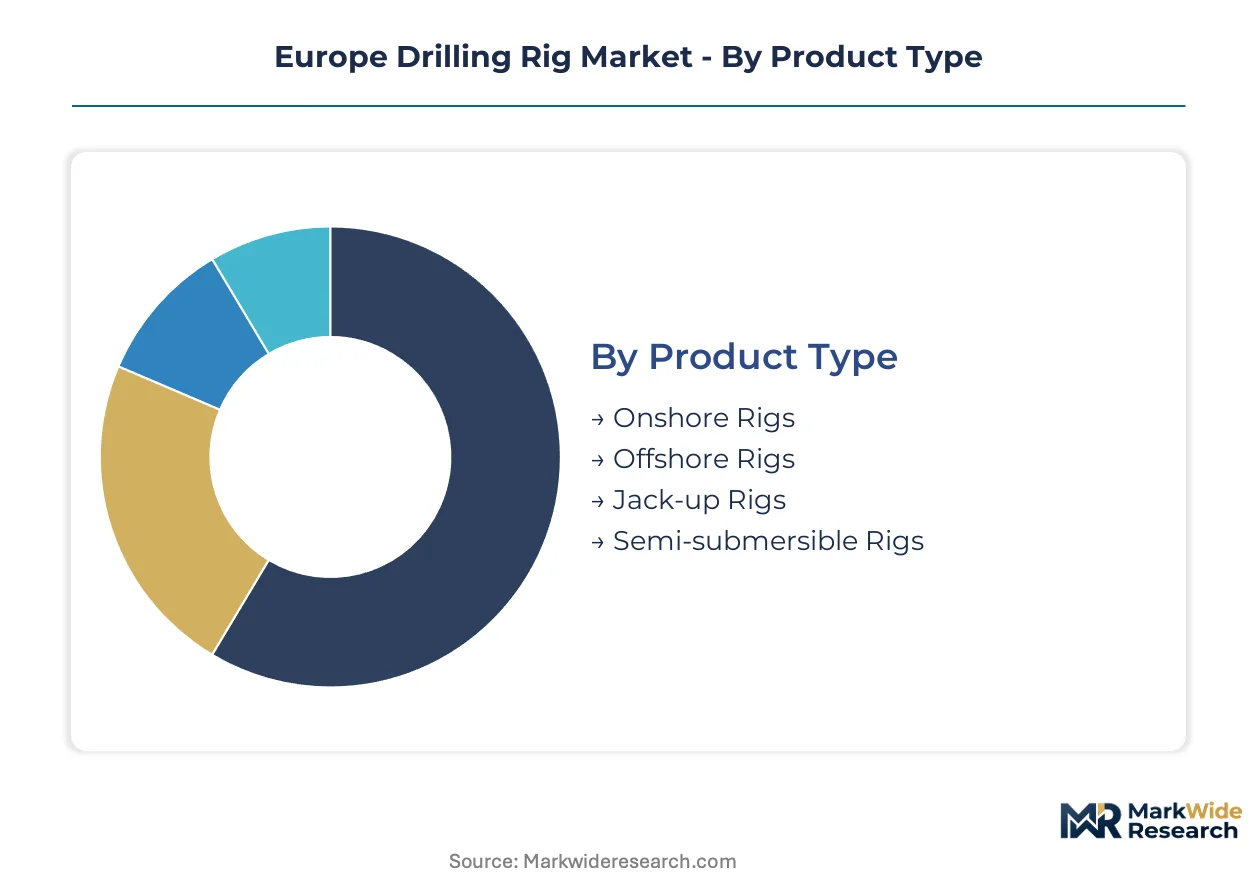
Segmentation in the Europe drilling rig market reveals how equipment specifications, deployment modes, and operator types determine service intensity and contract structures. Each dimension carries distinct aftermarket revenue profiles and regulatory compliance burdens that shape contractor profitability across the North Sea and Norwegian continental shelf.
Product Type:
After-sales service intensity varies dramatically across rig configurations, with harsh-environment offshore units demanding continuous technical support and classification society recertification.
- Offshore Rigs:These self-contained drilling platforms operate in water depths exceeding 500 meters, requiring dynamic positioning systems and subsea BOP stacks. Demand concentrates among Norwegian operators executing extended-reach campaigns in the Barents Sea, where EU methane regulations and PSA well integrity standards drive continuous equipment upgrades.
- Jack-up Rigs:Mobile platforms with retractable legs designed for shallow-water development of mature North Sea fields. UK and Dutch operators favor these units for platform drilling and slot recovery projects, with fleet utilization tied to basin redevelopment timelines and energy security procurement mandates.
- Onshore Rigs:Conventional land-based drilling systems deployed for unconventional gas in Poland and tight oil in the UK Weald Basin.
- Semi-submersible Rigs:Floating platforms with submerged pontoons providing stability in harsh North Sea wave conditions.
Offshore rigs hold the largest share; momentum sits with jack-up rigs as North Sea operators prioritize brownfield optimization over frontier exploration.
Technology:
Technology selection determines the depth of digital integration and the scale of proprietary service contracts that contractors can attach to base rig provision.
- Directional Drilling:Steerable bottom-hole assemblies enabling multiple target penetration from single surface locations. Norwegian operators deploy these systems aggressively in mature Ekofisk and Statfjord fields, where reservoir complexity and platform slot constraints make vertical drilling economically unviable.
- Rotary Drilling:Conventional rotating drillstring systems remain standard for straight-hole geothermal and mining applications. UK onshore shale exploration and Dutch geothermal heat projects sustain modest demand, though hydraulic fracturing moratoria in several EU member states constrain deployment scope.
- Hydraulic Fracturing:High-pressure fluid injection for reservoir stimulation, primarily relevant for Polish unconventional gas and limited UK tight oil prospects.
- Underbalanced Drilling:Managed pressure techniques reducing formation damage in depleted North Sea reservoirs.
Rotary drilling maintains baseline volume; directional drilling is climbing the fastest as extended-reach complexity escalates across Norwegian and UK mature assets.
End User:
Customer type dictates contract duration, risk allocation, and the degree of integrated service bundling that rig contractors can negotiate.
- Oil & Gas Companies:International majors and national oil companies operating North Sea assets under government production licenses. Equinor, BP, and TotalEnergies drive fleet utilization through multi-year drilling programs tied to field redevelopment commitments and domestic supply security targets.
- Service Providers:Drilling contractors and integrated project management firms leasing rigs to operators on well-by-well or campaign basis. These intermediaries concentrate in Aberdeen and Stavanger supply clusters, capturing margin through operational efficiency and supply chain coordination.
- Mining Industries:Mineral extraction firms deploying slim-hole rigs for core sampling and blasthole drilling.
- Government Agencies:State geological surveys and geothermal development authorities in the Netherlands and Denmark.
Oil & gas companies dominate contract value; service providers are expanding most quickly as operators unbundle integrated drilling packages.
Installation:
Deployment mode determines capital commitment intensity and the regulatory pathways governing platform safety certification.
- Mobile Installation:Self-propelled or towable rigs relocating between well locations without permanent seabed foundations. Norwegian PSA and UK NSTA regulations require continuous stability and station-keeping verification, creating recurring certification revenue for classification societies and marine warranty surveyors.
- Fixed Installation:Platform-mounted drilling packages permanently integrated with production facilities. UK North Sea operators favor these for hub-and-spoke developments where multiple satellite fields tie back to central processing infrastructure, though upfront capital requirements limit deployment to majors with balance sheet capacity.
- Temporary Installation:Rigs contracted for single-well or short-campaign deployment without long-term location commitment.
- Permanent Installation:Dedicated drilling structures built for field life-of-asset operations.
Mobile installation commands the largest fleet share; fixed installation shows the steepest expansion trajectory as operators consolidate processing infrastructure to reduce offshore carbon intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian operators deploy harsh-environment jack-ups for extended-reach campaigns while UK and Dutch contractors favor platform-mounted rigs for brownfield slot recovery, creating divergent fleet specifications across the North Sea basin.
Norway
Equinor and Aker BP drive jack-up utilization through Barents Sea exploration and mature field redevelopment in the Norwegian continental shelf. The Petroleum Safety Authority mandates progressively stringent well integrity protocols and subsea BOP testing standards. Stavanger anchors the supply cluster where drilling contractors coordinate with subsea engineering firms on integrated project tenders.
United Kingdom
BP and Harbour Energy prioritize platform drilling packages for hub-and-spoke developments tying back satellite fields to central processing infrastructure. The North Sea Transition Authority imposes methane emissions monitoring requirements under the UK Emissions Trading Scheme. Aberdeen concentrates contractor headquarters and classification society offices serving the UKCS fleet.
Netherlands
Neptune Energy and ONE-Dyas execute shallow-water gas field redevelopments requiring jack-up mobility across the Dutch continental shelf. REACH chemical authorization rules displace oil-based drilling fluids with synthetic alternatives. Rotterdam and Den Helder host mud engineering laboratories and rig refurbishment yards adapting fleet chemistry.
Denmark
Ørsted and TotalEnergies repurpose existing jack-up platforms for deep geothermal drilling in the Danish subsurface. The Danish Energy Agency streamlines permitting for renewable heat extraction projects leveraging offshore supply chains. Esbjerg functions as the logistics hub connecting North Sea rig operators with onshore geothermal developers.
Germany
Wintershall Dea conducts tight gas exploration in the North German Basin using onshore rotary rigs with managed pressure capabilities. The Federal Mining Act imposes groundwater protection standards affecting drilling fluid containment specifications. Celle and Wietze host specialized rig fabrication shops serving domestic unconventional gas campaigns.
Europe Drilling Rig Market Competitive Landscape
Capability concentration sits with specialized harsh-environment contractors; scale advantage sits with integrated energy service conglomerates. The market structures around three tiers: pure-play drilling contractors with certified North Sea fleets, integrated oilfield service providers bundling digital automation with rig provision, and engineering-to-drilling consortia capturing subsea installation margins. Dominant competitive moves include hybrid power retrofit partnerships with battery system vendors and selective fleet consolidation among jack-up specialists.
Within the integrated service tier, Schlumberger Limited and Saipem SpA exemplify divergent strategic positions—one anchoring digital drilling automation platforms, the other capturing margins through engineering-to-drilling contract bundling. Maersk Drilling AS occupies a position among pure-play contractors with purpose-built harsh-environment specifications. These three entities represent the archetype spectrum: technology-anchored automation providers, integrated project delivery specialists, and equipment-focused fleet operators.
| Leading Market Players |
|---|
| Aker Solutions ASA |
| Maersk Drilling AS |
| Saipem SpA |
| Dril-Quip Inc. |
| Seadrill Ltd |
| Noble Corporation PLC |
| Keppel Corporation Limited |
| Stena Drilling |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
EU carbon border adjustment exposure on high-grade steel plate determines both the spread between premium and standard rig day-rates and the geographic reconfiguration of fabrication capacity across the North Sea supply base. Contractors face compressed margins on legacy assets while capitalized players with certified low-emission systems capture pricing power in tender evaluations.
Pricing Analysis
Long-term offtake contracts with Norwegian operators under national petroleum directives anchor premium pricing for harsh-environment jack-ups, while spot-market availability in the UK North Sea creates volatility in standard-tier day-rates. Price differentiation hinges on EU F-Gas compliance certification and bundled digital automation services, with pure equipment lessors facing downward pressure from unbundled procurement patterns. Cost compression in the standard tier intensifies as operators extend asset life cycles rather than commission newbuilds. National oil companies exhibit the lowest price sensitivity due to energy security mandates, while independent service providers leasing on well-by-well terms show highest sensitivity to day-rate fluctuations.
Supply Chain Analysis
Tariff exposure between EU member states and third-country steel suppliers dominates supply chain risk planning for rig construction and major refurbishment programs. Fabrication capacity concentrates in Norway, the United Kingdom, and the Netherlands, with specialized high-grade steel plate sourcing from Germany and South Korea. Critical component dependencies include dynamic positioning systems, subsea BOP stacks, and battery-hybrid energy storage modules. Single-source vulnerability in steerable bottom-hole assembly technology creates chokepoints for directional drilling packages. Distribution runs through Aberdeen and Stavanger supply clusters coordinating with Den Helder and Esbjerg logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service unbundling fragments traditional integrated drilling contracts across the North Sea, creating specialized niches for contractors with certified emissions systems and proprietary automation platforms.
For Market Incumbents: Entrench competitive position through backward integration into battery-hybrid power system manufacturing and exclusive partnerships with classification societies for accelerated EU F-Gas recertification. Prioritize capacity maintenance in Stavanger and Aberdeen clusters where PSA and NSTA regulatory proximity accelerates certification timelines. Defend against margin erosion from pure equipment lessors by bundling real-time drilling automation with base rig provision. For New Entrants and Emerging Players: Deep geothermal drilling in the Netherlands and Denmark represents the most penetrable entry point, leveraging existing jack-up platform supply chains for renewable heat extraction projects. Platform-mounted rig refurbishment for UK hub-and-spoke developments offers secondary white-space with lower capital barriers than newbuild construction. Go-to-market positioning should emphasize EU Innovation Fund subsidy capture for hybrid power retrofits, differentiating from incumbent fossil-fuel-dependent service models. For Investors and Strategic Acquirers: The EU AI Act's pending high-risk designation for autonomous drilling control systems reshapes the acquisition landscape toward contractors with proven digital integration capabilities and established regulatory compliance frameworks. Long-term viability favors integrated service providers with engineering-to-drilling bundling capacity over pure equipment lessors facing automation displacement. Watch for PSA well integrity protocol amendments as the signal for accelerated fleet consolidation among North Sea-accredited contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Power Retrofit Partnerships | Battery-hybrid integration captures EU Innovation Fund subsidies while reducing fuel consumption during station-keeping operations. |
| Digital Automation Platform Deployment | Schlumberger and similar vendors collapse non-productive time through real-time downhole measurement orchestration. |
| Geothermal Co-Utilization Repurposing | Existing jack-up platforms pivot to deep geothermal drilling in Denmark and the Netherlands leveraging established supply chains. |
| Subsea BOP Certification Investment | Norway's Petroleum Safety Authority mandates progressively stringent testing protocols that filter market access toward capitalized players. |
| CSRD Disclosure Compliance Services | Mandatory sustainability reporting creates demand for emissions monitoring instrumentation and verified low-carbon rig certification. |
Research Methodology
Desk research of EU regulatory filings, Petroleum Safety Authority directives, North Sea Transition Authority emissions protocols, and customs trade data preceded structured interviews with drilling contractors, subsea engineering firms, mud engineering laboratories, and classification society surveyors. Primary fieldwork captured operational constraints on legacy asset retrofits and tender evaluation criteria at Equinor, BP, and Harbour Energy procurement teams. Secondary validation drew from SEC filings of listed drilling contractors, ECHA chemical authorization databases, and Innovation Fund disbursement records. Bottom-up rig utilization modeling triangulated against top-down energy security mandate projections.
Assumptions held fixed include EU F-Gas phasedown quotas, UK Emissions Trading Scheme coverage, and Norwegian continental shelf production license timelines; variables tested included EU AI Act implementation pacing and carbon border adjustment mechanism expansion scope. Segmentation modeling spanned rig configuration, technology type, end-user contract structure, and installation mode across the analysis window. CAGR derivation incorporated fleet age profiles, brownfield redevelopment timelines, and geothermal repurposing adoption curves. Industry-specific inputs included North Sea platform slot recovery schedules and Barents Sea exploration permit issuance patterns.
Macroeconomic conditions sit as an overlay; deviation in steel commodity pricing, offshore construction labor availability, or EU innovation subsidy allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and operator capital commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Global Dozers Market
Mining Equipment
Surface Mining Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Global Underground Mining Vehicles Market