
 LAMEA Stud Welding Machine Market | 2026-2036
LAMEA Stud Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Stud Welding Machine Market Insights
ISO 14555 certification for arc stud welding is bifurcating the competitive landscape into qualified system suppliers and peripheral equipment vendors. STANLEY Engineered Fastening leverages its captive fastener ecosystem to bundle welding equipment with consumable studs. HBS Bolzenschweiss-Systeme GmbH & Co. KG anchors its position through deep specialization in capacitor-discharge technology for thin-gauge applications. Taylor Studwelding Systems Ltd dominates aftermarket service networks across Gulf Cooperation Council job sites.
Stud welding machines join metal fasteners to base materials through controlled electric-arc or capacitor-discharge fusion, typically achieving shear strengths exceeding 350 MPa in structural steel applications. The equipment serves primarily as a production alternative to drilled-and-tapped connections in high-volume fabrication environments. Automatic product-type systems command the widest deployment in shipyard panel lines where repeatability requirements exceed manual operator consistency. Arc welding technology sustains the largest installed base, though capacitor-discharge configurations are capturing share in automotive body-in-white applications where minimal reverse-side marking is critical. Construction end users generate the heaviest equipment utilization, particularly in bridge-deck forming where welded shear connectors replace bolted alternatives.
Brazil's national construction regulator and South Africa's Department of Trade and Industry enforce equipment-safety and electromagnetic-compatibility standards that filter non-compliant imports from regional tenders. The UAE's civil defense and municipal engineering departments mandate third-party weld-procedure qualification for public infrastructure fasteners. Stakeholders must monitor evolving local-content thresholds in Saudi Arabia and Algeria, as procurement rules increasingly privilege assembly or fabrication within national borders over pure equipment import.
Market Dynamics
ISO 14555 certification requirements are bifurcating the LAMEA competitive landscape into qualified system suppliers and peripheral equipment vendors, forcing contractors toward certified automatic systems for public infrastructure tenders.
Growth Catalysts
- Bridge-deck forming demand:State-led megaprojects in Brazil and the UAE require welded shear connectors as bolted alternatives face rejection under updated structural codes.
- ANVISA equipment-safety enforcement:Brazil's national construction regulator filters non-compliant imports from regional tenders, privileging certified domestic distributors.
- Capacitor-discharge technology:Thin-gauge automotive applications in South Africa are absorbing CD systems for body-in-white assembly where reverse-side marking must remain minimal.
Market Restraints
- Copper and silicon steel input volatility:Transformer core materials face price swings that compress margin on mid-range arc welding systems.
- GCC aftermarket parts concentration:Service networks cluster around Dubai and Jeddah, leaving remote Saudi and Omani job sites exposed to extended downtime.
- Manual operator substitution:Semi-automatic systems face displacement by robotic cells in high-volume shipyard panel lines.
Strategic Opportunities
- Algerian local-content thresholds:Procurement rules increasingly privilege assembly within national borders over pure equipment import, creating partnership openings for regional fabricators.
- Renewable energy fastening:Wind tower base-plate and solar tracker foundation applications remain underpenetrated versus construction and automotive verticals.
- Saudi Vision 2030 industrial clusters:NEOM and Red Sea Project sites mandate third-party weld-procedure qualification, accelerating demand for certified automatic systems.
Industry Challenges
- Weld-procedure qualification timelines:UAE civil defense and municipal engineering departments require third-party certification that extends project mobilization by 6-12 weeks.
- Electromagnetic compatibility testing:South Africa's Department of Trade and Industry enforces standards that add compliance cost for European and Asian OEMs.
- Legacy manual system integration:Shipyards running 1990s-era panel lines face retrofit complexity when upgrading to automatic feed mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Stud Welding Machine Market |
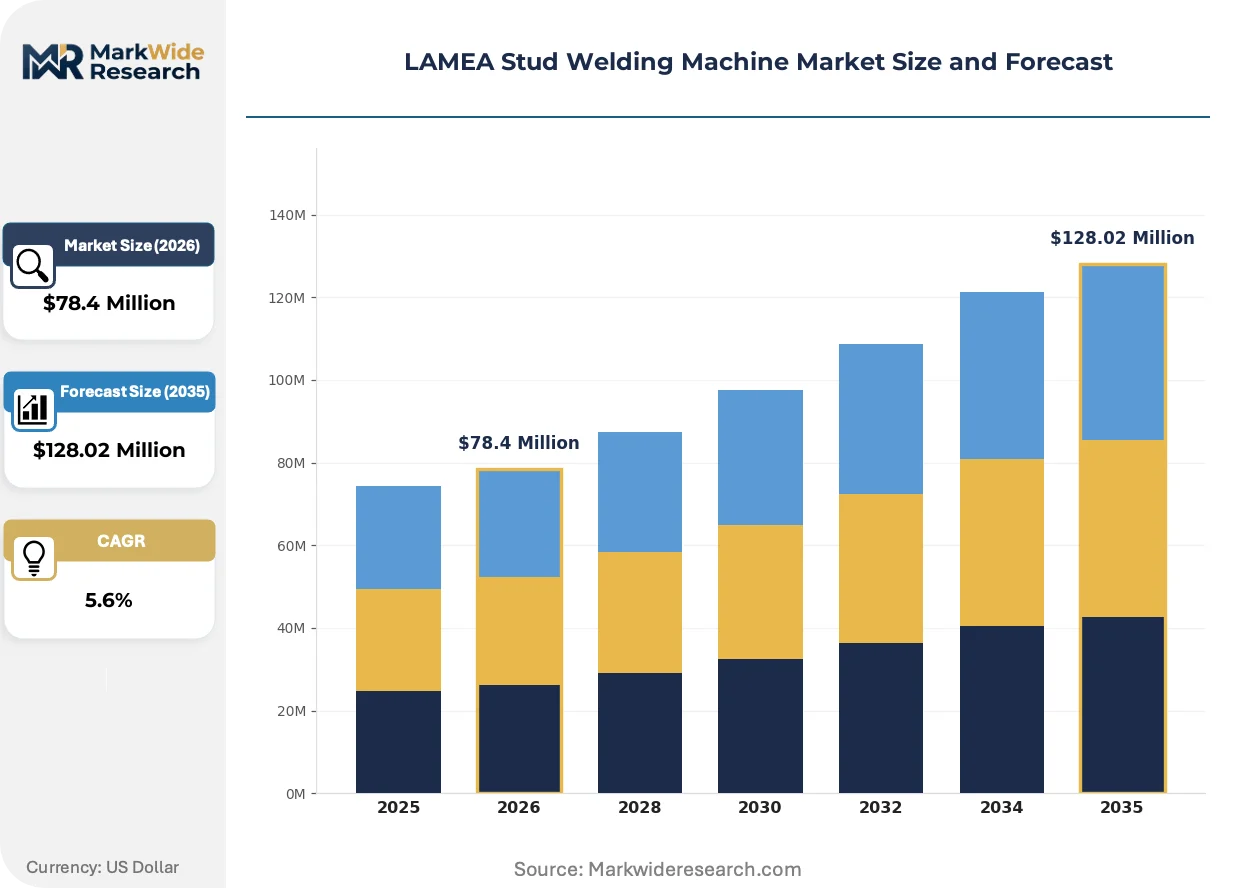
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $128.02 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Portable Technology: Arc Welding, Capacitor Discharge, Resistance, Laser Welding End User: Construction, Automotive, Aerospace, Electrical Application: Heavy Machinery, Bridges, Shipbuilding, HVAC |
| Companies Covered | STANLEY Engineered Fastening, Bolte GmbH, HBS Bolzenschweiss-Systeme GmbH & Co. KG, Midwest Fasteners Inc., KÖSTER & CO. GMBH, Taylor Studwelding Systems Ltd, HEINZ SOYER BOLZENSCHWEISSTECHNIK GMBH, ChangZhou Jinda Welding Co., Ltd., Cruxweld Industrial Equipments Private Limited, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Stud Welding Machine Market Trends and Innovations
Digital weld monitoring and closed-loop process control are reshaping how contractors demonstrate compliance to regional regulators. Equipment suppliers now embed arc-voltage feedback systems as standard.
Capacitor-discharge welding with microprocessor-controlled energy discharge is displacing conventional arc systems in automotive body-in-white applications across South Africa and Morocco. Tier-1 suppliers to Renault and Ford Otosan are specifying CD equipment to eliminate reverse-side marking on visible panel surfaces. This displacement is compressing the addressable market for low-amperage arc systems in thin-gauge segments.
ANVISA and South Africa's Department of Trade and Industry are synchronizing electromagnetic-compatibility enforcement with ISO 14555 weld-quality mandates. Equipment importers must now dual-certify for safety and process qualification before tender eligibility. Brazilian bridge contractors are responding by consolidating vendor relationships with ISO-certified system suppliers rather than maintaining multi-brand fleets.
After-sales service unbundling is fragmenting buyer relationships across Gulf Cooperation Council job sites. Contractors now separate equipment procurement from maintenance contracts, sourcing spare parts through independent distributors. This pattern is most visible in Saudi Arabia's Red Sea Project zone, where European OEMs compete against UAE-based service aggregators for multi-year maintenance agreements.
LAMEA Stud Welding Machine Market Segmentation
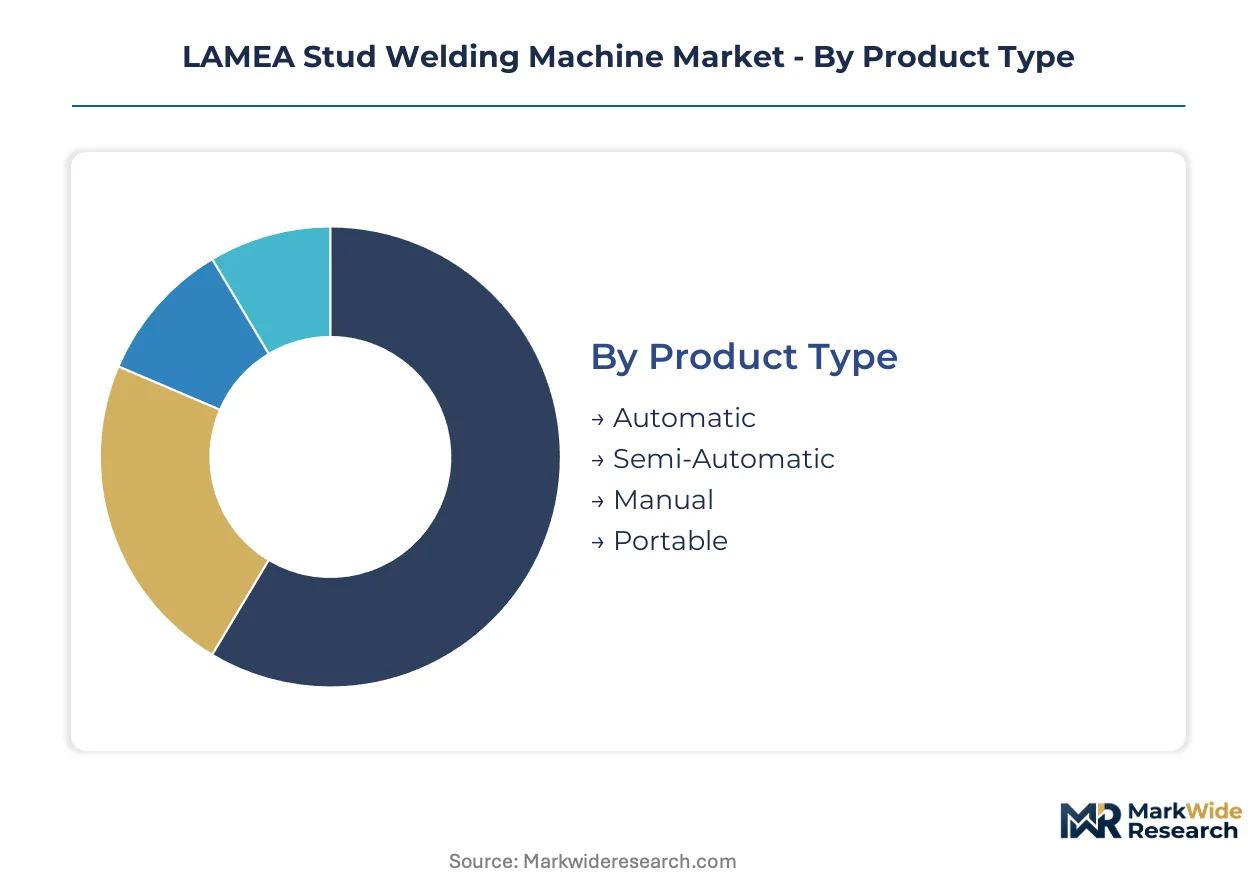
Stud welding equipment procurement across Latin America, Middle East, and Africa splits along certification requirements and operational intensity. Contractors in Brazil and the UAE select product types based on ANVISA safety mandates and municipal weld-procedure qualifications respectively.
Product Type:
ANVISA equipment-safety enforcement in Brazil and third-party weld-procedure mandates from UAE civil defense departments privilege certified automatic systems in public tenders.
- Automatic:Systems integrate programmable feed mechanisms and closed-loop arc-voltage feedback for repeatability in high-volume panel lines. Bridge-deck forming contractors in Brazil and shipyards in the UAE specify these units to meet ISO 14555 certification requirements for structural shear connectors.
- Semi-Automatic:Equipment requires operator intervention for stud loading while maintaining electronic process control. South African automotive suppliers deploy these for mid-volume body-in-white applications where full automation remains uneconomical.
- Manual:Hand-held units serve repair and field welding operations with basic arc initiation. Remote Saudi and Omani job sites rely on these where service network gaps complicate automatic system maintenance.
- Portable:Battery-powered or generator-compatible configurations enable on-site mobilization for infrastructure maintenance crews. Algerian state-owned construction firms favor these for distributed megaproject sites with limited grid access.
Automatic systems handle the majority of throughput in certified infrastructure tenders; portable configurations are gaining share fastest in remote North African job sites.
Technology:
Cost tier differentiation separates high-investment arc systems from compact capacitor-discharge units targeting thin-gauge precision.
- Arc Welding:Drawn-arc and short-cycle processes deliver fusion depths exceeding 6mm in structural steel plate. Brazilian bridge contractors specify these for shear connector welding under updated national structural codes that reject bolted alternatives.
- Capacitor Discharge:Microprocessor-controlled energy discharge achieves sub-millisecond weld times with minimal heat-affected zones. Tier-1 automotive suppliers in South Africa and Morocco specify CD equipment to eliminate reverse-side marking on visible body panels for Renault and Ford Otosan assembly lines.
- Resistance:Pressure-assisted current flow suits high-speed fastening of small-diameter studs in electrical component assembly. Moroccan electrical manufacturers deploy these for busbar and switchgear production.
- Laser Welding:Fiber-laser delivery enables non-contact fusion of dissimilar metals with precision positioning. Gulf aerospace maintenance facilities evaluate these for titanium fastener applications in aircraft component repair.
Arc welding sustains the broadest installed base across heavy fabrication; capacitor-discharge technology is expanding most quickly in automotive thin-gauge segments.
End User:
Application maturity and margin structure concentrate supplier attention on construction and automotive verticals.
- Construction:Bridge-deck forming, steel framing, and infrastructure metalwork generate the heaviest equipment utilization. Brazilian state-led megaprojects and UAE municipal engineering departments mandate certified automatic systems for public fasteners.
- Automotive:Body-in-white assembly and exhaust system fabrication drive demand for minimal-marking weld processes. South African and Moroccan plants supplying European OEMs specify capacitor-discharge systems to meet surface-quality standards.
- Aerospace:Aircraft structural repair and engine component fastening require specialized precision equipment. UAE and Saudi maintenance, repair, and overhaul facilities represent emerging demand pockets.
- Electrical:Switchgear, transformer, and busbar manufacturing utilize high-speed resistance and arc processes. Local-content thresholds in Algeria and Saudi Arabia favor domestic electrical equipment fabricators sourcing certified welding systems.
Construction absorbs the greatest equipment volume; automotive applications are climbing the fastest on precision requirements.
Application:
Geographic concentration of project types shapes regional demand patterns across the LAMEA zone.
- Heavy Machinery:Mining equipment, agricultural implements, and industrial press fabrication require deep-penetration arc welding. Brazilian and South African original equipment manufacturers specify automatic systems for chassis and frame assembly.
- Bridges:Steel girder and composite deck construction demands high-throughput shear connector welding. Brazilian national infrastructure programs and UAE transport authority projects specify ISO 14555-certified automatic equipment.
- Shipbuilding:Panel line production and hull assembly rely on repeatability exceeding manual operator consistency. Gulf Cooperation Council shipyards in the UAE and Saudi Arabia are retrofitting 1990s-era lines with automatic feed mechanisms.
- HVAC:Ductwork, air handling units, and refrigeration system fabrication utilize portable and semi-automatic equipment. Saudi Vision 2030 industrial clusters and NEOM construction zones generate concentrated demand for climate system installation.
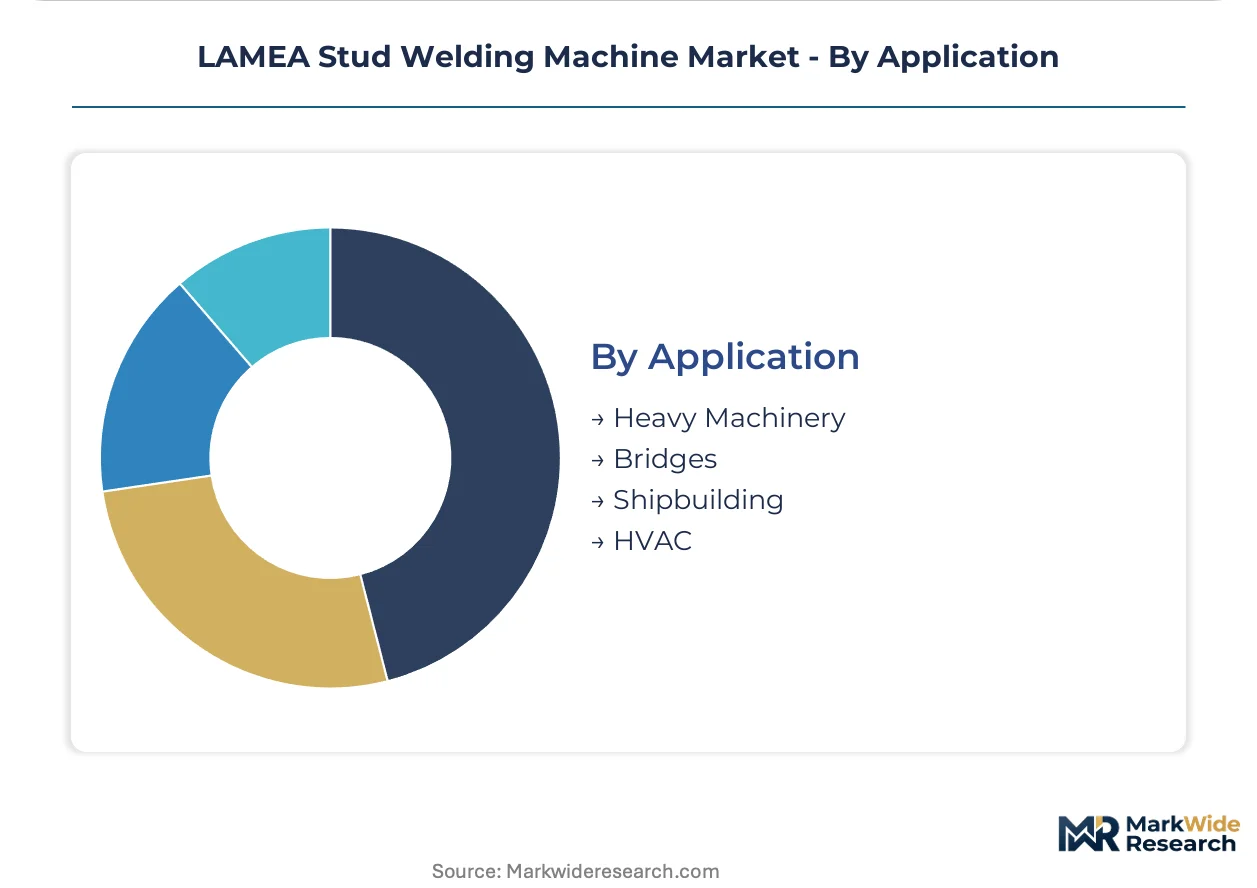
Bridge construction commands the largest project-based equipment deployment; shipbuilding panel-line retrofits represent the steepest expansion trajectory for automatic system suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The LAMEA stud welding machine market derives structural support from anchor infrastructure assets spanning Brazil's bridge corridors, UAE's port expansions, and Saudi Arabia's giga-project zones. These physical installations create concentrated demand pockets for certified fastening equipment.
Brazil
Federal bridge-deck programs and state-led highway expansions absorb automatic arc welding systems for shear connector installation. ANVISA equipment-safety mandates filter non-compliant imports from public tenders, privileging certified domestic distributors. São Paulo industrial fabricators supply certified systems to southeast corridor megaprojects including the Rio-São Paulo high-capacity rail link.
United Arab Emirates
Khalifa Port expansion and Dubai Metro line extensions generate sustained demand for ISO 14555-qualified automatic equipment. Municipal engineering departments mandate third-party weld-procedure qualification for all public infrastructure fasteners. Jebel Ali industrial zone clusters Gulf Cooperation Council distribution hubs for European OEM service networks.
Saudi Arabia
NEOM linear city construction and Red Sea Project tourism infrastructure require high-throughput fastening for steel framing and bridge components. Saudi Vision 2030 local-content thresholds privilege assembly within national borders over pure equipment import. Riyadh-based industrial zones attract partnership arrangements between European system suppliers and domestic fabricators.
South Africa
Automotive body-in-white assembly for export markets drives capacitor-discharge technology adoption among tier-1 suppliers. The Department of Trade and Industry enforces electromagnetic-compatibility standards that add compliance cost for European and Asian OEMs. Durban-Gauteng industrial corridor hosts retrofit programs for mid-volume semi-automatic system deployment.
Algeria
State-owned construction firms distribute portable welding equipment across remote megaproject sites with limited grid access. Procurement rules increasingly require assembly or fabrication within national borders, creating openings for regional equipment partnerships. Mediterranean coastal industrial zones concentrate HVAC and electrical fabrication demand for climate system installation.
LAMEA Stud Welding Machine Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and aftermarket reach. The LAMEA competitive structure bifurcates between ISO 14555-qualified system suppliers and peripheral equipment vendors serving uncertified segments. Three archetypes dominate: captive fastener ecosystem bundlers, deep-technology specialists in capacitor-discharge processes, and aftermarket service network aggregators. Consolidation pressure favors M&A between European OEMs and regional distributors, while technology licensing agreements accelerate local-content compliance.
Within the captive ecosystem tier, STANLEY Engineered Fastening represents equipment-fastener bundling strategies. Deep-technology specialists exemplified by HBS Bolzenschweiss-Systeme GmbH & Co. KG occupy positions in precision capacitor-discharge applications. Among aftermarket-focused players, Taylor Studwelding Systems Ltd anchors service network concentration across Gulf Cooperation Council job sites. These three entities collectively illustrate how competitive positioning in LAMEA markets depends on certification depth, captive consumable supply, and geographic service density rather than equipment manufacturing scale alone.
| Leading Market Players |
|---|
| STANLEY Engineered Fastening |
| Bolte GmbH |
| HBS Bolzenschweiss-Systeme GmbH & Co. KG |
| Midwest Fasteners Inc. |
| KÖSTER & CO. GMBH |
| Taylor Studwelding Systems Ltd |
| HEINZ SOYER BOLZENSCHWEISSTECHNIK GMBH |
| ChangZhou Jinda Welding Co., Ltd. |
| Cruxweld Industrial Equipments Private Limited |
| Others |
Pricing and Supply Chain Analysis
Ninety-day transformer core lead times from European mills compress margin flexibility for mid-range arc system assemblers, concentrating pricing power with ISO 14555-certified suppliers who pre-position inventory ahead of Brazilian and UAE tender windows. This inventory stratification separates certified automatic system vendors from peripheral equipment traders competing on spot availability.
Pricing Analysis
Volume-discount tiering structures stratify across certification grade, with ISO 14555-qualified automatic systems commanding premium positioning against uncertified manual units. Price differentiation hinges on ANVISA safety compliance and third-party weld-procedure qualification, with Brazilian bridge contractors showing lowest sensitivity due to regulatory mandate rigidity. Pricing pressure stems from copper and silicon steel input volatility, compressing mid-range arc welding system margins while premium certified tiers maintain resilience through captive fastener bundling.
Supply Chain Analysis
Inbound logistics costs from Hamburg to Santos and Jebel Ali fluctuate with container availability on Europe-Latin America and Europe-Middle East lanes, elevating landed cost uncertainty for German and Italian OEMs. Supply concentrates in Germany, Italy, and China for transformer assemblies, control systems, and consumable studs. Raw material dependencies center on copper windings, silicon steel cores, and ceramic ferrules. Single-source vulnerability from European transformer suppliers creates exposure for Brazilian assemblers. Distribution runs through certified domestic distributors in São Paulo and Dubai-based service aggregators across Gulf Cooperation Council job sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 14555 certification bifurcation fragments competitive space into qualified system suppliers and peripheral vendors, creating niche openings for regional fabricators meeting Saudi and Algerian local-content thresholds.
For Market Incumbents: Shield installed base relationships by embedding arc-voltage feedback systems as standard and pre-qualifying weld procedures with UAE civil defense departments ahead of tender publication. Backward integration into consumable stud production secures margin against raw material volatility from European copper mills. Channel control through exclusive distributor agreements in São Paulo industrial zones limits exposure to independent spare parts aggregators. For New Entrants and Emerging Players: Differentiate on capacitor-discharge specialization for South African and Moroccan automotive body-in-white applications where reverse-side marking constraints displace conventional arc systems. Target Algerian state-owned construction firms with portable equipment partnerships that satisfy local-content assembly requirements. Pursue technology licensing arrangements with European OEMs to accelerate certification timelines for Saudi Vision 2030 industrial cluster participation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant welding equipment divisions lacking ISO 14555 qualification depth. Long-term viability centers on certification moats and aftermarket service density rather than manufacturing scale alone. Acquisition archetypes include UAE-based service aggregators with Gulf Cooperation Council job site penetration. Monitor Saudi local-content threshold enforcement as inflection signal for partnership-driven market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14555 Certification Investment | ANVISA and UAE municipal mandates filter non-compliant imports from public tenders. |
| Backward Integration into Consumable Studs | STANLEY's captive fastener ecosystem demonstrates margin protection against copper volatility. |
| Regional Service Network Expansion | Taylor Studwelding's Gulf Cooperation Council density illustrates aftermarket unbundling defense. |
| Local-Content Partnership Formation | Saudi Vision 2030 and Algerian procurement rules privilege assembly within national borders. |
| Capacitor-Discharge Technology Licensing | HBS specialization in thin-gauge precision addresses Renault and Ford Otosan surface-quality standards. |
Research Methodology
The analysis maps automatic, semi-automatic, manual, and portable product configurations alongside arc, capacitor-discharge, resistance, and laser welding technologies, each validated through equipment procurement managers at Brazilian bridge contractors, UAE shipyard panel line engineers, and South African automotive tier-1 supplier quality directors. Secondary sources include ANVISA equipment-safety filings, UAE civil defense weld-procedure qualification registries, South African Department of Trade and Industry electromagnetic-compatibility standards, and Saudi Vision 2030 industrial cluster procurement disclosures. Bottom-up equipment shipment tallies triangulate against top-down infrastructure investment flows across the LAMEA zone.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product type, welding technology, end-user vertical, and geographic regulatory cluster. CAGRs derive from equipment replacement cycles tied to infrastructure project pipelines and automotive production schedules. Industry-specific forecast inputs incorporate bridge-deck forming shear connector specifications and body-in-white surface-quality mandates from European OEMs.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment commitment, stable copper and silicon steel pricing, and consistent ISO 14555 enforcement would require recalibration. Forecasts reflect documented assumptions regarding certification timeline standardization and regional regulatory alignment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Small Bulldozers Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Piles Turner Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market