
 Retort Pouch Market | 2026-2036
Retort Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Retort Pouch Market Intelligence
FDA 21 CFR 177.1390 compliance for laminated food-contact structures is collapsing the supplier base to converters with validated migration testing. Amcor plc leverages multi-layer coextrusion capabilities across Asia-Pacific and European production nodes. Berry Global sustains North American dominance through backward integration into cast polypropylene film. Huhtamaki competes in emerging markets with localized printing and forming operations.
A retort pouch is a multi-layer flexible package constructed from polyester, aluminum foil, polypropylene, and adhesive laminates, engineered to withstand sterilization temperatures exceeding 121°C while maintaining oxygen and moisture barriers. The format replaces metal cans and glass jars in shelf-stable food distribution, reducing shipping weight and enabling microwave heating. Food applications dominate volume, with ready-to-eat meals and soups anchoring demand among institutional buyers and retail chains. Pharmaceutical retort pouches for sterile medical devices represent a fast-growing margin pool as hospitals shift from rigid containers.
FDA migration limits under 21 CFR 177, EU Regulation 10/2011 on plastic food-contact materials, and Japan's Food Sanitation Act collectively govern material composition and additive approvals across major demand centers. These frameworks force converters to maintain parallel formulation portfolios, raising R&D overhead but creating regulatory moats against uncertified competitors. Stakeholders must monitor evolving state-level extended producer responsibility laws in the United States and European Union packaging waste directives that threaten multi-material laminate recyclability assumptions.
Market Dynamics
The retort pouch market is being restructured by the collision of military procurement standardization with civilian food retail channel consolidation, forcing converters to maintain dual certification tracks for high-barrier laminates while retail chains demand shorter production runs with regional customization.
Growth Catalysts
- Military Ration Modernization:Defense agencies in the United States, United Kingdom, and Australia are replacing metal cans with retort pouches to reduce field logistics weight and enable flameless ration heaters.
- FDA 21 CFR 177.1390:Migration testing protocols for laminated food-contact structures are validating converter capabilities and creating regulatory barriers against uncertified competitors in North American supply chains.
- Polypropylene Barrier Films:Advances in coextruded cast PP with enhanced oxygen transmission rates are displacing aluminum foil in microwave-only applications, opening new retail segments.
Market Restraints
- Aluminum Price Volatility:Foil layer costs in multi-material laminates swing with London Metal Exchange pricing, compressing converter margins during commodity spikes.
- Recyclability Friction:EU packaging waste directives and emerging state-level extended producer responsibility laws in California and New York threaten multi-material laminate acceptance in circular economy frameworks.
- Retort Sterilization Limitations:Maximum temperature thresholds of 135°C constrain protein-dense meal formulations, blocking penetration into certain institutional nutrition segments.
Strategic Opportunities
- Pharmaceutical Sterile Devices:Hospital systems in Germany, Japan, and the United States are shifting from rigid containers to retort-sterilized flexible pouches for surgical instrument kits, creating premium margin pools.
- India Packaged Food Retail:Urban middle-class expansion and FSSAI food safety enforcement are accelerating ready-to-eat meal adoption in modern trade channels.
- Digital Printing Integration:Convergence of high-barrier coextrusion with inkjet personalization enables batch-level traceability and regional flavor versioning without plate changeover costs.
Industry Challenges
- Migration Testing Bottlenecks:FDA and EU 10/2011 parallel certification timelines stretch 18-24 months, delaying new product launches and freezing formulation innovation cycles.
- Laminate Delamination Risk:Adhesive layer failures during retort sterilization require specialized polymer science expertise that concentrates among aging technical workforces in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retort Pouch Market |
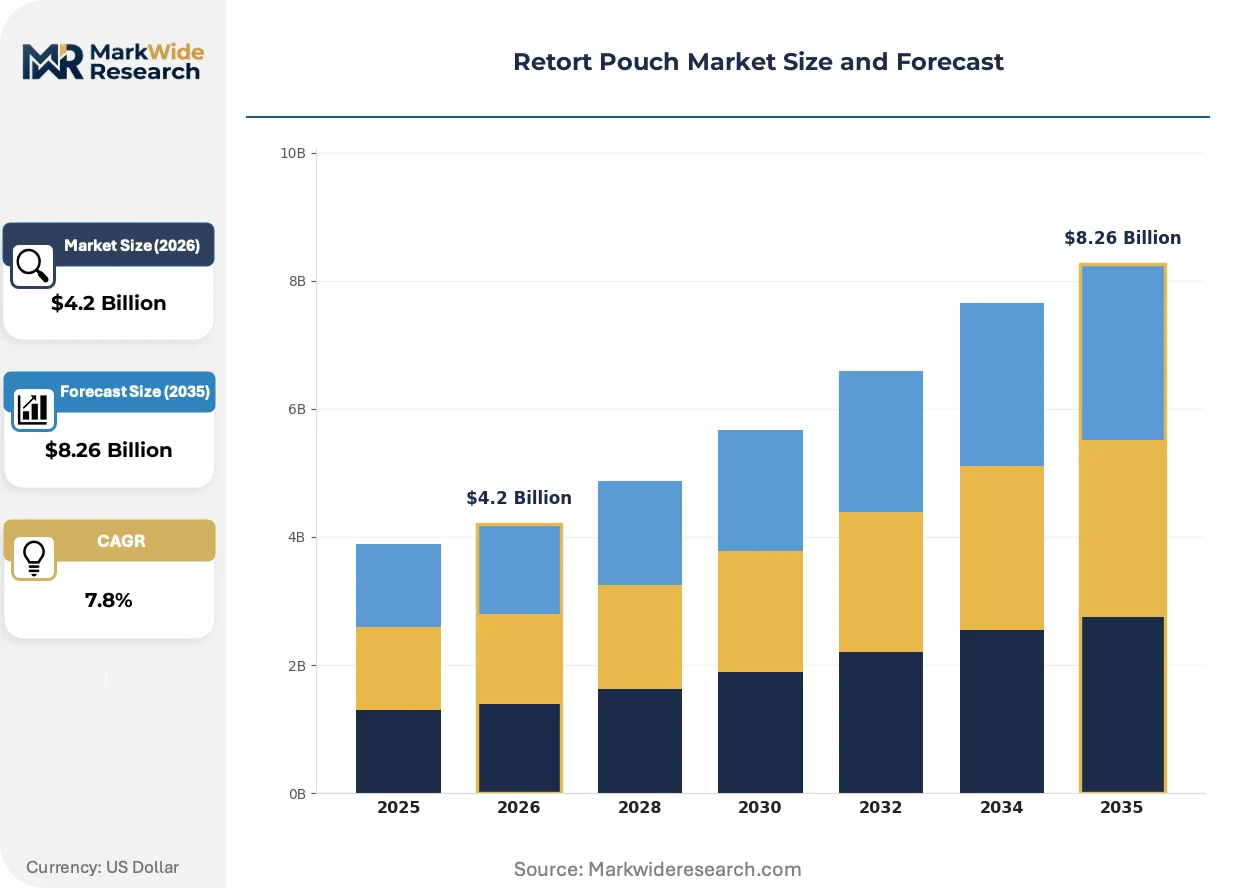
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.26 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverage, Pet Food, Pharmaceuticals Material: Aluminum, Polyester, Polypropylene, Nylon End User: Food Manufacturers, Beverage Companies, Retailers, Hospitals Application: Ready-to-Eat Meals, Sauces, Snacks, Soups |
| Companies Covered | Berry Global, Sonoco Products Company, Amcor plc, Constantia Flexibles, ProAmpac, Mondi Group, Huhtamaki, Coveris, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retort Pouch Market Strategic Shifts & Innovations
Retort pouch engineering is splitting along performance-versus-sustainability fault lines, with aluminum-dependent military specifications diverging from retail formats pursuing mono-material recyclability and digital supply chain integration.
High-barrier coextruded films with ethylene vinyl alcohol interlayers are bifurcating the market between microwave-transparent retail formats and foil-reinforced military rations. Food service distributors in the United States and United Kingdom are adopting EVOH-based pouches for chilled distribution networks, while defense procurement maintains aluminum foil for ambient shelf stability. This material divergence is compressing converter R&D budgets as parallel formulation portfolios become mandatory.
EU Regulation 10/2011 on plastic food-contact materials is tightening additive approval lists and migration limit enforcement, forcing Asian exporters to reformulate adhesive systems for European market access. The regulation's 2024 amendment cycle added testing burdens for primary aromatic amines, particularly affecting polyurethane-based laminates. German and French retail chains are now requiring third-party certification documentation that exceeds baseline compliance, filtering supplier bases.
Direct-to-retailer procurement contracts are displacing traditional distributor intermediaries in North American and European ready-to-eat meal segments. Retail chains in the United States are consolidating supplier panels and demanding vendor-managed inventory with scan-based trading terms. This channel compression is most visible in Walmart and Kroger private-label programs, where converters must integrate with retail ERP systems for automated replenishment signaling.
Retort Pouch Market Segmentation
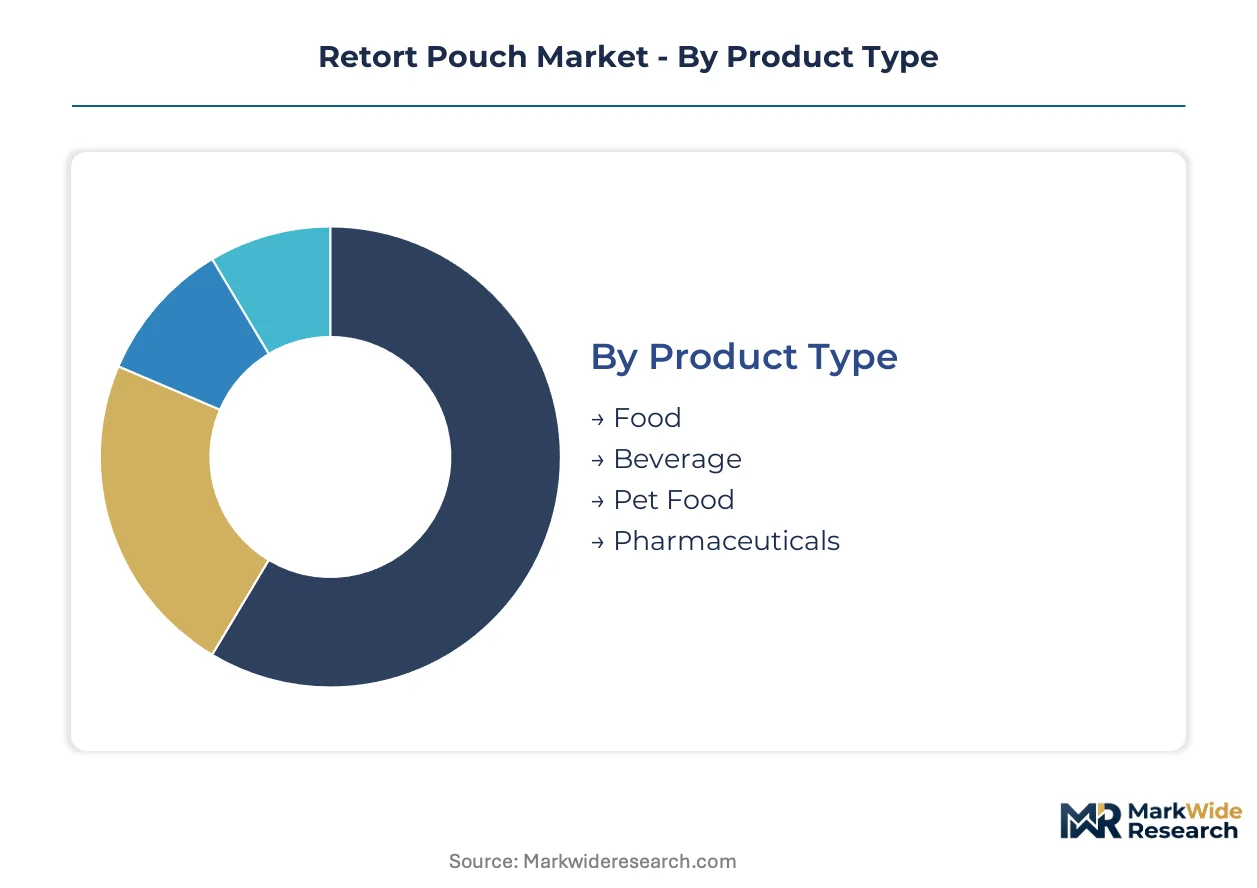
Retort pouch segmentation reveals divergent technical requirements across defense procurement, retail food service, and pharmaceutical sterilization. Material selection and barrier specifications vary sharply by end-use regulatory environment.
Product Type:
FDA 21 CFR 177.1390 and EU 10/2011 migration testing protocols create distinct certification tracks for each product category, with pharmaceutical applications demanding the most stringent validation cycles.
- Food:Multi-layer laminates with aluminum foil or EVOH interlayers withstand 121°C sterilization for shelf-stable ready-to-eat meals and institutional rations. Defense agencies in the United States, United Kingdom, and Australia drive specification tightening for field-deployable formats.
- Beverage:High-barrier coextruded films with enhanced puncture resistance accommodate liquid sterilization and hot-fill compatibility. Demand concentrates in Asian retail channels for ready-to-drink teas and functional beverages requiring ambient distribution.
- Pet Food:Odor-barrier formulations with enhanced seal integrity address protein-rich wet food formulations. Premium pet food manufacturers in Germany and Japan specify pouches with improved tear resistance for consumer convenience.
- Pharmaceuticals:Sterile medical device pouches meet ISO 11607 and FDA 510(k) requirements for surgical instrument kits. Hospital systems in the United States and Germany are shifting from rigid containers to flexible retort formats for supply chain efficiency.
Established volume favors Food; emerging adoption favors Pharmaceuticals.
Material:
Cost tier differentiation separates military-grade specifications from retail formats pursuing mono-material recyclability.
- Aluminum:Foil layers at 7-12 microns deliver near-zero oxygen transmission for multi-year military ration shelf life. Defense procurement in Australia and the United States maintains aluminum dependency despite circular economy pressures.
- Polyester:Biaxially oriented PET provides structural rigidity and print surface for retail-facing graphics. Food service distributors in the United Kingdom specify polyester-leaning laminates for chilled distribution networks with shorter shelf-life requirements.
- Polypropylene:Cast and oriented PP layers enable microwave-transparent formats without metallic components. Coextruded barrier grades with EVOH interlayers are displacing foil in civilian retail segments across North American mass-market channels.
- Nylon:Polyamide layers add puncture resistance and toughness for bone-in meat and seafood applications. Japanese converters leverage nylon expertise for premium retort pouch formats in convenience store retail.
Defense procurement anchors Aluminum volume; sustainability mandates accelerate Polypropylene substitution.
End User:
Customer type determines order scale, customization requirements, and certification burden.
- Food Manufacturers:Large-scale ready-to-eal meal producers run high-volume lines with validated retort cycles. Procurement consolidation among North American processors is narrowing approved supplier lists.
- Beverage Companies:Hot-fill and aseptic retort compatibility requirements drive specialized laminate development. Functional beverage brands in South Korea and Taiwan specify transparent high-barrier formats for visual product differentiation.
- Retailers:Private-label programs demand shorter production runs with regional flavor versioning and digital print compatibility. Walmart and Kroger in the United States enforce vendor-managed inventory with scan-based trading terms.
- Hospitals:Sterile processing departments require lot-level traceability and validated sterilization assurance. German hospital systems are piloting retort-sterilized surgical kits to reduce central sterile supply chain costs.
Food Manufacturers represent the deepest volume base; Hospitals are climbing the fastest as sterile device conversion accelerates.
Application:
Application maturity varies by protein density, viscosity, and distribution temperature requirements.
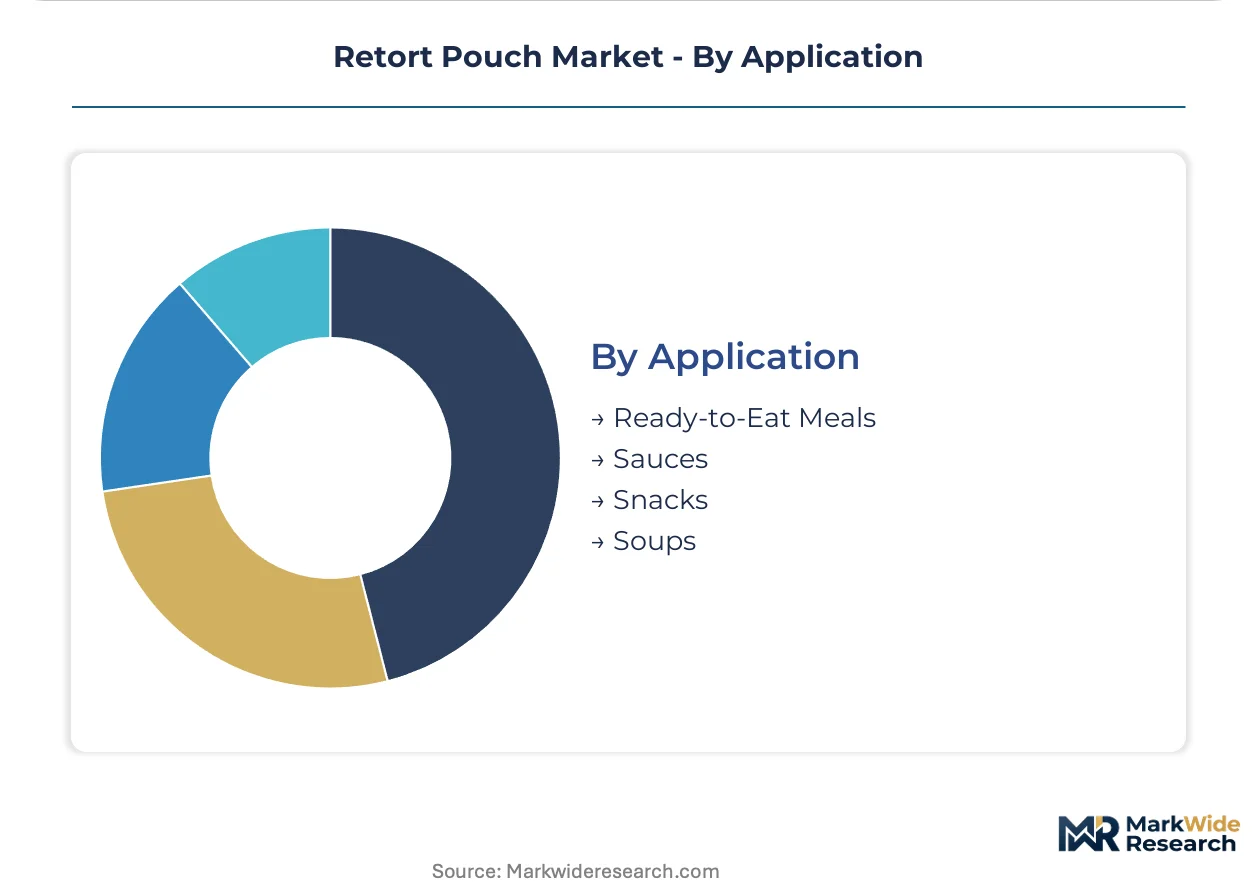
- Ready-to-Eat Meals:Complete meal formulations with protein, starch, and vegetable components require balanced barrier properties and reheating compatibility. Military MRE programs in the United States and United Kingdom specify flameless ration heater compatibility.
- Sauces:High-acid and tomato-based formulations leverage polyester-leaning laminates with reduced foil content. Italian and Mexican cuisine sauce lines in North American retail are expanding pouch format penetration.
- Snacks:Retort-sterilized shelf-stable snacks represent a nascent category with format experimentation. Japanese convenience store chains are testing retort-pouched prepared snacks for ambient distribution.
- Soups:Liquid and semi-liquid formulations with particulates demand enhanced seal integrity and puncture resistance. Institutional feeding programs in aged care facilities in Australia specify soup pouches for portion control and reduced waste.
Ready-to-Eat Meals dominate current procurement; Soups are gaining share fastest as institutional nutrition programs convert from cans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American retort pouch distribution, handling polymer resin imports and finished laminate exports to Pacific Rim defense procurement networks.
United States
Military MRE programs and Walmart private-label ready-to-eal meals drive specification demand. FDA 21 CFR 177.1390 migration testing requirements filter supplier bases for domestic food-contact applications. The Midwest manufacturing corridor around Chicago concentrates converter operations serving retail and institutional buyers.
Germany
Hospital sterile processing departments and premium pet food manufacturers anchor high-barrier pouch procurement. EU Regulation 10/2011 additive approval lists force adhesive system reformulation for European market access. The Baden-Württemberg industrial cluster hosts technical workforce expertise in laminate delamination prevention.
Japan
Convenience store retail chains and aging-care institutional nutrition programs sustain format innovation. The Food Sanitation Act governs food-contact material composition with stringent migration limits. The Kanto region around Tokyo concentrates converter R&D facilities and nylon-layer technical specialization.
Australia
Defense ration modernization and aged-care soup pouch conversion drive dual-use demand. TGA medical device regulations overlap with food safety frameworks for hospital sterile supply applications. The Sydney-Melbourne corridor hosts distribution infrastructure for Asia-Pacific military procurement.
India
Urban middle-class expansion in modern trade channels accelerates ready-to-eat meal adoption. FSSAI food safety enforcement raises barrier specifications for imported laminate structures. The Maharashtra-Gujarat industrial belt concentrates domestic converter capacity expansion.
Retort Pouch Market Key Industry Players
Listed leaders compete with private specialists across certification-track positioning, with public companies leveraging capital access for multi-regional migration testing validation while private converters exploit niche flexibility in shorter production runs. The supplier base concentrates among three strategic archetypes: integrated resin-to-pouch conglomerates, specialized military-grade laminate fabricators, and regional print-form converters. Dominant competitive moves include backward integration into cast polypropylene film production and geographic expansion through Asia-Pacific certification acquisition.
Within the integrated conglomerate tier, Amcor plc and Berry Global exemplify scale-driven positioning across multi-layer coextrusion capabilities. Mondi Group occupies a position bridging European regulatory expertise with emerging market localization. Among specialized fabricators, Constantia Flexibles and ProAmpac represent the military-retail dual-certification archetype. Huhtamaki anchors the emerging-market regional converter model with localized operations. The competitive dynamic situates Sealed Air Corporation and Coveris within the premium barrier-film technology tier, while Sonoco Products Company exemplifies diversified packaging portfolio breadth.
| Leading Market Players |
|---|
| Berry Global |
| Sonoco Products Company |
| Amcor plc |
| Constantia Flexibles |
| ProAmpac |
| Mondi Group |
| Huhtamaki |
| Coveris |
| Sealed Air Corporation |
| Others |
Cost & Logistics Intelligence
Converter scale economies around multi-layer coextrusion capacity shape both supply concentration and price floors, with FDA-validated migration testing capabilities creating tiered entry barriers that stratify pricing power across military-grade and retail-format producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates defense-procurement laminates from mass-market retail formats and commodity-grade regional supply. Price differentiation hinges on certification grade — FDA 21 CFR 177.1390 and EU 10/2011 dual validation commands substantial premiums — and volume scale, with annual procurement contracts above threshold volumes unlocking negotiated rate cards. Cost compression in standard-tier retail formats is intensifying because polypropylene barrier films displace aluminum foil in microwave-only applications. Food manufacturers running high-volume ready-to-eat meal lines exhibit the greatest price sensitivity, while hospital sterile processing departments prioritize barrier assurance over unit economics.
Supply Chain Analysis
China and South Korea anchor cast polypropylene film production for barrier-layer feedstock, while the United States and Germany concentrate converter operations with validated migration testing infrastructure. Raw material dependencies draw from aluminum foil rolling capacity in Japan and Taiwan, adhesive resin systems from European specialty chemical producers, and EVOH barrier resins from South Korean petrochemical complexes. Single-source vulnerability concentrates in aluminum foil supply for military-grade specifications, where defense procurement mandates restrict qualified supplier pools. Distribution runs through direct-to-retailer procurement contracts displacing traditional distributor intermediaries in North American and European ready-to-eat meal segments.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retort pouch market is entering a cyclical recovery phase as defense procurement normalization and retail channel inventory restocking converge, with military ration modernization programs providing the primary cyclical impetus.
For Market Incumbents: Compound barrier-film technical capabilities through backward integration into cast polypropylene production and parallel certification investment for EU 10/2011 additive compliance. Defense procurement standardization and retail chain consolidation threaten margin compression for non-integrated converters. Capacity addition in Asia-Pacific certification nodes secures emerging market access before FSSAI enforcement tightens import specifications. For New Entrants and Emerging Players: Lead with digital printing integration for regional flavor versioning and batch-level traceability, targeting private-label programs at mid-tier retail chains seeking vendor-managed inventory partnerships. India packaged food retail represents the most penetrable geography, with urban middle-class expansion and modern trade channel growth outpacing domestic converter capacity. A direct-to-retailer go-to-market angle bypasses entrenched distributor relationships that incumbents control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized military-grade laminate fabricators with multi-year defense procurement contracts and validated sterilization assurance protocols. Long-term viability over the projection horizon favors converters with dual-certification capabilities spanning FDA and EU regulatory frameworks. Acquisition targets should display established migration testing infrastructure and adhesive formulation expertise concentrated in aging technical workforces. The signal to watch is EU packaging waste directive enforcement accelerating mono-material recyclable format development.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cast Polypropylene Film | Berry Global's captive supply of barrier-layer feedstock insulates margin pressure from resin price volatility. |
| Dual-Certification Acquisition for FDA and EU Compliance | Converters with parallel 21 CFR 177.1390 and 10/2011 validation capture defense and pharmaceutical premium tiers. |
| Digital Printing Integration for Regional Versioning | Huhtamaki's localized printing operations enable batch-level traceability without plate changeover costs in emerging markets. |
| Pharmaceutical Sterile Device Format Development | Hospital systems in Germany and the United States are shifting surgical instrument kits from rigid containers to retort-sterilized flexible pouches. |
| Mono-Material Recyclable Format R&D | EU packaging waste directives threaten multi-material laminate acceptance, forcing EVOH-based microwave-transparent development. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with converter operations directors, food manufacturer procurement leads, defense agency packaging engineers, and pharmaceutical sterile processing managers; and secondary validation through FDA 21 CFR filings, EU 10/2011 amendment documentation, FSSAI regulatory circulars, and customs trade data for polymer resin imports. Bottom-up triangulation across product type, material, and end-user segmentation dimensions reconciled with top-down macroeconomic drivers.
Across the analysis window, the forecasting framework modeled volume and value outputs through treatment line differentiation between military-grade and retail-format specifications, material substitution dynamics between aluminum foil and polypropylene barrier films, and regional regulatory cluster divergence. CAGRs were derived from segment-level growth rate blending anchored to defense procurement cycles and retail channel penetration trajectories. Industry-specific forecast inputs incorporated migration testing certification timelines and laminate delamination risk factors.
The analysis sits within stated boundaries; outcomes outside sustained defense budget authorization and EU packaging waste directive enforcement trajectories would require recalibration. Forecasts reflect assumptions around aluminum price volatility, adhesive system reformulation costs, and extended producer responsibility law adoption rates. Recalibration cycles align with material shifts in defense procurement specification updates and regulatory amendment cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Aluminium Bags and Pouches Market
Pouch
Twist Wrap Packaging Market
Pouch
Portion Control Packs Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Slider Zipper Pouch Market
Pouch
Liquid Pouch Market
Pouch
PCR Pouches Market
Pouch
Telemetry Pouch Market
Pouch
Four Side Flat Pouch Market
Pouch
OPP Pouches Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Dual-Chamber Pouches Market
Pouch
Europe Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market