
 Slider Zipper Pouch Market | 2026-2036
Slider Zipper Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Slider Zipper Pouch Market Outlook
Subscription-based packaging design services is expanding the value proposition beyond unit sales toward ongoing consumer engagement programs. Sealed Air Corporation leverages digital printing integration to sustain brand customization contracts with multinational food brands. Mondi Group anchors European supply through integrated kraft paper and plastic film operations. Proampac differentiates via specialty barrier coatings for extended shelf-life applications.
Slider zipper pouches are flexible laminated containers incorporating a mechanical closure track that permits repeated opening and sealing, typically constructed from multilayer coextruded polyethylene or oriented nylon with aluminum oxide barrier deposition. Their primary commercial purpose centers on preserving product freshness while enabling portion-controlled dispensing for dry goods, frozen foods, and pharmaceutical tablets. Plastic material types dominate unit volume due to cost scalability, though Mylar constructions command premium positioning in freeze-dried and oxygen-sensitive segments where barrier performance determines shelf stability. The Food Industry end-user channel generates the densest margin pools, while Healthcare applications represent the fastest-growing demand vector driven by unit-dose medication compliance packaging.
FDA food-contact substance notifications govern resin selection and migration limits for domestic U.S. distribution, while EU REACH and F-Gas Regulation constrain fluorinated barrier chemistries and mandate recyclability disclosures. China's SAMR enforces GB standards for composite packaging safety that foreign suppliers must navigate for market access. Stakeholders should monitor evolving extended producer responsibility frameworks and substrate substitution timelines to align capital allocation with compliance-driven material transitions.
Market Dynamics
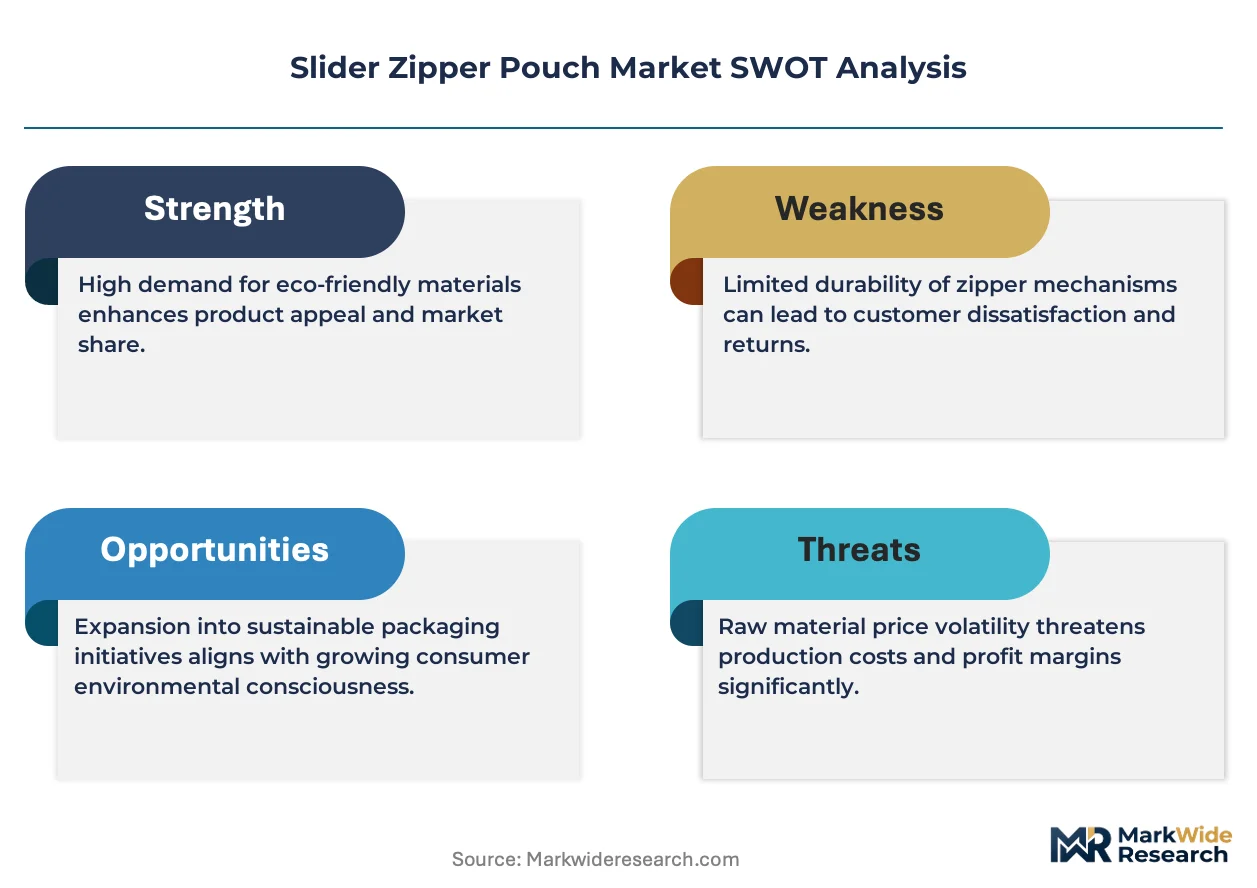
EU packaging waste directives and FDA food-contact substance notifications are forcing substrate substitutions across the laminated film supply base, compressing lead times for compliant resin qualification while reshaping procurement priorities toward mono-material constructions.
Growth Catalysts
- Frozen food format expansion:Resealable pouches displace rigid trays in private-label frozen vegetable and prepared meal lines as retailers prioritize shelf-space efficiency and consumer portion control.
- EU F-Gas Regulation phase-down:The constraint on fluorinated barrier chemistries accelerates adoption of aluminum oxide deposition and bio-based barrier coatings for oxygen-sensitive applications.
- China SAMR GB standard enforcement:Composite packaging safety mandates for imported goods drive domestic converter investment in certified multilayer coextrusion capacity.
Market Restraints
- Resin cost volatility:Ethylene and propylene feedstock price swings compress converter margins on polyethylene-dominant pouch constructions during contract renegotiation cycles.
- Barrier coating supply concentration:Aluminum oxide deposition equipment and vapor deposition chemistries concentrate among German and Japanese specialty chemical suppliers, creating single-source vulnerabilities.
- Mechanical zipper IP thickets:Patent estates surrounding slider track geometries and pull-tab designs constrain new entrants from launching differentiated closure mechanisms without licensing exposure.
Strategic Opportunities
- Indian pharmaceutical compliance packaging:CDSCO unit-dose regulations and expanding domestic generic manufacturing create demand for child-resistant slider pouches with desiccant integration.
- Digital printing convergence with short-run flexibility:Electrophotographic and inkjet web printing enables brand owners to regionalize SKUs without plate costs, collapsing minimum order quantities.
- Extended producer responsibility frameworks:Deposit-return schemes and recyclability mandates in Germany and France reward mono-material polyethylene pouch designs with reduced eco-modulation fees.
Industry Challenges
- Migration testing timeline compression:FDA food-contact substance notification reviews and EU plastic food contact material authorizations extend new product qualification cycles beyond 18 months.
- Legacy form-fill-seal retrofit requirements:Existing horizontal packaging lines require mechanical modifications to handle slider zipper film webs, demanding capital allocation from contract packers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slider Zipper Pouch Market |
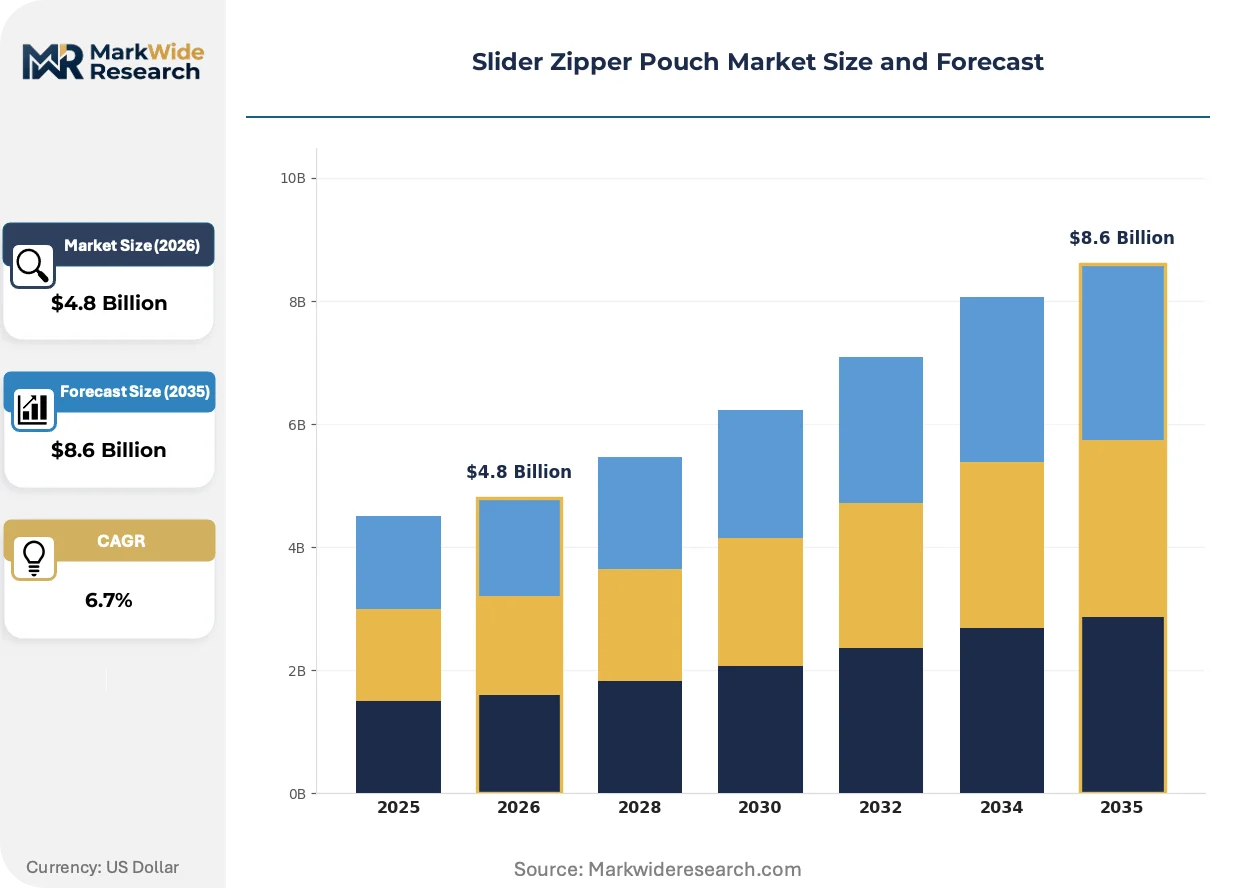
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Mylar, Polyethylene, Nylon Closure Mechanism: Slider, Zipper, Seal, Adhesive End User: Food Industry, Retail, Healthcare, Personal Care Packaging Size: Small, Medium, Large, Extra Large |
| Companies Covered | Sealed Air Corporation, Printpack, Amcor Limited, Winpak Ltd., Proampac, Berry Global Group, Mondi Group, American Packaging Corporation, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slider Zipper Pouch Market Strategic Shifts
Active developments across barrier deposition, digital production workflows, and retail-format specifications are compressing product development cycles while fragmenting the traditional volume-contract model.
Mono-material polyethylene pouch constructions incorporating ethylene-vinyl alcohol copolymer tie layers are unifying barrier performance with recyclability credentials. Major frozen food brands in Germany and the United States specify these constructions for private-label lines. The technology is unifying previously separate supply chains for performance and sustainability procurement.
REACH restrictions on per- and polyfluoroalkyl substances in food contact materials are eliminating legacy fluoropolymer barrier coatings from European supply chains. Converters pivot toward silicon oxide and aluminum oxide physical vapor deposition alternatives. Frozen seafood and freeze-dried coffee segments absorb the steepest cost premiums during this transition.
Brand owners now specify regional SKU fragmentation with lot-level traceability codes as standard requirements. Digital printing enables 500-unit production runs with variable graphics and regulatory text. Food brands in the United States and China deploy this capability for seasonal limited editions and provincial label mandates without inventory risk.
Slider Zipper Pouch Market Segmentation
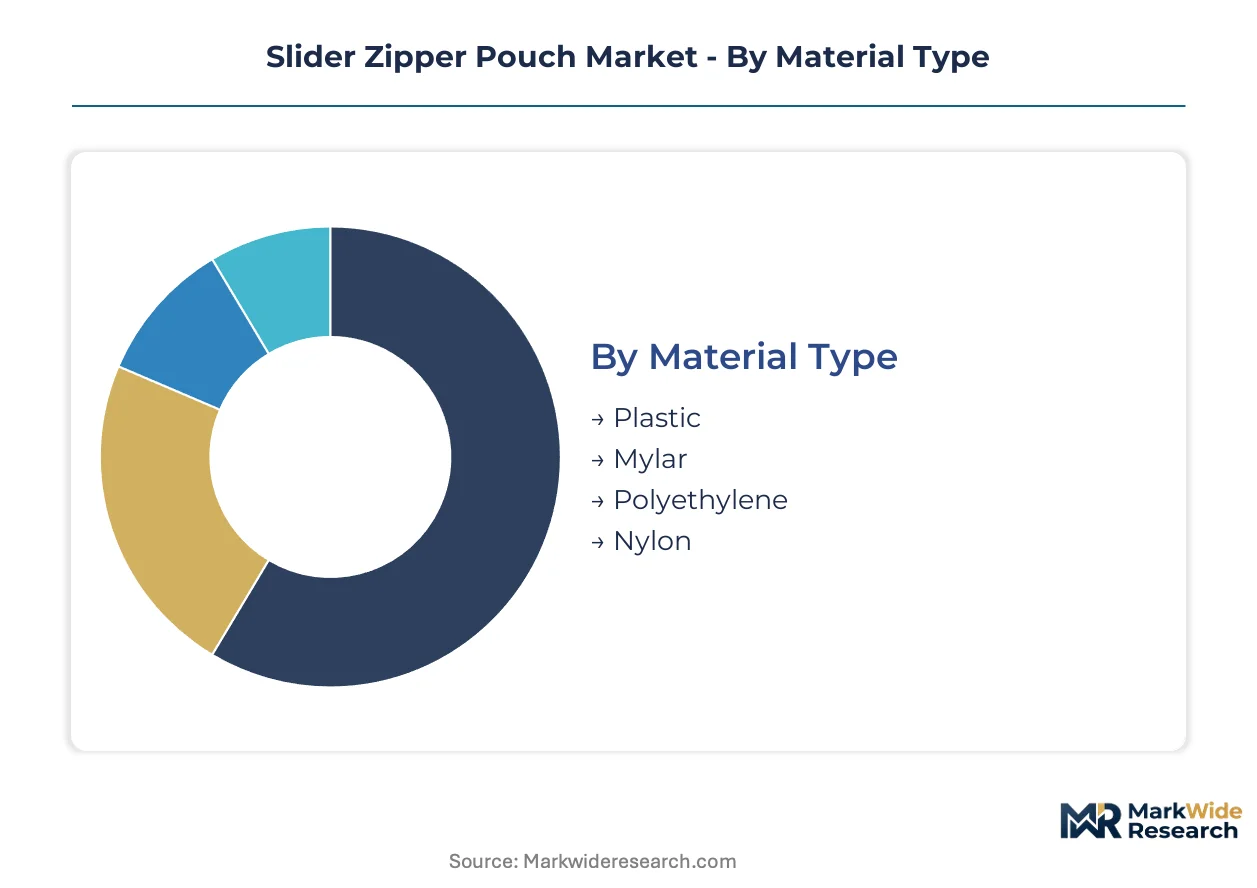
Material composition and closure engineering determine barrier performance, regulatory compliance pathways, and recyclability credentials across slider zipper pouch procurement. Specification choices cascade through converter capacity planning, brand owner sustainability commitments, and end-use shelf-life requirements.
Material Type:
Multilayer coextrusion technology and barrier deposition methods define the performance-cost tradeoffs available to specification engineers.
- Plastic:Polyethylene-dominant laminates with ethylene-vinyl alcohol copolymer tie layers balance oxygen transmission resistance against mechanical flexibility for frozen food applications. Demand concentrates in United States private-label retail lines where mono-material constructions qualify for reduced extended producer responsibility fees in California and New York deposit-return schemes.
- Mylar:Biaxially oriented polyethylene terephthalate films with aluminum metallization or aluminum oxide vapor deposition deliver sub-0.1 cc/m²/day oxygen transmission rates. Freeze-dried coffee and pharmaceutical desiccant pouches in Germany absorb premium positioning where barrier performance determines shelf stability certification.
- Polyethylene:Linear low-density and high-density polyethylene blends dominate unit volume through cost scalability on blown film extrusion lines. Snack food brands in China specify these constructions for high-speed form-fill-seal compatibility.
- Nylon:Oriented polyamide layers provide puncture resistance and tensile strength for bone-in meat and seafood packaging. Japanese frozen food processors favor nylon-polyethylene laminates for vacuum compatibility.
Mature deployment sits with Plastic. Newer deployment is concentrated in Mylar as fluorinated barrier chemistries face regulatory phase-downs.
Closure Mechanism:
Mechanical engagement geometry and actuation force requirements differentiate user experience profiles across consumer demographics and industrial handling conditions.
- Slider:Polypropylene track-and-carriage systems with audible engagement feedback enable single-handed operation for accessibility compliance. Senior nutrition and pediatric snack segments in the United States specify slider mechanisms for arthritis-friendly and child-independent access.
- Zipper:Interlocking male-female rib profiles without mechanical assist reduce unit cost and web thickness for lightweight dry goods. Cereal and baking ingredient brands in Germany optimize zipper specifications for vertical bagging line speeds.
- Seal:Heat-sealed peelable or permanent closures serve single-use pharmaceutical and diagnostic kit applications where resealability is non-critical. Unit-dose medication compliance packaging in India specifies child-resistant seal configurations per CDSCO guidance.
- Adhesive:Pressure-sensitive resealable tapes provide tamper-evidence and initial opening ceremony for premium confectionery. Seasonal gift packaging in France deploys adhesive closures for decorative tear-strip aesthetics.
Slider specifications command margin premiums in accessibility-regulated segments. Zipper configurations dominate volume throughput in commodity frozen vegetable lines.
End User:
Channel-specific regulatory burdens and shelf-life performance thresholds shape material and barrier specification roadmaps.
- Food Industry:FDA food-contact substance notifications and EU plastic food contact material authorizations govern resin selection for frozen prepared meals, snacks, and bakery goods. Private-label penetration in United States retail chains drives specification standardization toward mono-material polyethylene.
- Healthcare:Unit-dose medication compliance packaging with child-resistant and senior-friendly dual accessibility represents the steepest expansion trajectory. CDSCO regulations in India and FDA 21 CFR Part 4 combination product rules constrain closure mechanism validation protocols.
- Retail:Private-label house brands and seasonal promotional formats prioritize digital printing compatibility for short-run SKU fragmentation. Regional supermarket chains in Germany specify retail-format pouches with front-of-pack sustainability messaging space.
- Personal Care:Moisture-sensitive wipes and single-use cosmetic sachets require vapor transmission barriers and fragrance retention. Korean beauty brands specify personal care pouch constructions with aluminum oxide deposition for hyaluronic acid stability.
Food Industry procurement concentrates legacy volume contracts. Healthcare applications are climbing the fastest on regulatory compliance packaging mandates.
Packaging Size:
Fill volume and dimensional constraints determine web width requirements, zipper track length specifications, and case packing efficiencies.
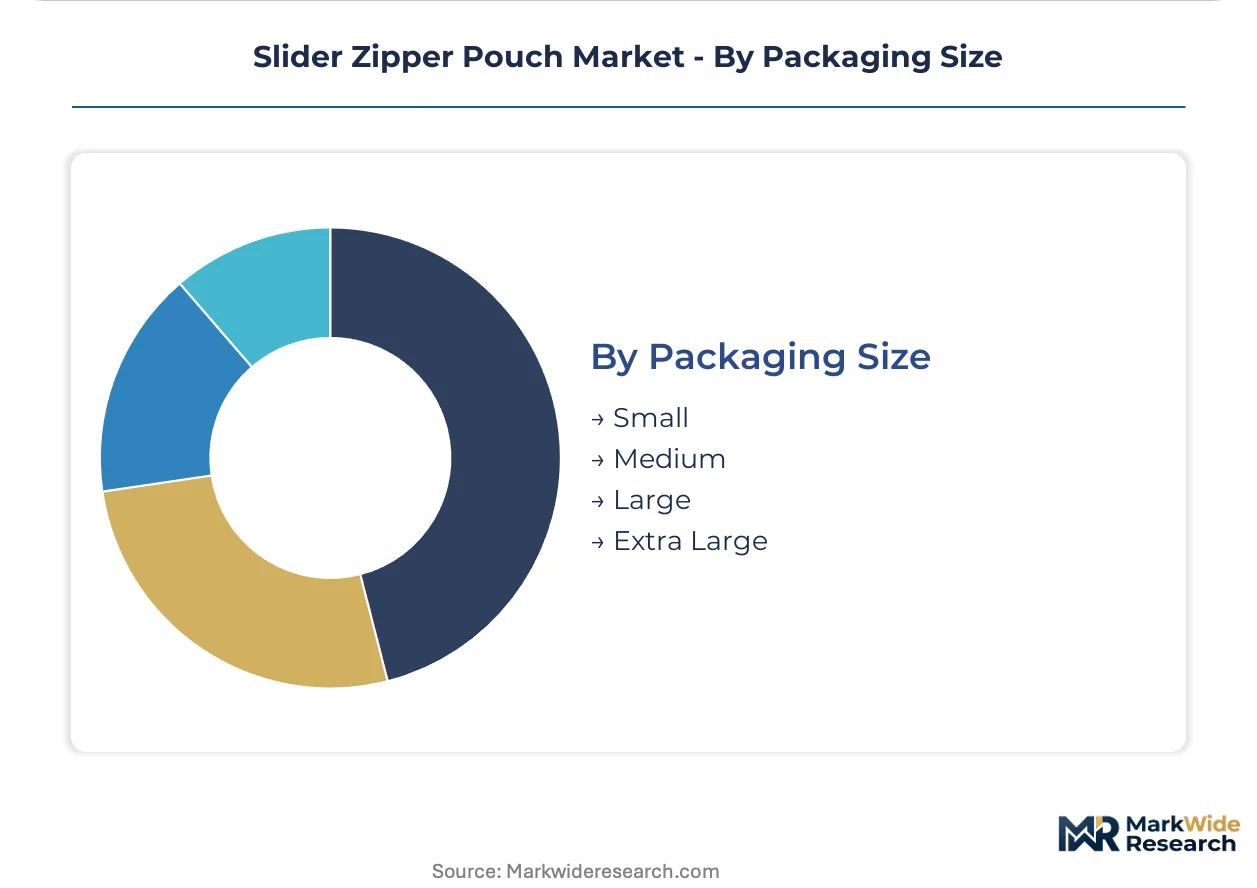
- Small:Sub-100 gram capacity for single-serve condiments, pharmaceutical unit doses, and sample sachets. United States quick-service restaurant condiment packs specify small-format sliders for portion control.
- Medium:100-500 gram range for standard snack, frozen vegetable, and personal care wipe counts. German frozen food brands optimize medium-format dimensions for European retail shelf modular spacing.
- Large:500 gram to 2 kilogram capacity for family-size cereal, pet food, and bulk ingredient storage. Chinese e-commerce fulfillment channels favor large-format pouches for reduced shipping cube versus rigid containers.
- Extra Large:Above 2 kilogram industrial and foodservice quantities with reinforced handle integration and double-track zipper security. United States warehouse club retail specifies extra-large formats for institutional baking and foodservice frozen vegetable procurement.
Medium formats anchor current converter capacity allocation. Extra Large specifications are gaining share fastest in foodservice and e-commerce fulfillment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in China and Germany while consumption concentrates in the United States and India, creating transoceanic supply flows that expose margins to resin cost volatility and tariff exposure.
United States
Frozen food private-label expansion drives medium-format polyethylene pouch demand as retailers displace rigid trays. FDA food-contact substance notifications govern resin migration limits for domestic distribution. Chicago-area converter networks supply quick-service restaurant condiment packs with small-format slider specifications.
Germany
Extended producer responsibility frameworks reward mono-material constructions with reduced eco-modulation fees. EU F-Gas Regulation phase-downs eliminate fluorinated barrier chemistries from European supply chains. Bavarian frozen food processors specify aluminum oxide deposition for oxygen-sensitive coffee and seafood segments.
China
E-commerce fulfillment channels absorb large-format pouches for reduced shipping cube versus rigid containers. SAMR enforces GB standards for composite packaging safety that foreign suppliers must navigate for market access. Yangtze River Delta converter clusters invest in certified multilayer coextrusion capacity for export compliance.
India
CDSCO unit-dose regulations and expanding domestic generic manufacturing create demand for child-resistant slider pouches. Pharmaceutical compliance packaging represents the fastest-growing demand vector within the regional footprint. Mumbai-Pune industrial corridors anchor healthcare-format pouch conversion for domestic and export markets.
Japan
Oriented polyamide layers for puncture resistance dominate frozen seafood and bone-in meat applications. METI circular economy roadmaps pressure substrate substitution toward recyclable mono-material constructions. Chubu region packaging machinery manufacturers supply vacuum-compatible form-fill-seal lines to domestic processors.
Slider Zipper Pouch Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the laminated film value chain. The vendor base spans integrated resin-to-pouch conglomerates, specialized barrier coating specialists, and regional converters with digital printing capabilities. Three archetypes dominate: multinational material science platforms with captive resin supply, mid-tier converters with vertical integration into printing and slitting, and niche specialists in pharmaceutical-grade validation protocols. Capacity expansion and strategic partnerships constitute the dominant competitive moves as participants secure aluminum oxide deposition equipment and digital press installations.
Within the multinational platform tier, Sealed Air Corporation and Amcor Limited represent integrated material science operations with global converter networks. Mondi Group anchors European supply through kraft paper and plastic film integration. Berry Global Group occupies a position across rigid and flexible formats with scale-driven polyethylene processing capabilities.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Printpack |
| Amcor Limited |
| Winpak Ltd. |
| Proampac |
| Berry Global Group |
| Mondi Group |
| American Packaging Corporation |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Ethylene price index volatility cascades through polyethylene converter margins into three-tier pricing stratification across premium barrier-coated, standard mono-material, and economy-grade zipper pouch tiers serving frozen food and pharmaceutical channels.
Pricing Analysis
Margin tightening in standard-grade polyethylene pouches reflects ethylene feedstock cost swings and contract renegotiation cycles with United States private-label retailers. Pricing stratifies across premium, standard, and economy tiers where Mylar barrier constructions with aluminum oxide deposition command brand premiums for oxygen-sensitive freeze-dried applications, while commodity snack food specifications compete on volume scale. Cost-down pressure on economy-grade zipper configurations accelerates because Chinese e-commerce fulfillment channels prioritize shipping cube efficiency over barrier performance. Quick-service restaurant condiment pack buyers exhibit highest price sensitivity due to annual procurement tenders, whereas German pharmaceutical compliance packaging demonstrates lowest sensitivity given CDSCO and FDA validation requirements.
Supply Chain Analysis
FDA food-contact substance notification and EU REACH compliance certification gates converter qualification timelines exceeding eighteen months, concentrating approved capacity among established multilayer coextrusion operators. Supply concentrates in China, Germany, and the United States where Yangtze River Delta and Bavarian converter clusters anchor regional output. Raw material dependencies center on ethylene-vinyl alcohol copolymer tie layers, aluminum oxide deposition equipment from German and Japanese specialty chemical suppliers, and oriented polyamide films. Single-source vulnerability in vapor deposition chemistries creates supply chain risk. Distribution runs through contract packer networks and retail private-label procurement channels with direct converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA food-contact substance notification requirements create an eighteen-month qualification moat protecting validated incumbents from commodity converter entry.
For Market Incumbents: Deploy backward integration into aluminum oxide deposition equipment to capture barrier coating margins currently concentrated among German and Japanese specialty suppliers. Sealed Air Corporation and Mondi Group should expand certified multilayer coextrusion capacity in China ahead of SAMR GB standard enforcement tightening. Patent licensing around slider track geometries offers defensive positioning against mechanical zipper IP thickets threatening new entrant disruption. For New Entrants and Emerging Players: CDSCO unit-dose regulations in India open a window for child-resistant slider pouch specialization with desiccant integration capabilities. Target Mumbai-Pune pharmaceutical corridors where domestic generic manufacturing expansion outpaces local converter capacity. Digital printing convergence enables short-run SKU fragmentation without plate costs, collapsing minimum order quantities for regional supermarket chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with SAMR certification and digital press installations in China and India. Long-term viability rests on mono-material polyethylene positioning ahead of extended producer responsibility framework expansion. The signal to watch is EU F-Gas Regulation phase-down acceleration forcing fluorinated barrier chemistry substitution toward aluminum oxide alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating | Captures margins from German and Japanese specialty chemical suppliers while securing deposition capacity. |
| Digital Printing Platform Installation | Enables 500-unit production runs with variable graphics for seasonal limited editions without inventory risk. |
| SAMR GB Standard Certification Investment | Unlocks Chinese domestic market access as composite packaging safety enforcement tightens on imports. |
| Child-Resistant Closure Validation | Addresses CDSCO unit-dose regulations and FDA 21 CFR Part 4 combination product rules in pharmaceutical channels. |
| Mono-Material Polyethylene Capacity Expansion | Qualifies for reduced eco-modulation fees under German and French extended producer responsibility frameworks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with converter operations managers, brand owner packaging engineers, retail category buyers, pharmaceutical regulatory affairs leads, and barrier coating equipment specialists. FDA food-contact substance notifications, EU REACH registrations, SAMR GB standard documentation, and CDSCO guidance circulars provided regulatory validation. Bottom-up capacity assessments across Yangtze River Delta and Bavarian converter clusters were triangulated against top-down demand estimates from frozen food and pharmaceutical end-use channels.
Segment-level modeling captured material type, closure mechanism, end user, and packaging size dimensions across the projection horizon, with additional granularity on barrier deposition method and regional regulatory cluster. CAGRs were derived from volume-weighted trajectory analysis incorporating ethylene price elasticity assumptions and private-label penetration rates. Forecast inputs included e-commerce fulfillment channel growth, extended producer responsibility fee schedules, and digital printing adoption curves.
The model assumes a particular technology adoption path; alternative pathways for aluminum oxide physical vapor deposition versus bio-based barrier coatings would alter the outlook. Forecasts reflect assumptions on SAMR enforcement timelines, EU F-Gas Regulation phase-down acceleration, and resin cost normalization patterns. A model refresh is warranted upon material change in FDA food-contact substance notification review durations or extended producer responsibility framework expansion beyond Germany and France.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Colombia Pouch Packaging Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Utility Pouches Market
Pouch
Japan Pouch Packaging Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Four Side Flat Pouch Market
Pouch
Doy Pouch Packaging Market
Pouch
China Pouch Packaging Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Telemetry Pouch Market
Pouch
Child Resistant Pouches Market
Pouch
Wrap-Around Packers Market
Pouch
Heat Sealed Lamination Pouch Market