
 Europe Pouch Packaging Market | 2026-2036
Europe Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pouch Packaging Market Insights
Food industry demand is pivoting toward shelf-stable and convenience formats, drawing capital into high-performance flexible packaging lines. Amcor Group GmbH leverages its European extrusion network to supply multilayer barrier films for retort applications. Mondi Group anchors its position through integrated kraft paper and plastic film operations serving fresh and frozen protein segments. Constantia Flexibles Group GmbH specializes in pharmaceutical-grade pouch compliance, competing on child-resistant and senior-friendly closure certifications.
Europe pouch packaging denotes flexible containers formed from single or laminated webs, typically 50-200 microns thick, sealed on three or four sides with optional reclosure features, designed to replace rigid cans, bottles, and boxes across liquid, solid, and powdered contents. Stand-up pouches with spout closures command premium positioning in beverages and condiments where dispensing precision and shelf presence determine retail placement. Plastic composites still dominate tonnage, though paper-based laminates are capturing share in dry grocery and personal care where moisture sensitivity permits fiber-dominant constructions.
The EU Green Deal and REACH frameworks mandate recyclability and restricted substance thresholds, forcing converters to validate mono-material or certified-compostable structures through ECHA-compliant testing protocols. Germany's national packaging law, France's extended producer responsibility decrees, and Italy's plastic tax implementation collectively reshape formulation roadmaps and supplier qualification criteria. Stakeholders must monitor evolving EFSA food-contact approvals for novel barrier coatings and decide between regional customization versus pan-European platform standardization.
Market Dynamics
Mono-material pouch construction is displacing multilayer laminates across European food and personal care packaging as Extended Producer Responsibility schemes and the EU Green Deal impose strict recyclability mandates on converters and brand owners.
Growth Catalysts
- Retort-ready mono-PE structures:High-temperature sterilization compatibility now extends to single-substrate films, opening replacement opportunities for aluminum-foil laminates in ready meals.
- France's extended producer responsibility decrees:Packaging fees scale with recyclability scores, accelerating converter investment in compatible barrier coatings and compatible sealing layers.
- Pharmaceutical compliance specialization:Child-resistant and senior-friendly pouch certifications command premium positioning as generics manufacturers outsource packaging to qualified European converters.
Market Restraints
- Ethylene-vinyl alcohol supply concentration:High-barrier resin availability depends on a limited supplier base in Western Europe, creating input cost volatility for oxygen-sensitive applications.
- Mechanical recycling infrastructure gaps:Sorting and reprocessing capacity for flexible packaging lulls behind substrate innovation, depressing post-consumer resin prices and circular economics.
- Aluminum foil substitution limits:Ultra-high barrier requirements in infant nutrition and medical nutrition retain metallized films despite sustainability pressures, fragmenting R&D priorities.
Strategic Opportunities
- Poland and Romania food retail modernization:Discounter expansion and private-label growth in Central and Eastern Europe create first-mover advantages for pouch format conversion from rigid alternatives.
- Paper-fiber barrier hybridization:Dry grocery segments in Italy and Spain permit fiber-dominant laminates where moisture sensitivity is manageable, capturing brand sustainability commitments.
- Digital printing integration with short-run flexibility:SKU proliferation in seasonal and limited-edition products rewards converters with in-house inkjet or toner capabilities.
Industry Challenges
- Mono-material validation timelines:EFSA food-contact approvals for novel barrier coatings extend 18-24 months, compressing product launch windows against competitor announcements.
- Legacy thermoforming asset stranding:Brand owner capital tied to rigid tray lines slows pouch adoption despite total cost advantages, requiring converter financing partnerships.
- Cross-border regulatory fragmentation:Germany's national packaging law, Italy's plastic tax, and France's repairability index create compliance complexity for pan-European platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pouch Packaging Market |
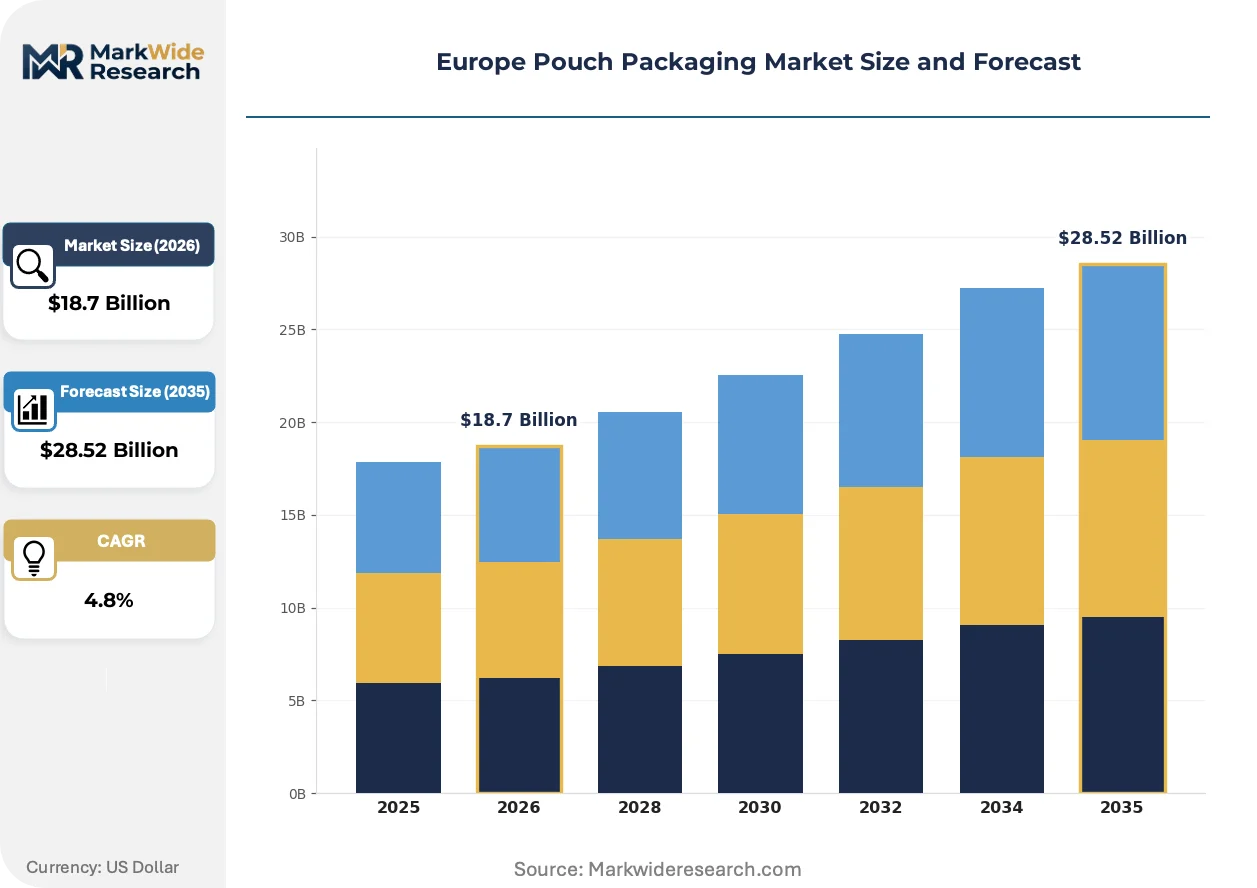
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Pillow Pouches, Flat Pouches, Retort Pouches Material: Plastic, Paper, Aluminum, Composites End User: Food Industry, Beverage Industry, Personal Care, Pharmaceuticals Closure Type: Zipper, Spout, Heat Seal, Tear Notch |
| Companies Covered | Amcor Group GmbH, Mondi Group, Constantia Flexibles Group GmbH, Bischof+Klein SE & Co. KG, AluFlexpack Group, ProAmpac, Huhtamaki Oyj, Coveris Group, Sealed Air, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pouch Packaging Market Trends and Innovations
Digitalization of packaging workflows and substrate chemistry breakthroughs are compressing development cycles while regulatory deadlines force simultaneous compliance across multiple technical pathways.
Water-based and solventless adhesive lamination is consolidating position in European converter operations as volatile organic compound restrictions tighten under REACH and national air quality directives. Mid-tier food manufacturers in Germany and the Netherlands are accelerating adoption to avoid permitting bottlenecks and emissions trading costs. This consolidation is compressing the viable supplier base for conventional solvent-based systems to specialty pharmaceutical and high-performance industrial segments only.
The EU F-Gas Regulation and accompanying delegated acts are restricting hydrofluorocarbon use in plasma-enhanced barrier deposition processes, forcing equipment retrofits or alternative vacuum technologies. Converter capital allocation now prioritizes physical vapor deposition and atomic layer deposition systems that eliminate fluorinated precursors. Fresh protein and ready-meal segments in France and Belgium face the steepest compliance curves given their reliance on ultra-high barrier specifications.
Brand owner procurement teams are consolidating supplier relationships around full-format capabilities rather than sourcing pouches, labels, and cartons separately. This behavior concentrates volume with integrated flexible packaging converters capable of single-SKU management across multiple substrate types. The shift is most visible in German and Swiss personal care and home care verticals where marketing-led SKU complexity outpaces operational bandwidth.
Europe Pouch Packaging Market Segmentation
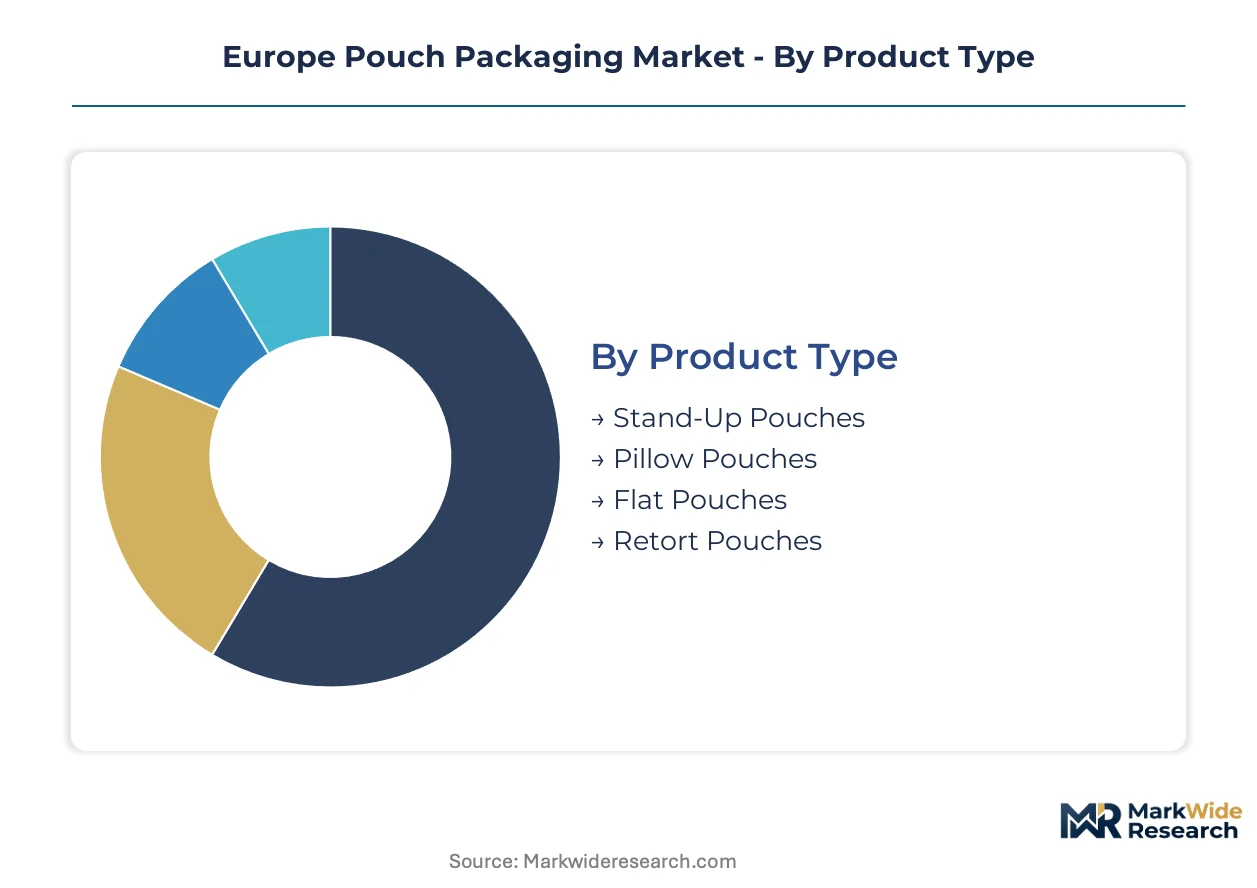
Pouch format selection in Europe hinges on shelf presence requirements, sterilization needs, and recyclability mandates under the EU Green Deal. Material and closure configurations further differentiate segments based on barrier performance and consumer convenience expectations.
Product Type:
Buyers differentiate primarily by vertical shelf stability and dispensing functionality rather than unit cost.
- Stand-Up Pouches:Gusseted bottom construction enables vertical retail display and maximizes shelf-facing efficiency. German and French condiment brands prioritize this format for premium positioning where reclosure and pour control determine repeat purchase rates.
- Retort Pouches:Multilayer or mono-material structures withstand 121°C sterilization cycles for ambient-stable ready meals. Italy and Spain show accelerating demand as private-label retailers convert from metal cans to reduce logistics cube and heating energy.
- Pillow Pouches:Three-side-sealed format dominates high-speed horizontal form-fill-seal lines for dry grocery and frozen protein.
- Flat Pouches:Minimal material usage suits single-serve portions and sample packs in cosmetics and pharmaceuticals.
Stand-Up Pouches lead volumes today; Retort Pouches are gaining share fastest.
Material:
Specification choices revolve around circularity compliance and EPR fee structures rather than raw material cost alone.
- Plastic:Mono-PE and mono-PP substrates dominate tonnage as converters validate recyclable barrier coatings through EFSA protocols. France's extended producer responsibility decrees penalize non-recyclable multilayer constructions, accelerating mono-material adoption in fresh protein and dairy applications.
- Composites:Paper-plastic and paper-aluminum laminates balance fiber-based sustainability claims with functional barrier needs. Italian dry pasta and Dutch coffee brands favor these structures where moisture sensitivity permits partial material substitution.
- Paper:Uncoated or barrier-coated fiber constructions capture personal care and dry grocery segments with minimal oxygen sensitivity.
- Aluminum:Metallized films and foil laminates retain niche positioning in infant nutrition and medical nutrition where ultra-high barrier specifications override recyclability pressures.
Plastic substrates command the largest installed base; Composites are climbing the fastest as brand sustainability commitments harden.
End User:
Volume concentration and margin structure vary sharply across buyer verticals.
- Food Industry:Ready-to-eat meals, fresh protein, and frozen vegetables drive pouch conversion from rigid formats. German discounter consolidation favors flexible packaging for logistics efficiency and shelf-space optimization.
- Pharmaceuticals:Child-resistant and senior-friendly pouch certifications command premium pricing as generics manufacturers outsource compliance-critical packaging to qualified European converters.
- Beverage Industry:Spouted stand-up pouches gain traction in smoothies and concentrates where portion control and refrigeration compatibility matter.
- Personal Care:Single-serve samples and refill pouches respond to sustainability messaging in French and Swiss cosmetics markets.
Food Industry leads volumes today; Pharmaceuticals shows the steepest expansion trajectory.
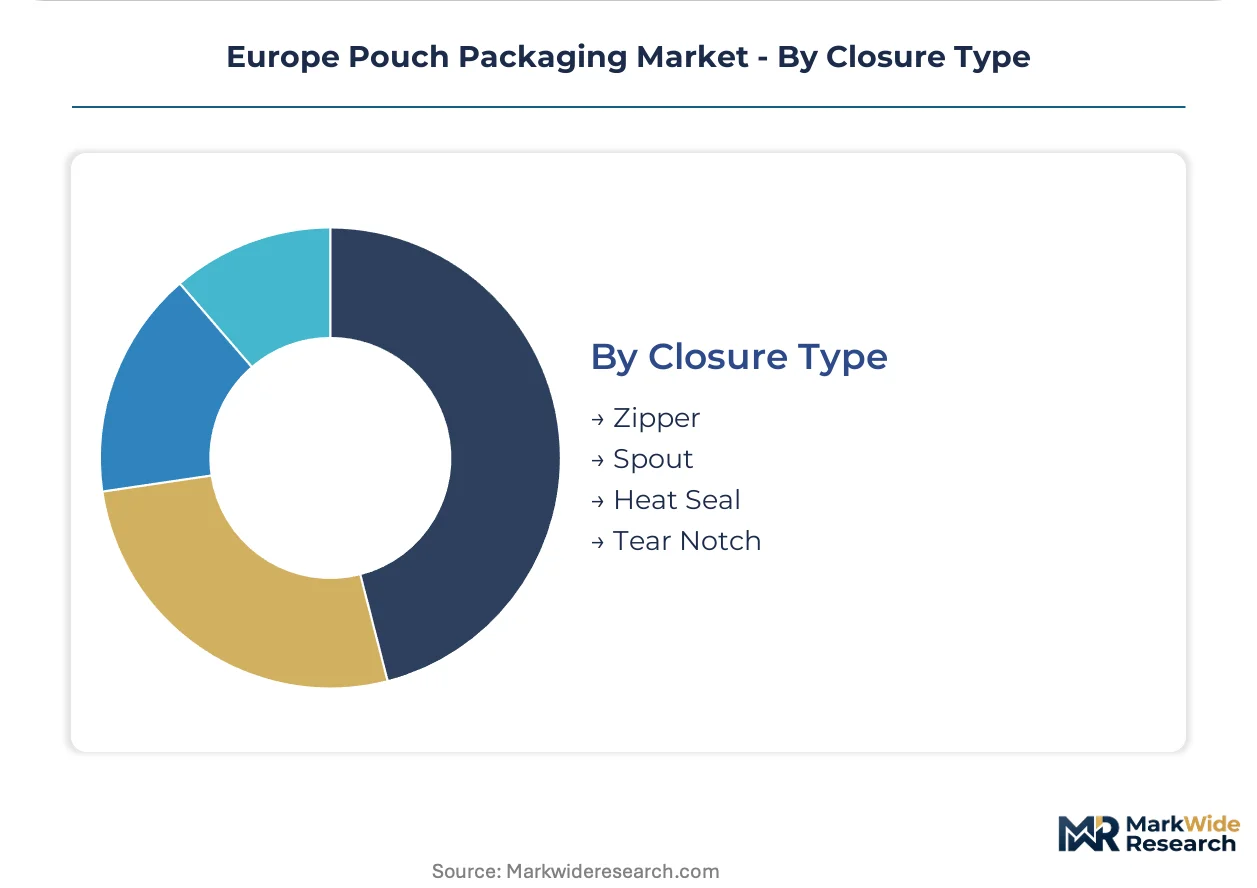
Closure Type:
Reclosure mechanism selection reflects usage occasion frequency and dispensing precision requirements.
- Spout:Integrated pour control enables precise dispensing for beverages, condiments, and liquid detergents. Belgian and Dutch converters invest in spout insertion equipment to capture premium positioning in home care and foodservice segments.
- Zipper:Press-to-close systems dominate dry grocery and frozen applications where multiple-use occasions extend product freshness.
- Heat Seal:Permanent closure minimizes material cost for single-serve portions and non-reclosable industrial formats.
- Tear Notch:Laser-scored opening features support accessibility compliance in pharmaceutical and senior-targeted food products.
Heat Seal closures retain the broadest application base; Spout configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across national Extended Producer Responsibility fee structures is redirecting pouch production investment toward jurisdictions with lower compliance costs and faster mono-material validation pathways. France's recyclability-scaled fees and Italy's plastic tax create divergent cost-of-compliance landscapes that favor strategic facility placement.
Germany
Discounter consolidation and private-label expansion drive pouch conversion from rigid formats in fresh protein and ready meals. The national packaging law imposes strict recyclability verification requirements on converters supplying Aldi, Lidl, and REWE networks. The Düsseldorf-Cologne industrial corridor hosts major extrusion and lamination operations serving pan-European food retail distribution.
France
Extended producer responsibility decrees penalize non-recyclable multilayer constructions through fee scaling, accelerating converter investment in mono-PE barrier coatings. EFSA food-contact approval timelines for novel coatings compress product launch windows. The Lyon-Grenoble cluster concentrates pharmaceutical-grade pouch specialists competing on child-resistant certification compliance.
Italy
The plastic tax implementation and brand sustainability commitments favor paper-fiber barrier hybridization in dry pasta, coffee, and personal care segments. Moisture-sensitive applications retain plastic dominance where fiber substitution risks shelf-life degradation. The Emilia-Romagna packaging belt anchors integrated converter operations serving Mediterranean export markets.
Poland
Food retail modernization and discounter expansion create first-mover advantages for pouch format conversion from metal cans and glass jars. Lower EPR compliance costs relative to Western Europe attract capacity investment from German and Austrian converters. The Warsaw-Łódź corridor emerges as a secondary hub for flexible packaging serving Central and Eastern European markets.
Netherlands
Solventless adhesive lamination adoption accelerates under REACH volatile organic compound restrictions and national air quality directives. Horizontal form-fill-seal line investments target high-speed dry grocery and frozen protein applications. The Rotterdam-Antwerp port complex facilitates resin import and film export logistics for converters supplying Benelux and German markets.
Europe Pouch Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters retrofit lines for mono-material production and install spout insertion equipment for premium beverage and home care segments. The vendor base exhibits moderate consolidation around integrated flexible packaging groups with full-format capabilities spanning pouches, labels, and secondary packaging. Three strategic archetypes define competitive positioning: multinational integrated converters with pan-European extrusion networks, mid-tier specialists in pharmaceutical compliance or regional food retail supply, and paper-based hybrid innovators capturing sustainability-driven brand procurement. Dominant competitive moves include backward integration into barrier coating development and geographic expansion into Central and Eastern European markets.
Within the integrated converter tier, Amcor Group GmbH and Mondi Group exemplify scale-driven positioning through captive extrusion networks and integrated kraft paper operations. Constantia Flexibles Group GmbH occupies a compliance-specialist position anchored in pharmaceutical-grade certification capabilities. These three entities represent divergent strategic bets on mono-material validation speed, fiber-based hybridization, and regulatory compliance depth respectively.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Mondi Group |
| Constantia Flexibles Group GmbH |
| Bischof+Klein SE & Co. KG |
| AluFlexpack Group |
| ProAmpac |
| Huhtamaki Oyj |
| Coveris Group |
| Sealed Air |
| Others |
Pricing and Supply Chain Analysis
Captive extrusion networks in Germany and Austria anchor supply positions for high-barrier mono-material films, simultaneously controlling input costs and commanding premium positioning against non-integrated converters facing EVOH resin volatility. This backward integration into barrier coating development locks in margin capture as France's EPR fee scaling penalizes multilayer competitors.
Pricing Analysis
Retailer markup layers dominate final pouch pricing, with German discounters extracting logistics efficiency gains that compress converter margins on commodity formats. Three-tier pricing structure across premium, standard, and economy levels separates spouted stand-up pouches for beverages from basic pillow pouches for dry grocery. Cost compression in standard tiers is intensifying because EVOH supply concentration limits substitution options for oxygen-sensitive applications. Private-label buyers at Aldi and Lidl networks exhibit highest price sensitivity, while pharmaceutical generics manufacturers accept premium positioning for child-resistant certification compliance.
Supply Chain Analysis
Mechanical recycling flows for post-consumer flexible packaging remain underdeveloped across France, Germany, and Italy, depressing circular economics and virgin resin price benchmarks. Raw material sourcing draws from Saudi ethylene crackers, Belgian EVOH polymerization, and Finnish kraft pulp integration. Single-source vulnerability concentrates in high-barrier resin supply where Western European EVOH capacity limits converter formulation flexibility. Distribution runs through pan-European food retail consolidation networks anchored by German discounter procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe pouch packaging rests on mono-material validation speed and EPR fee arbitrage, with converters capturing premium positioning by outrunning compliance curves in France and Italy.
For Market Incumbents: Cement barrier coating R&D partnerships with EFSA pre-submission pathways to compress 18-24 month approval timelines. Acquire spout insertion equipment capabilities in Poland and Romania before discounter consolidation locks in supplier relationships. Mono-material validation delays from emerging biopolymer entrants threaten first-mover premium capture. For New Entrants and Emerging Players: Enter via paper-fiber hybridization for Italian dry pasta and Spanish coffee segments where moisture sensitivity permits fiber-dominant constructions. Poland's food retail modernization offers the most penetrable geography given lower EPR compliance costs and rigid-to-flexible conversion demand. Lead with sustainability certification partnerships that satisfy French EPR recyclability scoring. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier pharmaceutical-grade pouch specialists because generics outsourcing trends concentrate compliance-critical volume with qualified European converters. Five-to-ten year viability hinges on EFSA approval pipeline depth and Central European capacity positioning. Monitor EVOH supply expansion announcements as inflection indicator for input cost volatility relief.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Coating Validation | EFSA approval pathways determine competitive positioning under France's EPR fee scaling. |
| Spout Insertion Equipment Investment | Belgian and Dutch converters capture premium beverage and home care segment placement. |
| Central European Capacity Expansion | Poland and Romania offer EPR arbitrage against Western European compliance cost structures. |
| Paper-Fiber Hybridization Development | Italian dry grocery and personal care segments reward fiber-dominant laminate substitution. |
| Pharmaceutical Certification Specialization | Child-resistant and senior-friendly pouch qualifications command generics manufacturer outsourcing. |
Research Methodology
Coverage spans Western Europe and Central Europe, with primary inputs from each regulatory cluster. Primary interviews with flexible packaging plant managers, food retail procurement leads, pharmaceutical regulatory affairs directors, and EPR scheme administrators combined with secondary validation from EFSA food-contact approval databases, EU Green Deal delegated acts, Cefic resin trade statistics, and national packaging law filings. Bottom-up volume modeling triangulates against top-down converter capacity assessments.
Rate-of-change decomposition separates volume growth from value expansion across substrate transitions, with CAGRs derived from segment-level elasticity modeling against regulatory deadline phasing. Segmentation dimensions include pouch format type, material substrate category, end-use vertical, closure mechanism, and national EPR compliance tier. Industry-specific forecast inputs incorporate EVOH supply contract visibility and discounter private-label conversion timelines.
Inputs from EFSA pre-submission consultations and converter R&D pipelines were available through the study window; gaps in post-consumer mechanical recycling capacity data introduce uncertainty bands for circular economics assumptions. Forecasts reflect documented assumptions on mono-material validation timelines and EPR fee trajectory implementation. Practitioners should monitor EVOH capacity expansion announcements and EFSA novel coating approval decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Slider Zipper Pouch Market
Pouch
Ziplock Products Market
Pouch
Zipper Pouch Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Clear Pouches Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Benelux Pouch Packaging Market
Pouch
Recyclable PE Pouch Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Stick Pouches Packaging Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Nigeria Pouch Packaging Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
GCC Retort Pouches Market
Pouch
Germany Pouch Packaging Market