
 Aluminium Bags and Pouches Market | 2026-2036
Aluminium Bags and Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Bags and Pouches Market Analytics
Subscription-based packaging design services is pivoting how converters engage brand owners, shifting transactions toward multi-year performance contracts. Constantia Flexibles Group GmbH leverages its European converter network to anchor high-barrier pharmaceutical pouch supply. Amcor Limited sustains global manufacturing scale across multiple aluminium-laminate platforms. Sealed Air Corporation differentiates through active packaging integration within pouch structures.
Aluminium bags and pouches are multi-layer flexible containers incorporating aluminium foil barrier layers ranging from 6 to 12 microns, laminated with polyethylene, polyester, or polyamide substrates via adhesive or extrusion bonding to exclude moisture, oxygen, and light. They serve primarily to extend product stability in shelf-sensitive applications including retort foods, pharmaceutical blisters, and lithium battery components. Stand-up pouches command the largest volume share among product types due to retail shelf efficiency and consumer convenience, while zipper bags represent the fastest-expanding closure-enhanced segment driven by resealability requirements in food and personal care. The 70 microns thickness category captures dominant margin pools by balancing material cost against barrier performance thresholds demanded by pharmaceutical and electronics end users.
FDA regulations governing pharmaceutical contact materials and EU REACH restrictions on adhesive chemistries shape formulation choices and supplier qualification timelines for aluminium pouch manufacturers. EFSA migration limits and ISO 9001 quality certifications further constrain substrate sourcing and lamination process controls in food-facing applications. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return scheme expansions that will recalibrate material recovery economics and lightweighting incentives across the value chain.
Market Dynamics
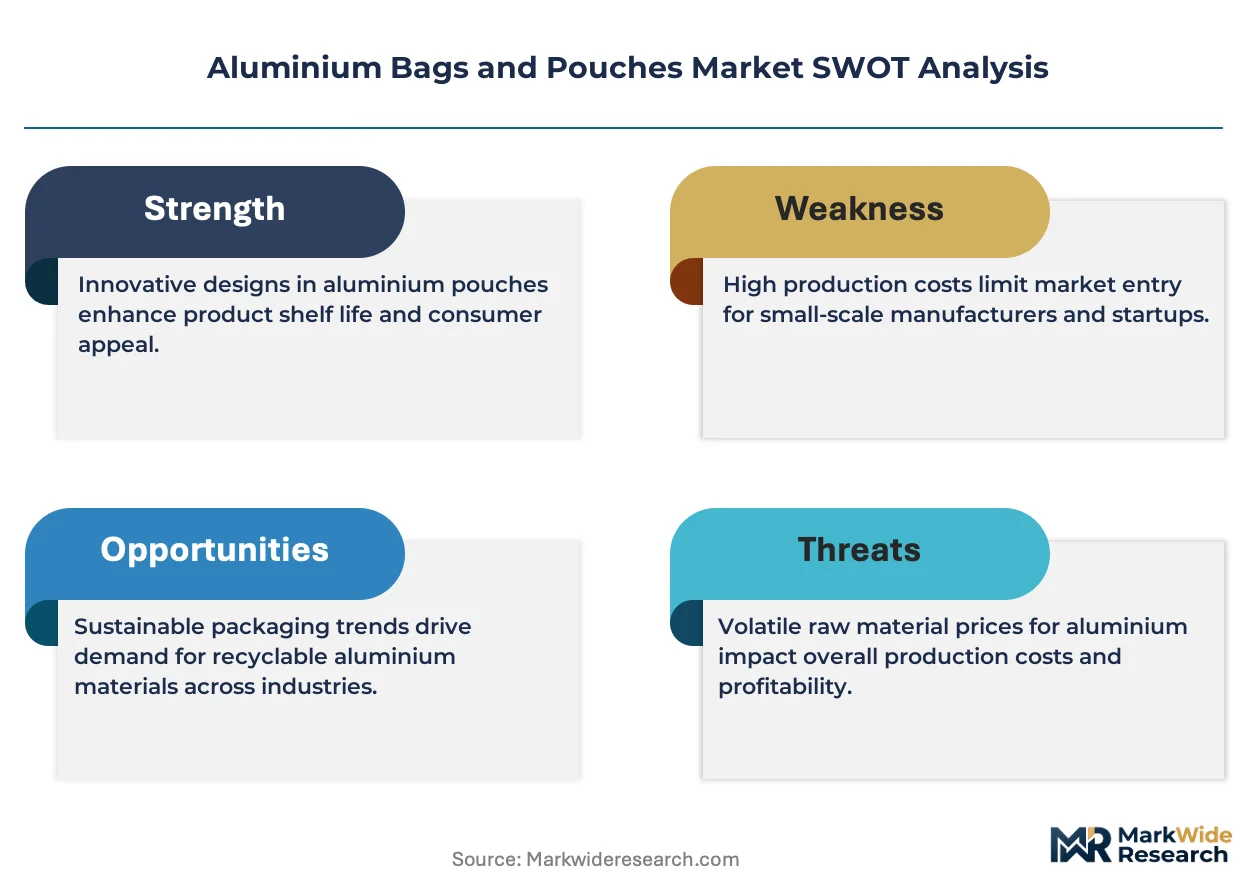
EU REACH restrictions on adhesive chemistries are forcing rapid reformulation across the aluminium pouch supply chain, compressing supplier qualification timelines and elevating compliance costs for converters serving pharmaceutical and food-grade applications.
Growth Catalysts
- Retort Food Expansion:Shelf-stable meal demand in Germany and the United States is pulling high-barrier pouch volumes, with converters investing in 12-micron foil lamination capacity to meet sterilization requirements.
- REACH-Driven Material Innovation:ECHA pressure on solvent-based adhesives is accelerating water-borne and UV-curable alternatives, opening qualification windows for compliant substrate suppliers.
- Lithium Battery Packaging:Electrolyte barrier demands from cell manufacturers in India are creating dedicated pouch specifications with enhanced puncture resistance and moisture exclusion.
Market Restraints
- Aluminium Foil Supply Concentration:Primary foil rolling capacity clusters in China and Russia, exposing converters to tariff volatility and energy cost pass-throughs.
- Polyethylene Tethering:Sealant layer dependence on fossil-derived PE creates margin pressure when ethylene feedstock prices spike, limiting lightweighting flexibility.
- Monomaterial Substitution Threat:Mylar and metallized PP films from European film extruders are capturing snack and confectionery applications where barrier requirements permit.
Strategic Opportunities
- Indian Pharmaceutical Cold Chain:Temperature-sensitive biologics distribution gaps create demand for insulated aluminium pouches with phase-change lining.
- EU Extended Producer Responsibility:Packaging waste directive revisions will reward aluminium's recyclability with fee reductions, favoring foil-heavy laminates over multi-polymer alternatives.
- Digital Printing Convergence:HP Indigo and Xeikon press compatibility with thin-gauge foil substrates enables short-run customization for craft food brands.
Industry Challenges
- Lamination Technician Scarcity:Adhesive formulation expertise and tension-control specialization are aging out of European and North American converter workforces.
- Migration Testing Backlogs:EFSA compliance documentation for new substrate combinations faces 14-18 month queue times at accredited laboratories.
- Legacy ERP Integration:Track-and-trace serialization requirements for pharmaceutical pouches clash with decades-old manufacturing execution systems at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Bags and Pouches Market |
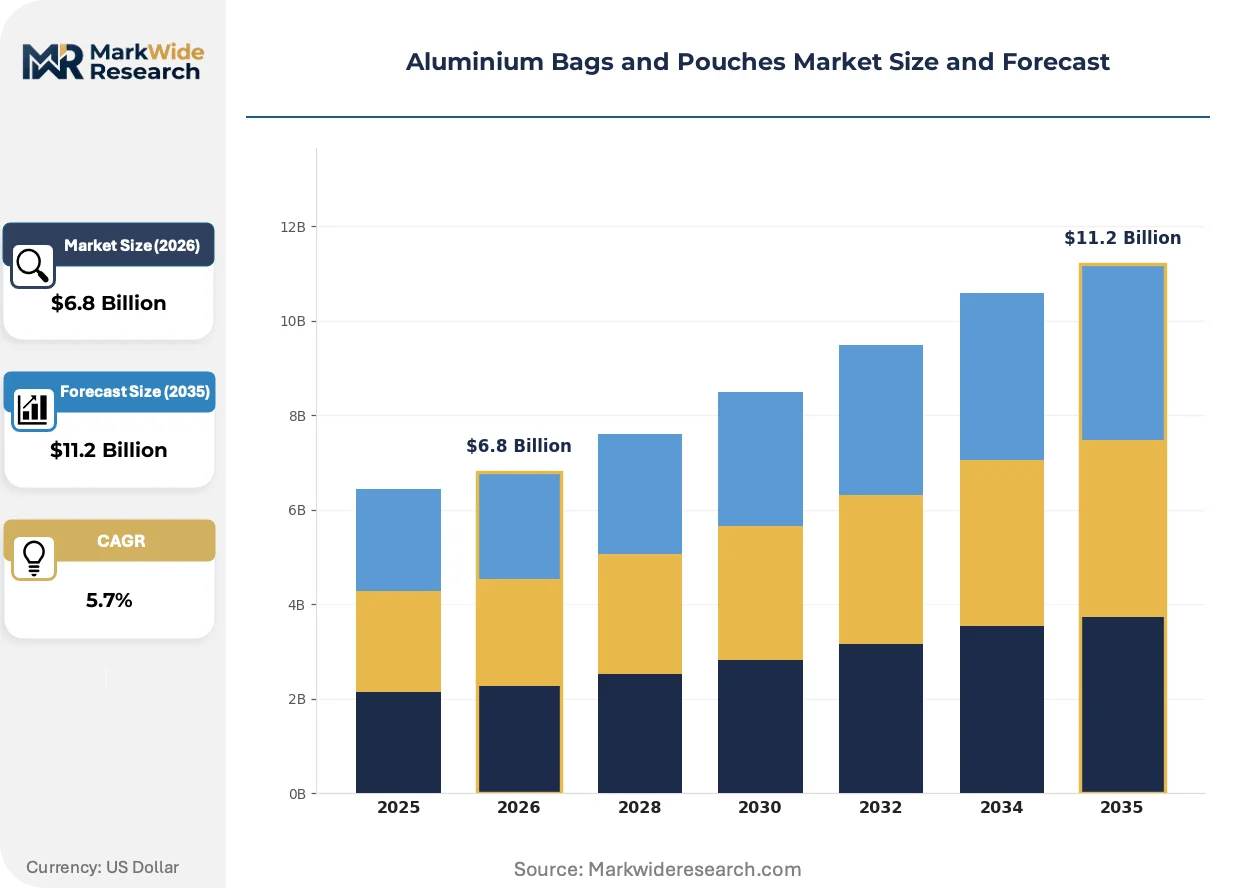
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Stand-up Pouches, Zipper Bags, Gusset Bags End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Closure Type: Heat Seal, Zipper Lock, Tear Notch, Pinch Bottom Thickness: 50 Microns, 70 Microns, 100 Microns, Others |
| Companies Covered | Constantia Flexibles Group GmbH, Ardagh Group, Amcor Limited, Paras Pack, Packman Industries, Mondi Group, Eurofoil Luxembourg S.A., Premier Polymers, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Bags and Pouches Market Evolving Landscape
Active packaging integration and digital manufacturing workflows are compressing development cycles for aluminium pouch formats, while regulatory pressure on chemical migration is rewriting substrate selection criteria across food and pharmaceutical end uses.
High-speed laser micro-perforation is rewriting breathable barrier specifications for fresh produce applications. Modified atmosphere packaging developers in the Netherlands and Spain are adopting 6-micron foil laminates with patterned aperture arrays to regulate respiration rates. This precision is displacing mechanical perforation and enabling shelf-life extension for ready-to-eat salads in German retail.
EFSA migration limit tightening on primary aromatic amines is forcing adhesive system overhauls before 2026 enforcement deadlines. Polyurethane and solventless lamination chemistries are displacing conventional two-component systems in converter R&D pipelines. Pharmaceutical blister and sachet manufacturers in Italy and France are accelerating qualification of compliant laminates to avoid supply disruption.
Brand owners are consolidating specification authority and demanding modular pouch platforms that accommodate format changes without full line revalidation. Food marketers in the United States are shifting from rigid can to retort pouch formats for premium soup and sauce offerings. This specification concentration is compressing converter margins while rewarding those with platform breadth and rapid prototyping capability.
Aluminium Bags and Pouches Market Segmentation
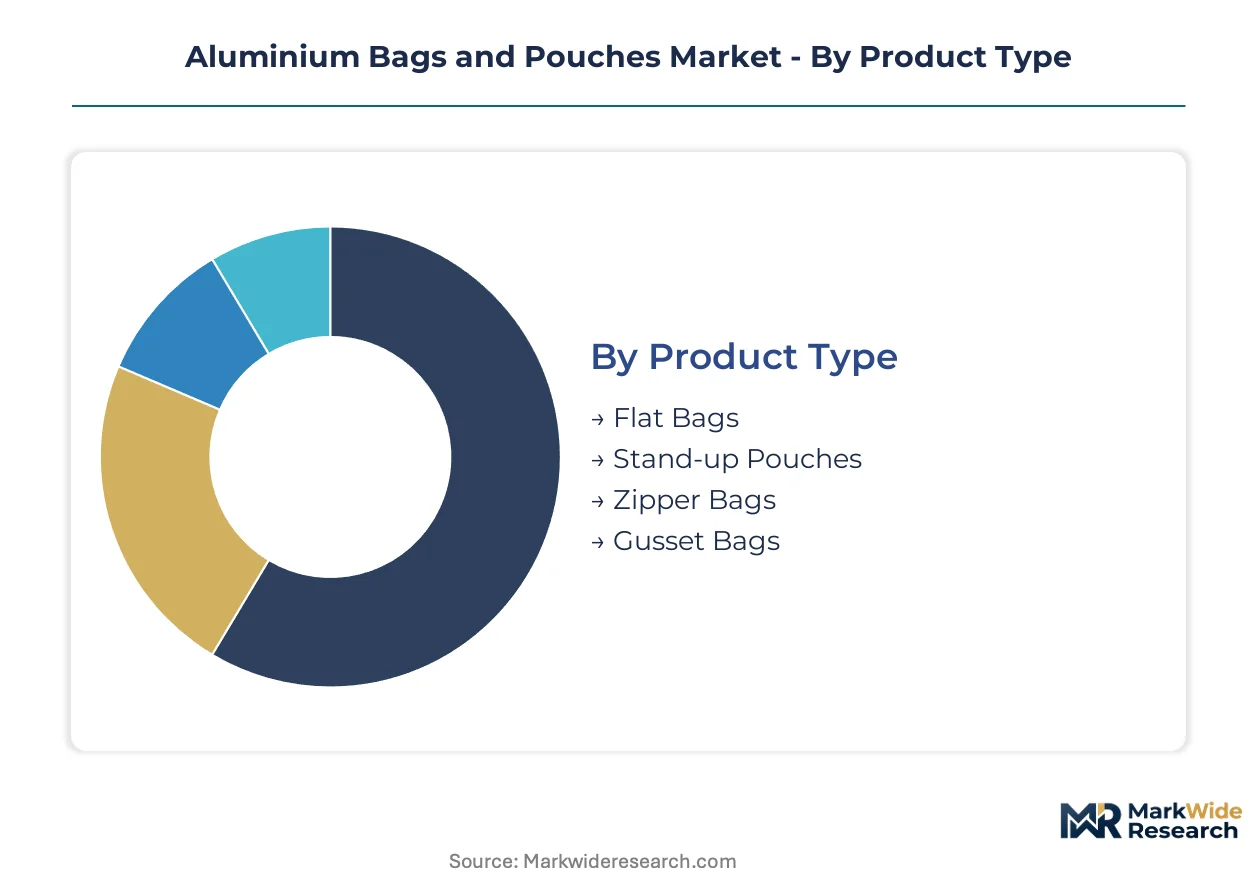
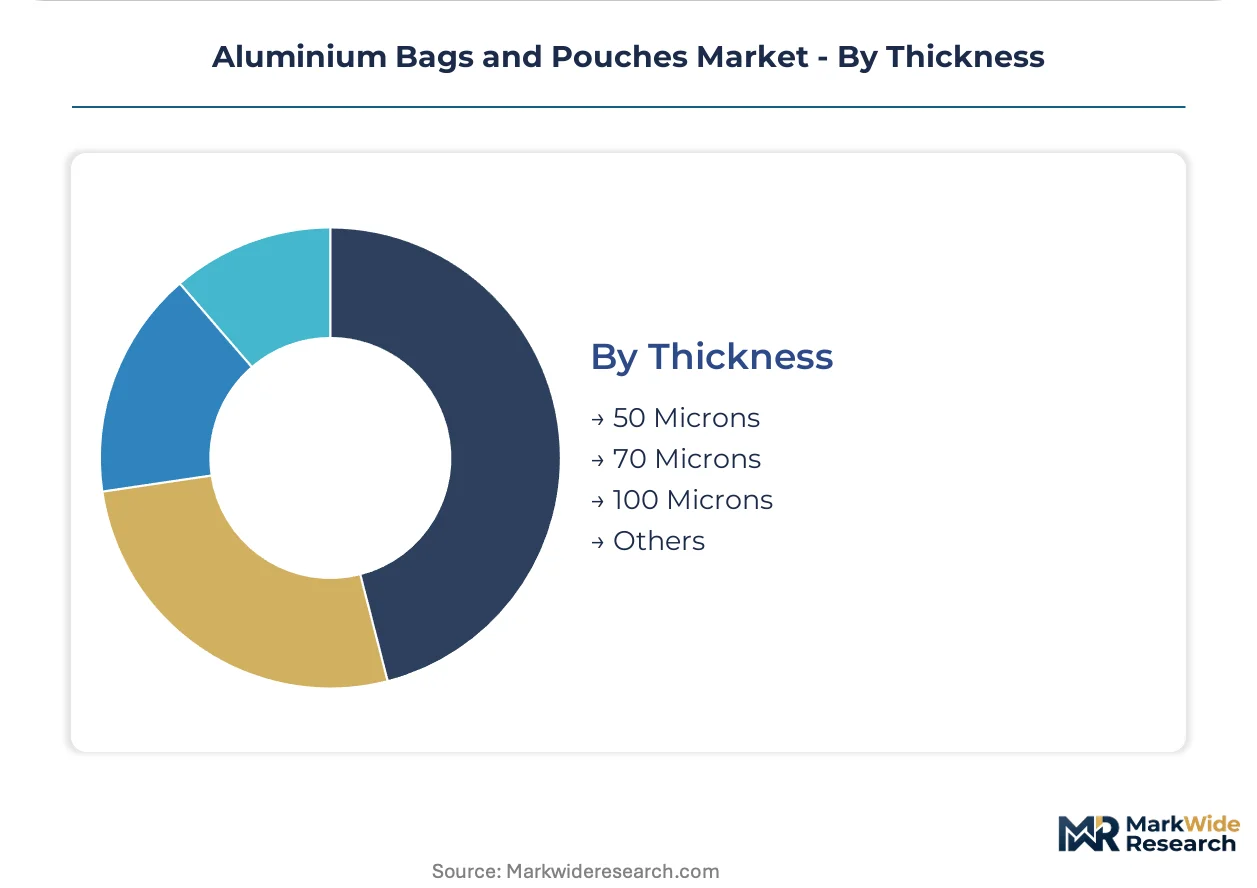
Converters align capacity investments with segment-specific barrier requirements and qualification timelines. Product type and thickness specifications determine lamination equipment configuration and margin structure across pharmaceutical, food, and electronics end uses.
Product Type:
Supply concentration in stand-up pouch converting clusters around German and US converters with platform flexibility.
- Stand-up Pouches:These formats incorporate bottom gusset structures enabling vertical shelf display. Retail format shifts in Germany and the United States favor these configurations for ready-to-eat soups and sauces, with converters investing in high-speed filling line compatibility.
- Zipper Bags:Resealable closure systems add polyethylene track lamination complexity. Personal care and premium snack segments in North America specify these for multi-use convenience, though zipper mechanism sourcing concentrates among three Asian component suppliers.
- Flat Bags:Three-side-seal configurations serve pharmaceutical blister and battery component applications where minimal headspace matters.
- Gusset Bags:Side-folded expansions accommodate bulk dry goods and industrial chemical packaging with variable fill volumes.
Stand-up pouches absorb the bulk of installed capacity; zipper bags are expanding most quickly.
End Use Industry:
Application-specific migration testing and sterilization requirements partition converter capabilities into distinct qualification tiers.
- Food & Beverage:Retort sterilization compatibility demands 12-micron foil lamination with high-temperature adhesive systems. Shelf-stable meal demand in Germany and the United States pulls capacity from pharmaceutical-qualified converters.
- Pharmaceuticals:Blister and sachet specifications require EMA and FDA dual-qualification with full batch traceability. Italian and French manufacturers face compressed timelines for REACH-compliant adhesive transitions.
- Personal Care:Cosmetic and hygiene applications prioritize oxygen exclusion for fragrance stability with moderate barrier specifications.
- Electronics:Lithium battery pouch requirements specify puncture-resistant laminates with electrolyte barrier performance; Indian cell manufacturers are driving dedicated capacity expansion.
Food & Beverage commands the majority of foil lamination output; Pharmaceuticals maintains the steepest expansion trajectory.
Closure Type:
Cost tier differentiation separates commodity heat-seal formats from value-added resealable systems requiring specialized component supply.
- Heat Seal:Direct foil-to-foil or foil-to-film bonding via impulse or constant heat equipment represents the baseline configuration across all end uses.
- Zipper Lock:Interlocking polyethylene tracks add material cost and lamination precision requirements; personal care adoption in North America accelerates specification.
- Tear Notch:Laser-scored or die-cut access features enable consumer opening without tools; common in single-serve pharmaceutical sachets.
- Pinch Bottom:Folded and crimped closures serve industrial and agricultural bulk packaging with mechanical rather than thermal sealing.
Heat Seal retains the largest volume base; Zipper Lock is gaining share fastest among premium format conversions.
Thickness:
Margin structure concentrates in mid-gauge specifications balancing material cost against performance thresholds.
- 70 Microns:Multi-layer constructions at this specification balance puncture resistance with flexibility for pharmaceutical and electronics applications. German and US converters anchor capacity here due to consistent demand from regulated end uses.
- 50 Microns:Lightweight laminates serve fresh produce and modified atmosphere packaging where breathability matters; Dutch developers lead laser micro-perforation integration at this gauge.
- 100 Microns:Heavy-duty constructions accommodate aggressive chemical contents and extended outdoor storage; limited converter specialization creates supply constraints.
- Others:Custom specifications including ultra-thin 6-micron foil layers for cost-sensitive applications and specialty gauges for military or aerospace requirements.
70 Microns captures dominant margin pools; 50 Microns is climbing the fastest on fresh produce format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and Russia concentrate primary aluminium foil rolling capacity, while Germany, India, and the United States absorb the majority of converted pouch output. This geographic split exposes downstream converters to raw material tariff volatility and energy cost pass-throughs.
Germany
Retort food manufacturers in Bavaria and North Rhine-Westphalia drive demand for 12-micron foil laminations with high-temperature adhesive compatibility. ECHA REACH enforcement on solvent-based chemistries compresses supplier qualification timelines for converters serving pharmaceutical blister applications. The Düsseldorf-Cologne corridor hosts Europe's densest cluster of flexible packaging R&D facilities.
United States
Shelf-stable meal brands in the Midwest and Southeast are shifting soup and sauce formats from rigid cans to retort pouches. FDA pharmaceutical contact material regulations shape substrate sourcing decisions for blister and sachet manufacturers. Chicago-area converters maintain the country's largest installed base of high-speed filling line compatible stand-up pouch capacity.
India
Lithium battery cell manufacturers in Gujarat and Maharashtra specify puncture-resistant pouches with electrolyte barrier performance for electrolyte exclusion. CDSCO pharmaceutical packaging regulations govern barrier specifications for temperature-sensitive biologics distribution. The Ahmedabad-Surat industrial belt anchors dedicated capacity expansion for electronics-grade laminates.
Italy
Pharmaceutical blister and sachet manufacturers in Lombardy and Emilia-Romagna face compressed timelines for EFSA-compliant adhesive transitions before 2026 enforcement deadlines. ANSM national pharmaceutical regulator documentation requirements extend batch traceability obligations through the supply chain. The Milan-Turin axis concentrates Italy's highest-value flexible packaging conversion for regulated medical applications.
Netherlands
Modified atmosphere packaging developers in the Randstad region adopt 6-micron foil laminates with laser micro-perforation for fresh produce respiration control. EU Packaging Waste Directive revisions reward aluminium's recyclability with extended producer responsibility fee reductions. Wageningen-area research clusters pioneer breathable barrier specifications displacing mechanical perforation.
Aluminium Bags and Pouches Market Competitive Landscape
Top-tier vendors anchor multi-regional platform scale, while mid-tier specialists occupy narrow qualification niches. The vendor base stratifies across integrated film-to-pouch converters, standalone laminators, and regional component suppliers. Strategic archetypes include pharmaceutical-qualified barrier specialists, food-grade retort pouch platform operators, and electronics-grade puncture-resistant laminators. Consolidation pressure favors backward integration into captive foil supply and geographic expansion through distributor partnerships.
Within the European converter tier, Constantia Flexibles Group GmbH and Eurofoil Luxembourg S.A. exemplify multi-platform barrier specialists with pharmaceutical and food-grade qualification breadth. Amcor Limited occupies a position among globally scaled laminators with manufacturing presence across multiple continents. Sealed Air Corporation represents the active packaging integration archetype, embedding functional layers within pouch structures for shelf-life extension. These three names illustrate how competitive positioning stratifies across geographic coverage, regulatory qualification depth, and technology integration capability.
| Leading Market Players |
|---|
| Constantia Flexibles Group GmbH |
| Ardagh Group |
| Amcor Limited |
| Paras Pack |
| Packman Industries |
| Mondi Group |
| Eurofoil Luxembourg S.A. |
| Premier Polymers |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Backward integration into captive foil rolling capacity anchors both supply security and pricing power for converters serving pharmaceutical and battery-grade applications. German and US laminators with in-house 12-micron foil supply command premium positioning against peers dependent on Chinese and Russian primary metal.
Pricing Analysis
Cost-down pressure on mid-tier converters accelerates because REACH-compliant adhesive reformulation is elevating qualification costs without commensurate price recovery. Three-tier pricing structure across pharmaceutical-qualified, food-grade retort, and economy snack tiers separates margin pools by certification depth and barrier performance. Pharmaceutical blister manufacturers exhibit lowest price sensitivity due to EMA batch-traceability requirements, while snack food brand owners drive hardest bargain on per-unit economics.
Supply Chain Analysis
Dual-sourcing mandates from lithium battery cell manufacturers in India and pharmaceutical packagers in Italy are forcing converters to qualify secondary foil suppliers in South Korea and Japan. Raw material dependencies center on primary aluminium ingot, solventless adhesive chemistries, and laser-perforation equipment from Dutch developers. Tariff exposure on Chinese foil imports constitutes the dominant structural risk. Distribution runs through converter-direct relationships with multinational brand owners, bypassing traditional distributor tiers in regulated end uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over 12-micron foil supply and REACH-compliant adhesive formulation determines long-term viability. Players are pursuing backward integration into foil rolling and forward integration into active packaging layers.
For Market Incumbents: Anticipate monomaterial substitution threats from metallized PP films in snack applications by deepening pharmaceutical and battery-grade qualification moats. Invest in solventless lamination capacity ahead of ECHA enforcement deadlines. Secure dual-source foil agreements with South Korean and Japanese rollers to mitigate tariff volatility on Chinese supply. For New Entrants and Emerging Players: The premium-economy price gap in Indian lithium battery pouch specifications creates entry space for puncture-resistant laminators with electrolyte barrier expertise. Target Gujarat and Maharashtra cell manufacturers with dedicated capacity and CDSCO documentation support. Pursue qualification partnerships with established European adhesive suppliers to compress EFSA approval timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multi-platform converters seeking pharmaceutical qualification breadth and Indian manufacturing footprint. Five-to-ten-year viability hinges on REACH compliance infrastructure and foil supply security. Monitor EFSA migration testing queue lengths as inflection indicator for adhesive system transition stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Rolling | Captive 12-micron supply insulates German converters from Chinese tariff volatility and energy cost pass-throughs. |
| Solventless Lamination Capacity Expansion | REACH-compliant adhesive systems qualify Italian and French pharmaceutical packagers ahead of ECHA deadlines. |
| Indian Manufacturing Footprint Establishment | Gujarat-based production serves lithium battery cell manufacturers with reduced logistics lead times and CDSCO proximity. |
| Laser Micro-Perforation Technology Adoption | Dutch-developed precision equipment enables 6-micron foil specifications for fresh produce modified atmosphere packaging. |
| Active Packaging Layer Integration | Embedded functional layers extend shelf-life for retort food applications, differentiating against commodity laminators. |
Research Methodology
Trade association filings, ECHA regulatory databases, and converter capacity announcements formed the secondary backbone for this analysis. Primary interviews with lamination equipment specialists, pharmaceutical packaging procurement managers, and lithium battery cell manufacturing engineers triangulated against customs records and SEC disclosures from publicly traded flexible packaging firms. Bottom-up segment sizing and top-down macro validation ensured cross-check integrity across the analysis window.
Historical trendline analysis on foil lamination output and pharmaceutical pouch adoption patterns anchored the projection framework. Segmentation modeling incorporated product type, thickness specification, end-use industry, and closure mechanism dimensions across the projection horizon. CAGRs derived from regression analysis on converter investment cycles and regulatory compliance cost trajectories. Industry-specific inputs included EFSA migration testing queue durations and REACH adhesive reformulation timelines.
Inputs from ECHA enforcement calendars and CDSCO packaging regulation updates were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term volume estimates. Deviation in Chinese foil export tariff schedules or EFSA enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Spain Pouch Packaging Market
Pouch
Flexible Pouch Market
Pouch
France Pouch Packaging Market
Pouch
Heat Seal Pouch Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Slider Zipper Pouch Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Recyclable PE Pouch Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Portion Control Packs Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Retort Pouch Packaging Market