
 Liquid Pouch Market | 2026-2036
Liquid Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Pouch Market Foresight
Converting engineer shortages across European flexible packaging hubs is redrawing competitive boundaries for liquid pouch producers. Amcor plc leverages its integrated film extrusion network to sustain supply security for spouted dairy formats. Tetra Pak International anchors aseptic carton-to-pouch technology leadership in ambient beverage segments. Mondi Group competes through paper-based barrier innovations that navigate emerging recyclability mandates.
A liquid pouch is a flexible primary package constructed from multilayer films—typically incorporating polyethylene, polyethylene terephthalate, or aluminum oxide barrier coatings—formed into sealed volumes with capacities ranging from single-serve milliliters to multi-liter family sizes, designed for the containment, protection, and dispensing of pumpable or pourable products. Stand-up pouches occupy the dominant volume position across food and beverage end uses where shelf presence and pallet efficiency matter. Spouted pouches represent the fastest-expanding closure configuration, capturing margin pools in toddler nutrition and adult sports nutrition where controlled dispensing commands price premiums. Composite material structures concentrate investment activity as converters balance oxygen barrier performance against mechanical recyclability requirements.
The EU Green Deal and REACH frameworks are tightening chemical migration thresholds for food-contact laminates, while FDA compliance obligations govern U.S. interstate commerce for infant formula and medical food pouches. China's GB standards and SAMR labeling rules shape import access and domestic formulation requirements for foreign suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to pursue in-house recycling infrastructure or outsource compliance to specialized recovery operators.
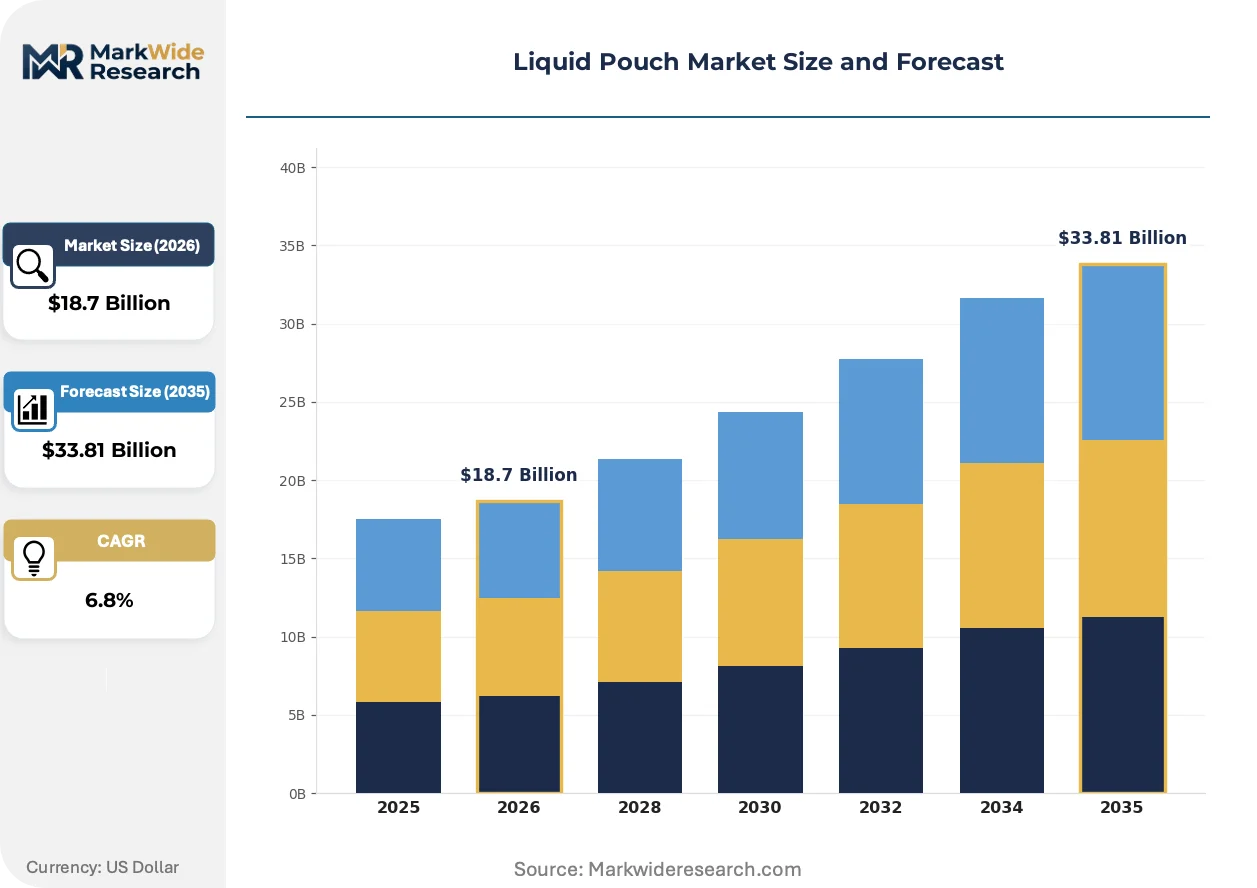
Market Dynamics
Flexible packaging converters face intensifying pressure from EU Green Deal mandates to redesign multilayer laminates for mechanical recyclability without sacrificing oxygen barrier performance in sensitive beverage applications.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for rigid containers accelerate brand migration toward lightweight pouch formats in ready-to-drink segments.
- E-commerce logistics optimization:Pallet density advantages of flat-packed empty pouches reduce inbound freight costs for beverage co-packers serving direct-to-consumer channels.
- Spout welding automation:Advances in ultrasonic sealing technology enable high-speed production lines previously constrained by manual fitment insertion.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin contracts track naphtha spreads, squeezing converter margins during upstream petrochemical tightness.
- Barrier coating supply concentration:Aluminum oxide deposition equipment manufacturers cluster in Germany and Japan, creating single-source vulnerability for regional converters.
- Recyclability certification delays:Extended producer responsibility schemes in France and Italy require third-party recyclability assessments that extend product launch timelines.
Strategic Opportunities
- Indonesia retail modernization:Convenience store expansion in Jakarta and Surabaya creates demand for ambient-stable pouch formats in tropical climates.
- Paper-based barrier convergence:Fiber substrates combined with bio-based coatings address brand commitments to eliminate fossil-derived plastics by 2030.
- Pharmaceutical liquid dosing:Unit-dose pouches for pediatric and geriatric medications remain underpenetrated versus blister packs in European markets.
Industry Challenges
- Multilayer adhesive compatibility:Solvent-free lamination chemistries require revalidation of bond strength across film substrates, extending qualification cycles.
- Converting engineer scarcity:European technical universities graduate insufficient extrusion and printing specialists to replace retiring workforce cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Pouch Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Spouted Pouches, Zipper Pouches Material: Plastic, Aluminum, Paper, Composite Closure Type: Stand-Up Zipper, Spout, Heat Seal, Press-to-Close End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products |
| Companies Covered | Amcor plc, Tetra Pak International, Mondi Group, Sealed Air Corporation, Berry Global Group, Smurfit Kappa Group, Sonoco Products Company, Constantia Flexibles Group, Uflex Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Pouch Market Shifts & Advancements
Active packaging intelligence and material stream redesign are compressing development cycles while regulatory chemistry restrictions force reformulation of established laminate structures.
High-barrier oxide coatings deposited through plasma-enhanced chemical vapor deposition are miniaturizing equipment footprints for mid-capacity converters. Regional dairy processors in Poland and Romania adopt compact deposition lines to bring barrier film production in-house. This technology is miniaturizing capital requirements that previously restricted access to multinational packaging groups.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances compel substitution of grease-resistant coatings in food-contact laminates. German and Dutch converters accelerate testing of silicone-based alternatives for oily sauce applications. Infant nutrition brands face compressed reformulation timelines as EFSA evaluates migration thresholds.
Brand procurement teams now mandate recyclability pre-certification before contract award, displacing price-only sourcing criteria. Co-packing agreements in the Netherlands and Belgium increasingly specify Design for Recycling guidelines from RecyClass. Sports nutrition startups leverage this shift to differentiate through circular packaging claims in competitive retail sets.
Liquid Pouch Market Segmentation
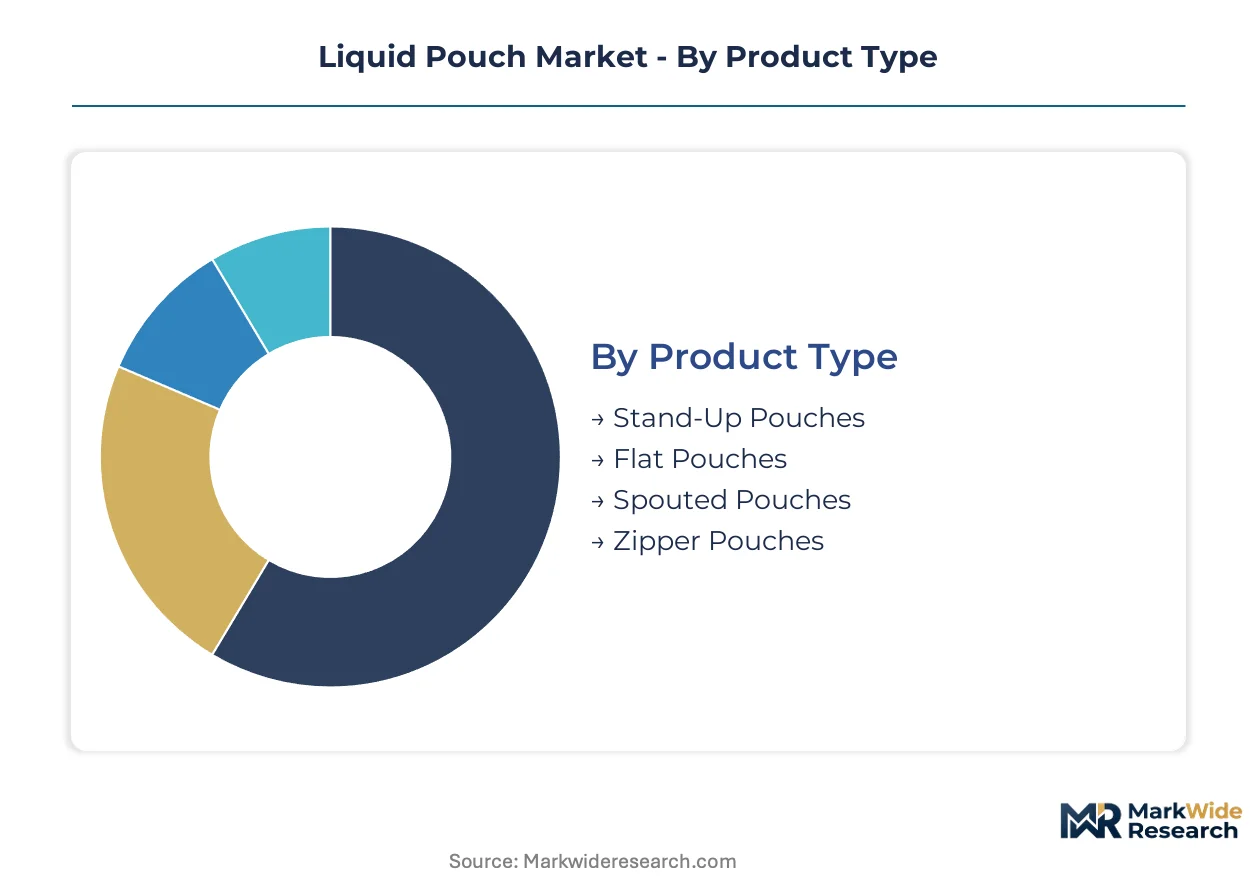
Liquid pouch segmentation reveals divergent margin structures across closure complexity tiers and material compliance pathways. Product architecture and substrate selection determine converter capital intensity and brand sustainability positioning.
Product Type:
Stand-up pouches dominate domestic consumption in North American and European retail channels, while spouted formats drive export-led premiumization in Asian infant nutrition markets.
- Stand-Up Pouches:Multilayer laminates with gusseted bases enable vertical shelf display and pallet stacking efficiency. Beverage co-packers in Germany and California prioritize this format for refrigerated juice and dairy alternatives where case cube optimization reduces distribution costs.
- Spouted Pouches:Fitment-welded constructions with threaded or tethered caps support controlled dispensing and resealability. Demand concentrates in Japanese toddler nutrition and Brazilian sports nutrition segments where single-serve precision dosing commands price premiums over rigid bottles.
- Flat Pouches:Two-seal pillow constructions serve commodity sauces and condiments in Southeast Asian retail modernization.
- Zipper Pouches:Press-to-close interlocking tracks suit multi-serve frozen smoothie packs in Australian and Canadian club store channels.
Stand-up pouches hold the largest share; momentum sits with spouted configurations.
Material:
Substrate selection stratifies across cost tiers, with virgin polyethylene dominating mass-market applications and fiber-based barriers capturing sustainability-driven procurement mandates.
- Composite:Multilayer coextrusions combining polyethylene, ethylene vinyl alcohol, and tie-layer adhesives balance oxygen barrier performance against mechanical recyclability. EU Green Deal compliance pressures are accelerating investment in mono-material composite redesigns by Dutch and Italian converters.
- Plastic:Single-polymer polyethylene or polypropylene structures dominate emerging market cost-sensitive segments.
- Aluminum:Foil laminations sustain ultra-high barrier requirements in retorted baby food and wine pouch applications.
- Paper:Fiber substrates with bio-based barrier coatings address brand fossil-plastic elimination commitments in Nordic and Benelux markets.
Composite structures retain volume leadership; paper-based alternatives are climbing the fastest.
Closure Type:
Closure complexity correlates with end-use precision requirements and automation capital deployment by regional co-packers.
- Spout:Injection-molded polyethylene or polypropylene fitments welded via ultrasonic or hot-plate sealing enable controlled flow rates. Sports nutrition brands in the United Kingdom and South Korea specify 10mm and 16mm neck finishes for isotonic gel and protein concentrate applications.
- Heat Seal:Peelable membrane closures dominate unit-dose pharmaceutical and sample pouch formats.
- Stand-Up Zipper:Integral zipper profiles compete with spouts in refrigerated dairy segments.
- Press-to-Close:Slider mechanisms serve multi-serve frozen and dry goods in North American mass retail.
Spout closures command the steepest expansion trajectory; heat seal retains cost-sensitive volume.
End User:
End-use concentration varies sharply by regulatory barrier intensity and formulation stability requirements.
- Food & Beverage:Aseptic and hot-fill processing compatibility requirements shape material specifications. Ready-to-drink coffee and plant-based milk brands in the United States and Indonesia are displacing rigid bottles with high-barrier pouch formats to meet retailer sustainability scorecards.
- Pharmaceuticals:Unit-dose oral liquid and topical gel pouches remain underpenetrated versus blister packs in European markets.
- Personal Care:Single-serve shampoo and conditioner pouches serve hospitality and airline amenity channels.
- Household Products:Refill concentrate pouches for surface cleaners reduce plastic intensity in concentrated product delivery.
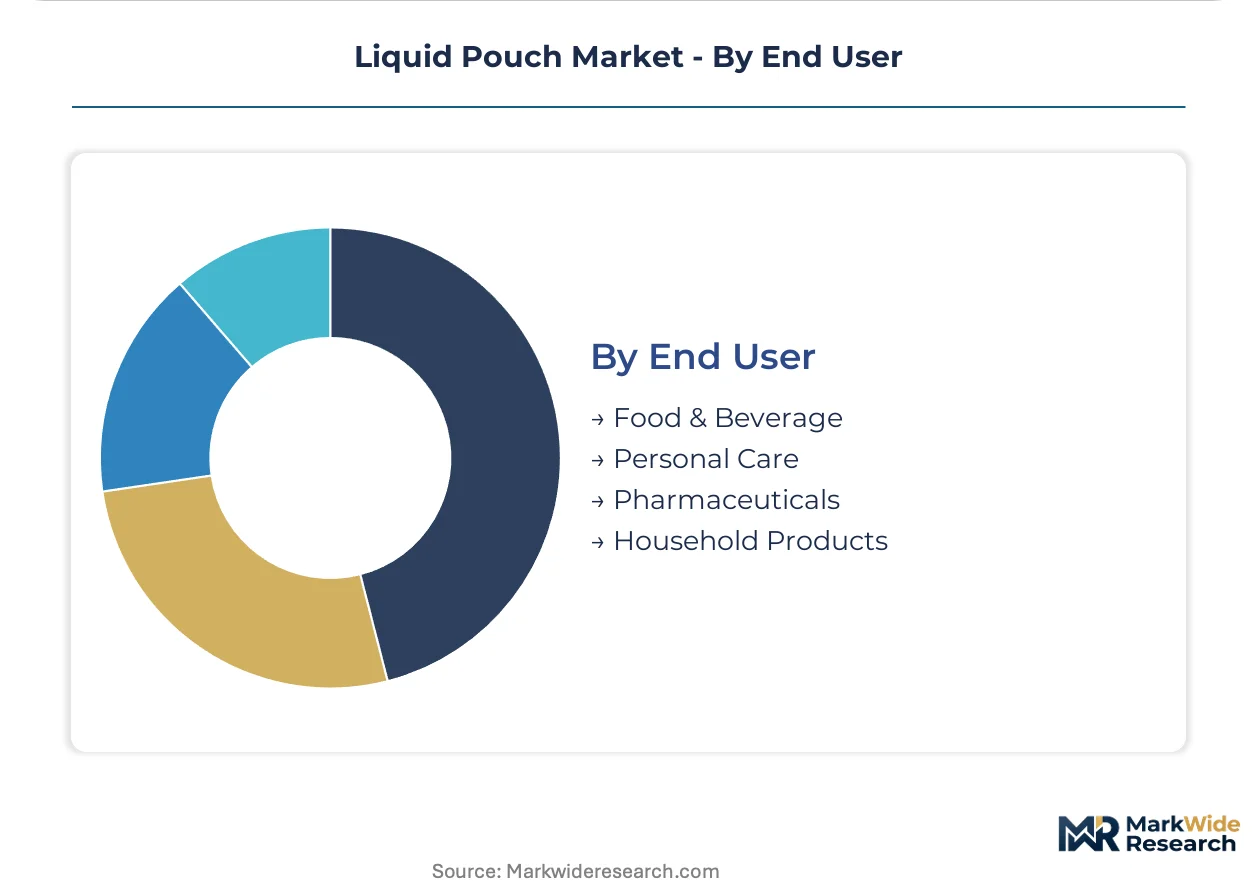
Food and beverage holds the largest share; pharmaceuticals present the steepest untapped margin opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany command pricing premiums against Indonesian competitors due to EU Green Deal compliance certification and technical workforce scarcity. Southeast Asian producers offset this disadvantage through feedstock proximity and labor arbitrage in spouted pouch assembly.
United States
Ready-to-drink beverage brands in California and Texas displace rigid bottles with high-barrier pouch formats to meet retailer sustainability scorecards. FDA compliance obligations govern interstate commerce for infant formula and medical food pouches. Dallas-Fort Worth co-packing clusters invest in ultrasonic spout welding automation for sports nutrition contract manufacturing.
Germany
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances compel substitution of grease-resistant coatings in food-contact laminates. Extended producer responsibility schemes require third-party recyclability assessments that extend product launch timelines. Hamburg and Düsseldorf converters accelerate testing of silicone-based alternatives for oily sauce applications.
China
GB standards and SAMR labeling rules shape import access and domestic formulation requirements for foreign suppliers. Dual carbon goals pressure converters toward mono-material composite redesigns. Yangtze River Delta packaging hubs in Jiangsu and Zhejiang provinces concentrate spout fitment manufacturing for export markets.
Indonesia
Convenience store expansion in Jakarta and Surabaya creates demand for ambient-stable pouch formats in tropical climates. Urban retail modernization and e-commerce logistics favor lightweight pouch formats over rigid alternatives. Batam and Surabaya converting facilities serve ASEAN regional distribution networks with cost-optimized polyethylene structures.
Japan
Unit-dose precision dosing requirements in pediatric and geriatric medications drive pharmaceutical pouch specification. METI circular economy roadmaps mandate Design for Recycling compliance by 2030. Osaka-Kobe industrial corridor hosts specialized deposition equipment for aluminum oxide barrier coating miniaturization.
Liquid Pouch Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated multinationals with captive film extrusion networks capture premium-margin aseptic and high-barrier segments. Regional specialists compete on spout assembly speed and local regulatory navigation. Dominant competitive moves include backward integration into barrier coating deposition and geographic expansion through co-packing joint ventures in Southeast Asia.
Within the integrated multinational tier, Amcor plc and Tetra Pak International exemplify divergent technology anchoring strategies. Amcor leverages its film extrusion network to sustain supply security for spouted dairy formats. Tetra Pak anchors aseptic carton-to-pouch technology leadership in ambient beverage segments. Mondi Group occupies a position bridging paper-based barrier innovation with emerging recyclability mandates in Nordic and Benelux markets.
| Leading Market Players |
|---|
| Amcor plc |
| Tetra Pak International |
| Mondi Group |
| Sealed Air Corporation |
| Berry Global Group |
| Smurfit Kappa Group |
| Sonoco Products Company |
| Constantia Flexibles Group |
| Uflex Limited |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for aluminum oxide deposition equipment compress converter pricing power in Germany and Japan, while Southeast Asian producers exploit feedstock proximity to undercut delivered costs across ASEAN distribution networks.
Pricing Analysis
German converters command pricing premiums against Indonesian competitors due to EU Green Deal compliance certification and technical workforce scarcity. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance tier and recyclability certification status. Cost compression in standard-tier polyethylene laminates is intensifying because naphtha feedstock volatility squeezes converter margins. Emerging market beverage co-packers exhibit highest price sensitivity, while infant nutrition brands in Japan and South Korea accept premium positioning for oxygen barrier assurance.
Supply Chain Analysis
Germany and Japan anchor aluminum oxide deposition equipment manufacturing, while China and Indonesia concentrate spout fitment molding and final pouch assembly. Raw material flows draw from Saudi ethylene crackers, South Korean EVOH resin plants, and Thai polyethylene film extrusion hubs. Single-source vulnerability in barrier coating equipment creates regional chokepoint exposure for mid-cap converters lacking multinational supplier relationships. Distribution runs through beverage co-packing clusters in California, Hamburg, and Jakarta before final retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid pouch market represents a high-growth disruption as EU Green Deal mandates force material redesigns that obsolete incumbent laminate structures and reward early movers in mono-material composites.
For Market Incumbents: Consolidate backward integration into film extrusion networks to secure supply security against resin volatility and engineer shortages. Acquire specialized deposition capabilities in Poland or Romania to capture mid-cap dairy processor demand. Prioritize RecyClass certification investment to defend contract renewals from sustainability-driven brand procurement teams.
For New Entrants and Emerging Players: RecyClass fast-track certification unlocks immediate contract eligibility with Dutch and Belgian co-packers specifying Design for Recycling guidelines. Target pharmaceutical unit-dose pouches in European markets where blister pack dominance leaves oral liquid formats underpenetrated. Pursue joint venture structures with Yangtze River Delta spout manufacturers to bypass capital-intensive fitment welding automation.
For Investors and Strategic Acquirers: Long-term, this sits as a materials science consolidation play because regulatory chemistry restrictions compel repeated reformulation cycles that favor R&D-intensive platforms. Acquisition targets include paper-based barrier specialists bridging fiber substrates with bio-based coatings. Watch EFSA migration threshold evaluations for infant nutrition as signal for compressed reformulation timelines and capability scramble.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Composite Redesign | EU Green Deal compliance secures contract eligibility with sustainability-mandated brand procurement teams. |
| Spout Welding Automation Investment | Ultrasonic sealing technology unlocks high-speed production lines previously constrained by manual fitment insertion. |
| RecyClass Certification Program | Third-party recyclability assessments satisfy extended producer responsibility schemes in France and Italy. |
| Backward Integration into Barrier Coating | Plasma-enhanced chemical vapor deposition miniaturization brings high-barrier film production in-house for regional dairy processors. |
| Pharmaceutical Pouch Format Development | Unit-dose precision dosing addresses underpenetrated oral liquid segments versus blister packs in European markets. |
Research Methodology
Desk research of customs trade data, SEC converter filings, and EU regulatory gazettes preceded structured interviews with flexible packaging plant managers, brand procurement leads, beverage co-packing operations heads, and polymer resin procurement directors. Secondary validation drew from ECHA substance restriction updates, RecyClass certification registries, and national extended producer responsibility scheme documentation. Bottom-up capacity assessments triangulated against top-down demand modeling across end-use segments.
Variance decomposition across product architecture, material compliance pathway, and regional regulatory cluster shaped analytical framework development over the projection horizon. Segmentation dimensions modeled include closure complexity tier, substrate selection, end-use concentration, and geographic production hub. CAGRs derived from elasticity-adjusted volume trajectories incorporating spout adoption curves and e-commerce logistics penetration rates. Forecast inputs encompassed ethylene feedstock spread projections and REACH Annex XVII substance restriction timelines.
Underlying assumptions cover mechanical recyclability performance thresholds, extended producer responsibility scheme enforcement intensity, and aluminum oxide deposition equipment delivery schedules, with deviation risk concentrated in EFSA migration threshold revisions and naphtha price volatility spikes. Recalibration cycles align with material shifts in EU Green Deal implementation phases and SAMR labeling rule updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Feminine Care Pouch Film Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Japan Pouch Packaging Market
Pouch
2 Seal Pouches Market
Pouch
PCR Pouches Market
Pouch
Morocco Pouch Packaging Market
Pouch
Box Pouch Market
Pouch
Mexico Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Monodose Packs Market
Pouch
Retort Pouch Market
Pouch
Spouted Pouches Market
Pouch
Colombia Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
Italy Pouch Packaging Market