
 Twist Wrap Packaging Market | 2026-2036
Twist Wrap Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Wrap Packaging Market Analytics
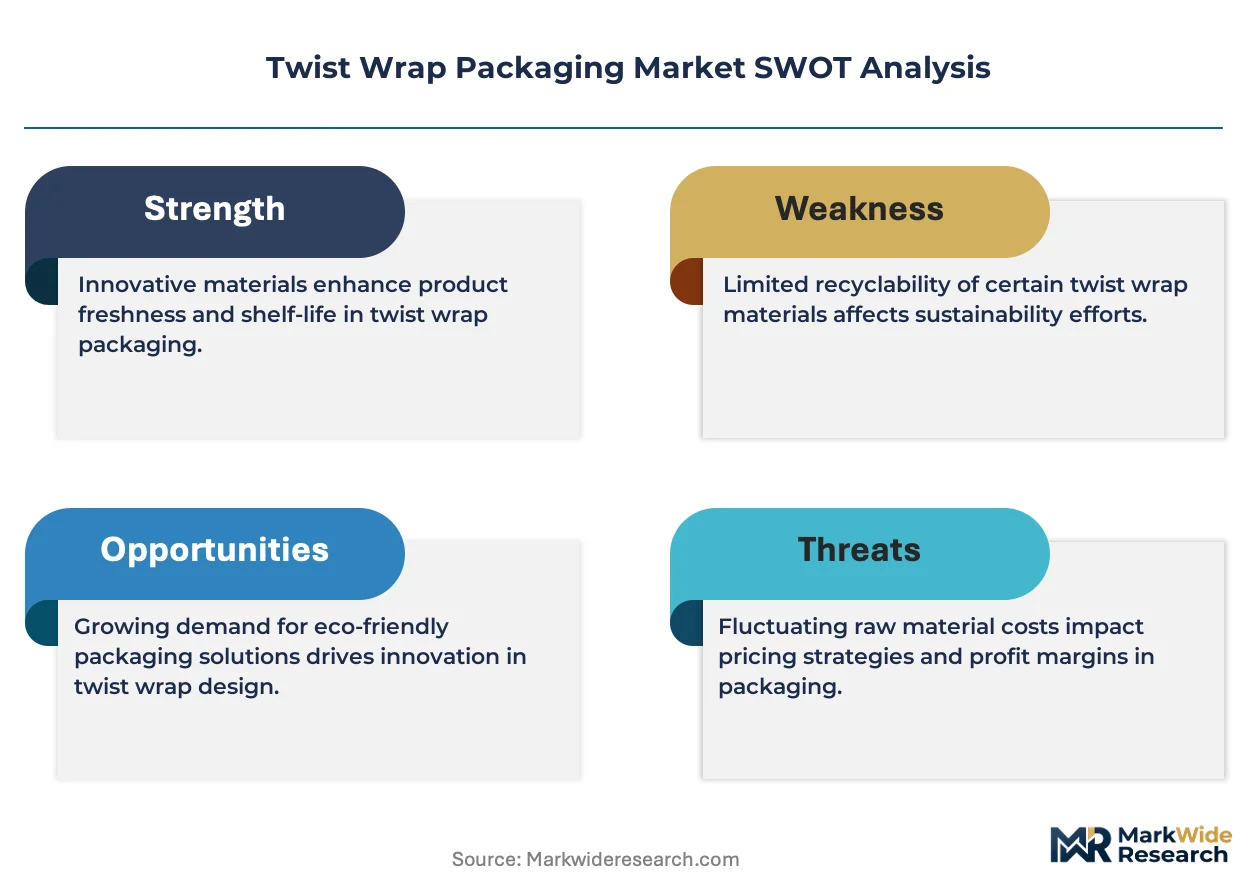
Cellulose-based biodegradable films is restructuring cost structures across confectionery packaging as converters phase out conventional plastic laminates. Amcor plc leverages its global film extrusion footprint to anchor supply for European chocolate brands. Huhtamaki competes through specialized heat-seal coating technologies that sustain shelf-life performance in biodegradable formats. Mondi Group differentiates via integrated kraft paper operations that control fiber sourcing for twist-wrap substrates.
Twist wrap packaging consists of thin, flexible webs—typically 12–30 micron aluminum foil, oriented polypropylene, or coated paper—cut into squares or rectangles and twisted manually or mechanically around individual confectionery pieces to form a sealed, tamper-evident enclosure. Its primary commercial purpose centers on portion control, brand visibility through printed surfaces, and moisture barrier protection for hygroscopic sweets. The material dimension shows aluminum foil occupying established premium chocolate lines while biodegradable films represent the fastest-growing category as retailers enforce sustainability scorecards. End-user demand concentrates in the food industry, where bakery and confectionery sub-segments generate recurring volume, though cosmetics applications for sampler-sized soaps and bath products are expanding.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications jointly shape material compliance pathways, with REACH restrictions on certain plasticizers redirecting formulation investments toward bio-based alternatives. ISO 18606 and ASTM D6400 compostability certifications function as gatekeeping standards for market access in regulated retail channels. Stakeholders must monitor evolving extended producer responsibility fee structures to calibrate material portfolios before compliance costs widen competitive gaps between early movers and laggards.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing material transitions across European confectionery supply chains, redirecting converter investments from conventional plastic laminates toward certified biodegradable films and reconfiguring cost structures for twist wrap packaging procurement.
Growth Catalysts
- REACH plasticizer restrictions:ECHA regulations on phthalate plasticizers redirect formulation investments toward bio-based heat-seal coatings that maintain barrier performance in cellulose-derived films.
- Aluminum foil premium positioning:Established chocolate lines in Germany and Switzerland sustain demand for 12-20 micron foil laminates where moisture barrier specifications exceed biodegradable alternatives.
- Extended producer responsibility fee structures:EU member state EPR schemes penalize non-recyclable packaging, accelerating converter transitions toward ISO 18606 certified substrates.
Market Restraints
- Cellulose pulp input volatility:Nordic softwood pulp price swings transmit directly to kraft paper substrate costs, compressing margins for integrated converters lacking captive fiber supply.
- Composting infrastructure gaps:ASTM D6400 certified films require industrial composting facilities absent in most US municipalities, limiting addressable market for biodegradable formats.
- Heat-seal performance trade-offs:Bio-based coatings exhibit 15-30% lower seal strength versus conventional polyethylene, restricting high-speed twist-wrap machinery compatibility.
Strategic Opportunities
- Cosmetics sampler expansion:Bath product and artisan soap brands in France and Italy are piloting twist-wrap formats for portion-controlled amenity sizing, opening non-food volume.
- Digital printing convergence:Hybrid flexo-inkjet systems enable short-run customization for seasonal confectionery launches, collapsing minimum order quantities from 500,000 to 50,000 units.
- Swiss retail sustainability scorecards:Migros and Coop procurement mandates favor packaging with SQS-certified compostability, creating preferential supplier status for early film certifiers.
Industry Challenges
- Multi-standard certification complexity:Converters must simultaneously navigate EU 13432, ASTM D6400, and home composting OK Compost HOME protocols, extending qualification timelines by 8-14 months.
- Legacy machinery retrofit requirements:Mechanical twist-wrap lines engineered for 25-micron polypropylene require tension control and heating element modifications to handle 35-45 micron biodegradable films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Wrap Packaging Market |
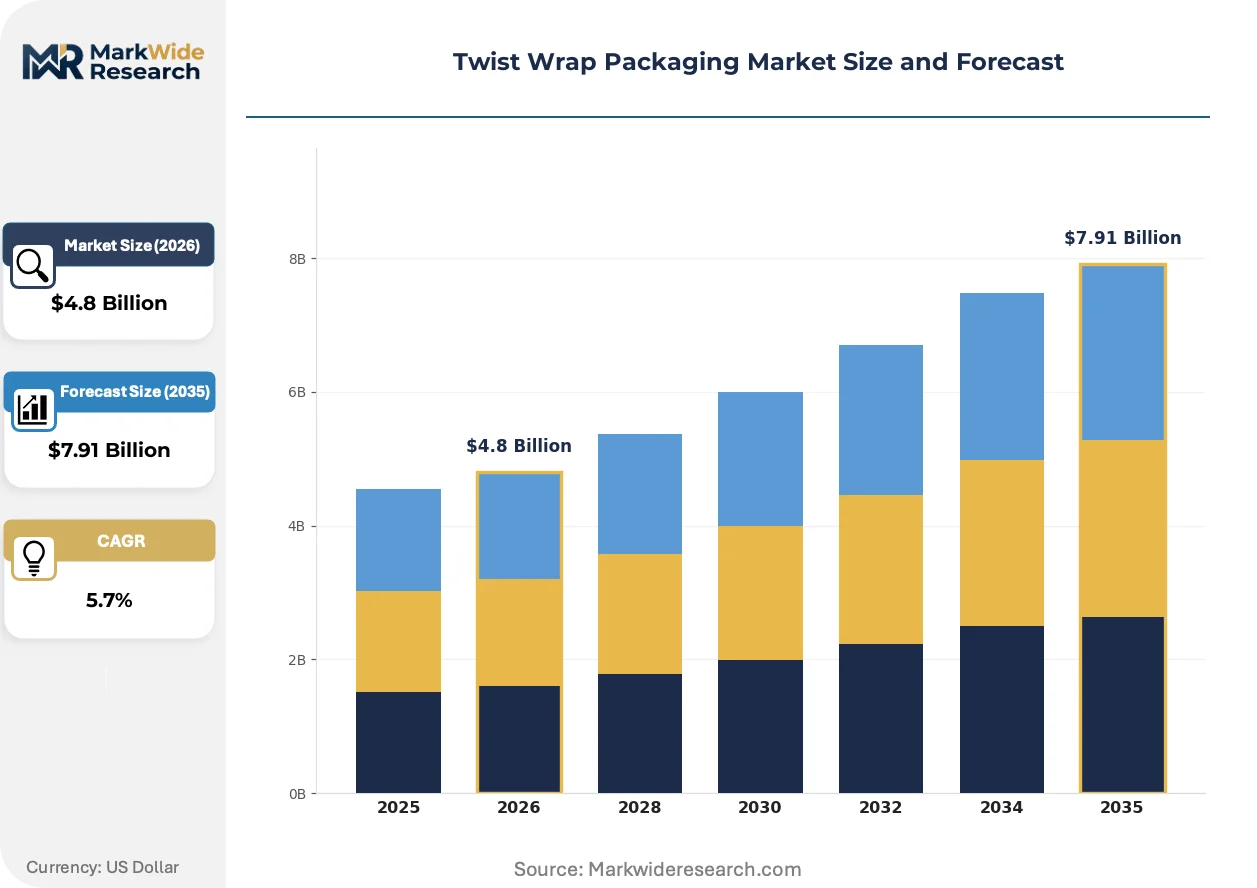
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candy, Chocolates, Snacks, Confectionery Material: Paper, Aluminum Foil, Plastic, Biodegradable Films End User: Food Industry, Bakery, Cosmetics, Pharmaceuticals Size: Small, Medium, Large, Custom |
| Companies Covered | Amcor plc, Huhtamaki, Berry Global Inc., Mondi Group, Polysack Flexible Packaging Ltd., Sunpack Corporation, UFlex Limited, Sonoco Products Company, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Wrap Packaging Market Evolving Landscape
Active investment in biodegradable film extrusion and digital print integration is compressing lead times and enabling mass customization, while regulatory compliance requirements fragment technical standards across jurisdictions.
Vision-guided robotic twist-wrap systems are automating high-speed confectionery lines previously dependent on manual feeding, with Swiss chocolate manufacturers deploying these units for premium truffle assortments where placement precision affects shelf presentation. The technology is automating quality consistency at throughputs exceeding 400 pieces per minute, compressing labor cost differentials between European and emerging-market production sites.
EU Green Deal packaging targets are tightening recycled content thresholds and expanding EPR fee coverage to include small-format flexible packaging, compelling converters to requalify supply chains for post-consumer recycled cellulose feedstocks. German chocolate brands are responding by consolidating procurement around converters with verified mass-balance certification through ISCC PLUS.
Retailer sustainability scorecards are reshaping supplier selection criteria, with French and Belgian supermarket chains weighting compostability certification above unit cost in private-label confectionery tenders. Bakery segment buyers are consolidating vendor relationships toward integrated converters controlling both film extrusion and rotogravure printing, collapsing coordination failures between substrate and graphics suppliers.
Twist Wrap Packaging Market Segmentation
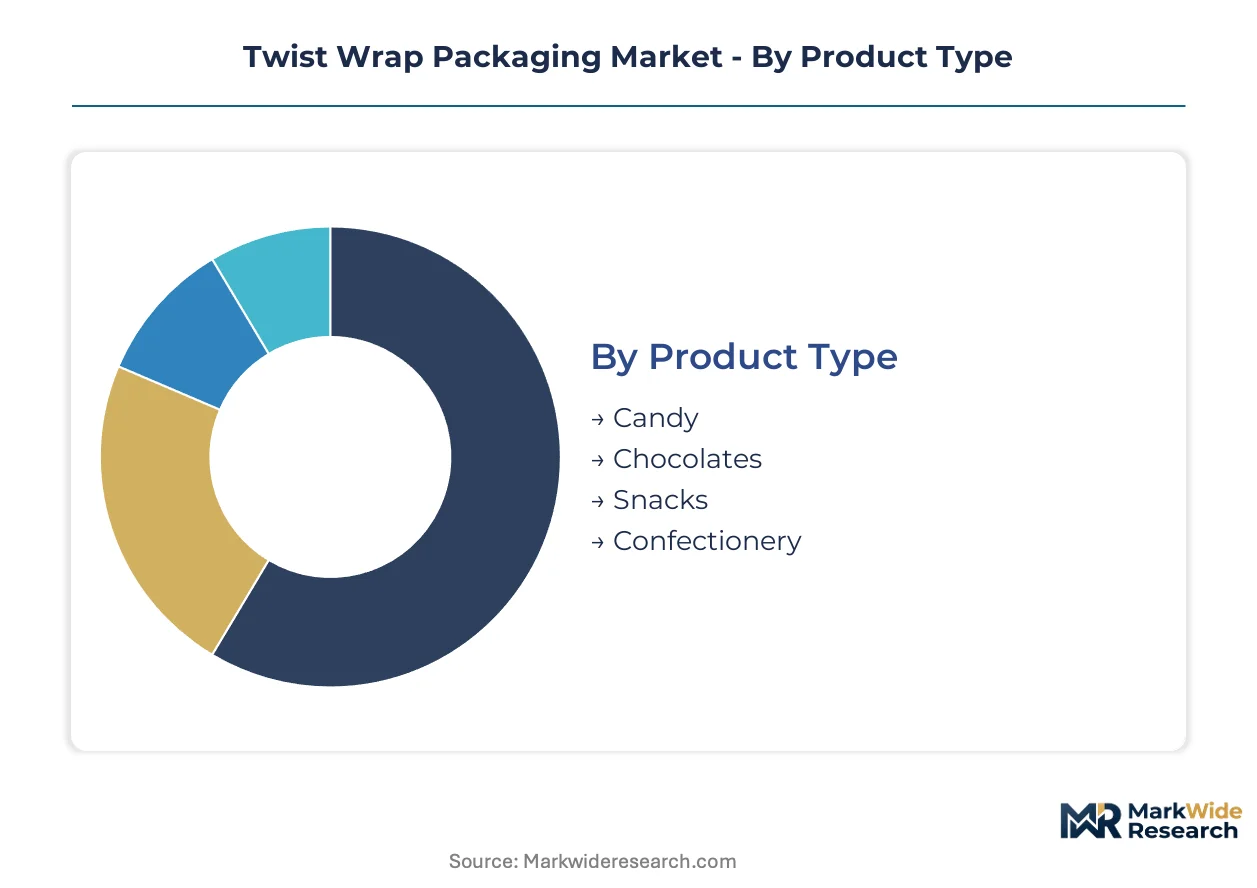
Twist wrap packaging procurement decisions hinge on barrier performance, sustainability certification, and machinery compatibility. Material selection directly determines seal integrity and shelf-life outcomes for moisture-sensitive confectionery. End-use applications impose distinct regulatory and aesthetic requirements that reshape converter specialization.
Product Type:
Brand owners prioritize portion control visibility and tamper-evidence when selecting formats for specific confectionery categories.
- Chocolates:Premium chocolate manufacturers in Germany and Switzerland specify 12-20 micron aluminum foil laminates where moisture vapor transmission rates below 0.1 g/m²/day protect cocoa butter integrity. Lindt and Ferrero procurement teams enforce ISO 18606 substrate certification for seasonal assortments distributed through Migros and Coop retail networks.
- Candy:Hard candy and chewy confectionery segments drive volume for oriented polypropylene twist wraps where clarity and twist retention matter more than absolute barrier performance. Halloween and Easter seasonal programs in North American retail channels concentrate demand for printed OPP formats with metallized decorative layers.
- Snacks:Nut and dried fruit portion packs adopt kraft-paper-based twist wraps for natural-positioned brands targeting zero-plastic claims. Seal strength limitations restrict high-speed line compatibility.
- Confectionery:Gummy and jellied sweets require grease-resistant coatings to prevent oil migration from filled centers. Bakery segment crossover applications expand addressable volume.
Volume sits with candy formats; growth tilts toward chocolate premiumization and biodegradable substrate transitions.
Material:
Regulatory pressure and retailer sustainability scorecards are restructuring converter material portfolios across European supply chains.
- Biodegradable Films:Cellulose-derived films certified to ASTM D6400 and EU 13432 standards are climbing the fastest as French and Belgian supermarket chains weight compostability above unit cost in private-label tenders. Huhtamaki and Mondi Group have anchored extrusion capacity around Nordic softwood pulp supply to secure feedstock continuity.
- Aluminum Foil:Established 12-30 micron foil laminates maintain premium positioning where barrier specifications exceed biodegradable alternatives. Swiss chocolate manufacturers sustain demand through Migros and Coop procurement mandates.
- Paper:Coated kraft papers integrate rotogravure printing for brand visibility in artisan confectionery segments. Integrated converters controlling both fiber sourcing and printing capture margin from coordination collapse.
- Plastic:Conventional oriented polypropylene faces EPR fee penalties under EU Packaging and Packaging Waste Regulation mandates. Legacy machinery tension settings optimized for 25-micron OPP require retrofit for alternative substrates.
Revenue concentrates in foil laminates; certification momentum favors biodegradable films.
End User:
Application-specific hygiene and regulatory requirements fragment converter qualification pathways.
- Food Industry:Confectionery and snack segments generate recurring volume with FDA food-contact substance notification requirements shaping coating formulation investments. ECHA REACH restrictions on phthalate plasticizers redirect heat-seal chemistry toward bio-based alternatives.
- Bakery:Portion-controlled cookies and pastries adopt twist-wrap formats for freshness preservation. French bakery chains are consolidating vendor relationships toward integrated converters.
- Cosmetics:Bath product and artisan soap brands in France and Italy pilot twist-wrap formats for sampler-sized amenity sizing, opening non-food volume expansion.
- Pharmaceuticals:OTC lozenge and supplement packaging requires child-resistant features and batch traceability that complicate standard twist-wrap mechanics.
Procurement scale favors food industry buyers; cosmetics applications expand most quickly.
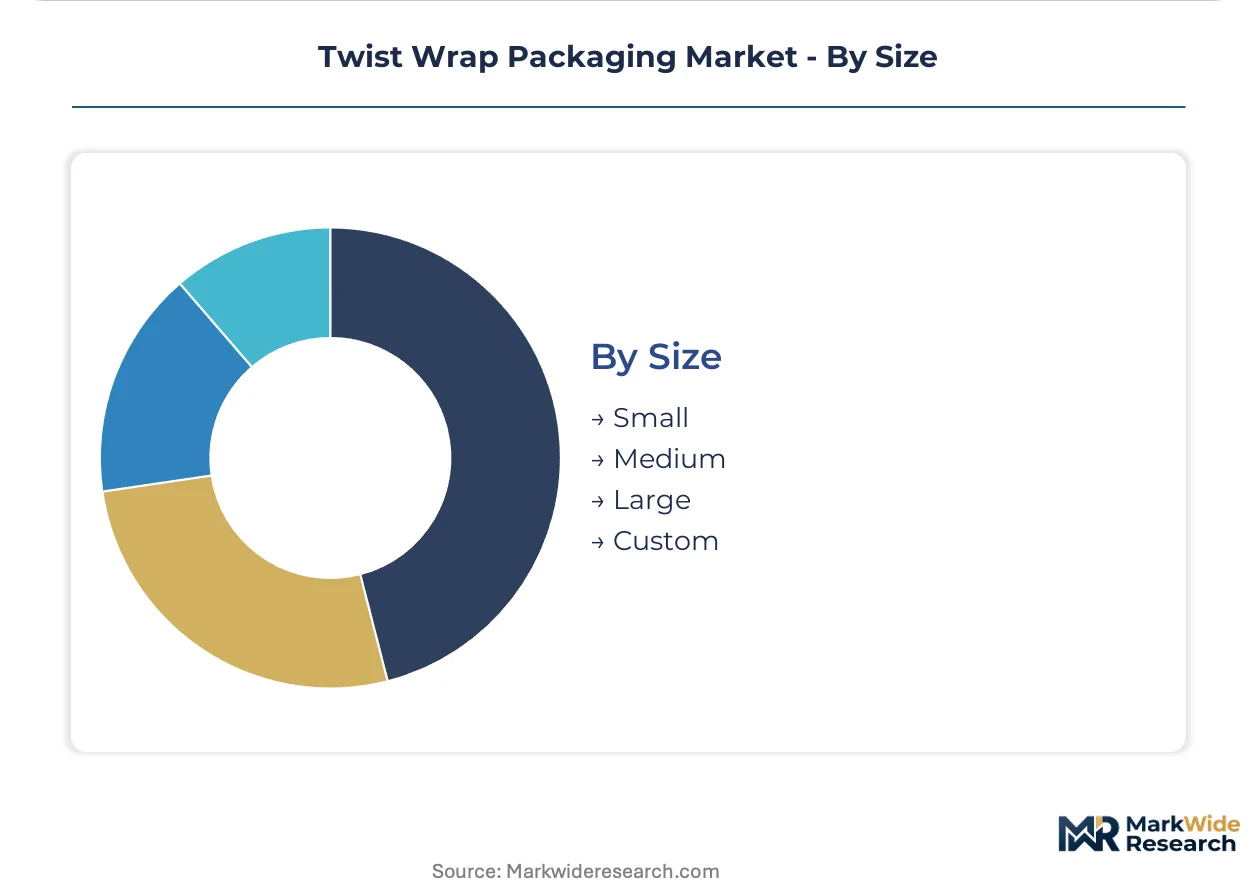
Size:
Order quantity economics and digital printing convergence reshape minimum viable production runs.
- Small:Single-serve portions for premium chocolate truffles and hotel amenity sizing command per-unit premiums. Swiss robotic twist-wrap systems handle placement precision at throughputs exceeding 400 pieces per minute.
- Custom:Hybrid flexo-inkjet systems enable short-run customization for seasonal launches, collapsing minimum order quantities and supporting regional brand differentiation.
- Medium:Standard retail multipack formats balance machinery efficiency with shelf-space optimization. German chocolate manufacturers cluster procurement around Cologne and Hamburg converters.
- Large:Bulk institutional and food-service formats prioritize unit cost over decorative printing. Barrier performance specifications relax relative to retail-facing formats.
Production volume centers on medium formats; customization demand climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones around Cologne and Hamburg anchor European converter concentration, while FDA food-contact zones in the US Midwest and Pearl River Delta manufacturing clusters in China concentrate machinery and film supply.
Germany
Lindt and Ferrero procurement teams drive premium chocolate twist-wrap demand with strict ISO 18606 substrate mandates. The EU Packaging and Packaging Waste Regulation forces accelerated biodegradable film transitions across North Rhine-Westphalia. Packaging converters cluster around Cologne and Hamburg, reconfiguring extrusion lines for certified cellulose films to serve Migros and Coop retail networks.
United States
Halloween and Easter seasonal programs concentrate demand for printed oriented polypropylene formats in Midwest confectionery manufacturing. FDA food-contact substance notifications shape coating formulation investments for heat-seal chemistry. Chicago-area converter operations supply national retail channels while facing ASTM D6400 certification gaps due to limited industrial composting infrastructure.
Switzerland
Premium truffle assortments sustain demand for 12-20 micron aluminum foil laminates where moisture vapor transmission specifications exceed biodegradable alternatives. Swissmedic and retailer sustainability scorecards from Migros and Coop enforce SQS-certified compostability preferences. Robotic twist-wrap system deployment around Zurich and Vevey automates placement precision at throughputs exceeding 400 pieces per minute.
France
French supermarket chains weight compostability certification above unit cost in private-label confectionery tenders, redirecting procurement toward EU 13432 certified substrates. ECHA REACH restrictions on phthalate plasticizers redirect heat-seal coating investments toward bio-based alternatives. Bakery segment buyers around Paris and Lyon consolidate vendor relationships toward integrated converters controlling both film extrusion and rotogravure printing.
Italy
Artisan soap and bath product brands pilot twist-wrap formats for sampler-sized amenity sizing, opening non-food volume expansion in cosmetics applications. The EU Green Deal packaging targets tighten recycled content thresholds for flexible packaging formats. Northern Italian converters around Milan and Bologna anchor digital printing convergence for short-run seasonal customization.
Twist Wrap Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated film extruders capturing margin from substrate-printing coordination while pure-play converters compete on machinery flexibility. The vendor base organizes around three archetypes: global film extruders with captive coating capacity, regional converters with digital print integration, and machinery specialists automating high-speed twist-wrap lines. Capacity expansion and strategic partnerships dominate competitive moves as EPR fee structures penalize non-certified substrates.
Within the integrated film extruder tier, Amcor plc and Mondi Group represent archetypes of backward integration into substrate supply, while Huhtamaki exemplifies specialized coating technology positioning. These three companies occupy distinct competitive positions based on geographic footprint and certification portfolio depth.
| Leading Market Players |
|---|
| Amcor plc |
| Huhtamaki |
| Berry Global Inc. |
| Mondi Group |
| Polysack Flexible Packaging Ltd. |
| Sunpack Corporation |
| UFlex Limited |
| Sonoco Products Company |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Nordic softwood pulp price indices transmit directly through kraft paper substrate costs, cascading into three-tier pricing structures that separate premium biodegradable films from standard aluminum foil laminates and economy-oriented plastic formats. Buyers in Germany and Switzerland absorb pulp volatility through long-term offtake contracts, while spot-market purchasers face margin compression during supply tightness.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to digital-printed seasonal formats where hybrid flexo-inkjet systems collapse production windows. Pricing stratifies across premium, standard, and economy tiers based on ISO 18606 certification grade and volume scale, with certified biodegradable films commanding sustainable procurement premiums. Cost compression in standard foil laminates is intensifying as EPR fee penalties widen cost differentials against certified alternatives. Private-label confectionery buyers at French supermarket chains exhibit highest price sensitivity, while Swiss premium chocolate manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Reverse logistics for post-consumer cellulose feedstock remains underdeveloped, constraining closed-loop material flows for biodegradable film converters. Raw material supply concentrates in Sweden, Finland, and Germany for Nordic softwood pulp, with aluminum foil sourcing anchored in Norway and Iceland. Converter operations draw from extrusion capacity clustered around Cologne, Hamburg, and Zurich, facing single-source vulnerability in certified heat-seal coating chemistry. Distribution runs through integrated converters controlling both substrate extrusion and rotogravure printing, collapsing coordination failures that plague fragmented supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable film extrusion technology is displacing conventional plastic laminate production, with cellulose-derived substrates replacing oriented polypropylene across European confectionery supply chains.
For Market Incumbents: Deploy captive fiber supply agreements to secure Nordic softwood pulp continuity against input volatility. Amcor plc and Mondi Group should accelerate ISCC PLUS mass-balance certification to defend procurement relationships with German chocolate manufacturers facing EU Packaging and Packaging Waste Regulation compliance deadlines. Backward integration into coating chemistry R&D addresses bio-based heat-seal performance gaps that threaten high-speed machinery compatibility. For New Entrants and Emerging Players: Capture cosmetics sampler applications in France and Italy where bath product brands pilot twist-wrap formats for portion-controlled amenity sizing. White-space exists in short-run digital printing for seasonal confectionery launches, where hybrid flexo-inkjet systems enable 50,000-unit minimums versus legacy 500,000-unit thresholds. Target integrated service models combining film extrusion with rotogravure graphics to displace fragmented supplier relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with stranded plastic-laminate capacity in North Rhine-Westphalia and verified ISO 18606 certification pipelines. Long-term viability hinges on 5-10 year regulatory compliance trajectories rather than near-term margin recovery. Monitor EU member state EPR fee implementation schedules as inflection indicators for accelerated substrate transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Certification | ISO 18606 and EU 13432 compliance unlocks Migros and Coop procurement channels. |
| Captive Pulp Supply Integration | Nordic softwood fiber control insulates margin from pulp price volatility swings. |
| Digital Print Capacity Addition | Hybrid flexo-inkjet systems collapse lead times for seasonal confectionery programs. |
| Robotic Twist-Wrap Automation | Vision-guided systems sustain 400-plus pieces per minute throughputs for premium truffles. |
| Cosmetics Segment Expansion | French and Italian bath product pilots open non-food volume diversification pathways. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with packaging converter plant managers, confectionery procurement leads at Lindt and Ferrero, retail category buyers at Migros and Coop, and technical R&D directors at film extrusion operations. Secondary sources included EU Packaging and Packaging Waste Regulation implementation documents, ECHA REACH restriction updates, FDA food-contact substance notifications, and Nordic pulp producer sustainability disclosures. Bottom-up volume estimates from machinery installation counts and substrate consumption patterns were triangulated against top-down market value reconstructions.
Data-stream reconciliation across production capacity databases, import-export statistics, and end-user procurement surveys shaped the analytical framework. Segmentation dimensions modeled included material substrate type, end-use application, geographic production cluster, and certification tier. CAGRs were derived from elasticity-adjusted demand projections and substitution rate assumptions for biodegradable formats. Industry-specific forecast inputs incorporated EU Green Deal packaging target timelines and retailer sustainability scorecard weightings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to composting infrastructure buildout rates and pulp price cycle amplitude. Practitioners should monitor EU member state EPR fee schedule announcements and ASTM D6400 industrial composting facility deployment for early signals of substrate transition acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Global Pre Zippered Pouches Market
Pouch
Russia Pouch Packaging Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Latin America Pouch Packaging Market
Pouch
Benelux Pouch Packaging Market
Pouch
UAE Pouch Packaging Market
Pouch
Global Pouches Packaging Market
Pouch
Feminine Care Pouch Film Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
High-Barrier Pouches Market
Pouch
Spout Pouch Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Ziplock Products Market
Pouch
Liquid Pouch Market
Pouch
Four Side Flat Pouch Market
Pouch
Flexible Plastic Drinking Pouch Market