
 Dual-Chamber Pouches Market | 2026-2036
Dual-Chamber Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Dual-Chamber Pouches Market Analytics
EU REACH compliance is recalibrating the cost-of-entry calculus for European converters. Amcor plc leverages its integrated film extrusion network to manage substance-of-very-high-concern documentation across multi-layer structures. Mondi plc sustains competitive positioning through kraft-paper hybrid R&D aligned with single-use plastic directives. Berry Global Group, Inc. anchors North American supply with blown film capacity optimized for pharmaceutical barrier specifications.
Dual-chamber pouches are flexible packaging constructs that integrate two discrete compartments within a single sealed envelope, typically employing coextruded polyethylene terephthalate or ethylene vinyl alcohol barrier layers to maintain active ingredient stability. They serve primarily to isolate reactive components—such as pharmaceutical powders and sterile diluents—until the moment of mixing and administration. Stand-up pouches command the largest volume share among product types due to shelf presence and dispensing ergonomics in retail pharmacy settings. Metalized film substrates represent the fastest-expanding material category as brand owners pursue oxygen transmission rates below 0.1 cc per square meter per day for biologic drug protection.
FDA 21 CFR Part 211, EU MDR Annex I, and ISO 11607-1 collectively govern sterile barrier performance, extractables testing, and shelf-life validation for pharmaceutical dual-chamber applications. These frameworks compel converters to maintain dedicated cleanroom manufacturing lanes and batch-level traceability systems that smaller regional competitors cannot replicate. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions that threaten existing high-barrier fluoropolymer coatings without proven alternatives at equivalent performance thresholds.
Market Dynamics
EU REACH substance-of-very-high-concern documentation requirements are forcing converters to restructure multi-layer film supply chains, compressing margins for smaller regional players while advantaging integrated manufacturers with captive extrusion networks and dedicated regulatory affairs teams.
Growth Catalysts
- Biologics formulation expansion:Moisture-sensitive monoclonal antibodies and lyophilized vaccines require oxygen transmission rates below 0.1 cc per square meter per day, driving specification upgrades across sterile barrier portfolios.
- German contract packaging capacity:Third-party logistics providers in Baden-Württemberg and Bavaria are installing dedicated cleanroom lanes for dual-chamber pouch assembly, reducing time-to-market for mid-size pharmaceutical developers.
- ISO 11607-1 validation protocols:Harmonized shelf-life testing standards across EU member states are reducing redundant certification costs for cross-border pharmaceutical distribution.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Three Japanese and Korean petrochemical suppliers control over 70% of pharmaceutical-grade EVOH supply, exposing converters to input volatility and allocation risk during polymer production outages.
- Fluoropolymer coating substitution gap:EPA per- and polyfluoroalkyl substance restrictions threaten existing high-barrier coatings without proven alternatives achieving equivalent oxygen and moisture vapor transmission performance.
- Cleanroom capex thresholds:Dedicated ISO Class 7 manufacturing lanes require 15-20 million euro facility investments, excluding regional converters from sterile pharmaceutical contracts.
Strategic Opportunities
- Indian CDMO penetration:Contract development and manufacturing organizations in Hyderabad and Bangalore are expanding biologics fill-finish capacity, creating demand for imported high-barrier pouch formats compliant with CDSCO packaging guidelines.
- Metalized film substrate convergence:Vacuum-deposited aluminum oxide coatings combined with polyethylene terephthalate base layers are enabling thinner gauge structures with equivalent barrier performance, reducing material intensity per unit.
- EU Green Deal circularity mandates:The Packaging and Packaging Waste Regulation's material recovery targets are accelerating R&D investment in mono-material dual-chamber constructs compatible with existing polyethylene recycling streams.
Industry Challenges
- Extractables testing expertise scarcity:Pharmaceutical sponsors now require comprehensive migration studies for 50+ chemical entities per pouch configuration, overwhelming analytical chemistry capacity at mid-size converter laboratories.
- Batch-level traceability system integration:EU MDR Annex I unique device identification requirements are forcing legacy ERP upgrades and serialization infrastructure investments across European supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual-Chamber Pouches Market |
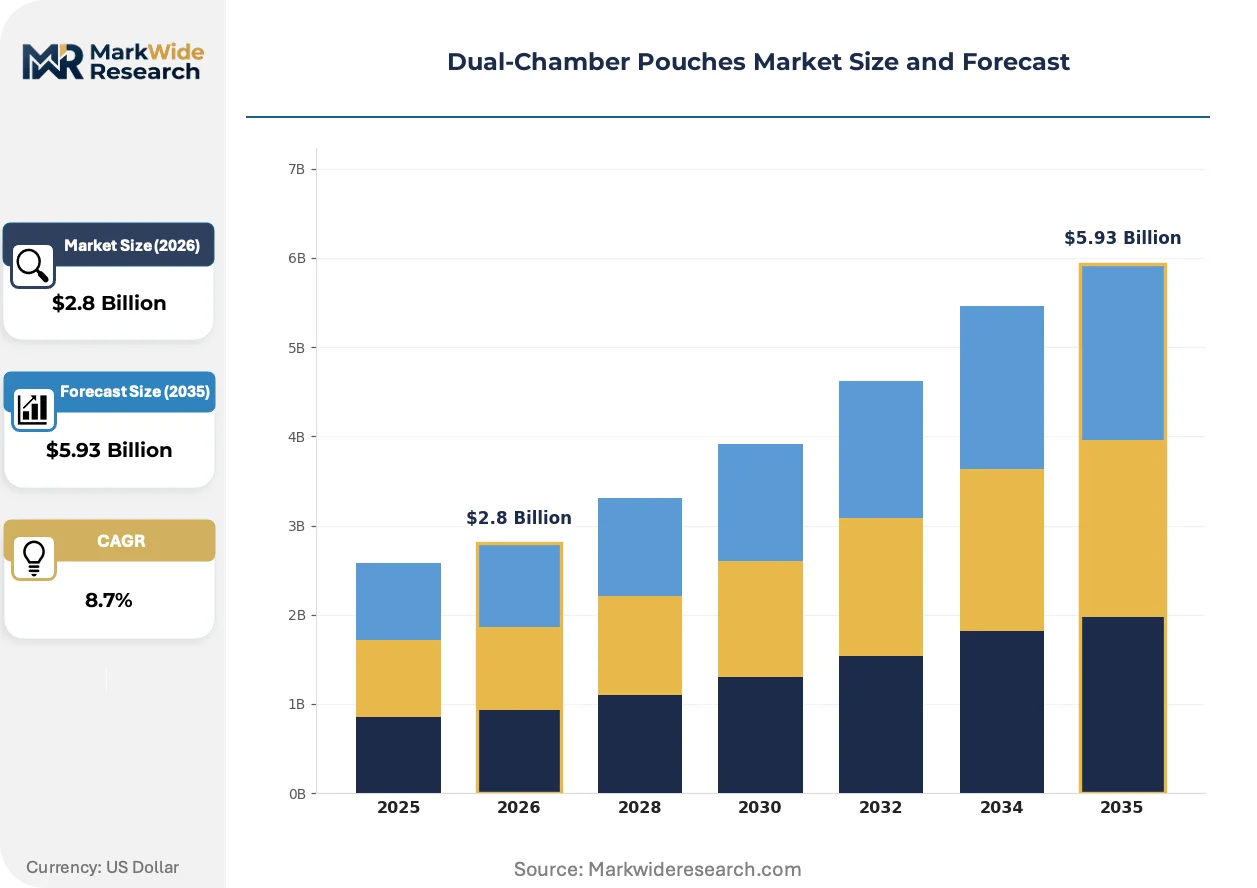
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Pouches, Rigid Pouches, Stand-Up Pouches, Flat Pouches Material: Plastic, Metalized Film, Aluminum, Paper End User: Pharmaceuticals, Food & Beverages, Personal Care, Chemicals Application: Packaging, Storage, Distribution, Dispensing |
| Companies Covered | Amcor plc, Mondi plc, ProAmpac, Huhtamaki, Berry Global Group, Inc., Smurfit Kappa Group plc, Sonoco Products Company, Sealed Air Corporation, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual-Chamber Pouches Market Evolving Landscape
Laser scoring and precision die-cutting technologies are automating pouch separation mechanics, while regulatory pressure on fluorinated chemistries accelerates barrier coating R&D. Demand-side consolidation among pharmaceutical contract manufacturers is reshaping procurement specifications.
Inline laser perforation systems are automating the controlled breach of frangible seals between dual chambers, enabling consistent mixing force thresholds without manual tear-initiation variability. Large molecule drug sponsors in Germany and Switzerland are specifying these systems for patient-administered emergency medications. The technology is automating quality assurance by reducing seal-failure rates from 3-5% to below 0.5% in validated production runs.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon propellants and process agents is restricting fluoropolymer coating manufacturing methods used for ultra-high barrier applications. Converters with integrated film extrusion capabilities are accelerating plasma-enhanced chemical vapor deposition alternatives. Metalized film substrates for biologic drug protection are experiencing the most acute specification pressure as coating suppliers reformulate.
Pharmaceutical procurement teams are consolidating supplier panels from 8-12 regional converters to 3-4 strategic partners with integrated regulatory documentation capabilities. This behavior shift is compressing quoting cycles and elevating batch consistency requirements. The pattern is most visible in German and Swiss markets where biologics developers prioritize supply security over unit cost minimization.
Dual-Chamber Pouches Market Segmentation
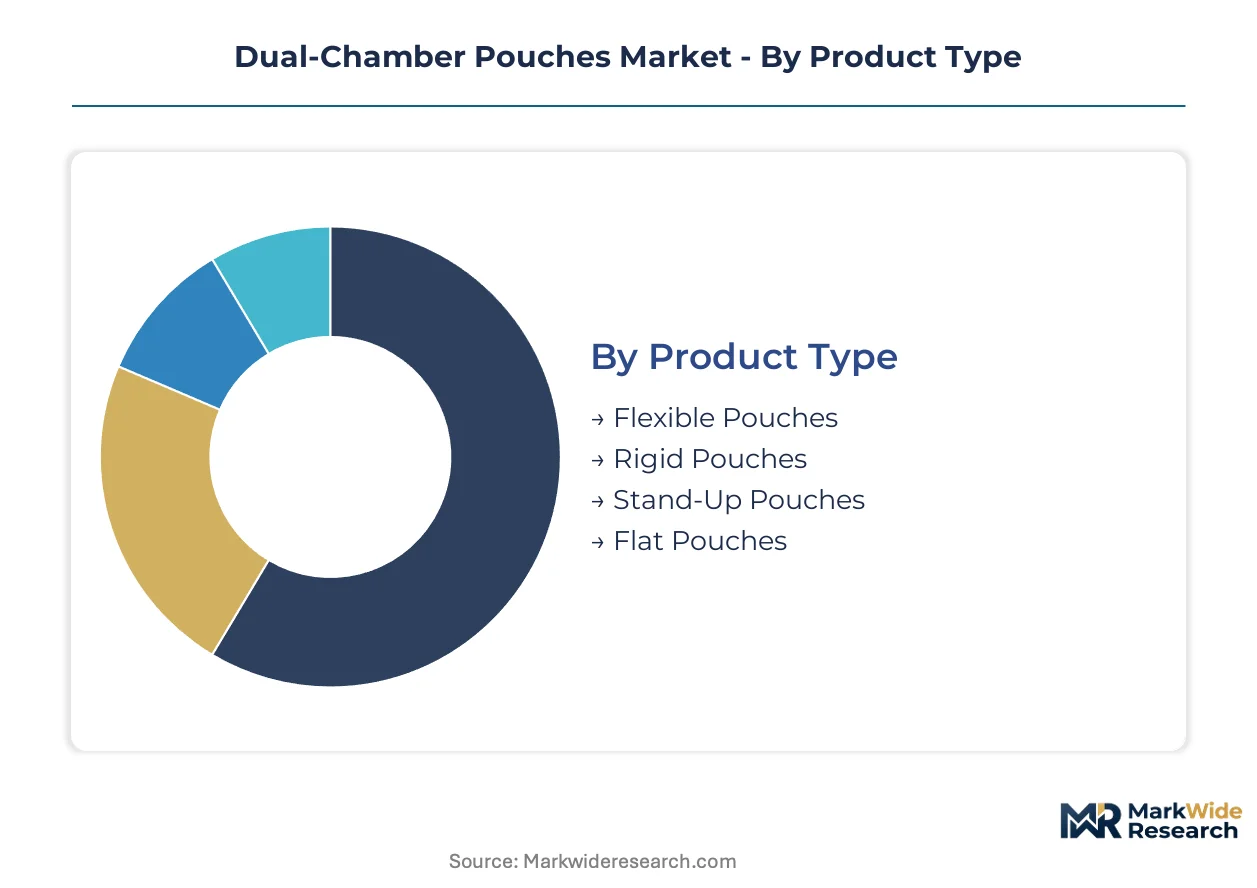
Segmentation in dual-chamber pouches reflects divergent technical requirements across sterile pharmaceutical applications versus consumer goods. Product architecture, barrier material selection, and end-use compliance obligations create distinct procurement specifications that reshape converter specialization strategies.
Product Type:
Customization intensity varies sharply across this category, with sterile pharmaceutical formats demanding validated cleanroom production while consumer formats prioritize throughput economics.
- Stand-Up Pouches:These formats incorporate gusseted bases and ergonomic dispensing geometries optimized for retail pharmacy shelf presence. German and Swiss biologics developers specify these configurations for patient-administered emergency medications requiring intuitive handling protocols.
- Flexible Pouches:Coextruded multi-layer envelopes with ethylene vinyl alcohol or polyethylene terephthalate barrier films dominate moisture-sensitive pharmaceutical applications. Demand concentrates among monoclonal antibody formulators requiring oxygen transmission rates below 0.1 cc per square meter per day.
- Rigid Pouches:Semi-structural formats with laminated board or thermoformed inserts suit chemical reagent kits requiring dimensional stability during transport.
- Flat Pouches:Two-dimensional sealed envelopes minimize material intensity for single-use diagnostic applications with short shelf-life requirements.
Leading the category by volume: Stand-Up Pouches. Growing fastest: Flexible Pouches.
Material:
Cost tier stratification separates premium barrier substrates from commodity alternatives, with pharmaceutical-grade specifications commanding 3-4x material cost multiples.
- Metalized Film:Vacuum-deposited aluminum oxide on polyethylene terephthalate base layers achieves ultra-low oxygen transmission without fluoropolymer coatings threatened by EPA restrictions. CDSCO-registered Indian CDMOs are importing these substrates for biologics fill-finish expansion.
- Plastic:Coextruded polyethylene and polypropylene structures with EVOH interlayers serve high-volume pharmaceutical applications where barrier performance must balance against recyclability mandates under EU Packaging and Packaging Waste Regulation.
- Aluminum:Foil laminates deliver absolute moisture and gas barrier for lyophilized vaccine components with multi-year stability requirements.
- Paper:Kraft-paper hybrid formats align with single-use plastic directives in European consumer segments, though pharmaceutical adoption remains limited by sterile barrier validation constraints.
Highest volume share: Plastic substrates. Steepest specification pressure: Metalized Film.
End User:
Application maturity separates regulated pharmaceutical segments with decade-long validation cycles from fast-turn consumer goods procurement.
- Pharmaceuticals:Sterile barrier systems governed by FDA 21 CFR Part 211, EU MDR Annex I, and ISO 11607-1 require dedicated cleanroom lanes and batch-level traceability. German contract packaging capacity in Baden-Württemberg and Bavaria is expanding assembly lines for these specifications.
- Food & Beverages:Oxygen-sensitive ingredients such as probiotic cultures and antioxidant formulations drive dual-chamber adoption for component isolation prior to consumption.
- Personal Care:Cosmetic active ingredients requiring protection from moisture and oxidation utilize pouch formats for premium positioning in retail channels.
- Chemicals:Two-part adhesive and coating systems employ industrial-grade dual-chamber formats with frangible seal technologies for field mixing applications.
Dominant procurement volume: Pharmaceuticals. Emerging specification intensity: Food & Beverages.
Application:
Supply concentration clusters around packaging functions, with downstream applications fragmenting across specialized logistics and patient-interface requirements.
- Packaging:Primary sterile barrier formation represents the core value-add function, with laser scoring and precision die-cutting technologies automating chamber separation mechanics for consistent mixing force thresholds.
- Storage:Extended stability requirements for biologics drive specification of metalized and aluminum substrates with validated shelf-life protocols.
- Distribution:Cold-chain compatibility and physical durability requirements shape material selection for cross-border pharmaceutical logistics.
- Dispensing:Patient-administered applications demand ergonomic tear-initiation and controlled flow geometries, particularly in emergency medication segments.
Core revenue concentration: Packaging. Fastest functional expansion: Dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's tax-advantaged innovation zones concentrate contract packaging investment for biologics. German and Swiss cleanroom infrastructure expansion anchors European sterile barrier capacity. Indian CDMO clusters in Hyderabad and Bangalore drive import demand for high-barrier substrates.
Germany
Monoclonal antibody formulators in Baden-Württemberg and Bavaria specify oxygen transmission rates below 0.1 cc per square meter per day for moisture-sensitive biologics. The EU Packaging and Packaging Waste Regulation tightens material recovery requirements across pharmaceutical supply chains. Third-party logistics providers in Stuttgart and Munich are installing dedicated ISO Class 7 cleanroom lanes for dual-chamber pouch assembly.
United States
FDA 21 CFR Part 211 compliance drives specification upgrades for sterile barrier validation and extractables testing protocols. EPA per- and polyfluoroalkyl substance restrictions threaten existing fluoropolymer coatings without proven alternatives. Blown film capacity in the Midwest anchors North American pharmaceutical barrier substrate supply.
India
CDSCO packaging guidelines govern biologics fill-finish expansion among contract development and manufacturing organizations. The Production Linked Incentive scheme accelerates domestic pharmaceutical manufacturing capacity. Hyderabad and Bangalore clusters are importing metalized film substrates for monoclonal antibody packaging.
Switzerland
Swissmedic regulations enforce batch-level traceability systems for sterile pharmaceutical packaging. Patient-administered emergency medication developers specify laser-scored pouch formats with consistent mixing force thresholds. Basel-area biologics sponsors prioritize supply security over unit cost minimization in procurement decisions.
Japan
PMDA guidelines align with ISO 11607-1 shelf-life validation protocols for cross-border distribution. Three Japanese petrochemical suppliers control over 70% of pharmaceutical-grade ethylene vinyl alcohol resin supply. Tokyo-Osaka pharmaceutical corridors face input volatility risks during polymer production outages.
Dual-Chamber Pouches Market Competitive Landscape
North American producers anchor one tier; European specialists hold integrated regulatory documentation capabilities. The vendor base separates into consolidated integrated manufacturers with captive extrusion networks and fragmented regional converters lacking cleanroom infrastructure. Three strategic archetypes dominate: integrated film extrusion operators, kraft-paper hybrid innovators, and blown film capacity holders. Competitive moves concentrate on M&A for regulatory affairs teams and geographic expansion into Indian CDMO supply chains.
Among integrated packaging multinationals, Amcor plc, Mondi plc, and Berry Global Group, Inc. exemplify divergent strategic positioning within the sterile barrier segment. Amcor plc represents the integrated film extrusion archetype with multi-layer structure capabilities. Mondi plc occupies a position within kraft-paper hybrid research aligned with single-use plastic directives. Berry Global Group, Inc. anchors the North American supply position through blown film capacity optimization. These three entities collectively illustrate how regulatory compliance scale separates strategic suppliers from excluded regional competitors.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi plc |
| ProAmpac |
| Huhtamaki |
| Berry Global Group, Inc. |
| Smurfit Kappa Group plc |
| Sonoco Products Company |
| Sealed Air Corporation |
| Constantia Flexibles |
| Others |
Value Network & Pricing Analysis
Plasma-enhanced chemical vapor deposition adoption for fluoropolymer-free barrier coatings is simultaneously elevating capital intensity for integrated converters and compressing margins for regional competitors lacking in-house film extrusion capabilities. This production-method transition concentrates pricing power with manufacturers possessing captive regulatory documentation teams while forcing smaller players toward contract tolling arrangements.
Pricing Analysis
Short lead-time premiums of 15-25% apply to validated sterile barrier orders from German biologics developers requiring ISO Class 7 cleanroom capacity within 6-8 weeks. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade metalized film specifications from industrial chemical formats. Pricing pressure stems from EVOH resin allocation constraints controlled by Japanese and Korean petrochemical suppliers. Mid-size pharmaceutical sponsors exhibit highest price sensitivity, while Swiss emergency medication developers prioritize supply security over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's Production Linked Incentive scheme are reshaping sourcing patterns for CDSCO-registered contract manufacturers in Hyderabad and Bangalore. Supply concentrates in Germany, Switzerland, and Japan for pharmaceutical-grade cleanroom assembly, with raw material dependencies on EVOH resin, vacuum-deposited aluminum oxide substrates, and fluoropolymer coating alternatives. Single-source vulnerability persists for pharmaceutical-grade EVOH following polymer production outages. Distribution runs through third-party logistics providers with dedicated pharmaceutical cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over captive film extrusion networks and regulatory affairs capacity determines competitive survival. Players are pursuing backward integration into multi-layer barrier substrate production to escape EVOH supplier concentration risks.
For Market Incumbents: Anticipate procurement panel consolidation among German and Swiss biologics sponsors by pre-positioning integrated regulatory documentation capabilities for EU MDR Annex I compliance. Defend market position through dedicated cleanroom capacity expansion in Baden-Württemberg tax-advantaged innovation zones. Prioritize plasma-enhanced chemical vapor deposition R&D investment to offset EPA fluoropolymer coating restrictions. For New Entrants and Emerging Players: Contract development and manufacturing organizations in Indian pharmaceutical clusters represent the most penetrable buyer segment given biologics fill-finish capacity expansion and imported substrate dependency. Target CDSCO-registered facilities in Hyderabad and Bangalore with metalized film substrate offerings compliant with packaging guidelines. Pursue technical partnership positioning with established European converters lacking Indian market presence. For Investors and Strategic Acquirers: Re-rating potential sits with integrated film extrusion operators given EU REACH substance-of-very-high-concern documentation requirements and procurement panel consolidation trends. Long-term viability over the next decade favors manufacturers with captive EVOH compounding relationships and cleanroom infrastructure. Monitor Indian PLI scheme disbursement velocity as inflection indicator for CDMO demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive EVOH compounding capacity insulates against Japanese and Korean supplier allocation risks. |
| Cleanroom Capacity Expansion | ISO Class 7 lanes in Baden-Württemberg secure German biologics contract packaging contracts. |
| Regulatory Documentation Investment | EU REACH SVHC compliance teams enable procurement panel retention amid sponsor consolidation. |
| Barrier Coating R&D Partnership | Plasma-enhanced chemical vapor deposition development addresses EPA fluoropolymer restrictions. |
| Indian CDMO Supply Chain Entry | CDSCO-compliant substrate offerings capture Hyderabad and Bangalore biologics fill-finish demand. |
Research Methodology
Multi-period observation of cleanroom capacity installation rates, EVOH resin pricing volatility, and pharmaceutical procurement panel consolidation anchored the trend analysis, supplemented by interviews with contract packaging operations directors, regulatory affairs leads at dual-chamber pouch converters, biologics supply chain managers, and CDSCO compliance officers. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EU MDR Annex I technical documentation requirements, ISO 11607-1 shelf-life validation protocols, ECHA SVHC candidate list updates, and customs trade data for pharmaceutical-grade barrier film imports. Bottom-up facility capacity modeling and top-down pharmaceutical packaging spend estimates were triangulated against primary interview findings.
Input-output matrices structured the analytical framework across product type, material substrate, end-user application, and regional regulatory cluster dimensions over the projection horizon. CAGRs were derived from segmented demand elasticity modeling calibrated to pharmaceutical biologics formulation expansion rates and sterile barrier specification upgrade patterns. Industry-specific forecast inputs included monoclonal antibody pipeline advancement data and EU Packaging and Packaging Waste Regulation material recovery target implementation timelines.
Several conditions sit outside the modeled scope, including unforeseen EPA fluoropolymer coating ban acceleration, catastrophic EVOH supply disruption from East Asian petrochemical facility incidents, and radical shifts in pharmaceutical cold-chain logistics economics. Forecasts reflect documented assumptions regarding regulatory implementation pacing and polymer supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Recyclable PE Pouch Market
Pouch
China Pouch Packaging Market
Pouch
Bio PE Pouches Market
Pouch
Child Resistant Pouches Market
Pouch
Open Mouth Sacks Market
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Ziplock Products Market
Pouch
Thailand Pouch Packaging Market
Pouch
Stand-Up Pouches Market
Pouch
Argentina Pouch Packaging Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Digital Printed Pouch Market
Pouch
2 Seal Pouches Market
Pouch
Global Boil-In Bags Market
Pouch
Feminine Care Pouch Film Market
Pouch
Inverted Pouch Market