
 South Africa Pouch Packaging Market | 2026-2036
South Africa Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Pouch Packaging Market Insights
SANS 10329 certification for flexible packaging materials is collapsing the supplier base as smaller converters fail retesting cycles. Amcor Group GmbH leverages its integrated film extrusion and print capabilities to sustain compliance leadership across pharmaceutical-grade barrier formats. Mondi Group anchors regional supply through its Richards Bay kraft paper integration, while Mpact Limited competes aggressively in recycled-content polyethylene structures for FMCG clients.
Pouch packaging denotes a flexible container format constructed from mono- or multi-layer substrates with sealed edges and optional resealable features, typically ranging from 50 microns to 250 microns in total caliper depending on barrier requirements. The format serves primary functions of product containment, shelf-life extension through oxygen and moisture barriers, and retail shelf differentiation via high-definition gravure or flexographic decoration. Stand-up pouches dominate value capture due to superior shelf presence and material efficiency versus rigid alternatives, while zipper closure types expand fastest as brand owners prioritize consumer convenience and portion control. Composite material structures concentrate margin pools where ethylene vinyl alcohol and metallized polyethylene terephthalate laminations command premiums for oxygen-sensitive food and pharmaceutical applications.
The National Regulator for Compulsory Specifications mandates SANS compliance for food-contact materials, while the Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that shift recycling accountability upstream to converters. The South African Health Products Regulatory Authority governs pharmaceutical pouch barrier specifications for moisture and light protection. Stakeholders must monitor pending amendments to extended producer responsibility targets and pre-emptively redesign material specifications to maintain market access as compliance thresholds tighten.
Market Dynamics
SANS 10329 certification requirements are collapsing the supplier base as smaller converters fail retesting cycles, concentrating supply among integrated film extrusion and print operations that can sustain compliance investments across pharmaceutical-grade barrier formats.
Growth Catalysts
- Extended Producer Responsibility Mandates:The Department of Forestry, Fisheries and the Environment enforces recycling accountability upstream to converters, accelerating redesign of material specifications toward mono-material structures that simplify end-of-life processing.
- Ready-to-Eat Meal Proliferation:Food and beverage manufacturers in the Johannesburg-Pretoria corridor are expanding pouch adoption for shelf-stable sauces and prepared meals, pulling demand for high-barrier metallized polyethylene terephthalate laminations.
- Zipper Closure Technology:Brand owners prioritize resealable features for portion control and consumer convenience, driving fastest expansion in zipper-equipped stand-up pouches across Gauteng province's densest converting operations.
Market Restraints
- Ethylene Vinyl Alcohol Input Volatility:Oxygen-sensitive food and pharmaceutical applications depend on EVOH barrier layers subject to petrochemical feedstock price swings that compress converter margins unpredictably.
- Richards Bay Kraft Paper Concentration:Regional supply anchors through limited kraft paper integration points create vulnerability to pulp cost shocks and logistics bottlenecks for paper-based pouch substrates.
- Rigid Container Substitution:Glass and metal cans retain preference for premium spirits and infant nutrition where perceived barrier superiority outweighs material efficiency advantages of flexible formats.
Strategic Opportunities
- Western Cape Wine Export Corridor:Underpenetrated pouch adoption for single-serve wine and spirits presents white space as export-oriented producers seek lightweight alternatives to glass for air freight efficiency.
- Digital Printing Convergence:Integration of high-definition gravure with short-run digital decoration enables mass customization for seasonal FMCG promotions without plate changeover costs.
- Pharmaceutical Barrier Specification Expansion:The South African Health Products Regulatory Authority's moisture and light protection mandates for drug delivery pouches create premium margin pools for certified converters.
Industry Challenges
- SANS Retesting Cycle Compression:Smaller converters face 18-month certification renewal timelines that demand dedicated quality personnel and laboratory investments many cannot sustain.
- Multi-Layer Structure Delamination:Recycling infrastructure struggles with composite material separation, forcing converters to balance barrier performance against mono-material redesign complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Pouch Packaging Market |
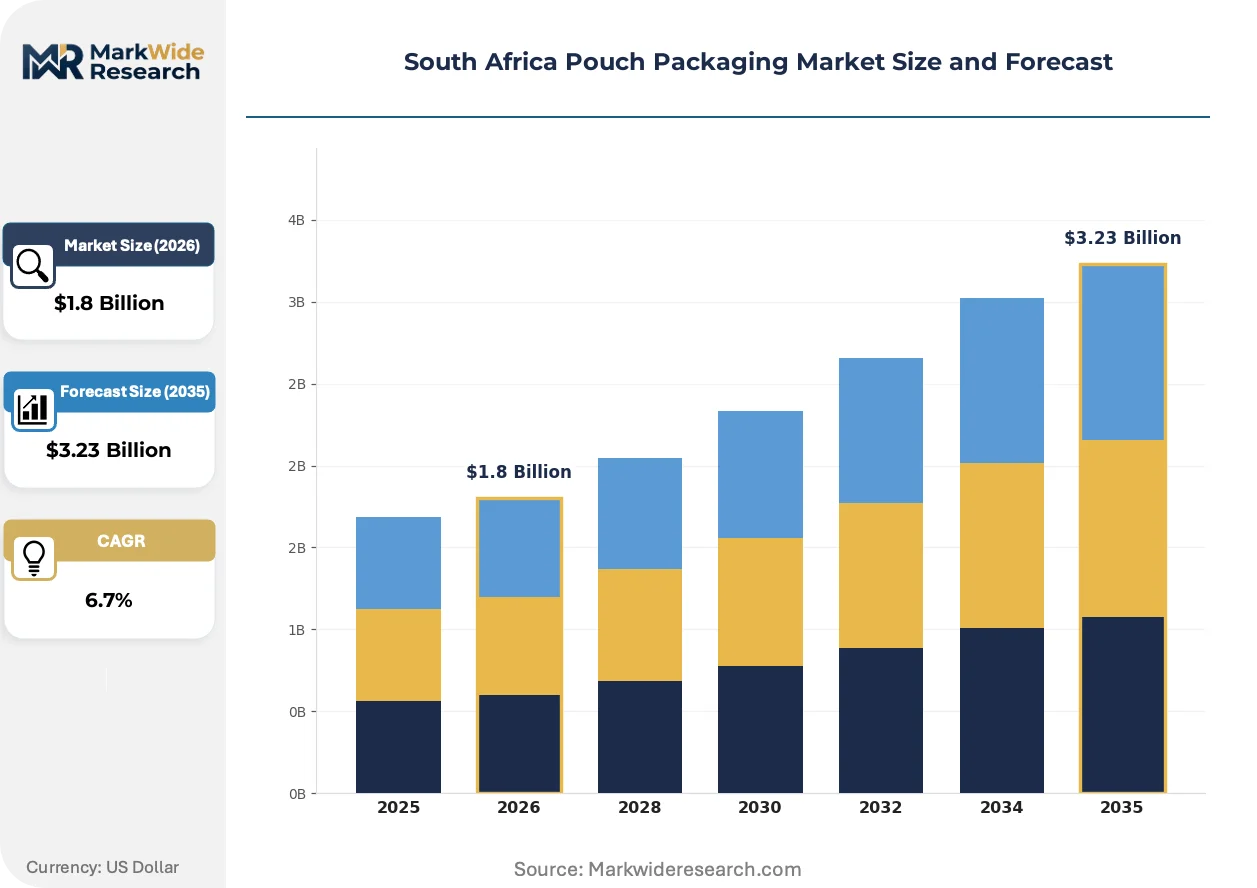
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Aluminum, Composite Pouch Type: Stand-Up Pouches, Flat Pouches, Side Gusset Pouches, Quad Seal Pouches Closure Type: Zipper, Spout, Resealable, Heat Seal End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products |
| Companies Covered | Amcor Group GmbH, Huhtamaki Oyj, Trempak Trading Pty Ltd, APAC Enterprises, Constantia Afripack Flexibles, Mondi Group, Mpact Limited, Nampak Ltd, Polyoak Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Pouch Packaging Market Trends and Innovations
Active reshaping of the South Africa pouch packaging market centers on material science breakthroughs, regulatory compliance automation, and procurement model compression that favors integrated suppliers over fragmented converters.
Mono-material polyethylene structures are decomposing traditional multi-layer laminations by simplifying recycling streams without sacrificing seal integrity. Retailers and brand owners in the FMCG sector are accelerating specification shifts toward these substrates. The structural consequence is margin compression for converters dependent on complex barrier film imports that face extended producer responsibility penalties.
The National Regulator for Compulsory Specifications enforces escalating SANS 10329 retesting frequencies that demand automated quality management systems. Industrial consequence includes elimination of manual inspection-dependent operations and capital migration toward spectroscopy-equipped production lines. Pharmaceutical and food-contact segments are responding by consolidating supplier relationships with integrated extrusion-to-print operations that can document continuous compliance.
Buyer concentration among Gauteng-based retail chains is compressing supplier negotiation cycles from annual to quarterly review. National supermarket procurement teams now mandate recycled-content thresholds and certified barrier documentation as table stakes. This pattern is most visible in Johannesburg-Pretoria industrial corridors where filling operations have reduced active converter relationships by half over three contract cycles.
South Africa Pouch Packaging Market Segmentation
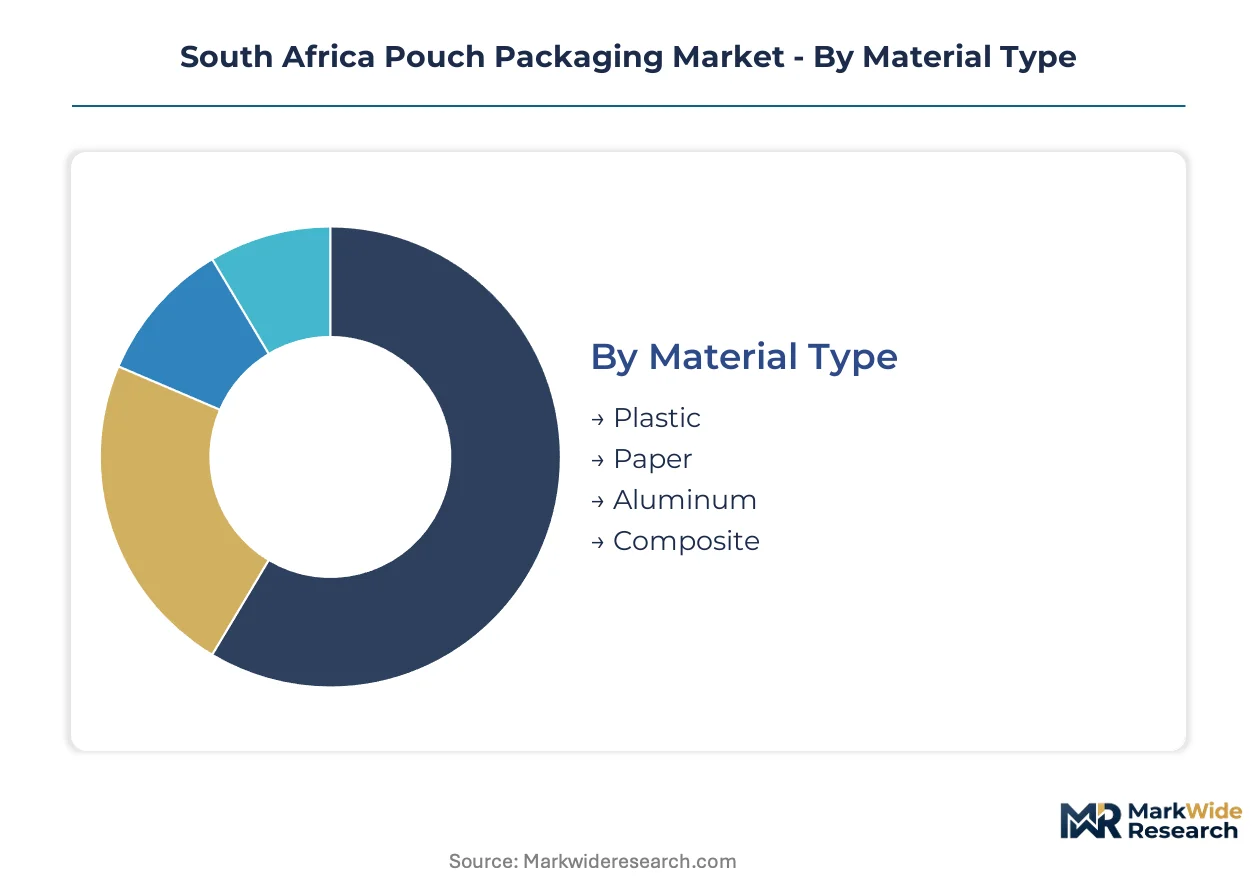
Pouch packaging specifications in South Africa diverge sharply across material substrates and functional formats, with Gauteng-based retail chains and Johannesburg-Pretoria filling operations driving consolidation toward high-barrier, resealable configurations. Channel mix determines margin capture, as pharmaceutical and premium food segments route through certified converters while mass-market FMCG flows through high-volume, price-sensitive procurement.
Material Type:
Channel mix splits by barrier requirement: composite and aluminum structures flow through pharmaceutical and export food channels demanding SANS 10329 documentation, while plastic and paper variants dominate domestic retail shelf-stable segments.
- Plastic:Polyethylene and polypropylene mono-material structures are displacing multi-layer laminations under extended producer responsibility mandates. Demand concentrates in Gauteng FMCG operations where retailers now mandate recycled-content thresholds as table stakes for supplier qualification.
- Composite:Ethylene vinyl alcohol and metallized polyethylene terephthalate laminations deliver oxygen barriers below 0.1 cc/m²/day for shelf-stable sauces and ready-to-eat meals. The Johannesburg-Pretoria corridor pulls disproportionate volume as food manufacturers expand retort pouch adoption.
- Paper:Mondi Group's Richards Bay kraft paper integration anchors regional supply for dry food and confectionery applications facing logistics cost pressure.
- Aluminum:Foil laminations serve pharmaceutical moisture-barrier specifications under South African Health Products Regulatory Authority mandates.
Plastic dominates installed base. Composite is where expansion concentrates.
Pouch Type:
Cost tier stratification separates premium shelf-presence formats from economy flat configurations, with stand-up and quad seal pouches commanding 40-60% material efficiency premiums over rigid alternatives.
- Stand-Up Pouches:Doyen-style bottom gusset construction enables vertical shelf display with total caliper ranging 80-200 microns depending on barrier specification. Brand owners in the Johannesburg-Pretoria corridor prioritize this format for retail differentiation and reduced shelf-space cost per unit volume.
- Flat Pouches:Three-side-seal construction minimizes material usage for single-serve condiments and sample portions. Volume concentrates in high-speed filling operations serving mass-market retail chains with quarterly procurement review cycles.
- Side Gusset Pouches:Traditional coffee and dry goods format retains share in legacy equipment bases.
- Quad Seal Pouches:Four-corner seal geometry maximizes pallet density for bulk dry ingredients and pet food applications.
Stand-up pouches dominate installed base. Quad seal configurations are climbing the fastest as pallet efficiency drives logistics cost reduction.
Closure Type:
Application context dictates closure selection: zipper and spout technologies expand in convenience-oriented consumer segments, while heat seal retains dominance in institutional and single-use pharmaceutical applications.
- Zipper:Interlocking polyethylene track systems enable repeated opening for portion control in snack and prepared meal segments. Demand accelerates across Gauteng province as national supermarket procurement teams mandate resealable features for private-label expansion.
- Spout:Injection-molded fitment integration supports controlled dispensing for beverages, sauces, and liquid detergents. Western Cape wine export corridor presents underpenetrated white space for single-serve alcohol alternatives to glass.
- Resealable:Adhesive strip systems serve lower-cost applications where zipper capital investment is uneconomical.
- Heat Seal:Permanent fusion closure remains mandatory for sterile pharmaceutical barrier integrity and tamper-evident food requirements.
Heat seal dominates installed base. Zipper is gaining share fastest as convenience specifications tighten across retail procurement.
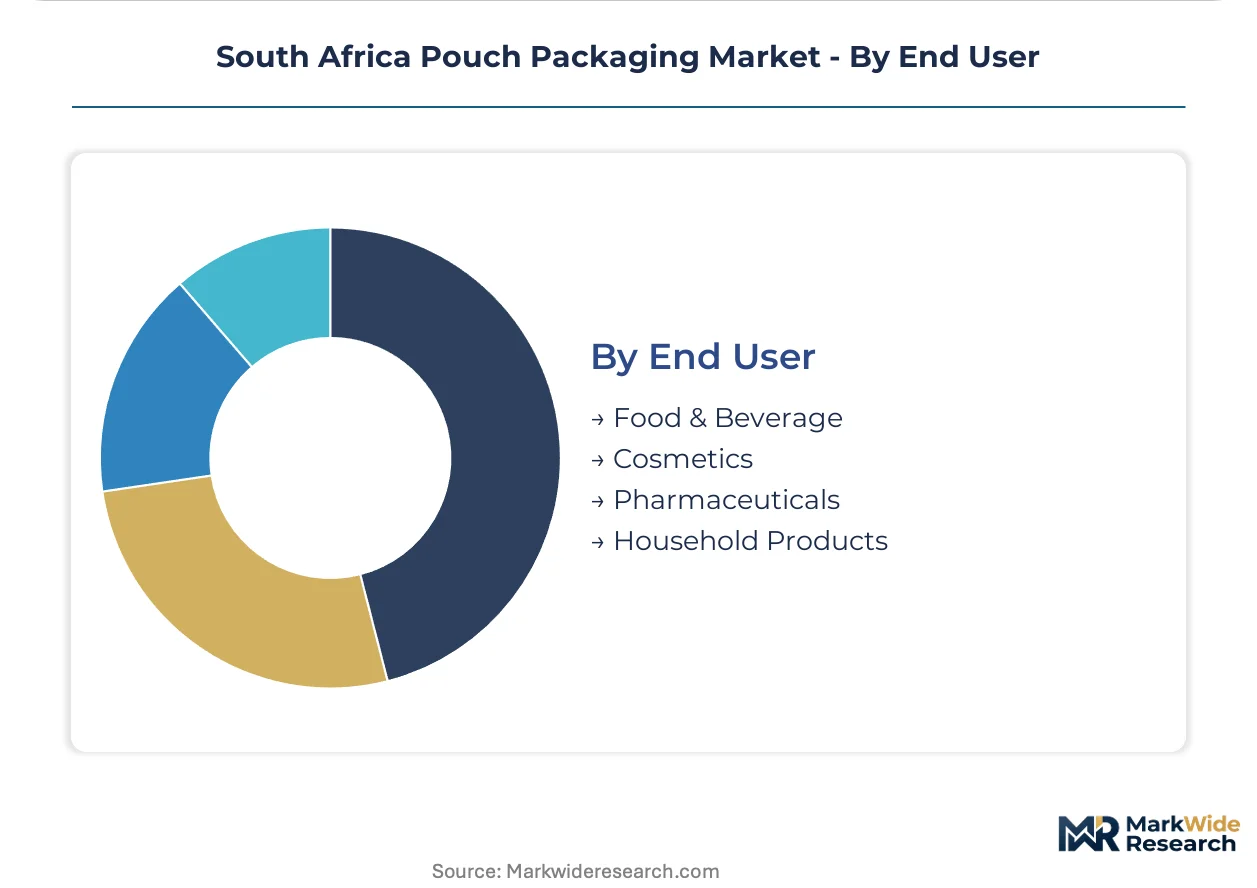
End User:
Customer type determines compliance burden and margin structure: pharmaceutical and cosmetics segments demand certified barrier documentation, while food and beverage and household products compete on material efficiency and speed-to-shelf.
- Food & Beverage:Shelf-stable sauces, ready-to-eat meals, and condiments drive metallized polyethylene terephthalate lamination demand. The Johannesburg-Pretoria industrial corridor hosts the densest converting and filling operations, with SANS 10329 certification eliminating smaller suppliers from approved vendor lists.
- Pharmaceuticals:Moisture and light protection mandates from the South African Health Products Regulatory Authority create premium margin pools for converters with integrated extrusion-to-print capabilities and automated quality management systems.
- Cosmetics:High-definition gravure decoration requirements favor converters with spectroscopy-equipped production lines for color consistency.
- Household Products:Detergent and cleaner applications prioritize chemical resistance and spout compatibility over oxygen barrier sophistication.
Food and beverage dominates installed base. Pharmaceuticals is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Regulator for Compulsory Specifications enforces SANS 10329 certification requirements that reshape supply geography across South Africa's provinces. Industrial concentration in Gauteng province drives converting capacity expansion, while regulatory enforcement tightens material specifications nationwide.
Gauteng Province
The Johannesburg-Pretoria industrial corridor hosts the densest converting and filling operations for shelf-stable sauces and ready-to-eat meals. The Department of Forestry, Fisheries and the Environment mandates extended producer responsibility compliance that accelerates mono-material redesign among Gauteng-based suppliers. National supermarket procurement teams in Johannesburg now enforce quarterly supplier reviews with recycled-content thresholds as mandatory qualification criteria.
KwaZulu-Natal
Mondi Group's Richards Bay kraft paper integration anchors regional supply for dry food and confectionery applications facing logistics cost pressure. The National Regulator for Compulsory Specifications applies identical SANS 10329 certification timelines to KwaZulu-Natal converters, though smaller operations struggle with 18-month retesting investments. Durban port infrastructure supports import of metallized polyethylene terephthalate films for barrier-sensitive pharmaceutical contracts.
Western Cape
Export-oriented wine producers in the Western Cape corridor present underpenetrated white space for single-serve alcohol alternatives to glass packaging. The South African Health Products Regulatory Authority governs moisture and light protection specifications that apply equally to pharmaceutical pouch exports through Cape Town port. Stellenbosch-Paarl wine clusters increasingly evaluate lightweight pouch formats for air freight efficiency to European markets.
Eastern Cape
Automotive component suppliers in the Eastern Cape generate secondary demand for industrial pouch formats protecting precision parts during shipment. The Department of Trade, Industry and Competition administers special economic zone incentives that attract packaging converters serving automotive OEMs in Gqeberha. Coega Industrial Development Zone infrastructure supports mid-volume converting operations with port access for polymer resin imports.
South Africa Pouch Packaging Market Competitive Landscape
Player mix skews toward integrated multinational operations with captive film extrusion capabilities, while smaller domestic converters face elimination from approved vendor lists under compressed SANS retesting cycles. Market structure concentrates around three strategic archetypes: integrated global suppliers with pharmaceutical-grade barrier expertise, regional paper-based substrate specialists leveraging kraft integration, and recycled-content polyethylene challengers competing on extended producer responsibility compliance. Dominant competitive moves include backward integration into polymer resin compounding and automated quality management system deployment to sustain certification continuity.
Within the integrated multinational tier, Amcor Group GmbH and Mondi Group exemplify archetypes that combine extrusion-to-print capabilities with spectroscopy-equipped production lines. Amcor Group GmbH occupies a position representing pharmaceutical-grade barrier format leadership, while Mondi Group anchors paper-based substrate supply through its Richards Bay integration point. Mpact Limited sits within the recycled-content challenger archetype, competing aggressively on polyethylene structures that satisfy retailer-mandated circularity thresholds.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Huhtamaki Oyj |
| Trempak Trading Pty Ltd |
| APAC Enterprises |
| Constantia Afripack Flexibles |
| Mondi Group |
| Mpact Limited |
| Nampak Ltd |
| Polyoak Packaging |
| Others |
Pricing and Supply Chain Analysis
SANS 10329 certification gates supplier qualification and price differentiation simultaneously, collapsing the vendor base toward integrated converters that command 15-25% premiums for pharmaceutical-grade barrier documentation while squeezing undifferentiated competitors into commodity polyethylene tiers.
Pricing Analysis
Cost-plus contracts with ethylene vinyl alcohol and metallized polyethylene terephthalate indexation dominate composite structure procurement, insulating integrated converters from petrochemical volatility while exposing smaller players to margin compression. Pricing stratifies across SANS-certified premium, standard multi-layer, and economy mono-material tiers driven by barrier performance and recycled-content thresholds. Cost compression in standard laminations intensifies as Gauteng retail chains consolidate procurement volumes and mandate quarterly price reviews. Mass-market FMCG buyers exhibit highest price sensitivity, while pharmaceutical and export food segments accept premiums for certified barrier documentation.
Supply Chain Analysis
Durban port congestion and container availability constraints on Asia-South Africa trade lanes elevate inbound logistics costs for metallized film and EVOH resin imports, compressing converter margins and accelerating regional sourcing shifts. Supply concentrates in China, South Korea, and Germany for barrier film technologies, while Saudi Arabia and the United States anchor polyethylene resin feedstocks. The supply chain rests on single-source vulnerability for pharmaceutical-grade EVOH grades and kraft paper integration limited to Mondi Group's Richards Bay facility. Distribution runs through Johannesburg-Pretoria industrial corridor consolidation points serving Gauteng-based retail chains and filling operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Gauteng-based national supermarket chains that have halved active converter relationships over three contract cycles, shifting negotiation leverage decisively toward retail procurement teams.
For Market Incumbents: Fortify certification continuity through automated spectroscopy-equipped production lines and backward integration into polymer resin compounding. Defend against SANS retesting cycle elimination by embedding dedicated quality personnel and laboratory investments that smaller competitors cannot replicate. Prioritize channel control through direct long-term agreements with Johannesburg-Pretoria filling operations to bypass quarterly procurement compression.
For New Entrants and Emerging Players: Lead with mono-material polyethylene structures targeting extended producer responsibility compliance gaps among mass-market FMCG clients underserved by integrated multinationals. The Western Cape wine export corridor presents the most penetrable white space for single-serve alcohol pouch alternatives to glass. Pursue a go-to-market angle anchored on air freight efficiency documentation and rapid digital printing turnaround for seasonal export promotions.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming flexible packaging divisions lacking SANS certification investment discipline. Long-term viability favors converters with captive film extrusion and pharmaceutical barrier expertise over pure-play converting operations exposed to resin price volatility. Watch for inflection signals in pending extended producer responsibility amendments that would accelerate mono-material specification mandates and reward early compliance repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Compounding | Captive supply of recycled-content polyethylene secures retailer-mandated circularity thresholds against import volatility. |
| SANS 10329 Certification Automation | Spectroscopy-equipped production lines eliminate manual inspection dependency and sustain 18-month retesting continuity. |
| Mono-Material Structure Redesign | Simplified recycling streams align with Department of Forestry, Fisheries and the Environment extended producer responsibility mandates. |
| Digital Printing Convergence Deployment | Short-run gravure-digital hybrid enables mass customization for seasonal FMCG promotions without plate changeover costs. |
| Western Cape Wine Corridor Expansion | Single-serve alcohol pouch formats capture air freight efficiency demand from Stellenbosch-Paarl export clusters. |
Research Methodology
A spread of perspectives from packaging plant managers, retail category buyers, regulatory affairs specialists at the National Regulator for Compulsory Specifications, and polymer procurement directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, SANS certification registries, Department of Forestry, Fisheries and the Environment extended producer responsibility filings, and SEC disclosures from listed packaging multinationals. Bottom-up volume triangulation across material type, pouch format, and end-use segment was cross-checked against top-down macroeconomic absorption models.
Segmentation dimensions modeled include material substrate, pouch geometry, closure technology, end-use industry, and provincial demand cluster across the projection horizon. CAGRs were derived from trend extrapolation of historical absorption patterns adjusted for regulatory enforcement intensity and buyer consolidation trajectories. Industry-specific forecast inputs incorporated ethylene vinyl alcohol price elasticity coefficients and SANS certification renewal rates by converter size tier.
Forecasts assume regulatory continuity in SANS 10329 retesting cycles and extended producer responsibility targets; material policy shifts would require re-modeling of supplier elimination rates and mono-material adoption curves. Forecasts reflect assumptions of stable petrochemical feedstock availability and Durban port throughput capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Italy Pouch Packaging Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Flexible Pouch Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Clipless Vertical Pouches Market
Pouch
North America Pouch Packaging Market
Pouch
Spain Pouch Packaging Market
Pouch
United States Retort Pouches Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Stand-Up Pouches Market
Pouch
Thailand Pouch Packaging Market
Pouch
Flat Bottom Pouch Market
Pouch
Japan Pouch Packaging Market
Pouch
Peel Pouches Market
Pouch
Doyen Style Pouches Market