
 Hot-Fill Food Packaging Market | 2026-2036
Hot-Fill Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hot-Fill Food Packaging Market Foresight
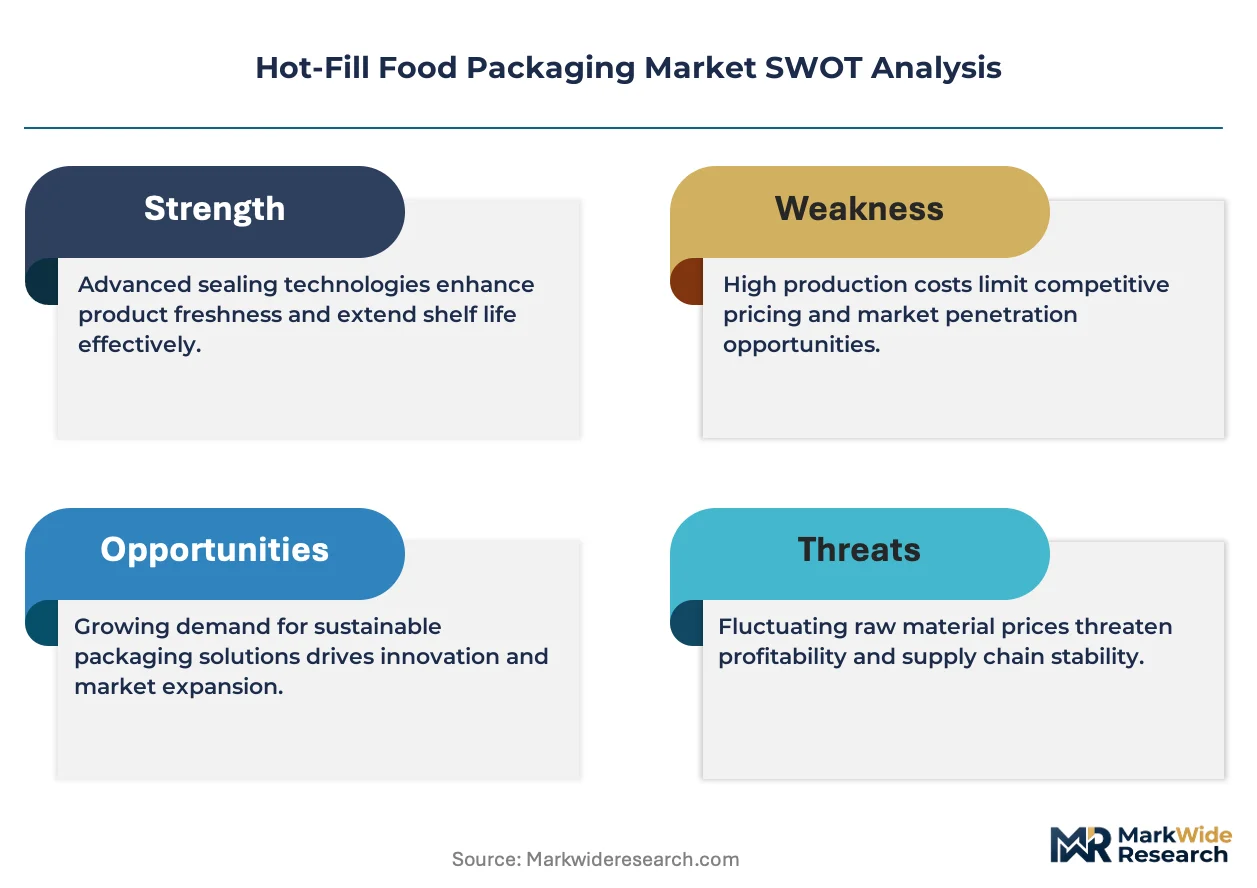
REACH compliance is consolidating the cost-of-entry calculus for European hot-fill packaging converters, favoring suppliers with in-house polymer testing and migration certification. Amcor plc leverages its integrated film-to-bottle platform to sustain margin capture across high-acid sauce applications. Berry Global Inc. anchors North American supply through multi-site blow-molding networks optimized for heat-set PET volumes. Tetra Pak International S.A. differentiates via aseptic-to-hot-fill technology crossover that competes for ambient soup and broth contracts.
Hot-fill food packaging denotes containers engineered to withstand filling temperatures between 85°C and 96°C without dimensional distortion, typically constructed from heat-set PET, multi-layer polypropylene, or tempered glass with thermal shock resistance exceeding 42°C differential. The process enables ambient shelf stability for 12–18 months without refrigeration, serving manufacturers of ready-to-eat meals, pasta sauces, and fruit beverages. Bottles dominate value contribution due to their ubiquity in single-serve beverage and sauce segments, while pouches represent the fastest-expanding format as retort-compatible barrier films displace rigid options in ready-to-eat meal kits. Biodegradable materials remain nascent but attract capital as European Extended Producer Responsibility schemes shift cost liability upstream toward brand owners.
FDA migration thresholds under 21 CFR 177.1630 govern contact-layer composition for US-bound hot-fill containers, while EU Regulation 10/2011 on plastic materials imposes stricter overall migration limits that reshape laminate specifications. China's SAMR enforces GB standards for composite packaging that diverge from Western testing protocols, creating dual-certification burdens for multinational suppliers. Stakeholders must monitor how divergent national shelf-life validation requirements affect format standardization strategies and capital allocation across regional production footprints.
Market Dynamics
EU Regulation 10/2011 migration limits are compressing laminate specifications and forcing converters toward mono-material PET structures that sacrifice barrier performance for recyclability compliance.
Growth Catalysts
- Ready-to-eat meal proliferation:Shelf-stable convenience food demand pulls heat-set PET procurement from pasta sauce and ambient soup manufacturers.
- REACH consolidation:European polymer testing mandates favor converters with in-house migration certification laboratories.
- Retort-compatible barrier films:Pouch format expansion displaces rigid containers in meal kit applications.
Market Restraints
- Heat-set PET supply concentration:Blow-molding capacity clusters in Germany and the US Midwest create geographic vulnerability.
- Overall migration limit compliance:EU Regulation 10/2011 forces adhesive and coating reformulation that extends R&D cycles.
- Aseptic technology substitution:Tetra Pak's ambient soup platforms compete for contracts traditionally served by hot-fill.
Strategic Opportunities
- Extended Producer Responsibility tailwinds:European EPR schemes shift cost liability toward brand owners willing to fund biodegradable material development.
- China SAMR dual-certification gap:GB standard divergence from Western protocols creates service revenue for testing laboratories serving multinationals.
- Aseptic-to-hot-fill technology convergence:Equipment suppliers can cross-sell into ambient broth and ready-meal segments.
Industry Challenges
- Migration testing talent scarcity:Analytical chemists with EU 10/2011 and FDA 21 CFR 177.1630 dual expertise command premium compensation.
- Legacy format standardization delays:Divergent national shelf-life validation protocols prevent volume scale across regional production footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot-Fill Food Packaging Market |
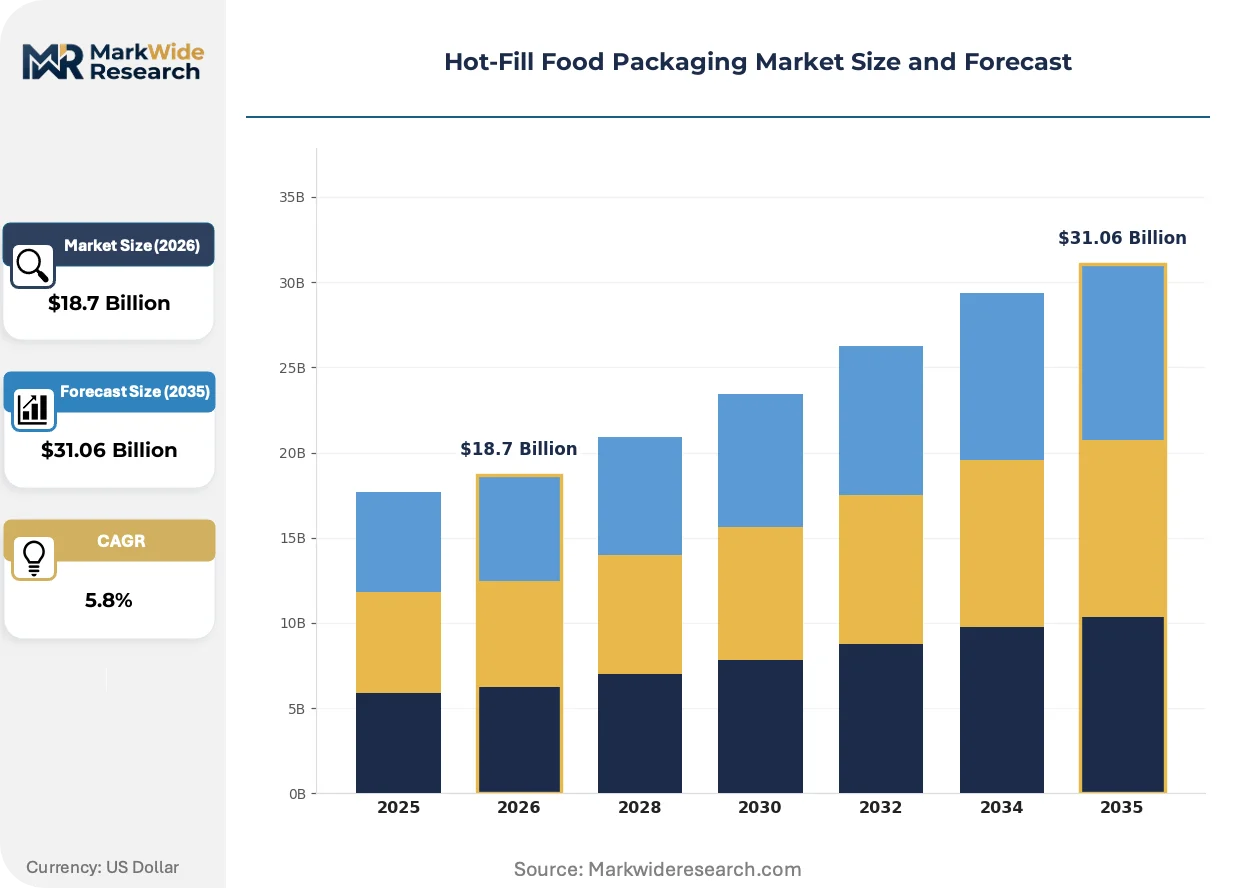
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Pouches, Trays Material: Glass, Plastic, Aluminum, Biodegradable Closure Type: Screw Caps, Snap-On Lids, Push-Down Lids, Heat-Sealed End Use: Ready-to-Eat Meals, Sauces, Beverages, Soups |
| Companies Covered | Amcor plc, Berry Global Inc., Graham Packaging Company, Silgan Holdings Inc., Plastipak Holdings Inc., Tetra Pak International S.A., Huhtamaki Group, Indorama Ventures Public Company Limited, Crown Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot-Fill Food Packaging Market Shifts & Advancements
Material science advances and regulatory compression are reconfiguring how converters balance barrier performance against circularity mandates. Three developments merit particular attention.
Digital inline inspection systems for heat-set PET dimensional stability are automating quality control at filling temperatures between 85°C and 96°C. Sauce and beverage manufacturers deploy these systems at line speeds exceeding 600 bottles per minute. This automation is compressing defect rates and reducing manual sampling labor.
REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing adhesive suppliers to reformulate multi-layer laminates. The industrial consequence extends R&D timelines by 8-14 months for new product qualifications. High-acid sauce applications face the steepest reformulation burden due to aggressive migration profiles.
Brand owners now specify mono-material structures in tender documents as a precondition for contract award. This specification shift displaces traditional multi-layer polypropylene in ready-to-eat meal packaging. Germany's food processing clusters around Frankfurt and Hamburg exhibit the most aggressive mono-material procurement criteria.
Hot-Fill Food Packaging Market Segmentation
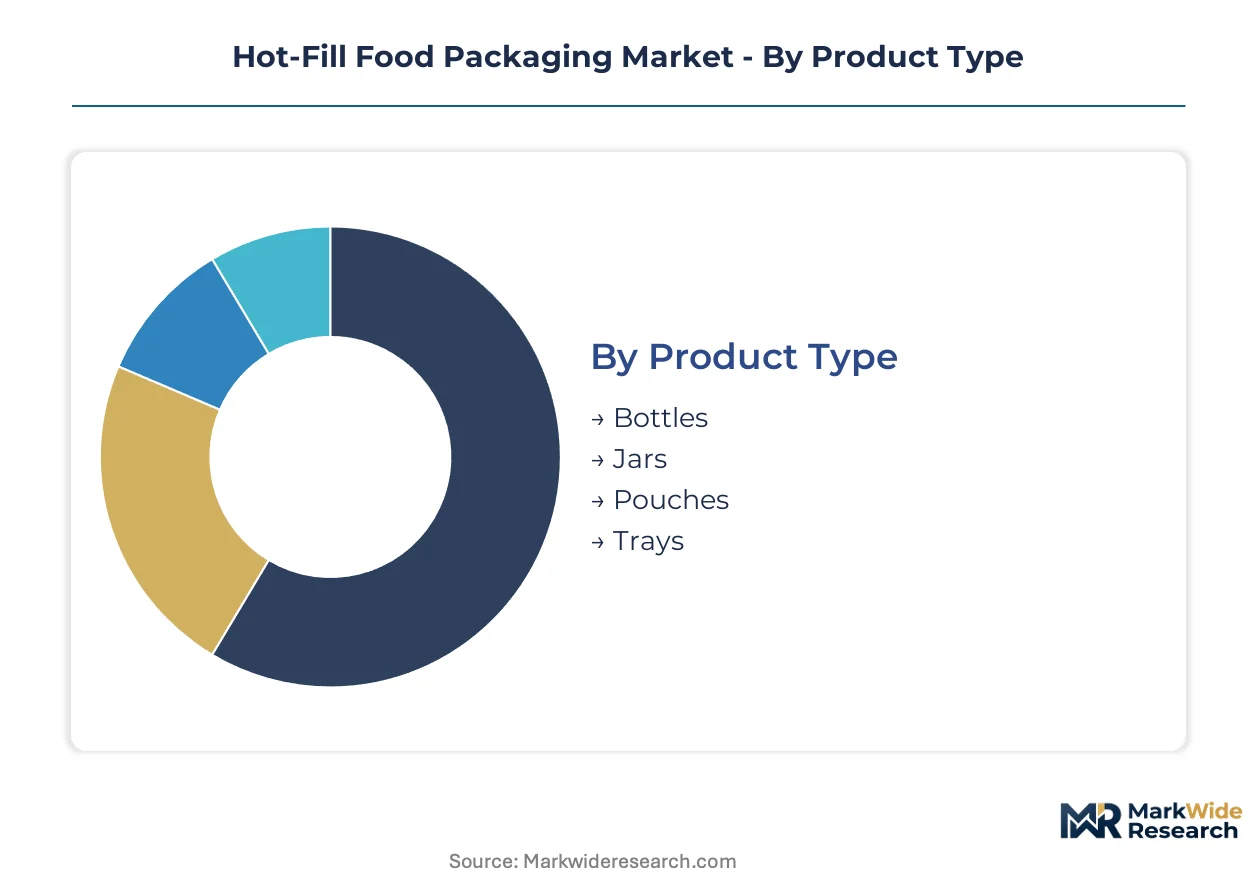
Hot-fill packaging specifications diverge sharply across product formats and material substrates, with each segment carrying distinct regulatory certification burdens and thermal performance thresholds. Understanding these segment boundaries clarifies where converters must invest in specialized equipment versus commodity-scale capacity.
Product Type:
FDA 21 CFR 177.1630 governs all four formats for US-bound shipments, while EU 10/2011 migration limits impose additional testing layers on multi-component structures like pouches and trays.
- Bottles:Heat-set PET dominates construction for single-serve beverages and pasta sauces. German food processors around Frankfurt specify premium barrier grades with oxygen transmission below 0.1 cc/day. Demand concentrates in high-acid sauce applications where dimensional stability at 96°C filling temperatures is non-negotiable.
- Pouches:Retort-compatible barrier films displace rigid containers in meal kit applications. European EPR schemes accelerate procurement of mono-material versions that sacrifice some barrier performance for recyclability compliance. The format climbs fastest as ambient soup manufacturers seek logistics efficiency.
- Jars:Tempered glass with thermal shock resistance exceeding 42°C differential serves premium sauce segments. Chinese GB standards for composite packaging create dual-certification burdens for multinationals sourcing from European converters.
- Trays:Multi-layer polypropylene structures face reformulation pressure under REACH Article 33 SVHC disclosure rules. Ready-to-eat meal producers specify these for shelf-stable entrees requiring 12–18 month ambient stability.
Leading the category by volume: Bottles. Growing fastest: Pouches.
Material:
Cost tiers separate commodity substrates from engineered alternatives, with biodegradables commanding 40–60% premiums over conventional plastics.
- Plastic:Heat-set PET and multi-layer polypropylene constitute the volume base. Blow-molding capacity clusters in Germany and the US Midwest, creating geographic vulnerability for converters without multi-site networks.
- Glass:Tempered variants with thermal shock resistance anchor premium sauce and beverage segments. Italian and French bottlers maintain strong procurement preference for aesthetic differentiation in retail-facing applications.
- Biodegradable:PLA and starch-based alternatives attract capital as European EPR schemes shift cost liability upstream. Barrier performance limitations restrict deployment to short-shelf-life applications currently.
- Aluminum:Lined cans and trays serve retort applications where metal detection compatibility matters. China's SAMR enforces GB standards that diverge from Western testing protocols for migration validation.
Plastic dominates procurement spend. Biodegradable materials gain share fastest among sustainability-mandated tenders.
Closure Type:
Application requirements dictate seal integrity specifications, with aseptic-to-hot-fill crossover technologies blurring traditional format boundaries.
- Screw Caps:Tamper-evident designs with oxygen scavenging liners protect high-acid sauces. German converters lead qualification speed for new barrier coating formulations.
- Heat-Sealed:Film-to-tray and film-to-pouch seals require precise temperature control at 85°C–96°C filling windows. Retort-compatible adhesives face 8–14 month R&D timelines under REACH reformulation mandates.
- Snap-On Lids:Polypropylene constructions suit ready-to-eat meal trays where reclosability adds consumer convenience. Migration testing talent scarcity delays new product introductions.
- Push-Down Lids:Child-resistant mechanisms expand in single-serve beverage segments. US FDA migration thresholds under 21 CFR 177.1630 govern contact-layer composition specifications.
Screw caps lead by installed base. Heat-sealed closures expand most quickly with pouch format proliferation.
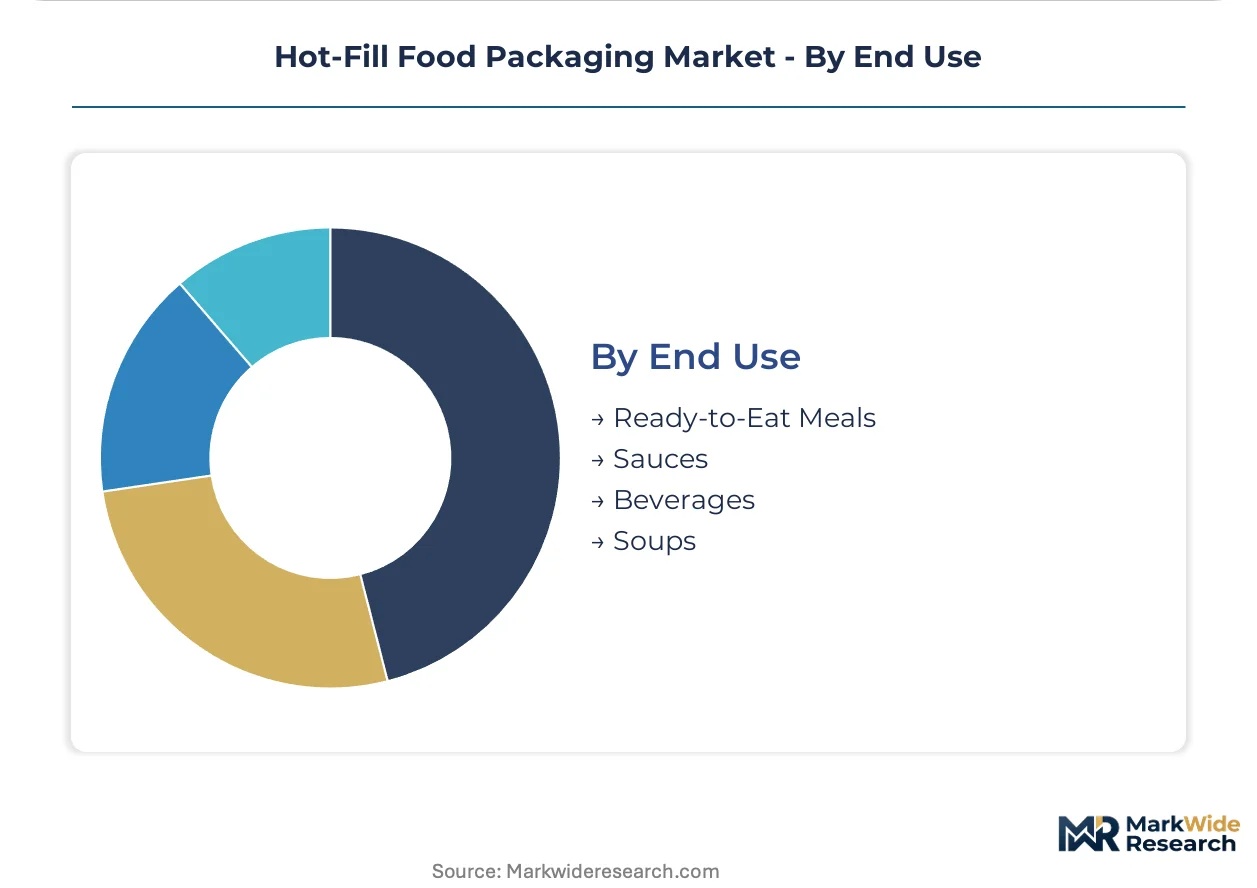
End Use:
Customer type segmentation reveals divergent procurement patterns between branded manufacturers and private-label converters.
- Sauces:Pasta sauce and condiment producers drive premium barrier packaging uptake. EU Regulation 10/2011 forces adhesive and coating reformulation that extends R&D cycles for high-acid applications.
- Ready-to-Eat Meals:Shelf-stable convenience food demand pulls heat-set PET procurement from ambient soup manufacturers. Mono-material specifications now appear as contract preconditions in German tender documents.
- Beverages:Fruit juice and functional drink bottlers specify heat-set PET for single-serve formats. Digital inline inspection systems automate quality control at line speeds exceeding 600 bottles per minute.
- Soups:Ambient broth manufacturers face competitive pressure from Tetra Pak aseptic platforms. Hot-fill retains cost advantage for lower-volume specialty SKUs.
Sauces command the largest packaging procurement budget. Ready-to-eat meals show the steepest expansion trajectory as meal kit distribution scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free economic zones around Frankfurt and Hamburg concentrate blow-molding capacity for heat-set PET, while China's coastal development areas attract retort-compatible film investments. National migration testing protocols and Extended Producer Responsibility schemes reshape procurement patterns across manufacturing clusters.
United States
Midwest food processing corridors around Chicago drive heat-set PET demand for pasta sauce and ambient soup applications. FDA 21 CFR 177.1630 migration thresholds govern contact-layer specifications for domestic converters. Wisconsin and Ohio host multi-site blow-molding networks optimized for high-volume beverage contracts.
Germany
Frankfurt and Hamburg food processing clusters specify premium barrier grades with oxygen transmission below 0.1 cc/day for high-acid sauces. EU Regulation 10/2011 overall migration limits force adhesive reformulation across multi-layer laminate suppliers. REACH Article 33 SVHC disclosure requirements extend R&D qualification timelines by 8-14 months.
China
Yangtze River Delta beverage bottlers expand heat-set PET procurement for single-serve fruit juice formats. SAMR enforces GB standards for composite packaging that diverge from Western testing protocols, creating dual-certification burdens. Shanghai and Jiangsu province converters invest in digital inline inspection systems for line speeds exceeding 600 bottles per minute.
Italy
Emilia-Romagna pasta sauce manufacturers sustain demand for tempered glass jars with thermal shock resistance exceeding 42°C differential. EFSA migration guidelines intersect with national packaging waste directives to reshape laminate specifications. Parma and Modena processing clusters favor aesthetic differentiation in retail-facing premium segments.
India
Maharashtra and Gujarat ready-to-eat meal producers accelerate pouch format adoption as retort-compatible barrier films displace rigid containers. FSSAI food contact regulations govern domestic packaging specifications while export-oriented converters pursue EU 10/2011 compliance. Mumbai-Pune industrial corridor attracts investments in mono-material structures for European contract manufacturing.
Hot-Fill Food Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material substrate and format boundaries. The vendor base organizes into three functional tiers: integrated film-to-bottle platforms sustaining margin capture, multi-site blow-molding networks optimizing heat-set PET volumes, and aseptic-to-hot-fill technology crossovers competing for ambient soup contracts. Consolidation pressures intensify as REACH compliance costs favor converters with in-house polymer testing laboratories. Strategic moves concentrate on backward integration into resin compounding and geographic expansion through qualification-speed advantages in migration certification.
Within the integrated platform tier, Amcor plc and Berry Global Inc. exemplify scale-driven positioning across high-acid sauce and beverage segments. Tetra Pak International S.A. occupies a distinct technology-crossover position competing for contracts traditionally served by hot-fill processes. These three anchors represent divergent strategic postures: film-to-bottle integration, multi-site manufacturing networks, and aseptic platform extension into ambient stability applications.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Graham Packaging Company |
| Silgan Holdings Inc. |
| Plastipak Holdings Inc. |
| Tetra Pak International S.A. |
| Huhtamaki Group |
| Indorama Ventures Public Company Limited |
| Crown Holdings Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up blow-molding specialists anchor capacity ownership across Germany and the US Midwest, compressing pricing discipline through consolidated procurement leverage while simultaneously constraining spot-market availability for smaller sauce and beverage converters.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as German food processors around Frankfurt and Hamburg prioritize qualification-speed over unit cost for high-acid sauce applications. Three-tier pricing structure across premium barrier grades, standard heat-set PET, and economy mono-material tiers separates converters by migration certification depth. Cost compression in standard-grade segments is intensifying because REACH Article 33 reformulation burdens extend R&D cycles. Private-label converters exhibit the highest price sensitivity, while branded sauce manufacturers absorb premiums for sub-0.1 cc/day oxygen transmission specifications.
Supply Chain Analysis
Freight cost differentials between German blow-molding clusters and Asia-Pacific film extrusion hubs reshape sourcing calculus for multinational ready-to-eat meal producers. Supply concentrates in Germany, the US Midwest, and China's Yangtze River Delta, with heat-set PET resin and retort-compatible barrier films as critical inputs. Single-source vulnerability in specialized migration testing laboratories creates qualification bottlenecks. Distribution runs through converter-direct relationships with food processing clusters, bypassing traditional packaging distributors for volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over resin compounding and in-house polymer testing laboratories separates margin sustainers from price-takers.
For Market Incumbents: Deepen captive supply of heat-set PET resin through compounding facility acquisitions in Germany or the US Midwest to defend against aseptic technology substitution from Tetra Pak's ambient soup platforms. Prioritize in-house migration certification capacity under EU 10/2011 and FDA 21 CFR 177.1630 to compress qualification timelines for high-acid sauce contracts. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with Indian converters in Maharashtra and Gujarat targeting European EPR-driven demand for mono-material pouches. Focus white-space capture on retort-compatible barrier films for ready-to-eat meal kits where rigid container displacement accelerates fastest. For Investors and Strategic Acquirers: REACH compliance cost consolidation among mid-tier converters is the leading indicator that acquisition multiples for testing-laboratory-equipped assets will diverge from commodity blow-molding capacity. Target converters with dual EU-US migration certification capabilities over the medium-term horizon. Monitor German tender document language specifying mono-material preconditions as the inflection signal for biodegradable material capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of heat-set PET raw material secures margin capture against volatile polymer feedstock costs. |
| In-House Migration Certification Laboratory | EU 10/2011 and FDA dual expertise compresses 8-14 month qualification timelines for high-acid sauce applications. |
| Mono-Material Structure Development | Recyclability compliance under European EPR schemes meets German tender preconditions for contract awards. |
| Retort-Compatible Film Capacity Expansion | Pouch format proliferation in ready-to-eat meal kits displaces rigid containers at logistics-efficient scale. |
| Aseptic-to-Hot-Fill Technology Crossover | Equipment suppliers capture ambient broth and soup contracts from traditional hot-fill incumbents. |
Research Methodology
Multi-period observation of heat-set PET procurement volumes, migration certification timelines, and EPR scheme implementation anchored the trend analysis, supplemented by interviews with blow-molding plant managers, food processing procurement leads at Frankfurt and Hamburg clusters, polymer testing laboratory directors, and regulatory affairs specialists at converters. Secondary validation drew from EU 10/2011 regulatory filings, FDA 21 CFR guidance documents, SAMR GB standard updates, and customs trade data for packaging material flows. Bottom-up capacity assessments across German free economic zones and US Midwest corridors triangulated against top-down demand modeling from ready-to-eat meal and sauce production statistics.
Segment-weighting across product format, material substrate, closure type, and end-use application distributed value and volume projections across the analysis window. CAGRs derived from regression analysis of historical procurement patterns against regulatory implementation schedules and food processing capacity expansion announcements. Model inputs included heat-set PET resin price indices, REACH Article 33 disclosure compliance costs, and digital inline inspection system adoption rates at line speeds exceeding 600 bottles per minute.
Regulatory enforcement variance, biodegradable material barrier performance breakthroughs, and aseptic technology cost reductions are the dominant revision risks to forecast assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Seafood Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
North America Food Packaging Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Food and Beverage Packaging Market