
 North America Smart Label Market | 2026-2036
North America Smart Label Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Label Market Intelligence
Subscription-based label management platforms is rebalancing vendor economics toward recurring revenue streams rather than one-time hardware sales. Avery Dennison Corporation leverages its materials science heritage to dominate high-performance adhesive substrates for RFID inlays. Zebra Technologies Corporation anchors North American channel networks through extensive reseller partnerships and enterprise mobility integration. SATO Holdings Corporation specializes in thermal printing ecosystems that complement smart label deployments across logistics verticals.
A smart label embeds electronic identifiers such as RFID chips, NFC circuits, or optical codes within printable substrates to enable automated data capture without direct line-of-sight. These labels operate across frequencies from 125 kHz to 960 MHz UHF and incorporate antenna structures etched from aluminum or copper on polyethylene terephthalate backings, serving industrial purposes ranging from real-time inventory visibility to pharmaceutical authentication. RFID Labels command the largest installed base due to decades of supply chain standardization, while NFC Tags capture premium positioning in consumer-facing authentication where smartphone tap interactions drive engagement. Bluetooth Low Energy labels represent the fastest-expanding technology segment as battery-assisted beacons extend location tracking beyond passive read ranges into dynamic asset monitoring.
The FDA enforces pharmaceutical serialization requirements through the Drug Supply Chain Security Act, compelling manufacturers to adopt machine-readable labels at the unit dose level. FCC Part 15 regulations govern UHF RFID transmission power and spectrum allocation, directly constraining read range performance and infrastructure design across American warehouse networks. Health Canada and the Canadian Food Inspection Agency impose parallel traceability mandates for cross-border agricultural and medical shipments. Stakeholders must monitor evolving state-level privacy legislation in California and New York that could restrict consumer-facing NFC data collection practices.
Market Dynamics
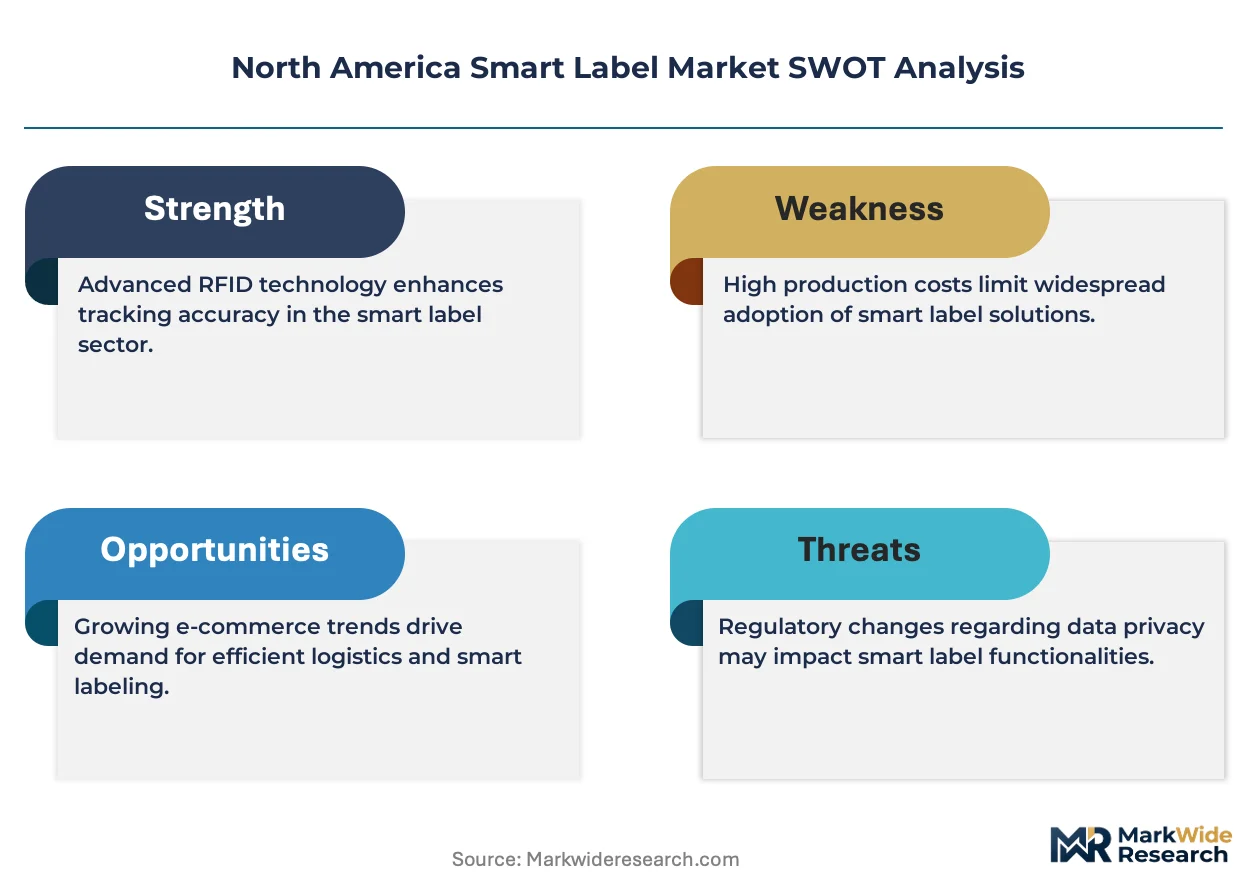
Pharmaceutical serialization mandates under the FDA's Drug Supply Chain Security Act are compressing implementation timelines and forcing RFID infrastructure upgrades across manufacturing and distribution networks. Unit-level traceability requirements are cascading from finished goods down to component suppliers, reshaping procurement specifications and vendor qualification processes throughout the value chain.
Growth Catalysts
- California's logistics corridor concentration:Dense warehousing clusters around Los Angeles and the Inland Empire generate network effects for RFID reader infrastructure, lowering marginal deployment costs for adjacent facilities.
- FDA Drug Supply Chain Security Act:The 2023 enforcement deadline for unit-level serialization compelled pharmaceutical manufacturers to embed machine-readable identifiers at the smallest saleable unit, creating baseline demand for high-memory RFID inlays.
- Cold-chain verification protocols:Temperature-sensitive biologics and vaccines require continuous environmental monitoring, driving integration of sensor-enabled smart labels with passive RFID for dual-function authentication.
Market Restraints
- Aluminum and copper substrate volatility:Antenna etching relies on thin-gauge metal foils whose spot pricing fluctuates with commodity markets, compressing inlay margins during supply tightness.
- UHF spectrum fragmentation:FCC Part 15 power limits constrain read range in dense metallic warehouse environments, forcing redundant reader placement and infrastructure cost escalation.
- Optical code persistence:2D barcodes and QR patterns retain cost advantages for low-value consumer goods, limiting RFID penetration in mass-market retail tagging below certain price thresholds.
Strategic Opportunities
- Northeast pharmaceutical belt expansion:New Jersey and Massachusetts biotech clusters are retrofitting legacy facilities with item-level tracking, opening retrofit service revenue streams for systems integrators.
- Battery-assisted passive convergence:Hybrid labels combining energy harvesting with Bluetooth Low Energy beacons enable location tracking beyond traditional passive read ranges into dynamic asset monitoring.
- Canadian cross-border harmonization:Health Canada alignment with FDA serialization standards creates unified North American compliance pathways, reducing dual-certification burdens for multinational manufacturers.
Industry Challenges
- RF engineering talent scarcity:Antenna design and impedance matching for custom form factors require specialized electromagnetic simulation expertise concentrated among a limited pool of practitioners.
- Legacy WMS integration friction:Warehouse management systems deployed before 2015 often lack native RFID middleware modules, necessitating expensive custom API development or parallel data architectures.
Report Scope
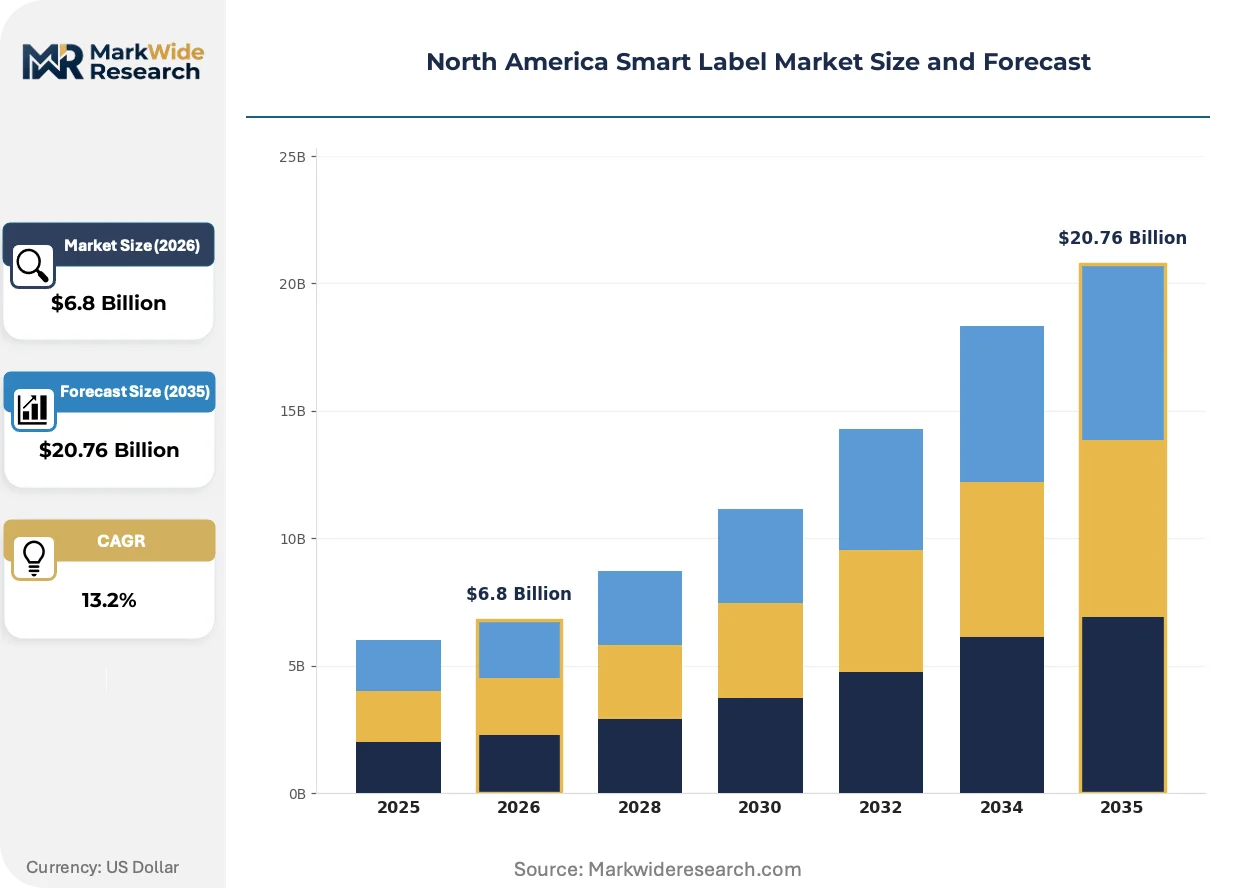
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Label Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFID Labels, NFC Tags, QR Code Labels, Barcode Labels, Biometric Labels Technology: Near Field Communication, Radio Frequency Identification, Optical Recognition, Biometric Sensing, Bluetooth Low Energy Application: Supply Chain Management, Anti-Counterfeiting, Inventory Tracking, Authentication, Asset Management End User: Retail Chains, Logistics Providers, Pharmaceuticals, Consumer Electronics, Food & Beverage |
| Companies Covered | Honeywell International Inc., SATO Holdings Corporation, Avery Dennison Corporation, Invengo Information Technology, Alien Technology Corporation, CCL Industries Inc., Checkpoint Systems, All4Labels Global Packaging Group, Zebra Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Label Market Strategic Shifts & Innovations
Smart label architectures are converging around multi-protocol designs that bridge passive UHF RFID with active beaconing capabilities. This convergence is compressing the historical segmentation between inventory tracking and real-time location systems, enabling unified platform investments.
Chipless RFID encoding through printable conductive inks is consolidating antenna manufacturing into standard flexographic and screen printing processes. Pharmaceutical contract packagers in Puerto Rico and the Northeast are piloting these substrates to eliminate silicon die attachment steps. The structural consequence is a compression of inlay production capital requirements, opening entry paths for regional converters previously excluded by semiconductor handling expertise.
The FDA's enhanced enforcement discretion letters for DSCSA non-compliance are tightening audit protocols for wholesale distributors. Third-party logistics providers in Memphis and Louisville hubs are deploying redundant verification stations to preempt regulatory action. Cold-chain pharmaceutical lanes crossing the Ambassador Bridge and Buffalo-Niagara corridor face the most intensive inspection scrutiny, driving preemptive label redundancy investments.
Subscription-based platform licensing is displacing perpetual hardware purchases among mid-market 3PLs. Monthly per-asset fees bundle tag supply, reader maintenance, and cloud analytics, converting capital expenditure into operational budgets. This shift is most visible among California-based e-commerce fulfillment operators serving health and beauty verticals with high SKU velocity and return rates.
North America Smart Label Market Segmentation
Smart label procurement specifications diverge sharply across end-use verticals, with FDA serialization mandates, FCC transmission regulations, and Health Canada traceability requirements creating distinct certification burdens that reshape vendor qualification criteria. Understanding these segment-specific compliance pathways enables manufacturers to align R&D investments with the highest-velocity demand corridors.
Product Type:
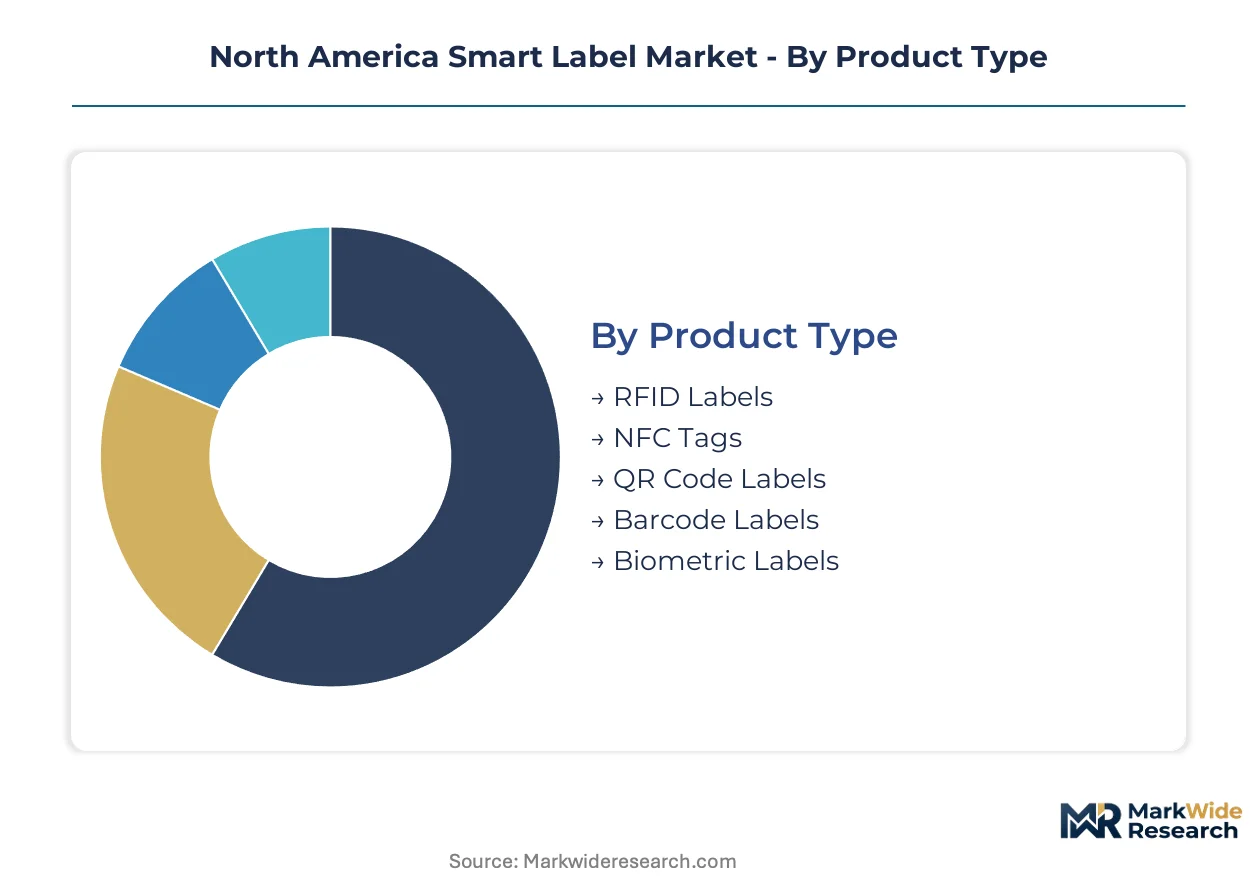
Certification requirements vary dramatically by embedded technology, with RFID Labels and NFC Tags facing the most intensive FCC Part 15 electromagnetic compliance testing while QR Code and Barcode Labels navigate simpler optical readability standards.
- RFID Labels:Aluminum or copper antenna structures etched on PET backings operate across 125 kHz to 960 MHz UHF bands. Pharmaceutical serialization under FDA DSCSA concentrates demand in New Jersey and Massachusetts biotech clusters, where unit-level traceability mandates force high-memory inlay adoption.
- NFC Tags:13.56 MHz inductive coupling circuits enable smartphone tap interactions for consumer authentication. California health and beauty e-commerce operators deploy these for premium product verification, though state-level privacy legislation in Sacramento and Albany constrains data collection practices.
- QR Code Labels:Two-dimensional matrix patterns encode URL pointers or serialized identifiers through standard printing processes.
- Barcode Labels:Linear symbologies retain cost advantages for high-volume, low-unit-value consumer goods tracking.
- Biometric Labels:Fingerprint or facial recognition substrates integrate with access control and high-security authentication workflows.
RFID Labels sit at the top of the volume ranking, with NFC Tags climbing the fastest.
Technology:
Cost tiers separate passive UHF architectures from battery-assisted beaconing, with Bluetooth Low Energy commanding premium pricing for extended read ranges while Near Field Communication and Radio Frequency Identification compete on infrastructure density economics.
- Near Field Communication:Short-range magnetic induction enables secure pairwise device communication without pairing protocols. Retail loyalty programs in Toronto and Vancouver deploy NFC for frictionless customer engagement, though merchant acquirer certification delays slow rollout velocity.
- Radio Frequency Identification:Backscatter modulation across unlicensed spectrum supports bulk reading without line-of-sight. Dense Los Angeles warehousing clusters generate network effects for reader infrastructure, lowering marginal deployment costs for adjacent Inland Empire facilities.
- Optical Recognition:Camera-based decoding of printed patterns requires no specialized hardware beyond commodity imaging sensors.
- Biometric Sensing:Physiological characteristic capture demands specialized sensor integration and liveness detection algorithms.
- Bluetooth Low Energy:Battery-assisted beacons extend location tracking beyond passive read ranges into dynamic asset monitoring, representing the steepest expansion trajectory among all technology segments.
Radio Frequency Identification dominates current installed base, while Bluetooth Low Energy gains share fastest among greenfield deployments.
Application:
Application selection correlates directly with customer IT maturity, with Supply Chain Management and Inventory Tracking demanding WMS integration capabilities while Anti-Counterfeiting and Authentication prioritize cryptographic security architectures.
- Supply Chain Management:End-to-end visibility platforms integrate smart label reads with transportation management and warehouse execution systems. Memphis and Louisville third-party logistics hubs deploy redundant verification stations to preempt FDA enforcement action for DSCSA non-compliance.
- Anti-Counterfeiting:Cryptographic authentication protocols verify product provenance through immutable ledger or centralized database lookups. Puerto Rico pharmaceutical contract packagers pilot chipless RFID substrates to eliminate silicon die attachment steps and compress production capital requirements.
- Inventory Tracking:Real-time stock position monitoring reduces carrying costs and stockout frequency.
- Authentication:Consumer-facing verification builds brand trust through transparent provenance disclosure.
- Asset Management:Capital equipment tracking extends label utility beyond consumable goods into returnable containers and tooling.
Supply Chain Management commands the largest addressable spend, with Anti-Counterfeiting expanding most quickly under regulatory pressure.
End User:
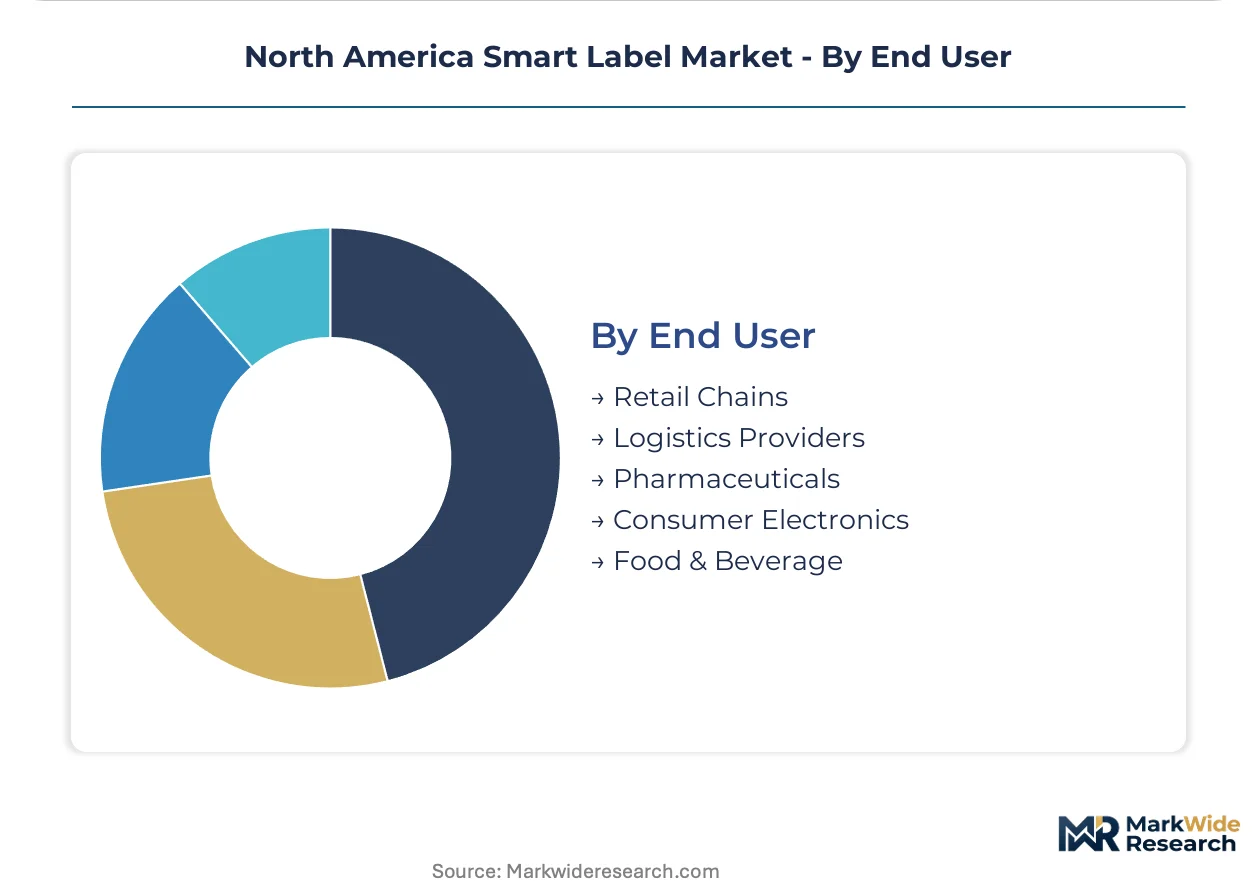
End-user procurement patterns stratify by margin structure, with Pharmaceuticals and Consumer Electronics tolerating higher per-label costs for compliance and brand protection while Retail Chains and Food & Beverage prioritize unit economics at scale.
- Retail Chains:High-SKU velocity operations demand rapid inventory cycling and returns processing. California e-commerce fulfillment operators serving health and beauty verticals are shifting from perpetual hardware purchases to subscription-based platform licensing, converting capital expenditure into operational budgets.
- Logistics Providers:Asset-light network operators require interoperable standards across heterogeneous shipper environments. Cold-chain pharmaceutical lanes crossing the Ambassador Bridge and Buffalo-Niagara corridor face intensive inspection scrutiny, driving preemptive label redundancy investments.
- Pharmaceuticals:FDA DSCSA mandates compel machine-readable identifiers at the smallest saleable unit, creating non-discretionary demand.
- Consumer Electronics:High-value goods warrant sophisticated authentication to combat gray market diversion.
- Food & Beverage:Health Canada and Canadian Food Inspection Agency traceability mandates for cross-border agricultural shipments parallel FDA requirements.
Pharmaceuticals generate the highest revenue per label deployed, with Logistics Providers scaling fastest through multi-tenant infrastructure sharing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's cross-border pharmaceutical harmonization lags the United States in RFID infrastructure density, while Mexico's maquiladora networks are accelerating smart label adoption for automotive component traceability. Both countries navigate distinct regulatory frameworks that reshape deployment economics differently than their southern neighbor.
United States
FDA DSCSA enforcement deadlines and FCC Part 15 spectrum rules dominate procurement specifications. California's Inland Empire warehousing clusters generate network effects for UHF reader infrastructure, lowering marginal deployment costs for adjacent logistics facilities serving health and beauty e-commerce verticals.
Canada
Health Canada alignment with FDA serialization standards creates unified North American compliance pathways for cross-border pharmaceutical shipments. The Ambassador Bridge and Buffalo-Niagara corridor face intensive inspection scrutiny for cold-chain biologics, driving preemptive label redundancy investments among third-party logistics providers.
Mexico
Automotive OEMs in Nuevo León and the Bajío Region deploy RFID for component traceability under USMCA origin verification requirements. The country's national pharmaceutical regulator is drafting serialization standards that mirror FDA frameworks, preparing domestic manufacturers for export compliance.
Northeast Corridor
New Jersey and Massachusetts biotech clusters retrofit legacy facilities with item-level tracking systems. Puerto Rico pharmaceutical contract packagers pilot chipless RFID substrates to eliminate silicon die attachment steps, compressing production capital requirements for regional converters.
North America Smart Label Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with adhesive substrate innovators commanding premium positioning in high-memory inlay applications while thermal printing ecosystem providers capture recurring service revenue. The vendor base organizes around three strategic archetypes: materials science heritage players, enterprise mobility integrators, and specialized thermal printing vendors. Consolidation pressure intensifies through backward integration into antenna manufacturing and strategic partnerships for cloud analytics bundling.
Within the materials science tier, Avery Dennison Corporation anchors high-performance adhesive substrate supply for RFID inlays, while Zebra Technologies Corporation exemplifies enterprise mobility integration through extensive North American channel networks. SATO Holdings Corporation occupies a specialized position in thermal printing ecosystems that complement smart label deployments across logistics verticals.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| SATO Holdings Corporation |
| Avery Dennison Corporation |
| Invengo Information Technology |
| Alien Technology Corporation |
| CCL Industries Inc. |
| Checkpoint Systems |
| All4Labels Global Packaging Group |
| Zebra Technologies Corporation |
| Others |
Cost & Logistics Intelligence
Chipless RFID substrate adoption is compressing antenna production capital requirements while redistributing manufacturing capacity toward regional converters previously excluded by semiconductor handling expertise. This production-method transition simultaneously lowers entry barriers for mid-tier suppliers and intensifies price competition in standard inlay tiers.
Pricing Analysis
Capacity additions in Mexico and Southeast Asia are reshaping price floors for passive UHF inlays. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical grades from general logistics tiers. Cost compression in standard RFID labels is intensifying because aluminum and copper foil spot pricing fluctuates with commodity markets. Retail chains and mass-market consumer goods buyers exhibit highest price sensitivity, while pharmaceutical manufacturers tolerate premium positioning for DSCSA-compliant serialization.
Supply Chain Analysis
FCC Part 15 electromagnetic compliance certification gates access to UHF RFID reader infrastructure deployments across American warehouse networks. Antenna etching draws from thin-gauge aluminum and copper foil supply concentrated in China, Germany, and Japan. PET substrate and conductive ink dependencies create single-source vulnerability for chipless RFID pilot programs. Distribution runs through converter networks in California's Inland Empire and the Northeast pharmaceutical belt, with final assembly increasingly shifting to maquiladora facilities in Nuevo León.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Smart Label Market functions as a stable compounder, with FDA DSCSA enforcement creating non-discretionary demand that insulates revenue from cyclical downturns.
For Market Incumbents: Lock in long-term adhesive substrate supply agreements with copper and aluminum foil producers to neutralize commodity volatility. Deepen backward integration into antenna manufacturing through acquisition of specialized etching facilities in Mexico. Prioritize certification investment for FCC Part 15 and Health Canada dual-compliance to preempt regulatory fragmentation. For New Entrants and Emerging Players: Cloud-native label management platforms offer the most penetrable entry vector, bypassing incumbent channel lock-in through subscription-based SaaS positioning. Target mid-market third-party logistics providers in Memphis and Louisville with bundled tag-reader-analytics offerings. Pursue chipless RFID substrate partnerships with Puerto Rico pharmaceutical contract packagers to establish reference installations. For Investors and Strategic Acquirers: Roll-up economics work for regional thermal printing specialists because FDA serialization mandates are forcing legacy facility retrofits that demand local service presence. Five-to-ten year viability hinges on multi-protocol convergence capabilities spanning passive UHF and active beaconing. Monitor Health Canada-FDA harmonization progress as inflection indicator for cross-border infrastructure consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Antenna Manufacturing | Captures margin compression from aluminum foil volatility while securing FCC-compliant etching capacity. |
| Subscription Platform Licensing | Converts California e-commerce 3PL capital expenditure into recurring revenue with health and beauty verticals. |
| Chipless RFID Substrate Partnership | Eliminates silicon die attachment steps for Puerto Rico pharmaceutical packagers, reducing production capital requirements. |
| Health Canada Dual-Certification Investment | Opens unified North American compliance pathways for cross-border pharmaceutical shipments through Ambassador Bridge corridors. |
| Battery-Assisted Passive Convergence R&D | Extends location tracking beyond passive read ranges into dynamic asset monitoring for Northeast biotech clusters. |
Research Approach
Multiple input streams — primary interviews with RFID systems integrators, pharmaceutical serialization executives, and thermal printing equipment specialists; secondary validation through FCC equipment authorization databases, FDA DSCSA guidance documents, and Health Canada regulatory notices; plus customs trade data for aluminum and copper foil imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment volumes for RFID inlays, NFC tags, and Bluetooth Low Energy beacons were cross-referenced against panel input from converter networks and 3PL procurement leads. Segmentation dimensions modeled include embedded technology type, application workflow, end-user vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to enforcement timeline impacts and infrastructure deployment lags across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for chipless RFID encoding through printable conductive inks would alter the outlook if semiconductor die attachment costs compress faster than projected. Forecasts reflect assumptions regarding FDA enforcement discretion and Health Canada harmonization velocity. A model refresh is warranted upon material change in FCC Part 15 spectrum allocation rules or aluminum spot pricing regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Smart Bottle Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Smart Packaging Market
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Global Spoil Detection-Based Smart Label Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
Smart Retail Packaging Market
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
Smart Label Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
Self Cooling Packaging Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Digital Packaging Market