
 OPP Pouches Market | 2026-2036
OPP Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
OPP Pouches Market Analytics
Modular pouch configurations with resealable closures and multi-compartment designs is rebalancing buyer choice toward convenience-oriented formats in the OPP pouches market. Amcor Plc leverages its global manufacturing footprint to dominate high-barrier OPP laminate production for shelf-stable foods. Inteplast Group anchors North American supply through vertical integration from resin extrusion to finished pouch conversion. Kleer Pak specializes in custom-printed OPP solutions for regional food brands seeking differentiated shelf presence.
OPP (oriented polypropylene) pouches are biaxially oriented polypropylene film containers, typically 30–150 microns thick, manufactured through tenter-frame stretching and heat-setting to achieve high clarity, moisture resistance, and printability for consumer goods packaging. The closure type dimension shows heat seal configurations sustaining the largest volume base due to cost efficiency in commodity food applications, while zip lock formats are expanding fastest in premium snack and pet food segments where resealability commands price premiums. Material type segmentation reveals OPP/PE laminates occupying the dominant share for moisture-sensitive goods, with OPP/CPP structures gaining ground in retort-compatible applications where thermal stability matters.
The EU's Packaging and Packaging Waste Regulation and REACH compliance requirements are forcing reformulation of adhesive layers and ink systems in OPP pouch supply chains destined for European markets. FDA food contact substance notifications govern material specifications for pouches entering US retail channels, while India's BIS certification mandates dimensional and migration testing for imported flexible packaging. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability labeling mandates that will determine which laminate structures retain market access across major economies.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing laminate producers to eliminate non-recyclable adhesive systems and migrate toward mono-material OPP structures, compressing formulation windows for converters serving European retail channels.
Growth Catalysts
- Organized Retail Expansion in India:Reliance Retail and D-Mart are industrializing fresh and snack food distribution, creating standardized pouch specifications for private-label suppliers.
- REACH Compliance Migration:Reformulation of solvent-based inks to water-based and UV-cured systems is opening retrofit demand for printing equipment across flexible packaging converters.
- Retort-Compatible OPP/CPP Laminates:Thermal stability improvements in coextruded structures are displacing aluminum foil in shelf-stable ready-meal applications.
Market Restraints
- Propylene Monomer Volatility:Crude-linked feedstock pricing for polypropylene resin creates margin compression for non-integrated converters in Southeast Asia.
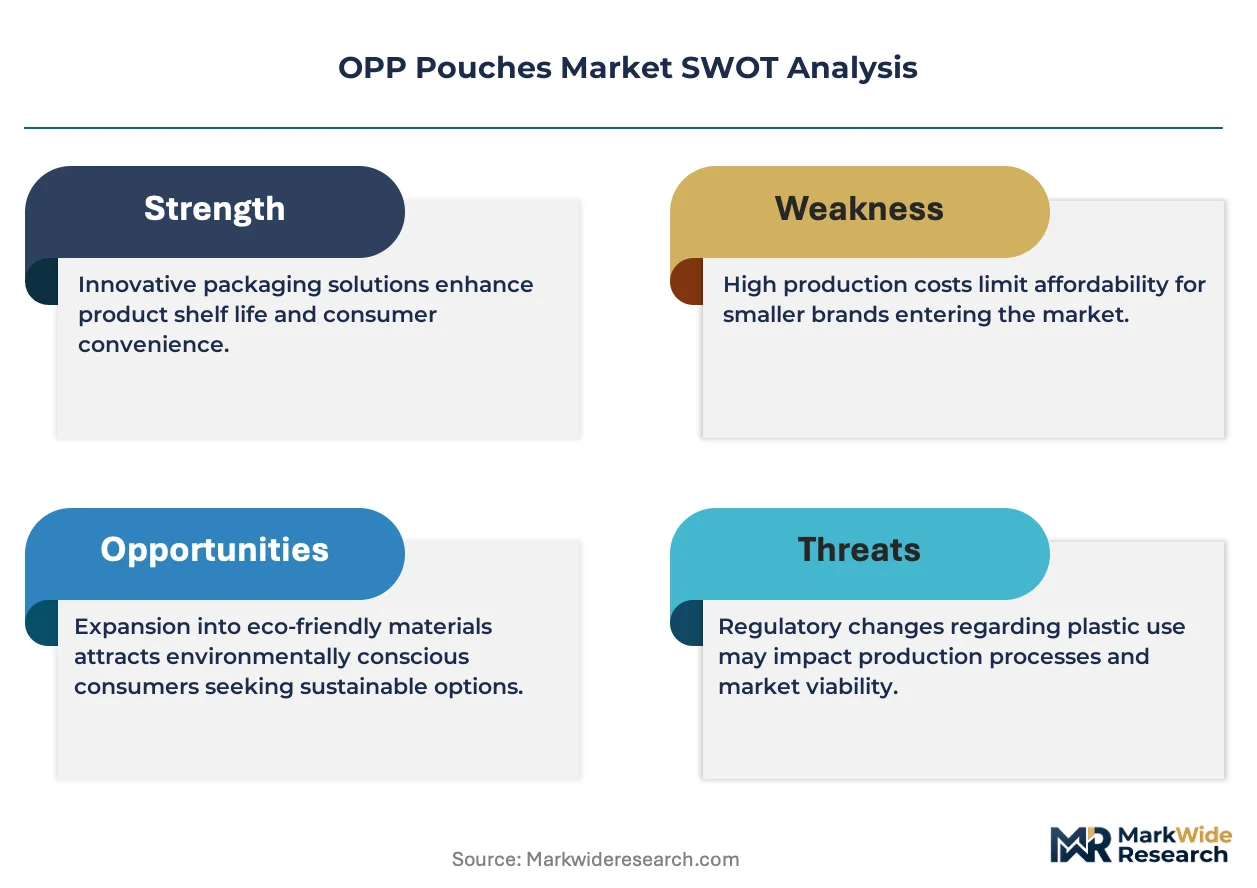
- Mechanical Recycling Contamination:Multi-layer OPP/PE/EVOH structures face technical rejection at European sorting facilities, limiting circular economy claims.
- Paper-Flexible Hybrid Substitution:Fiber-based barrier packaging from Mondi and Smurfit Kappa is capturing frozen food segments where moisture protection requirements moderate.
Strategic Opportunities
- Mono-Material Design Mandates:The EU Green Deal's recyclability targets are incentivizing OPP/OPP sealant web development for dual-stream collection systems.
- E-Commerce Fulfillment Specifications:Amazon's Frustration-Free Packaging certification is creating demand for puncture-resistant OPP mailer pouches with tear-notched openings.
- Digital Printing Convergence:HP Indigo and Xeikon press installations are enabling run-length flexibility for regional snack brands requiring SKU proliferation.
Industry Challenges
- Migration Testing Backlogs:India's BIS certification queue for imported flexible packaging extends lead times by 8-12 weeks, disrupting just-in-time supply contracts.
- Adhesive System Requalification:Converter technical teams must validate new solvent-free laminating chemistries without historical performance data for retort applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OPP Pouches Market |
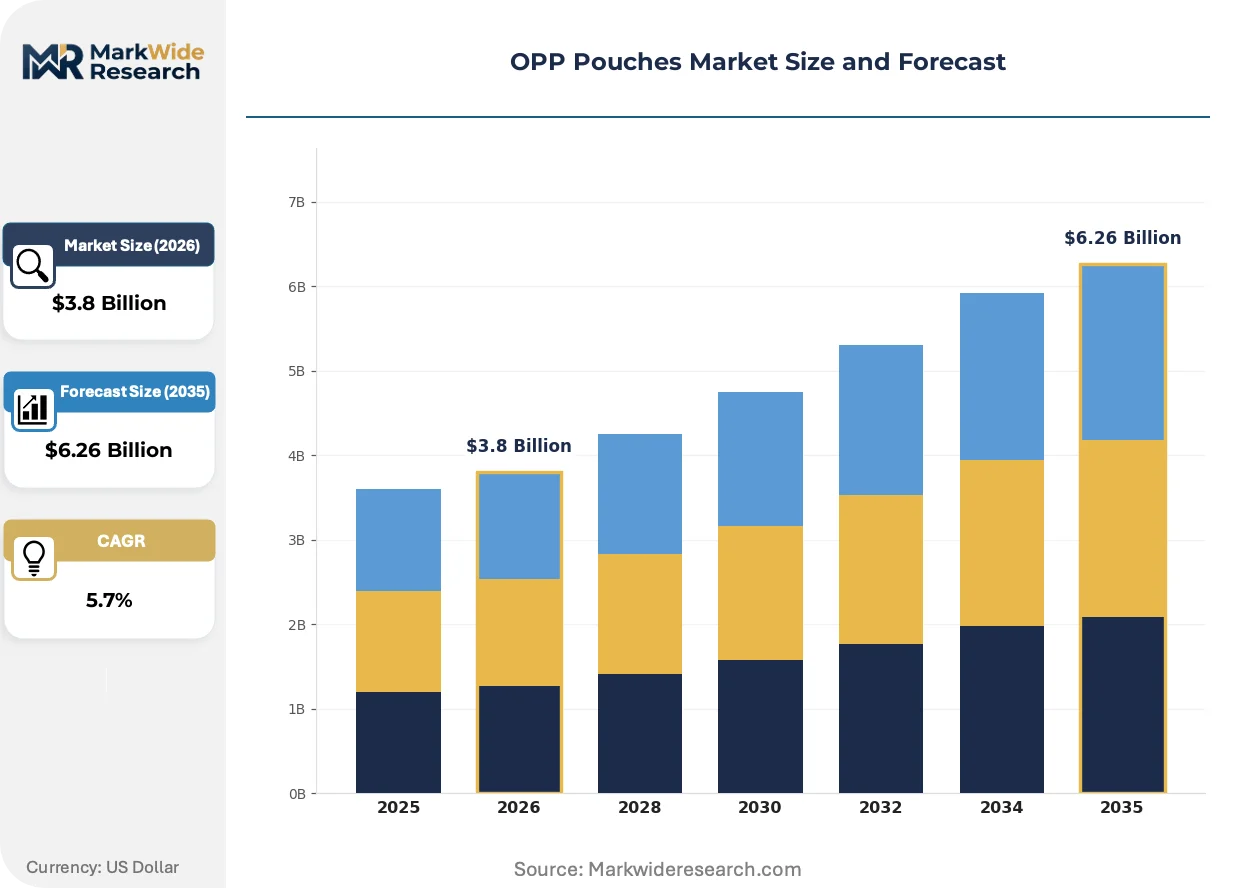
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: OPP, PE, PET, CPP Closure Type: Zip Lock, Heat Seal, Tear Notch, Press-to-Seal End Use: Food Packaging, Pharmaceuticals, Personal Care, Household Products Thickness: 50 Micron, 70 Micron, 100 Micron, 150 Micron |
| Companies Covered | Amcor Plc, United Bags, Jarrett Industries, Kleer Pak, Inteplast Group, Carepac, Johnpac Inc., Quincy Bag Co., BISON BAG Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OPP Pouches Market Evolving Landscape
Automation of quality assurance and inline inspection systems is compressing defect rates while regulatory pressure on material composition accelerates structural redesign cycles across converter operations.
Machine vision inspection with hyperspectral cameras is automating seal-integrity verification at production speeds exceeding 600 pouches per minute. Frozen vegetable packers in the Netherlands and Germany are deploying these systems to eliminate manual sampling. The technology is automating rejection protocols that previously required line stoppage, raising effective throughput without capital expansion.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are prohibiting fluoropolymer-based grease barriers in microwave popcorn and bakery applications. European converters must qualify silicone and clay-based alternatives with shorter shelf-life validation cycles. Snack food multinationals are responding by consolidating supplier audits to pre-approved substrate libraries.
Brand procurement teams are compressing supplier panels from twelve to four approved converters, demanding volume commitments in exchange for technical collaboration on sustainability roadmaps. This concentration is visible in German and French retail private-label programs, where Aldi and Carrefour have centralized flexible packaging tendering. Smaller regional converters face exclusion without mono-material development capabilities or third-party recyclability certifications.
OPP Pouches Market Segmentation
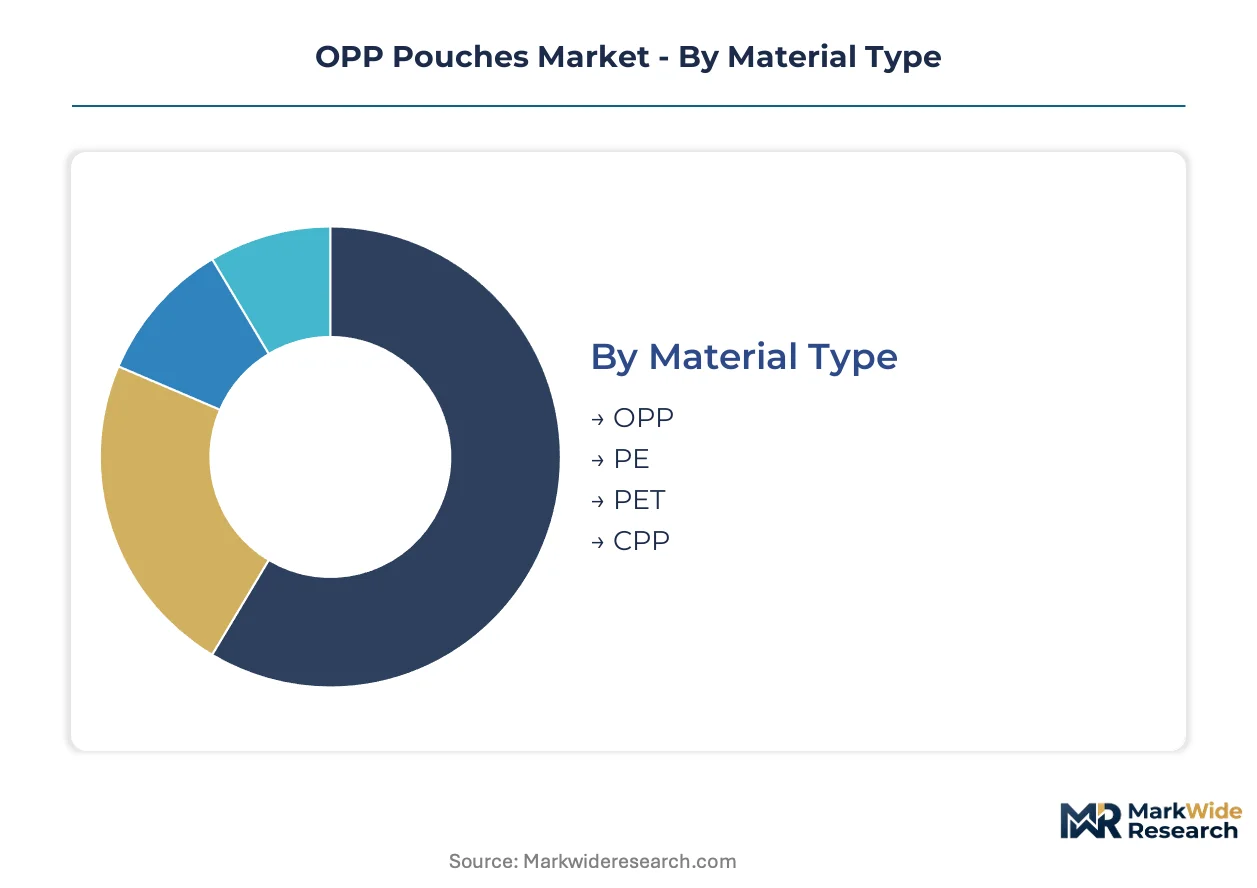
OPP pouch specifications vary sharply across material stacks and closure mechanisms, with each configuration demanding distinct extrusion, lamination, and converting investments. Converter capex decisions hinge on which segment combinations align with target end-use certifications and regional compliance mandates.
Material Type:
Capital intensity peaks with multi-layer coextrusion lines capable of OPP/PE/EVOH laminates, while mono-material OPP structures require less complex but higher-precision tenter-frame equipment.
- OPP:Biaxially oriented polypropylene film delivers the clarity and moisture barrier that dominates snack food and frozen vegetable packaging in European retail channels. German and Dutch packers specify OPP as the base web for high-speed form-fill-seal lines running above 200 cycles per minute.
- PE:Polyethylene sealant layers complete the laminate structure for heat-seal integrity in retort applications. Indian converters are adding PE extrusion capacity to serve Reliance Retail's private-label ready-meal programs.
- PET:Polyester films provide dimensional stability and print registration for premium cosmetic pouches requiring metallic decoration.
- CPP:Cast polypropylene enables thermal processing compatibility in shelf-stable curry and sauce applications across Southeast Asian export markets.
Most installed capacity flows through OPP base webs. Expansion is steepest in CPP coextrusion for retort-compatible formats.
Closure Type:
Zip lock mechanisms command the highest tooling investment per line, with integrated slider insertion equipment adding 40-60% to standard converting capex.
- Zip Lock:Resealable interlocking profiles now appear in 30-gram snack packs and 5-kilogram pet food formats alike. US premium brands specify zip lock for products commanding shelf price premiums above commodity heat-seal equivalents.
- Heat Seal:Thermal bonding remains the default for high-volume commodity applications where line speed outweighs consumer convenience. Indian biscuit and namkeen packers run heat-seal OPP pouches at throughput rates exceeding 400 units per minute.
- Tear Notch:Laser-scored opening features satisfy Amazon Frustration-Free Packaging certification requirements for e-commerce mailer pouches.
- Press-to-Seal:Adhesive strip closures bridge the cost gap between permanent heat seals and mechanical zip locks in single-serve condiment sachets.
Heat seal lines dominate current installed base. Zip lock capacity is expanding most quickly in North American pet food and premium snack segments.
End Use:
Pharmaceutical pouch production demands cleanroom-adjacent converting environments and batch traceability systems that triple quality assurance overhead versus food-grade operations.
- Food Packaging:Moisture-sensitive snacks, frozen vegetables, and shelf-stable ready meals consume the majority of OPP laminate output. EU Packaging and Packaging Waste Regulation compliance is forcing reformulation of adhesive systems in pouches bound for German and French retail channels.
- Pharmaceuticals:Unit-dose and compliance-pouch formats for OTC medications require child-resistant closure validation and migration testing documentation. India's CDSCO and BIS jointly regulate flexible packaging for drug applications.
- Personal Care:Stand-up pouches for shampoo and conditioner concentrates compete with rigid bottles on shelf differentiation and e-commerce cube efficiency.
- Household Products:Detergent pods and cleaning wipe refills specify puncture-resistant OPP/PE structures for chemical compatibility.
Food packaging commands the majority of active production lines. Pharmaceutical applications are climbing the fastest as unit-dose formats displace blister packs.
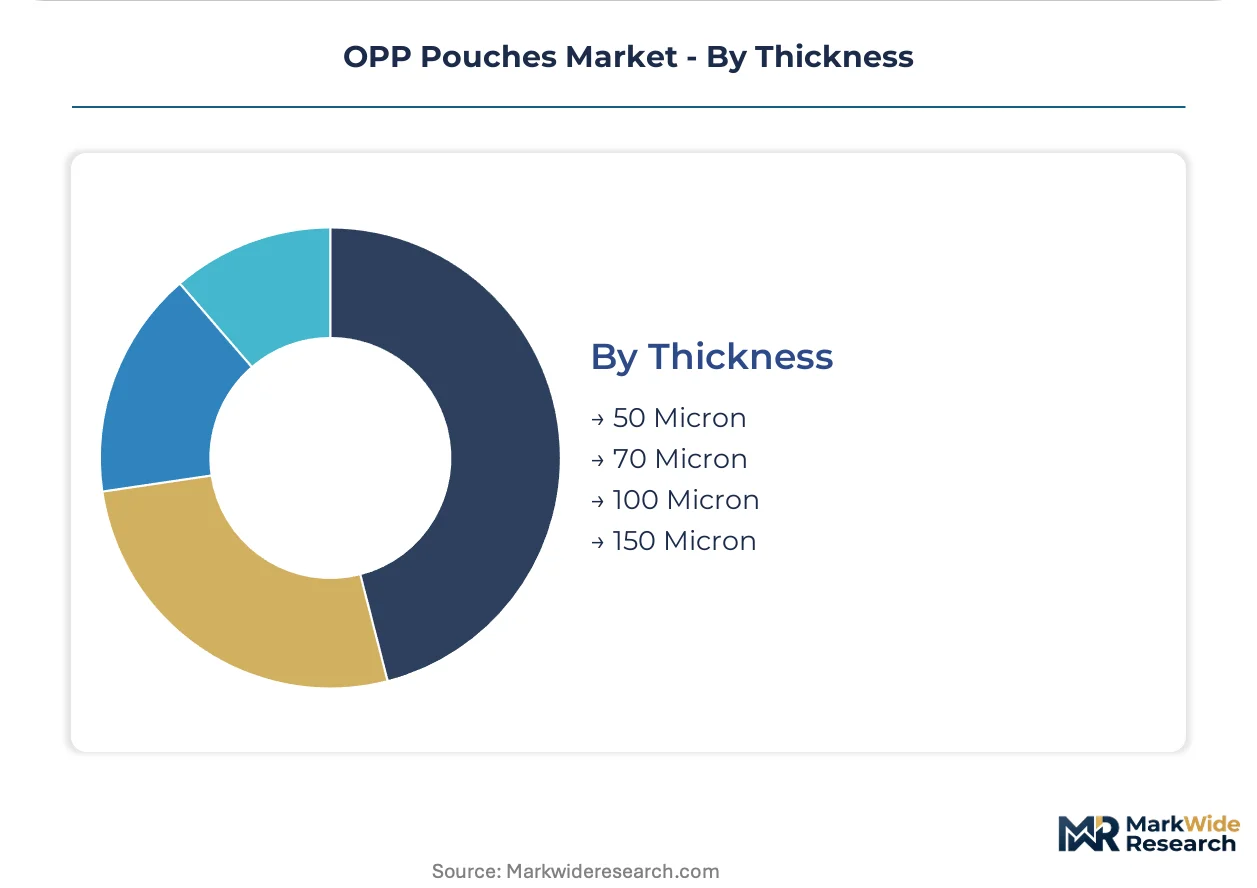
Thickness:
Gauge selection directly determines extruder output rates and resin consumption per thousand pouches, with 150-micron structures requiring 3x the polypropylene feedstock of 50-micron equivalents.
- 50 Micron:Ultra-thin specifications serve single-serve condiments and sample sachets where material minimization drives unit economics. Japanese convenience store chains specify 50-micron OPP for onigiri and sandwich packaging.
- 70 Micron:Mid-gauge structures balance puncture resistance and material efficiency for standard snack food applications.
- 100 Micron:Heavy-duty specifications protect frozen seafood and ice cream through distribution cold chains in Indian organized retail networks.
- 150 Micron:Maximum gauge enables stand-up pouch stability for liquid detergents and industrial lubricants requiring drop-test certification.
70-micron specifications flow through the most installed extrusion capacity. 100-micron production is expanding most quickly in frozen food and e-commerce fulfillment applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The OPP pouches industry traces its commercial scaling to post-war European flexible packaging development, where German and Italian converters first industrialized biaxially oriented polypropylene film for food applications. This technical foundation spread through licensing agreements to North American and Asian markets during the 1970s and 1980s.
United States
Amazon's Frustration-Free Packaging certification and Walmart's sustainability scorecards are reshaping converter specifications for e-commerce-ready pouches. FDA food contact substance notifications govern adhesive and ink formulations for pouches entering interstate commerce. Chicago-area converters supply private-label snack programs for national retailers, with zip-lock capacity expanding fastest in Wisconsin and Illinois plants.
Germany
Aldi and Carrefour procurement centralization is compressing supplier panels from twelve to four approved converters. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are prohibiting fluoropolymer grease barriers in microwave popcorn applications. The Rhine-Ruhr industrial corridor hosts Europe's densest concentration of high-barrier OPP laminate production for shelf-stable ready meals.
India
Reliance Retail and D-Mart are industrializing fresh and snack food distribution, creating standardized pouch specifications for private-label suppliers. BIS certification mandates dimensional and migration testing that extends lead times by 8-12 weeks for imported flexible packaging. Gujarat and Maharashtra house the fastest-expanding converting capacity, with Surat-based extruders adding CPP coextrusion lines for retort-compatible formats.
China
Domestic snack food industrialization and cross-border e-commerce fulfillment are driving puncture-resistant mailer pouch demand. GB standards for food contact materials regulate polypropylene migration limits in pouches for domestic retail sale. The Yangtze River Delta cluster around Shanghai concentrates the highest volume of OPP film extrusion capacity serving both domestic and export markets.
Japan
Convenience store chains specify ultra-thin 50-micron OPP for onigiri and sandwich packaging where material minimization drives unit economics. METI circular economy guidelines incentivize mono-material designs compatible with existing plastic recycling streams. The Kanto region around Tokyo maintains specialized converting capacity for premium cosmetic pouches requiring metallic decoration and precise print registration.
OPP Pouches Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier performance and sustainability certification dimensions. The vendor base organizes into three functional tiers: multinational laminate specialists with global manufacturing footprints, regional converters with vertical integration from resin to finished pouch, and niche custom-printing houses serving differentiated brand requirements. Consolidation pressure is intensifying as procurement teams demand volume commitments in exchange for technical collaboration on recyclability roadmaps. Capacity expansion and mono-material development capability acquisition represent the dominant competitive moves.
Within the multinational laminate tier, Amcor Plc and Inteplast Group exemplify divergent geographic anchoring strategies. Amcor occupies a position spanning European and Asia-Pacific retail channels with high-barrier production systems. Inteplast Group represents North American supply security through captive resin extrusion and converting integration. Kleer Pak sits within the custom-printing specialist archetype, serving regional food brands seeking shelf differentiation without multinational minimum order requirements.
| Leading Market Players |
|---|
| Amcor Plc |
| United Bags |
| Jarrett Industries |
| Kleer Pak |
| Inteplast Group |
| Carepac |
| Johnpac Inc. |
| Quincy Bag Co. |
| BISON BAG Co., Inc. |
| Others |
Value Network & Pricing Analysis
Mono-material OPP structure migration is compressing converter formulation costs while simultaneously redistributing supply power toward extruders with tenter-frame precision capabilities in Germany and China. This technical transition rewards backward-integrated producers able to control resin specification and film orientation parameters in-house.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-barrier OPP/EVOH laminates from commodity OPP/PE structures and basic mono-web formats. Price differentiation hinges on recyclability certification tier and volume commitment scale. Cost compression in standard-tier pouches is intensifying because Indian and Southeast Asian converters are adding extrusion capacity faster than brand procurement consolidation. Private-label buyers at Aldi and Carrefour exhibit highest price sensitivity, while pharmaceutical contract packers accept premiums for migration-tested documentation.
Supply Chain Analysis
Single-source vulnerability sits with propylene monomer supply concentrated in Saudi Arabia, South Korea, and the US Gulf Coast. Converter operations draw from biaxially oriented film, PE sealant resins, and solvent-free adhesive systems as critical inputs. Tariff exposure on Chinese OPP film imports into the EU and US creates margin volatility for non-integrated distributors. Distribution runs through converter-direct relationships with multinational food brands and regional private-label aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where premium pouch specifications command widening margins as EU recyclability mandates filter buyer procurement criteria toward certified mono-material suppliers.
For Market Incumbents: Anticipate procurement panel compression at German and French retailers by consolidating volume commitments with Reliance Retail and D-Mart before competitor extruders complete Gujarat capacity additions. Deepen backward integration into CPP coextrusion for retort-compatible formats to defend against aluminum foil substitution in ready-meal applications. Prioritize third-party recyclability certification investment to maintain EU market access under evolving extended producer responsibility frameworks. For New Entrants and Emerging Players: Regional snack brands requiring sub-10,000 unit digital print runs represent the most penetrable buyer archetype underserved by multinational minimum order requirements. Target North American pet food private-label programs where zip-lock pouch specifications outpace incumbent converter capacity expansion. Lead with HP Indigo press partnerships enabling SKU proliferation without legacy gravure cylinder investments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European converters lacking mono-material development capabilities but holding established relationships with Aldi and Carrefour procurement teams. Long-term viability favors targets with verified solvent-free lamination chemistries and BIS certification experience for Indian pharmaceutical pouch applications. Monitor India's CDSCO queue processing velocity as an inflection indicator for import-dependent supply chain disruption severity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material OPP/OPP Development | EU Green Deal recyclability targets force adhesive system elimination and sealant web redesign. |
| Digital Printing Press Installation | HP Indigo and Xeikon partnerships enable run-length flexibility for regional snack brand SKU proliferation. |
| CPP Coextrusion Capacity Addition | Retort-compatible thermal stability improvements displace aluminum foil in shelf-stable curry applications. |
| Third-Party Recyclability Certification | Pre-approved substrate libraries become mandatory for supplier qualification at consolidated retail procurement panels. |
| Machine Vision Quality Assurance Deployment | Hyperspectral camera systems automate seal-integrity verification exceeding 600 pouches per minute throughput. |
Research Methodology
Multiple input streams — primary interviews with extrusion plant managers, flexible packaging procurement leads at multinational food brands, and regulatory affairs specialists at BIS and CDSCO — were reconciled against secondary validation from customs trade data, SEC 10-K filings of listed converters, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up capacity estimates from tenter-frame equipment installations were triangulated with top-down demand modeling across snack food, pharmaceutical, and personal care end-use segments.
Segment-level volume and value outputs across the projection horizon reflect modeled interactions between material stack configurations, closure mechanism adoption curves, and regional compliance mandate implementation timelines. CAGRs were derived from elasticity-adjusted demand functions incorporating propylene monomer price volatility and organized retail expansion rates in India. Industry-specific forecast inputs include Amazon Frustration-Free Packaging certification penetration and REACH Annex XVII substance restriction enforcement schedules.
Underlying measurement precision varies by segment; heat-seal commodity pouch volumes carry tighter precision than emerging zip-lock pharmaceutical formats where adoption curves remain unsettled. Forecasts reflect assumptions about EU extended producer responsibility implementation timing and Indian BIS queue processing efficiency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Aluminum-Free Food Pouch Market
Pouch
Zipper Pouch Market
Pouch
Brazil Pouch Packaging Market
Pouch
Liquid Pouch Packaging Market
Pouch
Wrap-Around Packers Market
Pouch
Thailand Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Stand Up Paper Pouches Market
Pouch
Foil Pouch Packaging Market
Pouch
Open Mouth Sacks Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Russia Pouch Packaging Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Slider Zipper Pouch Market