
 Four Side Flat Pouch Market | 2026-2036
Four Side Flat Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Four Side Flat Pouch Market Analysis
Market Context
Converting technician shortages across European and North American flexible packaging plants is reorganizing production geography toward automated pouch fabrication centers. Amcor Plc leverages its integrated film extrusion and converting network to supply four side flat pouches at scale across multiple continents. Mondi Group anchors its competitive stance through fiber-based barrier innovations that reduce plastic dependency in pouch constructions. ProAmpac specializes in high-barrier multilayer structures for oxygen-sensitive food applications, competing on technical specification rather than commodity volume.
Technical Definition and Segment Structure
Four side flat pouches are sealed flexible containers with heat-sealed edges on all four sides, typically constructed from laminated films of polyethylene, polyester, or aluminum oxide-coated substrates to achieve oxygen transmission rates below 0.1 cc per square meter per day for shelf-stable goods. These pouches serve primary industrial purposes in portion-controlled food distribution, pharmaceutical unit-dose packaging, and cosmetic sample containment where flat pack-out efficiency reduces shipping cube versus bottles or cans. Composite materials command the widest functional range across barrier requirements, though paper-based laminates are gaining structural share as brand owners face EPR compliance deadlines. Food Packaging occupies the dominant application position by volume, with pharmaceutical packaging representing the fastest margin pool expansion due to FDA and EMA validation requirements for primary drug contact materials.
Regulatory Framework and Outlook
EMA stability testing guidelines for pharmaceutical primary packaging, FDA 21 CFR 177 food contact substance regulations, and EU REACH restrictions on per- and polyfluoroalkyl substances are collectively reshaping material selection criteria for four side flat pouch converters. The EU Green Deal's packaging waste reduction targets are forcing reformulation of multilayer structures toward mono-material or fiber-hybrid designs that maintain barrier performance. Stakeholders must monitor how rapidly evolving extended producer responsibility fee structures alter the total cost of ownership for composite versus recyclable mono-polymer pouch formats.
Market Dynamics
EU Green Deal packaging waste reduction targets are forcing converters to dismantle multi-layer laminate structures and rebuild them as mono-material or fiber-hybrid formats without sacrificing oxygen barrier performance below 0.1 cc per square meter per day.
Growth Catalysts
- EMA stability testing guidelines:Pharmaceutical primary packaging validation requirements in Europe are pulling high-barrier pouch demand into unit-dose drug distribution.
- Snack food automation:German manufacturers are standardizing four side flat pouch formats to maximize line speeds on robotic filling equipment.
- EPR fee structures:Extended producer responsibility frameworks in France and Italy are penalizing non-recyclable multi-layer films and rewarding mono-polymer designs.
Market Restraints
- Aluminum oxide coating supply:Deposition equipment for ultra-high barrier films concentrates among three European equipment builders, creating input bottlenecks.
- REACH substance restrictions:Per- and polyfluoroalkyl substance bans are eliminating proven grease-resistant chemistries from paper-based laminates.
- Rigid container substitution:Glass jars and metal cans retain cost advantages for ambient-stable goods in price-sensitive retail channels.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO alignment with ICH stability guidelines is opening unit-dose pouch demand for European contract manufacturers.
- Pet food premiumization:Fresh and raw pet food brands in the UK are adopting flat pouches for portion-controlled single-serve formats.
- Digital printing convergence:HP Indigo and Xeikon presses are enabling short-run SKU proliferation without cylinder changeover costs.
Industry Challenges
- Converting technician scarcity:Heat-seal calibration and laminate adhesion troubleshooting skills are retiring faster than vocational programs replace them.
- Validation timeline compression:FDA 21 CFR 177 food contact notifications and EMA stability protocols now run in parallel rather than sequence, straining regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Four Side Flat Pouch Market |
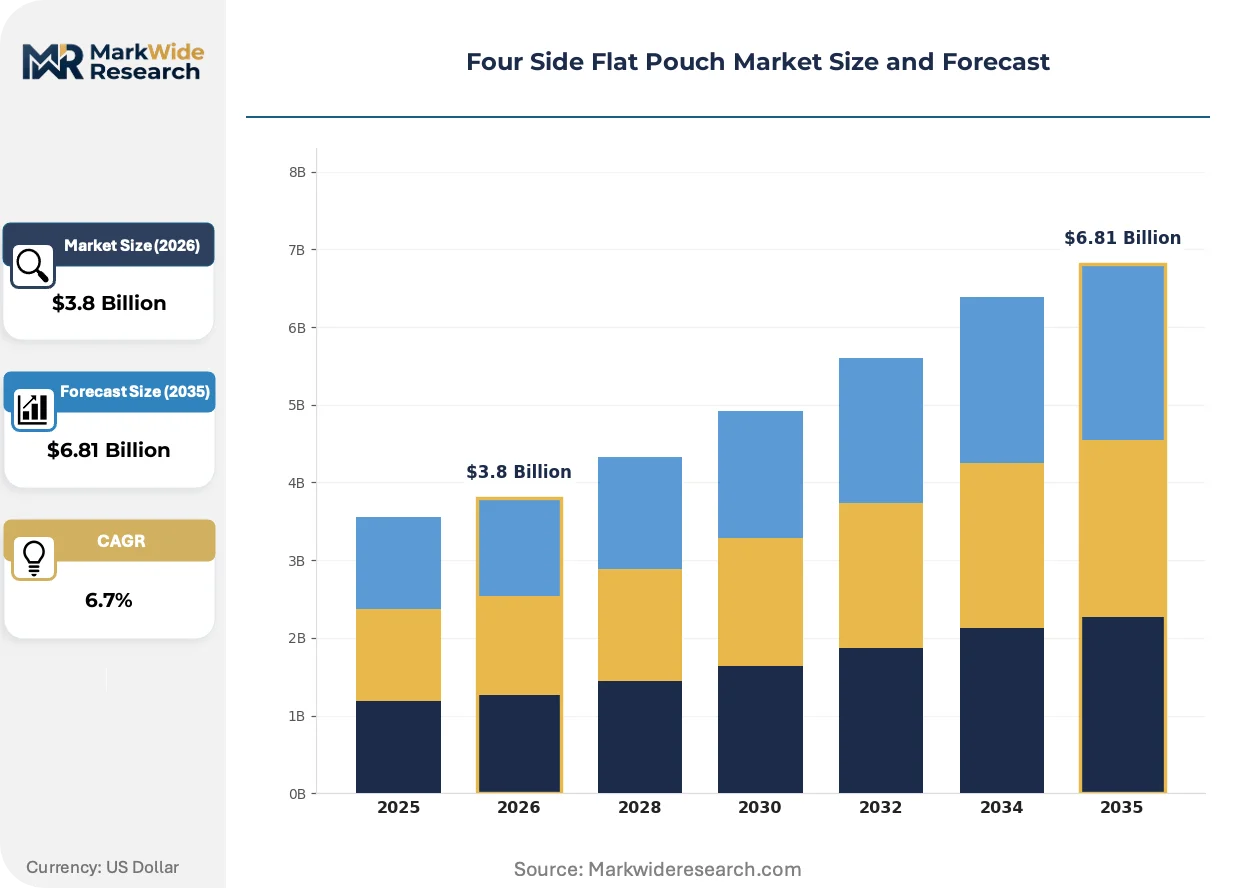
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminium, Paper, Composite Application: Food Packaging, Cosmetic Packaging, Pharmaceutical Packaging, Industrial Packaging Closure Type: Zipper, Heat Seal, Tear Notch, Velcro Capacity: 100 ml, 250 ml, 500 ml, 1 L |
| Companies Covered | Coveris, Glenroy Inc., Amcor Plc, Sonoco, Huhtamaki, Mondi Group, Sealed Air, Winpak, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Four Side Flat Pouch Market Emerging Trajectories
Barrier film architecture is fragmenting into competing technical philosophies as brand owners face incompatible regulatory timelines for recyclability versus shelf-life extension.
Water-based barrier coatings are decomposing the aluminum oxide monopoly on ultra-low oxygen transmission. Snack and pet food brands in Germany and the Netherlands are piloting silica- and clay-nanoparticle alternatives at 15-20% cost premiums. This materials transition is decomposing the capital intensity advantage of vacuum deposition equipment and opening pouch fabrication to mid-scale converters without metallization lines.
EU Packaging and Packaging Waste Regulation recyclability mandates are forcing reformulation of polyethylene-polyester laminates into mono-material polyethylene structures. French and Italian converters are investing in MDO-PE film lines to match the stiffness and printability of PET. Pharmaceutical applications lag this transition due to EMA validation requirements for existing barrier specifications.
Brand technical buyers are consolidating supplier panels and demanding integrated film extrusion-to-pouch converting capabilities. Snack food procurement teams in Germany now specify single-source accountability for seal integrity failures. This concentration is visible in automated filling line investments where pouch format standardization reduces changeover downtime.
Four Side Flat Pouch Market Segmentation
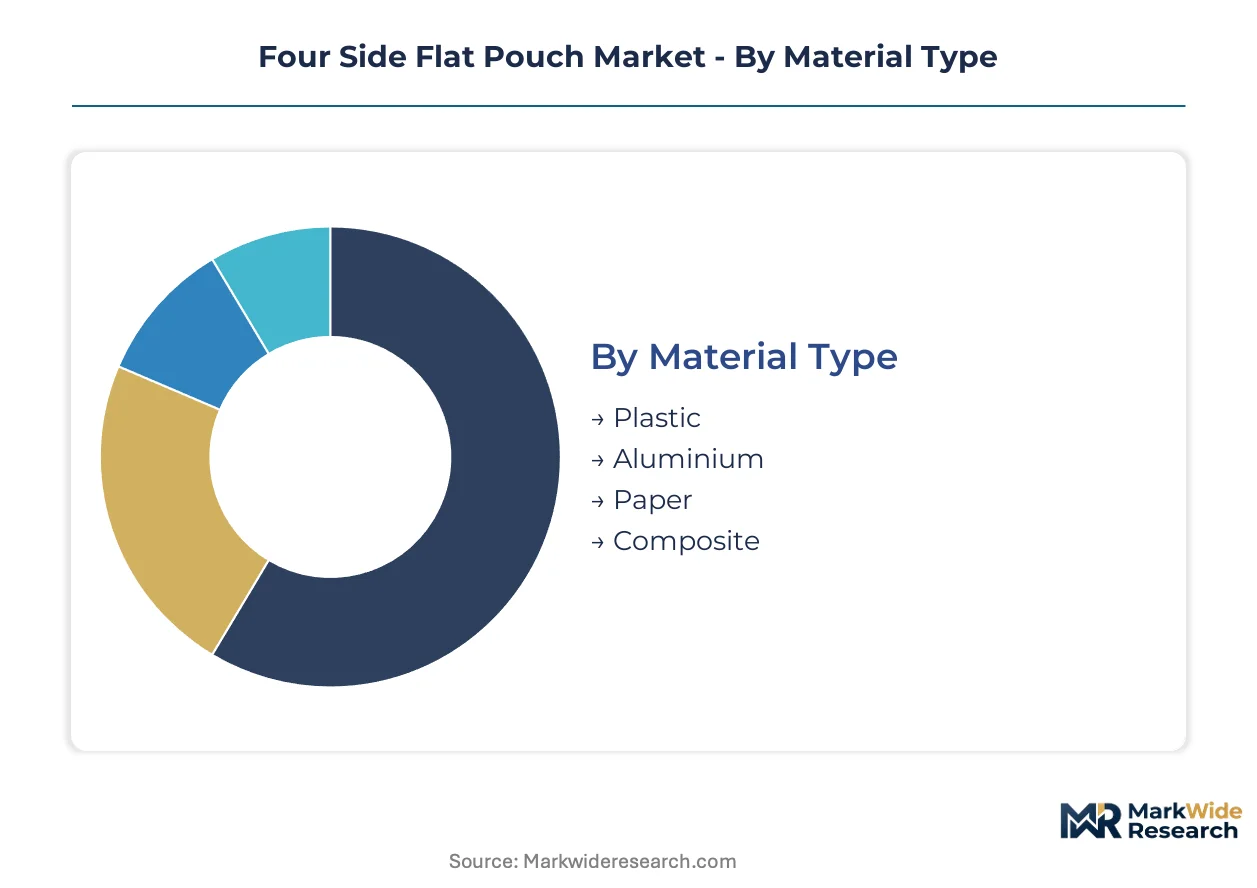
Four side flat pouch converters face divergent technical requirements across material systems and end-use validations. Segmentation reveals where regulatory compliance costs concentrate and which format specifications command automation investments from brand owners.
Material Type:
REACH substance restrictions and EPR fee structures in France and Italy are fragmenting material selection criteria across barrier performance, recyclability, and total cost of ownership.
- Plastic:Polyethylene-polyester laminates dominate oxygen-sensitive food applications with transmission rates below 0.1 cc per square meter per day. German snack manufacturers are standardizing mono-material polyethylene formats to satisfy EU Packaging and Packaging Waste Regulation recyclability mandates while maintaining line speed compatibility.
- Composite:Multi-layer structures incorporating aluminum oxide or silica coatings deliver ultra-high barrier protection for pharmaceutical unit-dose packaging. EMA stability testing guidelines are pulling demand toward validated composite constructions that pharmaceutical contract manufacturers in Germany and Switzerland specify for primary drug contact applications.
- Aluminium:Metallized films provide cost-efficient intermediate barrier solutions for ambient-stable dry goods.
- Paper:Fiber-based laminates are gaining structural share as brand owners face EPR compliance deadlines in France and Italy.
Plastic handles the majority of throughput; Composite is the fastest mover on share.
Application:
Validation timelines and automation readiness separate margin pools across end-use categories.
- Food Packaging:Portion-controlled snack distribution and pet food single-serve formats drive volume concentration. German manufacturers are maximizing robotic filling line speeds through pouch format standardization, while UK fresh pet food brands adopt flat pouches for premium positioning.
- Pharmaceutical Packaging:FDA 21 CFR 177 food contact notifications and EMA stability protocols now run in parallel, compressing validation timelines for primary drug contact materials. European contract manufacturers are expanding capacity for unit-dose pouch distribution as CDSCO alignment with ICH guidelines opens Indian pharmaceutical export channels.
- Cosmetic Packaging:Sample containment and travel-size formats emphasize flat pack-out efficiency for e-commerce distribution.
- Industrial Packaging:Chemical and component containment applications prioritize seal integrity over barrier sophistication.
Food Packaging carries the volume base; Pharmaceutical Packaging is climbing the fastest on margin expansion.
Closure Type:
Automation compatibility and reseal functionality determine specification splits across consumer convenience and industrial efficiency requirements.
- Heat Seal:Permanent sealing delivers tamper-evident protection and lowest unit cost for single-serve applications. German snack food procurement teams specify heat-seal integrity as a single-source accountability metric when consolidating supplier panels.
- Zipper:Press-to-close reseal mechanisms command premium placement in multi-serve pet food and snack categories where portion control extends product freshness.
- Tear Notch:Controlled opening features balance consumer convenience with manufacturing simplicity for mid-tier positioning.
- Velcro:Hook-and-loop closures serve specialized applications requiring repeated access without seal degradation.
Heat Seal manages the highest production throughput; Zipper is gaining share fastest on premium format adoption.
Capacity:
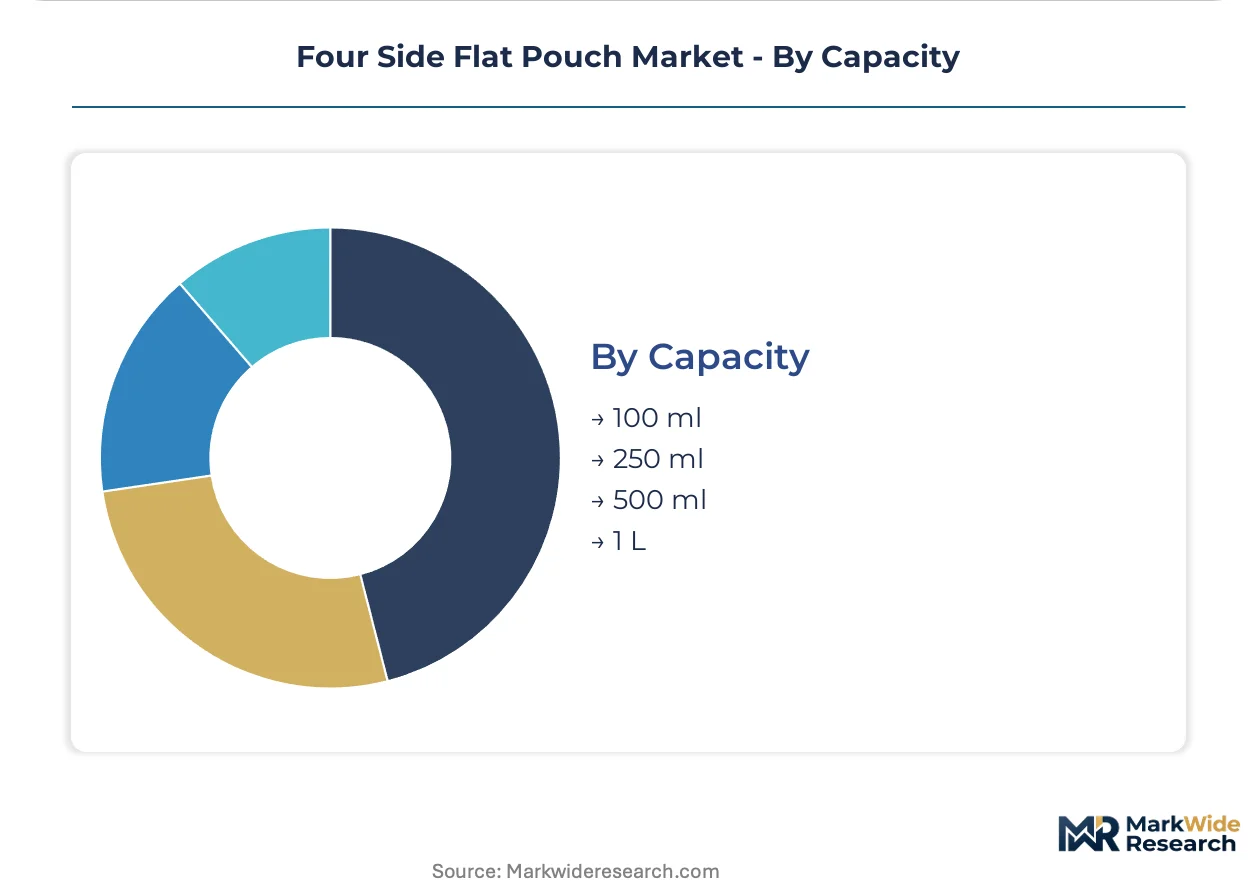
Line changeover economics and shipping cube optimization shape format selection across distribution channels.
- 500 ml:Mid-size formats balance portion control with shelf presence for mainstream snack and pet food positioning. Dutch and German brands piloting silica-nanoparticle barrier alternatives are standardizing 500 ml as the reference volume for automated filling line validation.
- 100 ml:Compact single-serve units minimize shipping cube for pharmaceutical unit-dose and cosmetic sample distribution. EMA validation requirements for primary packaging are concentrating specification authority for 100 ml formats among European contract manufacturers serving export markets.
- 250 ml:Reduced-portion formats target health-conscious snacking and premium pet food trial sizes.
- 1 L:Family-size and bulk formats serve value-positioned retail channels and institutional foodservice.
500 ml anchors production volume; 100 ml is expanding most quickly on pharmaceutical validation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes four side flat pouches differently than other markets by prioritizing automated filling line compatibility over barrier sophistication, while India and China emphasize cost-efficient mono-material formats for pharmaceutical exports.
Germany
Snack and pet food manufacturers in Baden-Württemberg and Bavaria standardize pouch formats for robotic filling equipment. The EU Packaging and Packaging Waste Regulation tightens recyclability requirements for multi-layer films. Converting capacity concentrates around Stuttgart and Munich as flexible packaging plants reorganize toward automated fabrication centers.
United States
Pharmaceutical contract manufacturers drive unit-dose pouch demand for oxygen-sensitive drug distribution. FDA 21 CFR 177 food contact substance regulations govern material selection for primary packaging applications. Production clusters in New Jersey and North Carolina expand validation capacity for export markets.
India
CDSCO alignment with ICH stability guidelines opens pharmaceutical export channels for European contract manufacturers. The country's national pharmaceutical regulator enforces stability testing protocols for primary drug contact materials. Manufacturing concentrates in Maharashtra and Gujarat where mid-scale converters invest in barrier coating alternatives.
China
Domestic snack brands adopt flat pouches for portion-controlled distribution in tier-one cities. GB standards and SAMR regulations shape food contact material compliance requirements. Yangtze River Delta converters pilot silica-nanoparticle barrier coatings at 15-20% cost premiums over aluminum oxide.
France
EPR fee structures penalize non-recyclable multi-layer films and reward mono-polymer designs for ambient-stable goods. ANSM pharmaceutical packaging guidelines influence barrier specification for unit-dose applications. Industrial activity clusters in Île-de-France and Auvergne-Rhône-Alpes as converters invest in MDO-PE film lines.
Four Side Flat Pouch Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in four side flat pouch supply. The upper tier commands film extrusion-through-converting integration that single-source accountability demands now require. Mid-scale specialists compete on barrier coating innovation and short-run digital printing flexibility. Dominant competitive moves include backward integration into film extrusion and geographic expansion through contract manufacturing partnerships.
Among European-based integrated players, Amcor Plc and Mondi Group exemplify the film-to-pouch control archetype, while ProAmpac occupies a position within the high-barrier specialist tier. These three anchors represent how competitive positioning fragments between scale-driven integration and technical specification depth.
| Leading Market Players |
|---|
| Coveris |
| Glenroy Inc. |
| Amcor Plc |
| Sonoco |
| Huhtamaki |
| Mondi Group |
| Sealed Air |
| Winpak |
| ProAmpac |
| Others |
Supply Flow & Price Mechanics
Sixty-day aluminum oxide deposition equipment lead times in European barrier film manufacturing concentrate pricing power among three equipment builders and force converters into long-term offtake commitments for high-barrier pouch production. This supply bottleneck amplifies cost premiums for ultra-low oxygen transmission specifications while pushing mid-scale converters toward silica-nanoparticle alternatives.
Pricing Analysis
Long-term offtake contracts dominate high-barrier pouch procurement between German pharmaceutical contract manufacturers and integrated film-to-pouch suppliers, while spot purchasing persists for commodity snack food formats. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated pharmaceutical specifications from automated-line-compatible food formats and generic industrial containment. Pricing pressure stems from REACH substance restrictions eliminating proven chemistries and forcing reformulation investments. Snack food procurement teams exhibit highest price sensitivity due to rigid container substitution threats, while pharmaceutical buyers prioritize validation continuity over unit cost.
Supply Chain Analysis
Inventory compression to three-week film stockpiles in Stuttgart and Munich converting clusters reflects just-in-time coordination with MDO-PE film line investments. Supply concentrates in Germany, France, and China, with German converters anchoring automated fabrication and Chinese manufacturers piloting nanoparticle barrier alternatives. Raw material dependencies center on polyethylene resin, polyester film, and aluminum oxide deposition capacity. Single-source vulnerability concentrates in European vacuum deposition equipment builders. Distribution runs through direct mill-to-filler relationships for automated line compatibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pouch format standardization across German robotic filling lines creates platform-economics dynamics where interoperability specifications determine supplier panel inclusion. This ecosystem shift rewards integrated film-to-pouch players with single-source accountability capabilities.
For Market Incumbents: Compound barrier coating innovation investments to defend against silica-nanoparticle displacement of aluminum oxide deposition. Prioritize backward integration into MDO-PE film extrusion to capture EPR fee structure advantages in France and Italy. Consolidate supplier panels around automated filling line validation partnerships. For New Entrants and Emerging Players: Anchor in UK fresh pet food premiumization as the most penetrable white-space segment, where portion-controlled single-serve formats lack established high-barrier supply relationships. Target digital printing convergence for short-run SKU proliferation without cylinder changeover costs. Pursue contract manufacturing partnerships with European pharmaceutical exporters serving Indian CDSCO-aligned markets. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EPR fee structures and REACH substance restrictions will continuously reshape material specifications and reward reformulation capabilities. Acquisition target archetype: mid-scale converters with validated barrier coating alternatives and digital printing infrastructure. Watch EMA stability testing guideline revisions as the inflection signal for pharmaceutical pouch demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDO-PE Film Extrusion | Captures EU Packaging and Packaging Waste Regulation recyclability premiums in France and Italy. |
| Barrier Coating Alternative Validation | Silica-nanoparticle pilot programs in Germany and Netherlands decompose aluminum oxide equipment bottlenecks. |
| Automated Filling Line Format Standardization | German snack manufacturers specify single-source accountability for seal integrity failures. |
| Digital Printing Infrastructure Investment | HP Indigo and Xeikon presses enable short-run pharmaceutical unit-dose SKU proliferation. |
| Contract Manufacturing Partnership Expansion | European pharmaceutical exporters leverage CDSCO alignment for Indian market access. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with flexible packaging plant managers, converting technicians, pharmaceutical regulatory affairs leads, and snack food procurement directors; and secondary validation through EU Packaging and Packaging Waste Regulation filings, EMA stability testing guideline documents, FDA 21 CFR 177 food contact notifications, and customs trade data on film laminate imports. Bottom-up capacity assessments at Stuttgart and Munich converting clusters were triangulated against top-down demand modeling from German robotic filling line installation records.
Across the projection horizon, the analytical framework modeled volume and value trajectories by material type, application, closure mechanism, and capacity tier, with additional segmentation by regulatory compliance cluster. CAGRs were derived from regression analysis of historical capacity additions correlated with EPR fee structure implementation timelines. Forecast inputs incorporated aluminum oxide deposition equipment order backlogs and MDO-PE film line investment announcements.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal packaging waste reduction target enforcement and stable REACH substance restriction timelines; material deviation would warrant model refresh. Specific risk factors include accelerated per- and polyfluoroalkyl substance bans and unexpected EMA validation protocol revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Global Boil-In Bags Market
Pouch
Feminine Care Pouch Film Market
Pouch
Poland Pouch Packaging Market
Pouch
UAE Pouch Packaging Market
Pouch
Foil Zipper Bags Market
Pouch
Twist Wrap Packaging Market
Pouch
Flexible Pouch Market
Pouch
Canada Pouch Packaging Market
Pouch
Italy Pouch Packaging Market
Pouch
Stick Pouches Packaging Market
Pouch
Squeeze Pouch Market
Pouch
Flexible Plastic Pouches Market
Pouch
Liquid Pouch Packaging Market
Pouch
Feed Pouches Market
Pouch
Heat Seal Pouch Market
Pouch
Child Resistant Pouches Market