
 Portion Control Packs Market | 2026-2036
Portion Control Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Portion Control Packs Market Outlook
The portion control packs sector is recalibrating around a widening gap between premium branded formats and commodity private-label supply. Amcor Plc leverages its global film and laminate infrastructure to serve multinational quick-service accounts with customized barrier specifications. Berry Global Inc. sustains volume leadership in injection-molded condiment cups through captive resin sourcing and distributed manufacturing. Sealed Air Corporation differentiates via active packaging technologies that extend shelf stability for high-value sauce and dairy applications.
Portion control packs are precision-manufactured single-unit or multi-unit containers, typically ranging from 5 milliliters to 250 milliliters in fill volume, engineered from plastic films, aluminum foils, or molded substrates to deliver exact product quantities with minimal waste. Their primary commercial purpose centers on food safety assurance, inventory control, and labor reduction across food service and retail channels. Single-serve formats dominate volume throughput in quick-service and institutional catering, while biodegradable materials represent the fastest-expanding material class as operators confront extended producer responsibility frameworks. The food service application segment anchors margin pools due to contract-based procurement and specification lock-in, whereas retail multi-packs compete primarily on shelf impact and household penetration.
The FDA governs food-contact substance compliance under 21 CFR, while the EPA regulates per- and polyfluoroalkyl substance phaseouts affecting grease-resistant coatings. The EU F-Gas Regulation and REACH restrictions on intentionally added microplastics are reshaping material qualification requirements for exporters. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York, as these jurisdictions typically prefigure broader federal packaging mandates.
Market Dynamics
Quick-service restaurant chains are consolidating procurement around pre-portioned formats to offset labor inflation, while the EU Single-Use Plastics Directive forces substrate transitions that fragment supplier qualifications across export markets.
Growth Catalysts
- Food service labor compression:Quick-service operators in the United States are expanding single-serve condiment programs to reduce front-of-house staffing requirements and standardize portion consistency.
- REACH microplastic restrictions:The EU's tightening controls on intentionally added microplastics are accelerating demand for certified biodegradable barrier films in export-bound packaging.
- Active packaging integration:Shelf-life extension technologies for high-value sauce and dairy applications are penetrating institutional catering contracts where waste reduction carries financial penalties.
Market Restraints
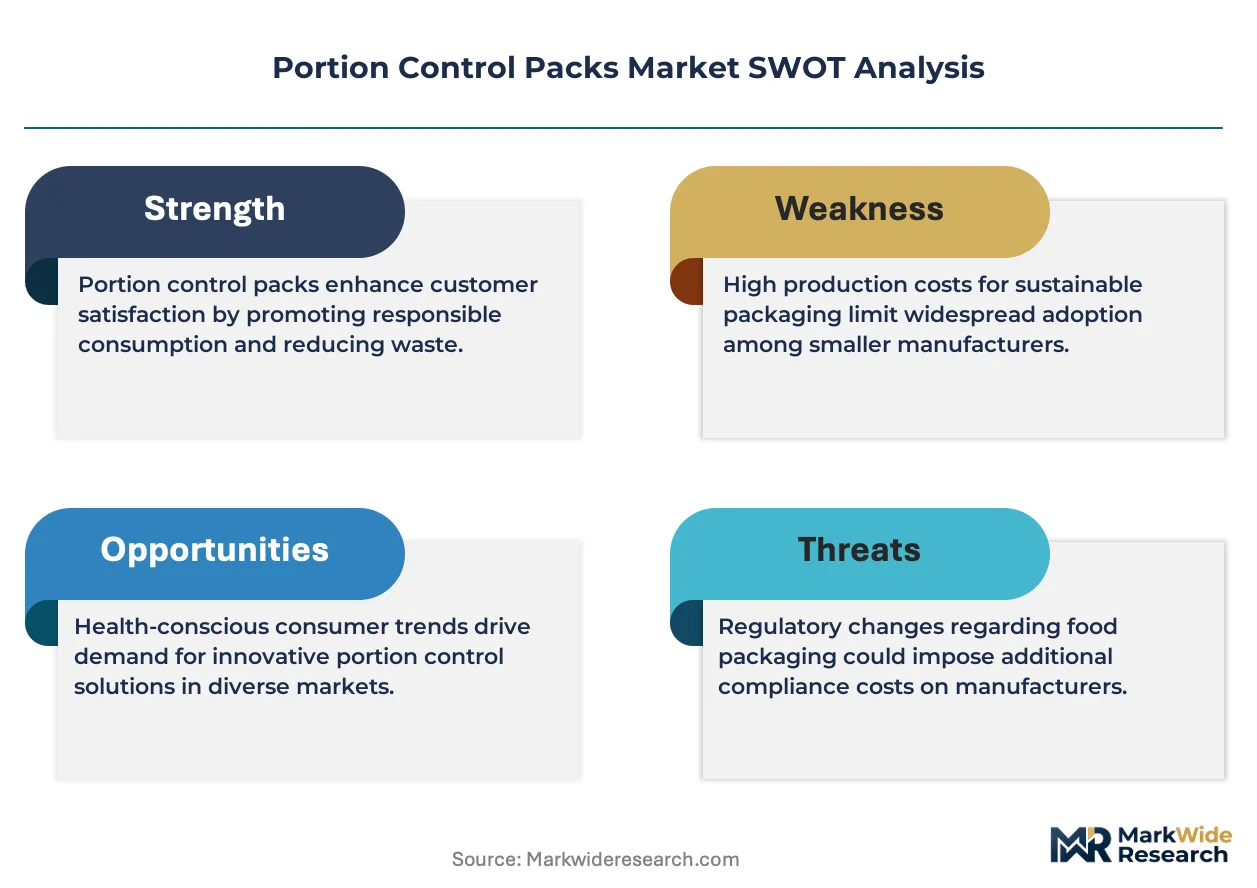
- Resin input volatility:Captive sourcing advantages favor integrated converters, leaving independent molders exposed to polyethylene and polypropylene price swings without volume hedges.
- F-Gas Regulation compliance costs:EU restrictions on fluorinated greenhouse gases are eliminating conventional grease-resistant coatings, forcing reformulation investments that commodity suppliers cannot absorb.
- Aluminum foil substitution pressure:High-barrier retort pouches are displacing formed foil lids in premium sauce segments, compressing margins for legacy laminate producers.
Strategic Opportunities
- California EPR pre-positioning:The state's extended producer responsibility legislation is creating first-mover advantages for domestic converters with verified recycling pathway documentation.
- Healthcare institutional expansion:Hospital and long-term care facilities are adopting single-serve condiment and supplement formats to reduce cross-contamination risk and simplify dietary compliance.
- Film-to-molded convergence:Thermoformed barrier trays with integrated lidding are capturing multi-component meal kit applications previously served by flexible pouch assemblies.
Industry Challenges
- Compostable certification timelines:ASTM D6400 and EN 13432 validation cycles stretch 18-24 months, delaying commercialization of novel biodegradable substrates.
- Legacy filling line retrofit costs:Narrow-web form-fill-seal equipment requires mechanical modification to handle plant-based films with divergent seal initiation temperatures and elongation profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portion Control Packs Market |
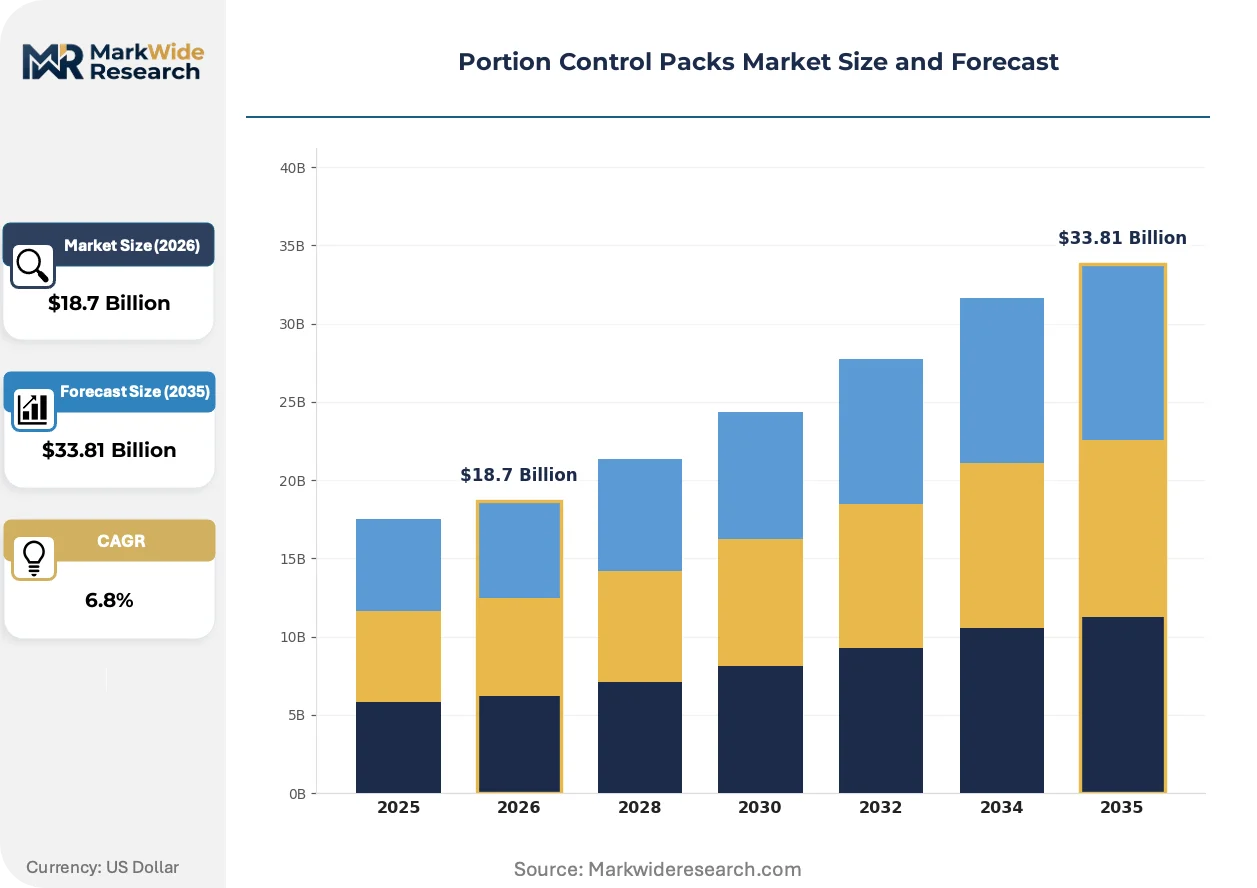
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve, Multi-Pack, Reusable, Disposable Material: Plastic, Glass, Aluminum, Biodegradable Application: Food Service, Retail, Home Use, Catering Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Amcor Plc, Berry Global Inc., Sealed Air Corporation, Mondi Group, Nestlé S.A., The Kraft Heinz Company, Mondelez International, Inc., Unilever PLC, PepsiCo, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portion Control Packs Market Strategic Shifts
Material science advances and regulatory phaseouts are converging to reshape substrate selection, with automation and compliance documentation becoming primary competitive differentiators rather than secondary cost centers.
High-speed vision inspection integrated with form-fill-seal lines is automating defect detection for seal integrity and fill accuracy in condiment cup production. Quick-service chains with centralized commissary operations are deploying these systems at throughput rates exceeding 600 units per minute. The technology is automating quality assurance staffing reductions while generating the traceability data required by FDA Food Safety Modernization Act documentation mandates.
The EPA's per- and polyfluoroalkyl substance phaseout under TSCA Section 6 is eliminating long-chain fluorochemical treatments from grease-resistant paperboard and molded fiber formats. Converters serving export markets must now qualify alternative barrier coatings against both FDA 21 CFR food-contact requirements and EU REACH restrictions on intentionally added microplastics. Quick-service brands with transatlantic supply chains are consolidating specifications around mineral-oil-free, fluorine-free substrates to avoid dual inventory stocks.
Specification lock-in through multi-year equipment lease agreements is tightening buyer-supplier relationships in the food service channel. Large operators are trading volume commitments for dedicated production slots and custom barrier development, displacing spot-market purchasing. The United States quick-service segment exhibits this pattern most acutely, where three-year beverage and condiment supply contracts now routinely include packaging exclusivity clauses.
Portion Control Packs Market Segmentation
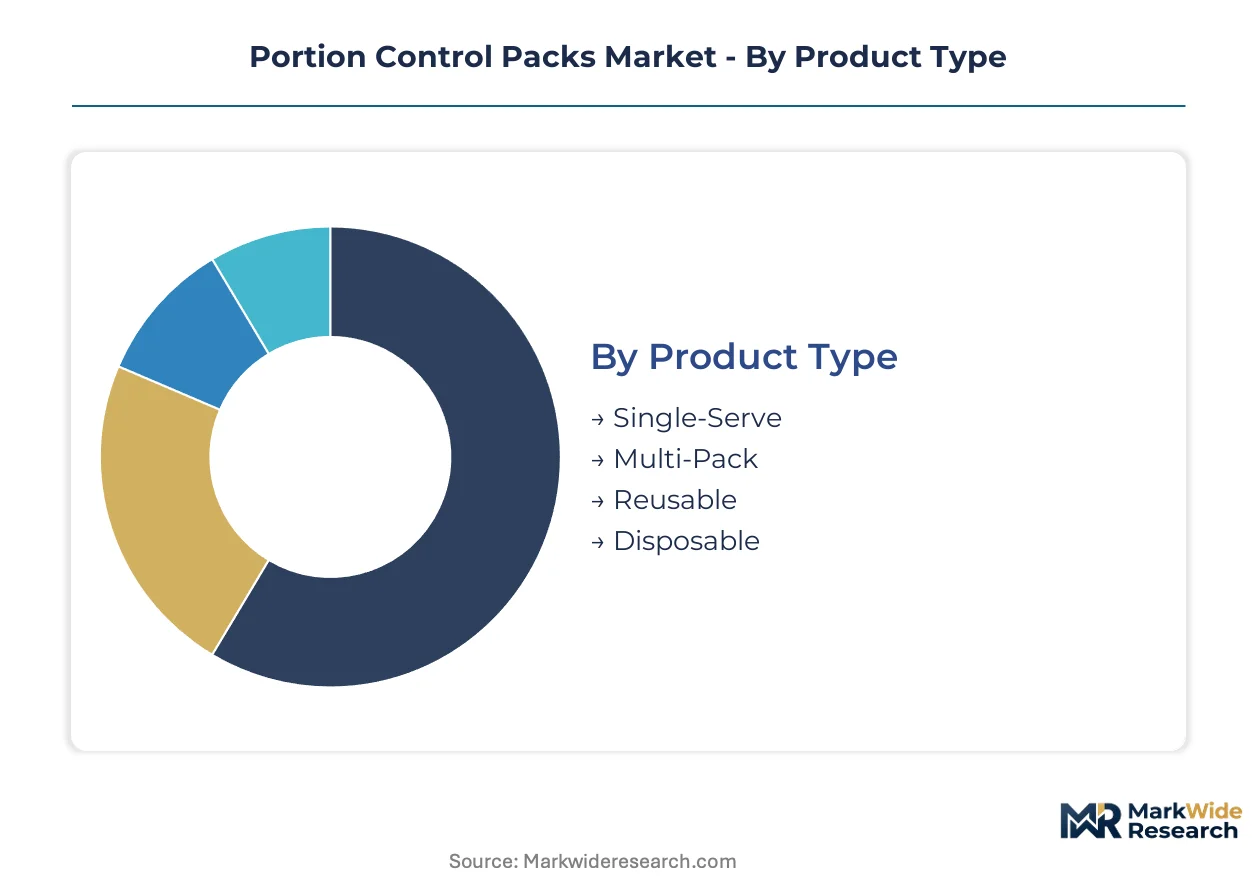
Segmentation in portion control packs reveals how procurement specifications diverge between labor-constrained food service operators and household consumers prioritizing convenience. Material transitions and format preferences are reshaping supplier qualification requirements across end-use channels.
Product Type:
Format selection tracks directly to staffing economics and consumption occasion frequency, with operators trading unit cost against labor savings and waste reduction.
- Single-Serve:Individual-unit formats ranging from 5 to 250 milliliters, typically film-sealed or lidded cups. Quick-service chains in the United States are expanding condiment programs to reduce front-of-house labor requirements and standardize portion consistency.
- Multi-Pack:Bundled configurations of 4 to 12 units for retail shelf presence and household inventory management. Supermarket buyers favor these formats for condiment and sauce categories where trial-size purchasing drives category penetration.
- Reusable:Durable containers designed for wash-cycle reuse in institutional settings. Healthcare facilities specify these for dietary supplement dispensing to reduce per-patient packaging waste.
- Disposable:Single-use formats engineered for cost minimization in high-throughput catering. Event catering operators prioritize these for post-service cleanup efficiency.
Volume sits with Single-Serve; growth tilts toward Multi-Pack.
Material:
Substrate decisions are increasingly governed by regulatory phaseouts rather than purely functional performance, fragmenting supplier qualifications across export markets.
- Plastic:Polyethylene and polypropylene films and injection-molded substrates dominate current throughput. FDA 21 CFR compliance remains baseline for food-contact applications, though EPA per- and polyfluoroalkyl substance phaseouts are eliminating conventional grease-resistant grades.
- Biodegradable:Certified compostable films and molded fiber formats qualifying under ASTM D6400 or EN 13432. EU REACH restrictions on intentionally added microplastics are accelerating qualification timelines for export-bound supply chains.
- Aluminum:High-barrier foils for retort and extended-shelf-life applications. Premium sauce segments are seeing displacement pressure from film-based alternatives.
- Glass:Premium-positioned jars and bottles for retail condiment categories. Specialty retail channels specify these for perceived quality differentiation.
Plastic retains volume leadership; biodegradable substrates are climbing the fastest.
Application:
End-use channel economics determine specification rigor, with contract-based procurement enabling custom barrier development in food service versus spot-market purchasing in retail.
- Food Service:Quick-service, institutional catering, and hospitality procurement with specification lock-in through multi-year agreements. Three-year supply contracts now routinely include packaging exclusivity clauses.
- Retail:Supermarket and mass-merchandise shelf placement competing on household penetration and visual impact. Private-label programs dominate volume in condiment categories.
- Catering:Event and contract catering with variable batch requirements and compressed delivery windows. Operators prioritize disposables for post-service efficiency.
- Home Use:Direct-to-consumer and subscription formats emphasizing portion precision for dietary management. Meal kit assemblers specify these for recipe-component accuracy.
Food Service commands margin concentration; Retail drives absolute unit volume.
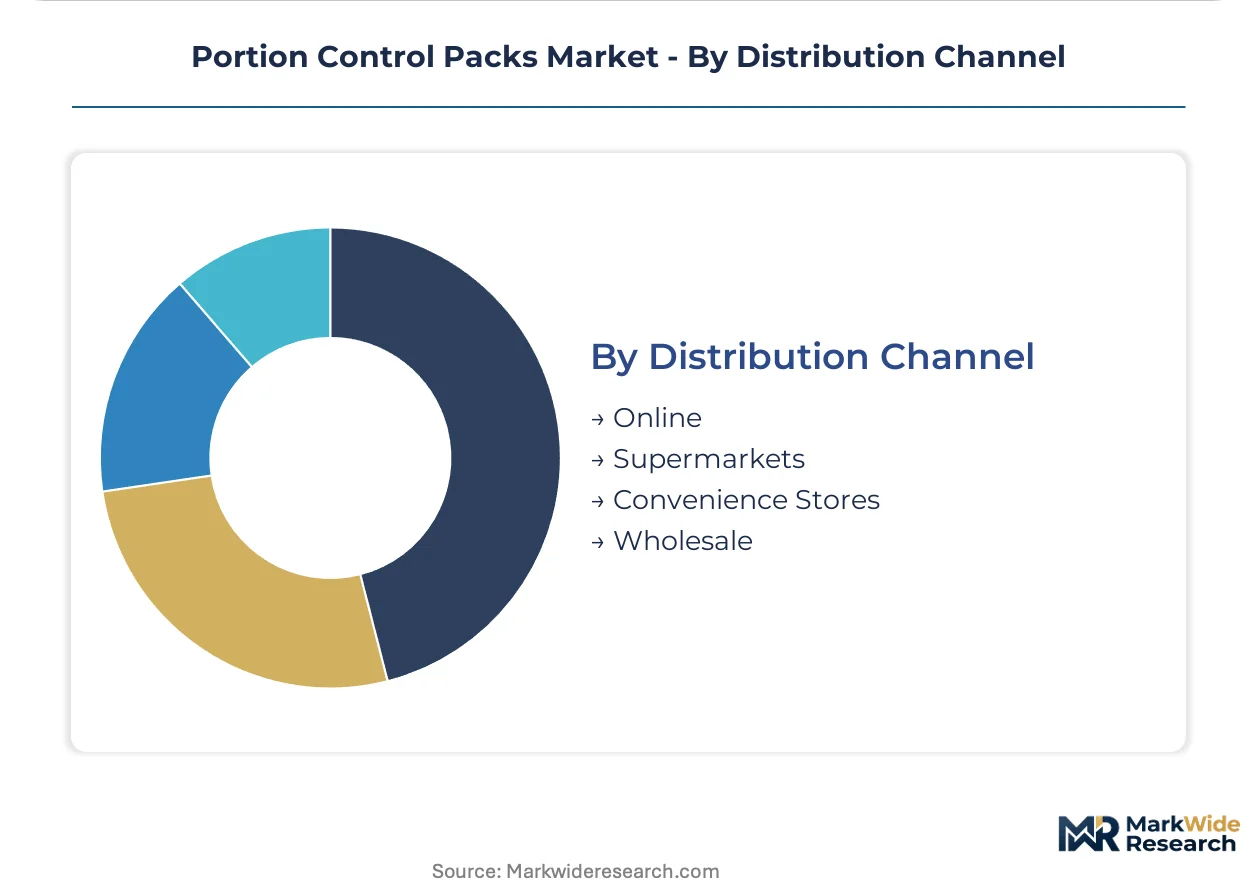
Distribution Channel:
Channel selection reflects buyer scale and replenishment velocity, with wholesale consolidating procurement for multi-unit operators and e-commerce capturing trial-size demand.
- Wholesale:Broadline and specialty food service distributors serving multi-location operators. Quick-service chains consolidate procurement through these channels for volume leverage.
- Supermarkets:Grocery retail with planogram-driven shelf allocation and seasonal promotional cycles. Multi-pack formats dominate this channel for condiment and sauce categories.
- Online:Direct-to-consumer and marketplace platforms capturing trial-size and subscription demand. Specialty dietary brands prioritize this channel for portion-controlled supplement formats.
- Convenience Stores:Grab-and-go retail with space-constrained merchandising. Single-serve condiment and sauce packets serve impulse and immediate-consumption occasions.
Wholesale anchors contract value; Online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's food service manufacturing corridor anchors North American portion control pack demand, with commissary operations and quick-service headquarters driving specification development for pre-portioned formats.
United States
Quick-service chains in the Southeast and Midwest are expanding single-serve condiment programs to reduce front-of-house labor requirements. The FDA's 21 CFR food-contact substance compliance mandates shape substrate qualification timelines. Dallas-Fort Worth hosts concentrated flexible packaging conversion capacity serving national quick-service accounts.
Germany
Industrial catering operators in Bavaria and North Rhine-Westphalia prioritize biodegradable formats for corporate campus dining contracts. The EU F-Gas Regulation eliminates conventional grease-resistant coatings, forcing reformulation investments. Hamburg's port logistics infrastructure supports import-export packaging material flows for transatlantic supply chains.
China
Food delivery platforms in the Yangtze River Delta and Pearl River Delta generate massive throughput for single-serve sauce and seasoning formats. The country's national food safety regulator enforces GB standards for food-contact materials. Shenzhen's manufacturing clusters produce high-volume injection-molded condiment cups for domestic quick-service expansion.
India
Institutional catering in Maharashtra and Karnataka adopts portion-controlled formats for IT campus and hospital feeding programs. The FSSAI governs food-contact compliance for domestic and export-bound packaging. Ahmedabad's chemical and polymer processing base supplies biodegradable film substrates to regional converters.
Brazil
Event catering operators in São Paulo and Rio de Janeiro prioritize disposable formats for post-service cleanup efficiency in high-volume entertainment venues. The national health surveillance agency regulates food-contact material safety for institutional feeding. Curitiba's packaging machinery cluster supports regional form-fill-seal equipment deployment.
Portion Control Packs Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the portion control packs sector, with integrated resin-to-converter operations holding input cost advantages over independent molders. The market structure tilts toward consolidation among multinational flexible packaging groups, while regional specialists capture niche biodegradable certification segments. Three archetypes dominate: integrated resin converters with captive sourcing, technology licensors of active packaging systems, and compliance-focused biodegradable substrate specialists. Capacity expansion and strategic partnerships constitute the primary competitive vectors as operators seek to lock in multi-year supply contracts.
Among Australia-based packaging multinationals, Amcor Plc represents the integrated converter archetype with global film and laminate infrastructure. Berry Global Inc., a US-incorporated entity, exemplifies scale-driven injection molding capacity distributed across regional manufacturing nodes. Sealed Air Corporation occupies a technology-forward position, anchoring the active packaging tier with shelf-life extension capabilities for high-value applications.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Mondi Group |
| Nestlé S.A. |
| The Kraft Heinz Company |
| Mondelez International, Inc. |
| Unilever PLC |
| PepsiCo, Inc. |
| Others |
Value Chain & Pricing Dynamics
High-speed vision inspection integration across form-fill-seal lines is compressing quality assurance staffing costs while simultaneously concentrating production among capitalized converters capable of deploying 600-unit-per-minute systems. This automation transition favors multinational flexible packaging groups with centralized commissary relationships, fragmenting spot-market suppliers unable to absorb retrofit investments.
Pricing Analysis
Outcome-based pricing tied to shelf-life extension performance anchors premium tiers for active packaging technologies in high-value sauce and dairy applications. Three-tier pricing structure across premium, standard, and economy levels separates certified biodegradable barrier films from conventional polyethylene grades and commodity private-label supply. Cost compression in standard tiers is intensifying because independent molders lack captive resin sourcing to hedge polyethylene and polypropylene volatility. Quick-service chains with multi-year exclusivity contracts exhibit lowest price sensitivity, while event catering operators purchasing spot-market disposables face margin erosion from input cost pass-through.
Supply Chain Analysis
Returns and refurbishment flows for reusable institutional formats remain underdeveloped, creating stranded asset risk for healthcare facilities with wash-cycle infrastructure. Raw material supply draws from Saudi Arabia and Qatar for virgin polyethylene feedstock, China's petrochemical complexes for polypropylene resin, and Germany's polymer processing base for engineered barrier films. Single-source vulnerability concentrates in EU-certified biodegradable film substrates, where ASTM D6400 and EN 13432 validation cycles stretch 18-24 months. Distribution runs through broadline food service distributors consolidating procurement for multi-location quick-service operators, with direct-to-manufacturer relationships tightening for accounts with dedicated production slot commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU F-Gas Regulation compliance costs and extended producer responsibility frameworks are forcing commodity suppliers without reformulation capabilities toward exit or acquisition.
For Market Incumbents: Deepen specification lock-in through multi-year equipment lease agreements that trade volume commitments for dedicated production slots and custom barrier development. Captive resin sourcing and backward integration into polymer processing insulates margin pools from input volatility that independent molders cannot hedge, displacing spot-market competitors unable to absorb ASTM D6400 certification timelines. For New Entrants and Emerging Players: Active packaging integration for shelf-life extension serves as a technology-first wedge into institutional catering contracts where waste reduction carries financial penalties. Healthcare long-term care facilities present the most penetrable white-space target for single-serve supplement formats, with regulatory compliance documentation rather than unit cost serving as the primary go-to-market angle against established food service suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational flexible packaging groups seeking biodegradable certification capabilities and regional manufacturing nodes. Five-to-ten-year viability favors converters with verified recycling pathway documentation pre-positioned for California extended producer responsibility enforcement. Practitioners should monitor state-level packaging mandate prefiguration patterns for early signals of federal policy convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Certification | ASTM D6400 and EN 13432 validation unlocks EU export eligibility for transatlantic supply chains. |
| Active Packaging Technology Licensing | Shelf-life extension capabilities penetrate institutional catering contracts with waste reduction penalties. |
| Captive Resin Sourcing Integration | Backward control over polyethylene and polypropylene feedstock hedges margin compression from volatility. |
| Healthcare Channel Expansion | Hospital and long-term care facilities adopt single-serve formats for cross-contamination risk reduction. |
| California EPR Pre-Positioning | Verified recycling pathway documentation creates first-mover advantage before federal mandate convergence. |
Study Parameters
Trade databases, regulatory filing repositories, and food service procurement records formed the secondary backbone for demand quantification and material flow mapping. Primary interviews with quick-service procurement directors, flexible packaging plant managers, regulatory compliance officers at converters, and healthcare food service administrators validated specification trends and contract structures. Bottom-up volume estimates from form-fill-seal equipment deployment rates and top-down cross-checks against resin consumption data were triangulated to anchor market sizing.
Historical trendline analysis of quick-service condiment program expansion and biodegradable substrate adoption rates informed projection assumptions across the analysis window. Segmentation dimensions modeled include product format, material substrate class, end-use channel, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating labor cost inflation coefficients and extended producer responsibility implementation timelines. Forecast inputs included EU REACH microplastic restriction enforcement patterns and FDA per- and polyfluoroalkyl substance phaseout schedules.
Several conditions sit outside the modeled scope, including breakthrough barrier coating technologies that circumvent current fluorine-free limitations and abrupt shifts in quick-service front-of-house automation investment. Forecasts reflect documented assumptions about certification timeline stability and resin price volatility bands. Practitioners should monitor state-level extended producer responsibility legislative progression and alternative barrier coating commercialization for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Retort Pouch Market
Pouch
Liquid Pouch Packaging Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Latin America Pouch Packaging Market
Pouch
Stand Up Paper Pouches Market
Pouch
Spain Pouch Packaging Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Paper Pouch Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Russia Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
Fin Seal Pouches Market
Pouch
Clear Pouches Market