

Horizontal Premade Pouch Packing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Premade Pouch Packing Machine Market Insights
Food-grade stainless steel construction with IP65 washdown certification is collapsing the gap between entry-level and premium horizontal premade pouch packing systems. Mespack leverages captive manufacturing of servo-driven filling modules to sustain margin control across European pharmaceutical accounts. Viking Masek anchors its competitive position through specialized rotary configurations for frozen food processors in North America. SN Maschinenbau differentiates via extended R&D intensity in continuous-motion designs for high-output snack lines.
A horizontal premade pouch packing machine feeds pre-formed flexible pouches through a linear or rotary transport system, then opens, fills, and seals them at speeds ranging from 30 to 200 cycles per minute depending on motion type and servo configuration; its primary purpose centers on automating shelf-ready packaging for moisture-sensitive and oxygen-sensitive goods across food, pharmaceutical, and personal care sectors. Servo-driven product types now lead capital expenditure flows as converters replace pneumatic legacy lines to cut changeover times and reduce film waste. Pharmaceutical packing applications represent the fastest-growing segment category, driven by serialization mandates and child-resistant closure integration that favor programmable PLC control architectures over mechanical alternatives.
FDA validation protocols for pharmaceutical contact surfaces and EMA Annex 1 sterile manufacturing guidelines are tightening qualification requirements for pouch packing equipment sold into regulated end uses, forcing OEMs to pre-integrate audit trails and electronic signature capture. The EU Machinery Directive and ISO 13849 safety standards further shape design priorities for interlocked guarding and fail-safe pneumatic exhausting across export-bound systems. Buyers must weigh total cost of ownership against validation support depth when selecting between European, Japanese, and North American supplier bases.
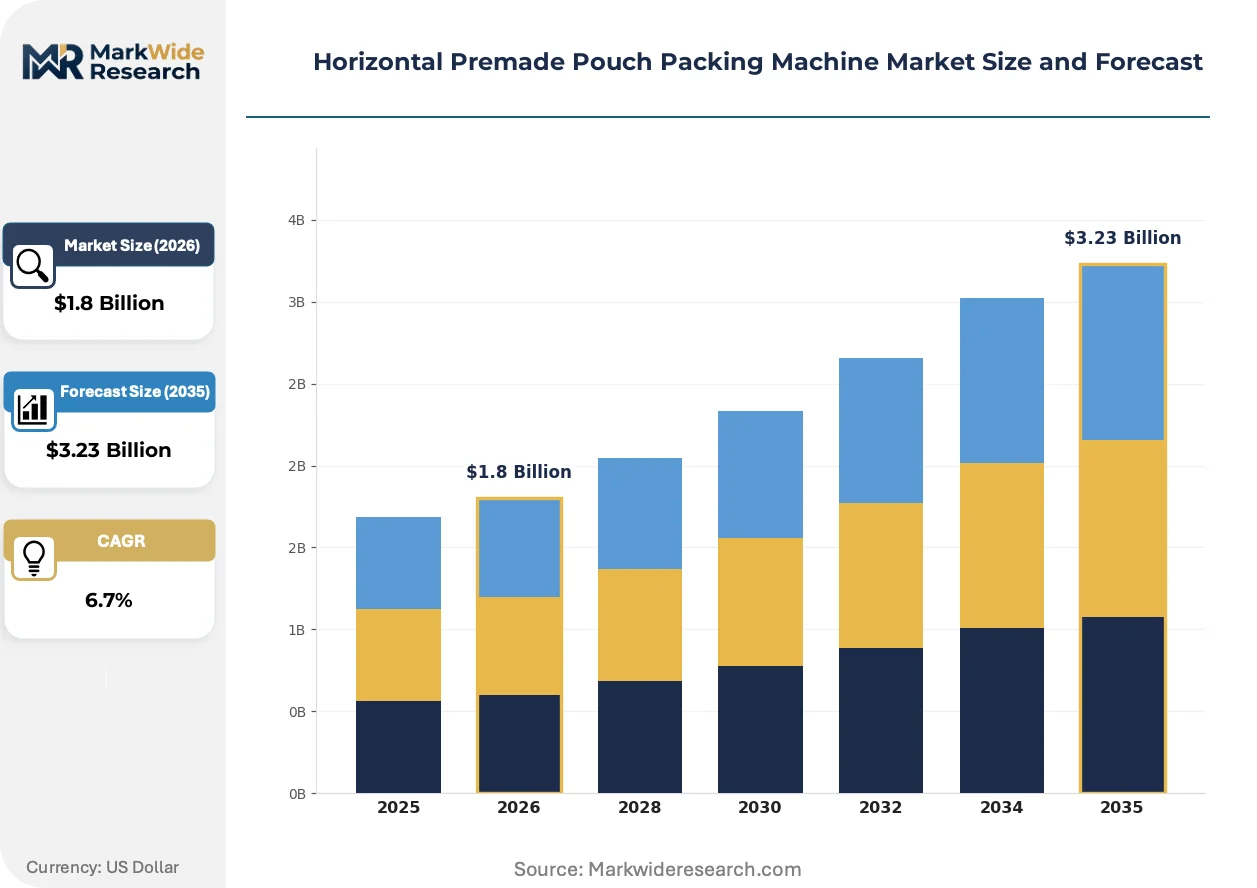
Market Dynamics
Servo-driven automation architectures are compressing changeover windows and forcing pneumatic legacy lines into obsolescence across pharmaceutical and food processing facilities.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:Pharmaceutical converters in Germany and Switzerland are retrofitting lines with continuous-motion servo configurations to satisfy updated aseptic validation protocols.
- Child-resistant closure integration:Personal care manufacturers in Japan are specifying programmable PLC architectures that accommodate tamper-evident zipper mechanisms without mechanical cam replacement.
- Frozen food shelf-life extension:High-barrier metallized film adoption across North American processors is pulling demand for vacuum-compatible pouch handling systems with oxygen transmission rate below 0.5 cc/m²/day.
Market Restraints
- Stainless steel input cost volatility:Food-grade 316L sheet and sanitary tubing price swings from Chinese and South Korean mills are compressing OEM margins on IP65-certified washdown systems.
- Validation documentation burden:FDA 21 CFR Part 11 electronic record requirements impose six-to-nine-month qualification timelines that extend pharmaceutical sales cycles and strain smaller European equipment builders.
- Flexible format substitution:Thermoform-fill-seal lines for single-serve pharmaceutical unit doses are capturing share from pouch formats in high-volume sterile applications.
Strategic Opportunities
- Indian pharmaceutical export expansion:CDSCO serialization mandates and EU-GMP upgrade programs are creating pull for mid-speed servo lines with integrated track-and-trace modules in Ahmedabad and Hyderabad clusters.
- Retort pouch protein formats:Shelf-stable meat and seafood applications in Thailand and Vietnam are opening demand for rotary configurations with overpressure sterilization compatibility.
- EU Green Deal packaging waste targets:Mono-material recyclable pouch specifications are incentivizing OEMs to develop sealing jaw geometries optimized for polyethylene-based structures.
Industry Challenges
- Servo motion programming expertise gap:Shortage of technicians fluent in Rockwell, Siemens, and Beckhoff drive commissioning is extending installation timelines and inflating aftermarket service costs.
- Legacy pneumatic line integration friction:Food processors with 1990s-era intermittent-motion machines face control architecture mismatches when adding modern vision inspection and checkweigher modules.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Premade Pouch Packing Machine Market Trends and Innovations
Continuous-motion mechanical designs are ceding ground to modular servo architectures that enable format changeover without tool replacement, reshaping capital deployment patterns across high-output packaging operations.
Collaborative robot loading stations are fragmenting the traditional boundary between primary packaging and secondary case packing. Snack and confectionery processors in the Netherlands and Belgium are deploying Universal Robots and FANUC cobot arms for fragile product gentle handling at 80-120 picks per minute. This convergence is collapsing the historical separation between pouch packing OEMs and robotic integrators, forcing equipment builders to pre-certify third-party safety systems.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling European converters to validate heat-seal jaw coatings that eliminate PTFE-based non-stick surfaces. Equipment suppliers in Italy and Germany are qualifying ceramic and plasma-coated sealing bar alternatives that maintain release properties across 10 million cycle lifespans. Pharmaceutical and organic food segments are driving specification priority for PFAS-free contact surfaces ahead of anticipated US EPA action under TSCA Section 6.
Converter procurement committees are unbundling aftermarket service contracts from initial capital purchases, compressing OEM recurring revenue streams. Mid-sized North American co-packers are negotiating hourly-rate technical support agreements separate from parts-and-labor warranties, favoring regional service depots over manufacturer-direct coverage. This behavioral shift is most pronounced in California and Texas food processing corridors where third-party maintenance specialists have built certified technician networks.
Horizontal Premade Pouch Packing Machine Market Segmentation
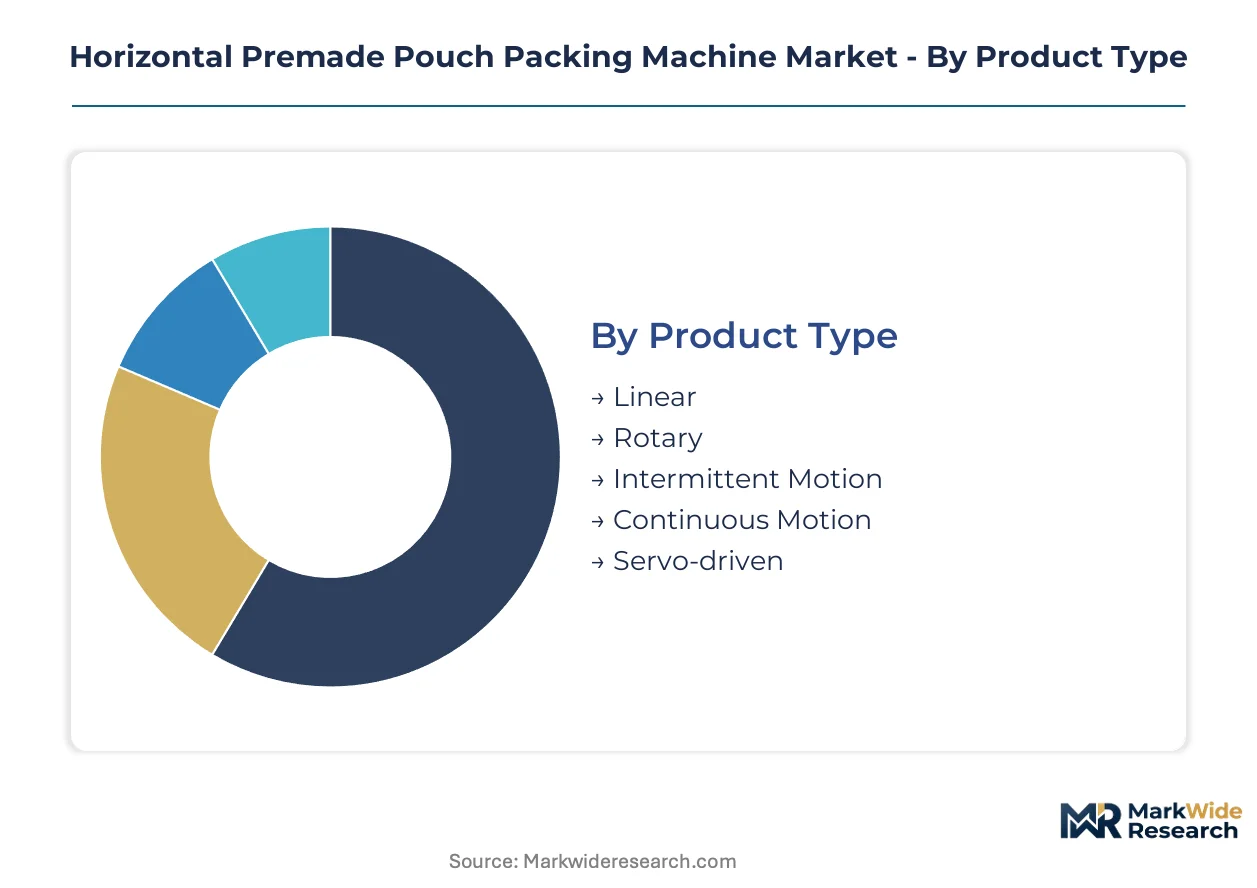
Horizontal premade pouch packing machine procurement flows through distinct technical and application channels, with servo-driven architectures and pharmaceutical end uses commanding premium positioning. Channel mix varies sharply by validation burden, changeover frequency, and output volume requirements across converter operations.
Product Type:
Equipment selection channels split between high-volume continuous-motion lines for dedicated production and flexible intermittent-motion systems for contract packers managing frequent format switches.
- Continuous Motion:Mechanical transport maintains pouch flow without stopping during fill and seal cycles, enabling rated speeds above 150 cycles per minute. German pharmaceutical converters specify these configurations for aseptic vial and sachet lines under EMA Annex 1 sterile manufacturing guidelines. By volume, Continuous Motion leads. By growth pace, Servo-driven is expanding most quickly.
- Servo-driven:Independent axis control replaces mechanical cams and linkages, permitting electronic format changeover without physical tooling swaps. Japanese personal care manufacturers deploy these systems for child-resistant closure integration requiring programmable motion profiles. By volume, Continuous Motion leads. By growth pace, Servo-driven is expanding most quickly.
- Linear:Straight-line pouch transport with intermittent dwell stations for open-fill-seal operations.
- Rotary:Circular turret configuration indexing pouches through discrete processing stations.
- Intermittent Motion:Start-stop transport cycle allowing precise filling accuracy for fragile or viscous products.
Cost tiers separate premium servo architectures from standard pneumatic and economy mechanical cam systems.
Technology:
Control architecture investments track regulatory complexity, with pharmaceutical accounts prioritizing audit-capable PLC platforms over simpler pneumatic alternatives.
- PLC Control:Programmable logic controllers with embedded recipe management and electronic signature capture support FDA 21 CFR Part 11 validation requirements. Swiss and German pharmaceutical OEMs specify Rockwell and Siemens architectures for serialization line integration. PLC Control captures the largest installed base. Sensor Based technology is climbing the fastest.
- Servo Motor:Brushless AC servomotors with absolute encoders deliver sub-millimeter positioning repeatability for precision filling applications. North American frozen food processors adopt these drives to reduce film waste during acceleration and deceleration phases. PLC Control captures the largest installed base. Sensor Based technology is climbing the fastest.
- Pneumatic:Compressed air actuation for clamping, opening, and sealing functions in legacy intermittent-motion designs.
- Touch Screen Interface:HMI panels enabling operator parameter adjustment without programming terminal access.
- Sensor Based:Vision and proximity sensing arrays for pouch presence detection, fill level verification, and seal integrity inspection.
Application requirements dictate technology stacking, with pharmaceutical validation driving multi-layer control redundancy.
Application:
End-use channel concentration shapes equipment specification, with moisture-sensitive and oxygen-sensitive goods demanding specialized barrier film handling.
- Pharmaceutical Packing:Aseptic filling of unit-dose powders, liquids, and lyophilized products with integrated serialization and tamper-evident sealing. German and Swiss contract manufacturers specify continuous-motion servo lines to meet EMA Annex 1 qualification timelines. Pharmaceutical Packing commands the highest average selling prices. Food Packaging moves the largest unit volumes.
- Food Packaging:Shelf-stable snacks, frozen vegetables, and retort-ready proteins requiring high-barrier metallized film compatibility. Thai and Vietnamese seafood processors drive rotary configuration demand for overpressure sterilization cycles. Pharmaceutical Packing commands the highest average selling prices. Food Packaging moves the largest unit volumes.
- Cosmetics Filling:Viscous creams, serums, and single-use sample sachets with precision dosing requirements.
- Chemical Packaging:Aggressive detergent and agrochemical formulations necessitating corrosion-resistant contact surfaces.
- Pet Food Packing:High-moisture wet food and treat formats with oxygen scavenger integration for extended shelf life.
Customer maturity separates validated pharmaceutical installations from price-sensitive commodity food operations.
End User Industry:
Industry verticals concentrate demand through distinct procurement channels, with nutraceuticals bridging regulatory rigor and volume scale.
- Fast Moving Consumer Goods:High-volume snack, confectionery, and beverage concentrate operations requiring 24/7 reliability and rapid format changeover. Dutch and Belgian processors deploy collaborative robot loading stations for fragile product gentle handling at 80-120 picks per minute. Fast Moving Consumer Goods dominates unit shipments. Nutraceuticals posts the steepest expansion trajectory.
- Nutraceuticals:Dietary supplements, functional foods, and probiotic formats straddling food and pharmaceutical regulatory boundaries. Indian exporters in Ahmedabad and Hyderabad clusters specify mid-speed servo lines with CDSCO-mandated track-and-trace modules for EU-GMP compliance. Fast Moving Consumer Goods dominates unit shipments. Nutraceuticals posts the steepest expansion trajectory.
- Personal Care:Wipes, masks, and liquid personal hygiene products with child-resistant and tamper-evident closure specifications.
- Agrochemicals:Pesticide, fertilizer, and seed treatment formulations requiring chemical-resistant sealing jaw coatings.
- Household Products:Detergent pods, cleaning wipes, and air care formats with fragrance retention and moisture barrier requirements.
Supply concentration in European and Japanese OEM bases limits vendor options for validated pharmaceutical and personal care applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German pharmaceutical converters absorb premium pricing for validated servo systems, while Indian contract packers prioritize mid-speed lines with modular upgrade paths. Japanese personal care manufacturers fall between these poles, specifying programmable architectures without continuous-motion premiums.
United States
Frozen food processors in Wisconsin and California drive vacuum-compatible pouch system procurement for high-barrier metallized films. FDA 21 CFR Part 11 electronic record requirements extend qualification timelines to six-to-nine months for pharmaceutical installations. The Pacific Northwest corridor concentrates demand for IP65 washdown-certified systems serving organic food co-packers.
Germany
EMA Annex 1 sterile manufacturing guidelines are forcing retrofits of continuous-motion servo configurations across Baden-Württemberg pharmaceutical clusters. Swissmedic cross-border compliance requirements shape equipment specifications for contract manufacturers near the Swiss frontier. The Stuttgart region anchors demand for aseptic filling lines with integrated serialization modules.
Japan
Personal care manufacturers in the Kanto region specify programmable PLC architectures for child-resistant closure integration. METI industrial automation incentives accelerate pneumatic-to-servo conversions across Osaka packaging districts. The Nagoya corridor concentrates mid-speed line demand for tamper-evident zipper mechanisms without mechanical cam replacement.
India
CDSCO serialization mandates and EU-GMP upgrade programs create pull for mid-speed servo lines in Ahmedabad and Hyderabad pharmaceutical clusters. The country's national pharmaceutical regulator tightens track-and-trace requirements for export-oriented contract manufacturers. Gujarat's industrial belt dominates procurement of integrated vision inspection modules for blister-to-pouch format conversions.
Thailand
Retort pouch protein applications for shelf-stable seafood drive rotary configuration demand with overpressure sterilization compatibility. The country's national food and drug administration enforces stricter barrier film validation for export markets. Bangkok's eastern seaboard manufacturing zone concentrates vacuum pouch handling system installations for European supermarket private label contracts.
Horizontal Premade Pouch Packing Machine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the horizontal premade pouch packing machine market. European and Japanese OEMs dominate validated pharmaceutical applications with servo-driven architectures, while Chinese and Southeast Asian fabricators capture commodity food packaging through standardized mechanical configurations. The competitive structure separates into three archetypes: premium-tier validation specialists, mid-tier flexible solution providers, and economy-scale volume producers. Consolidation pressure is intensifying through strategic partnerships between European automation component suppliers and regional system integrators, alongside captive manufacturing investments by leading OEMs seeking margin protection on servo modules.
Among European validation specialists, Mespack and SN Maschinenbau occupy positions exemplifying premium-tier pharmaceutical focus, with German and Italian engineering heritage respectively. Viking Masek represents the mid-tier North American specialist archetype, while General Packer anchors the Asia-Pacific volume-driven segment. These three named entities illustrate the geographic and technological stratification without exhausting the competitive set.
| Leading Market Players |
|---|
| General Packer |
| Mespack |
| Viking Masek |
| SN Maschinenbau |
| REZPACK Machinery |
| Echo Machinery |
| Topack |
| Universal Pack |
| Matrix Packaging |
| Others |
Pricing and Supply Chain Analysis
Ninety-day stainless steel inventory cycles in South Korean and Chinese mills determine margin compression trajectories for IP65-certified washdown systems, concentrating pricing power with OEMs holding captive servo module production while forcing spot-market buyers into cost pass-through vulnerability.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture as procurement committees unbundle technical support from capital purchases. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical configurations with FDA 21 CFR Part 11 compliance from commodity food-grade mechanical lines. Cost compression in mid-speed servo tiers intensifies because Chinese fabricators are expanding standardized platform output. Contract packers in India and Thailand exhibit highest price sensitivity; German pharmaceutical converters absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites component delivery reliability for Southeast Asian retort pouch fabricators, exposing European OEMs to logistics chokepoint vulnerability. Manufacturing gravity centers on Germany, Japan, and Italy for precision servo assemblies, with China and South Korea dominating food-grade 316L stainless steel sheet supply. Brushless AC servomotors, sanitary tubing, and ceramic sealing jaw coatings constitute critical input dependencies. Distribution runs through regional service depots in North America and Western Europe, bypassing manufacturer-direct coverage as third-party maintenance specialists consolidate certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of Rockwell, Siemens, and Beckhoff drive commissioning expertise constrains output scaling across pharmaceutical and frozen food automation upgrades, privileging OEMs with in-house training academies over pure hardware vendors.
For Market Incumbents: Compound validation documentation depth to extend pharmaceutical sales cycle insulation against thermoform-fill-seal substitution threats. Deepen backward integration into servo motor production to protect margin control as Chinese steel price volatility transmits through component tiers. Anchor regional service depot density in California and Texas corridors where third-party maintenance specialists are consolidating technician networks. For New Entrants and Emerging Players: Aftermarket service contract unbundling by mid-sized North American co-packers creates entry space for hourly-rate technical support specialists with certified Rockwell and Siemens programming capabilities. Target Indian pharmaceutical export clusters in Ahmedabad and Hyderabad where CDSCO serialization mandates outpace incumbent validation response capacity. Lead with modular upgrade path offerings that retrofit 1990s-era pneumatic legacy lines without full control architecture replacement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parent companies with under-monetized pharmaceutical packaging equipment divisions lacking standalone FDA validation infrastructure. Long-term viability hinges on servo automation architecture ownership rather than mechanical cam legacy revenue streams. Monitor PFAS-free sealing jaw coating qualification timelines as inflection signal for regulatory-driven replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Servo Module Manufacturing | Mespack's margin control across European pharmaceutical accounts demonstrates vertical integration value. |
| Regional Service Depot Expansion | Third-party maintenance specialist consolidation in California corridors reshapes aftermarket revenue capture. |
| PFAS-Free Coating Validation | REACH Annex XVII compliance ahead of US EPA action secures pharmaceutical and organic food specification priority. |
| Collaborative Robot Pre-Certification | Universal Robots and FANUC integration collapses historical boundaries between pouch packing OEMs and robotic integrators. |
| Indian Pharmaceutical Cluster Penetration | CDSCO track-and-trace mandates in Ahmedabad and Hyderabad create pull for mid-speed servo line deployment. |
Research Methodology
A spread of perspectives from plant engineers at frozen food processors, pharmaceutical packaging line managers, aftermarket service heads at OEMs, and procurement leads at contract packers converged on the working assumptions shaping equipment specification trends. Primary interview insights combined with secondary validation from FDA 21 CFR Part 11 guidance documents, EMA Annex 1 sterile manufacturing updates, EU Machinery Directive technical specifications, and customs trade data on stainless steel mill shipments. Bottom-up installed base estimates and top-down capital expenditure flows were triangulated to anchor volume projections.
Segmentation dimensions modeled span motion type architecture, control technology stack, end-use application requirements, and regional regulatory compliance clusters across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, retrofit intensity patterns, and greenfield facility investment pipelines. Pharmaceutical serialization mandate timelines and frozen food shelf-life extension specifications provided industry-specific forecast inputs.
Material uncertainties — stainless steel input cost volatility, FDA qualification timeline extensions, and thermoform-fill-seal format substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about servo automation adoption velocity and regulatory enforcement consistency. Practitioners should keep alternative scenarios live as EMA Annex 1 interpretation evolves and US EPA PFAS restrictions advance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.