
 PCR Pouches Market | 2026-2036
PCR Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Pouches Market Analytics
Multi-source resin procurement is pivoting toward certified post-consumer recycled supply chains as virgin polyethylene volatility persists. Amcor Limited leverages its global recycling partnerships to secure food-grade rPE volumes ahead of competitors. Berry Global Inc. anchors North American capacity through mechanical recycling alliances with municipal collection programs. Mondi Group differentiates via integrated kraft-PCR hybrid structures that reduce plastic intensity while preserving barrier performance.
PCR pouches are flexible packaging formats manufactured with post-consumer recycled resins, typically containing 30-90% recycled polyethylene or polypropylene content through extrusion and lamination processes, designed to reduce virgin plastic dependence while maintaining seal integrity and product protection. Stand-up pouches command premium positioning in food packaging due to shelf presence and reduced material usage versus rigid alternatives. Heat-sealed pouches dominate pharmaceutical and industrial segments where hermetic closure and contamination control override convenience features. Roll stock occupies the volume base, feeding form-fill-seal operations across cosmetics and food sectors where converter efficiency determines margin capture.
The EU Green Deal and PPWR mandate minimum recycled content thresholds for plastic packaging placed on European markets, directly shaping converter procurement specifications and resin certification requirements. FDA issued letters on post-consumer recycling processes for food-contact applications, establishing the regulatory pathway for rPET and rPE use in U.S. food pouches. Stakeholders must monitor evolving mechanical versus chemical recycling eligibility under emerging state-level extended producer responsibility frameworks in California and New York, as certification standards fragment across jurisdictions and determine market access.
Market Dynamics
Recycled resin certification requirements are tightening procurement specifications across converter networks as EU Green Deal timelines accelerate compliance deadlines for post-consumer content verification.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds for plastic packaging placed on European markets are compelling brand owners to source certified PCR pouches ahead of enforcement dates.
- Mechanical recycling advances:Food-grade rPE purification technologies now enable direct-contact applications previously restricted to virgin resins, opening dairy and ready-meal segments.
- German retail consolidation:Discounter and supermarket chains are unilaterally exceeding regulatory minimums with 50-70% PCR commitments in private-label packaging.
Market Restraints
- Post-consumer feedstock volatility:Municipal collection program interruptions create resin availability gaps that force converters to maintain dual virgin-PCR inventory positions.
- Food-contact certification bottlenecks:FDA no-objection letter timelines for novel recycling processes extend 18-24 months, delaying U.S. market entry for European converters.
- Flexible packaging substitution:Fiber-based alternatives and reusable container systems are capturing premium shelf-space commitments from sustainability-focused CPG brands.
Strategic Opportunities
- Pharmaceutical compliance packaging:Child-resistant zipper mechanisms combined with FDA-validated rPE structures address unmet demand in over-the-counter medication pouches.
- California extended producer responsibility:State-level PCR rate mandates are creating first-mover advantages for converters establishing West Coast mechanical recycling partnerships.
- Chemical recycling integration:Pyrolysis-derived resin streams are converging with mechanical recycling outputs to expand food-contact eligible supply beyond current contamination limits.
Industry Challenges
- Optical sorting technician scarcity:Automated flake purification systems require specialized calibration expertise that outpaces vocational training program output.
- Multi-jurisdiction certification fragmentation:Divergent state-level EPR frameworks in New York and California force converters to maintain parallel compliance documentation systems.
- Legacy extrusion line retrofit costs:Processing equipment designed for virgin resin tolerances requires screw and die modifications to handle variable PCR melt flow indices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Pouches Market |
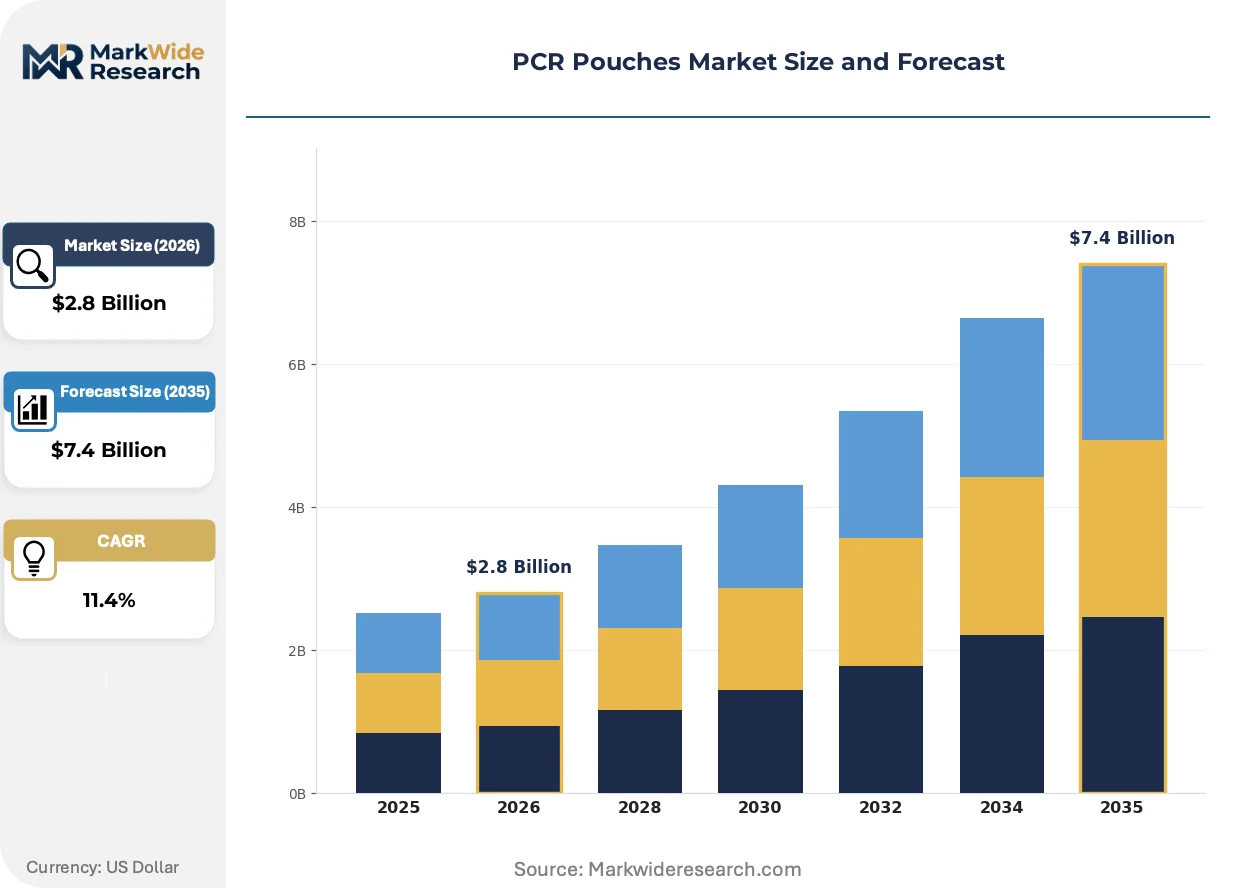
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat-Sealed Pouches, Zipper Pouches, Stand-Up Pouches, Roll Stock Material: Polyethylene, Polypropylene, Polyester, Nylon End User: Pharmaceuticals, Cosmetics, Food Packaging, Industrial Closure Type: Zip Lock, Heat Seal, Tear Notch, Others |
| Companies Covered | Amcor Limited, Berry Global Inc., Mondi Group, Sonoco Products Company, Constantia Flexibles, Sealed Air Corporation, Uflex Ltd., ProAmpac, Huhtamaki Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Pouches Market Evolving Landscape
Digital watermarking and blockchain traceability systems are reshaping how brand owners verify post-consumer content claims across multi-tier supply chains.
Advanced optical sorting with near-infrared polymer identification is expanding into flexible packaging recovery streams previously rejected by municipal MRFs. German sorting facilities are deploying this technology at commercial scale, enabling food-grade rPE output purity above 99.5%. The structural consequence is expanding into converter sourcing strategies that bypass traditional resin brokers.
REACH authorization requirements for recycled content additives are tightening impurity thresholds for substances of very high concern in European PCR streams. Industrial consequence includes mandatory third-party testing protocols that add 8-12 weeks to batch release cycles. Stand-up pouch converters serving German organic food brands are absorbing these costs to maintain shelf placement.
Direct converter-brand procurement relationships are compressing traditional distributor intermediaries in PCR pouch supply chains. Major European retailers are establishing multi-year offtake agreements with certified converters, displacing spot-market purchasing. This pattern concentrates in France and the Netherlands where centralized sustainability procurement functions have formalized direct sourcing mandates.
PCR Pouches Market Segmentation
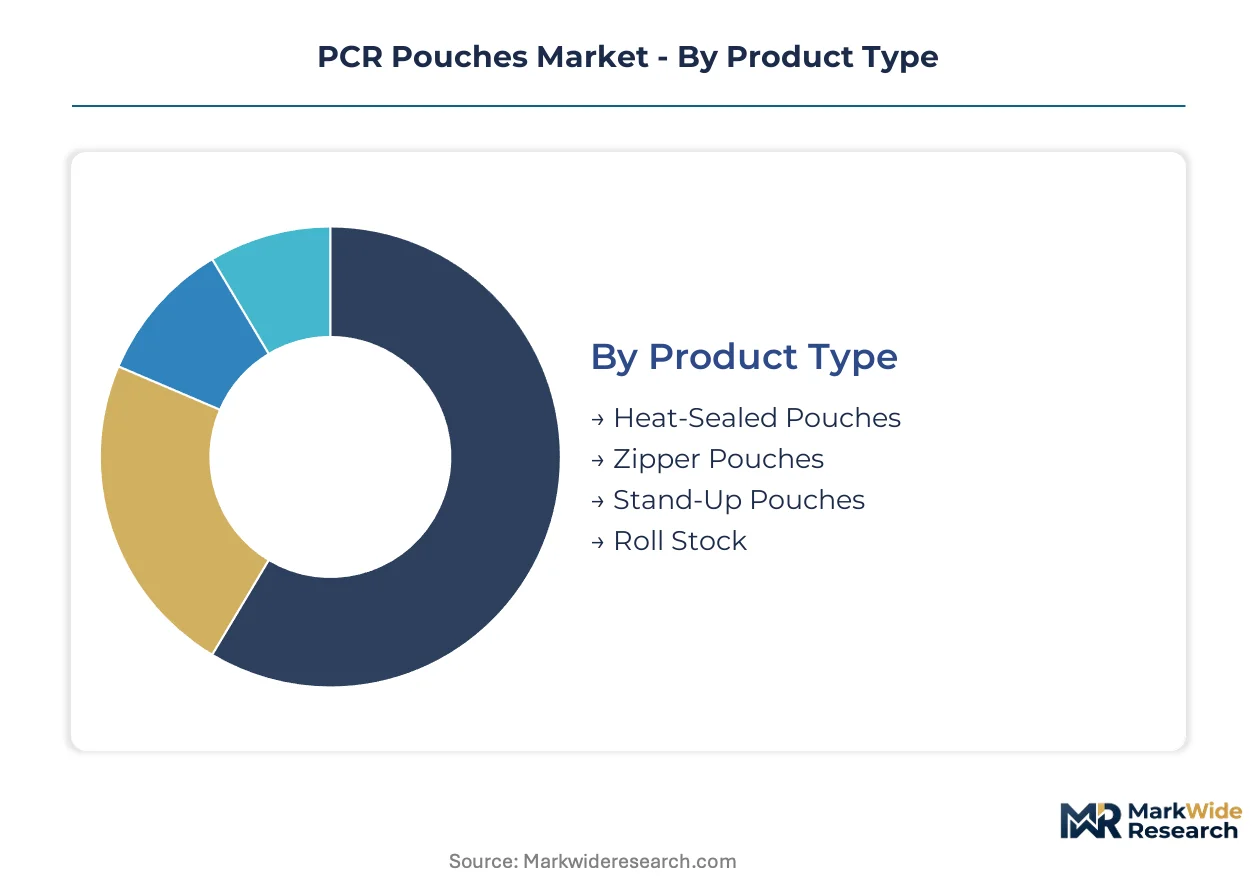
PCR pouch specifications diverge sharply across end-use requirements, with food-contact certification and barrier performance dictating resin selection and conversion technology. Converter procurement patterns track these technical boundaries, creating distinct supply chain configurations for each segment cluster.
Product Type:
Structural format determines equipment compatibility, shelf presence, and material efficiency trade-offs across converter operations.
- Stand-Up Pouches:These formats integrate gusseted bases with multi-layer barrier films, enabling vertical shelf display while reducing plastic mass versus rigid containers. German organic food brands and French retail chains are expanding procurement of 50-70% PCR content stand-up formats for private-label dry goods and ready meals, driven by visible sustainability commitments that influence consumer purchase decisions at point-of-sale.
- Heat-Sealed Pouches:Hermetic closure systems using impulse or constant heat sealing deliver contamination control for moisture-sensitive and sterile applications. Pharmaceutical manufacturers in Switzerland and the Netherlands specify these formats for unit-dose medications where seal integrity validation overrides convenience features, with FDA no-objection letters for rPE food-contact applications now enabling parallel dairy packaging adoption.
- Zipper Pouches:Child-resistant slider mechanisms combined with resealable interlocking profiles serve over-the-counter medication and premium snack segments requiring repeated access.
- Roll Stock:Unformed web material feeds high-speed form-fill-seal lines across cosmetics and food sectors, with converter efficiency determining margin capture in high-volume applications.
Roll stock leads on scale; stand-up pouches lead on momentum.
Material:
Resin chemistry governs barrier properties, mechanical performance, and regulatory eligibility for food-contact applications.
- Polyethylene:rPE streams from mechanical recycling now achieve food-grade purity above 99.5% through advanced optical sorting, opening direct-contact dairy and ready-meal segments previously restricted to virgin resins. German sorting facilities are deploying near-infrared identification at commercial scale, enabling converter sourcing strategies that bypass traditional resin brokers.
- Polypropylene:Higher melting points and stiffness profiles suit retort and hot-fill applications where dimensional stability under thermal stress is critical. Pharmaceutical compliance packaging in the Netherlands and Belgium specifies rPP for sterilizable medical device pouches, with EMA guidance on recycled content additives shaping batch release testing protocols.
- Polyester:rPET delivers optical clarity and oxygen barrier performance for premium cosmetics and beverage applications where shelf visibility matters.
- Nylon:Superior puncture resistance and gas barrier properties serve industrial and vacuum-packaged protein segments requiring extended shelf life.
Polyethylene dominates volume; polypropylene is expanding most quickly.
End User:
Regulatory stringency and contamination risk tolerance create divergent specification corridors across customer categories.
- Food Packaging:EU Green Deal and PPWR mandates are compelling brand owners to source certified PCR pouches ahead of enforcement dates, with German discounters unilaterally exceeding regulatory minimums. REACH authorization requirements for recycled content additives are tightening impurity thresholds, adding 8-12 weeks to batch release cycles that converters absorb to maintain shelf placement.
- Pharmaceuticals:Child-resistant zipper mechanisms combined with FDA-validated rPE structures address unmet demand in over-the-counter medication pouches. Swiss and Dutch manufacturers lead adoption of barrier-grade PCR formats for unit-dose compliance packaging where hermetic closure validation is mandatory.
- Cosmetics:Premium positioning and optical clarity requirements favor rPET and high-purity rPE streams with enhanced aesthetic performance.
- Industrial:Lower regulatory barriers and durability priorities enable higher PCR content ratios with relaxed aesthetic specifications.
Food packaging leads on scale; pharmaceuticals lead on margin expansion.
Closure Type:
Opening mechanism selection balances convenience, child safety, and seal integrity requirements across application contexts.
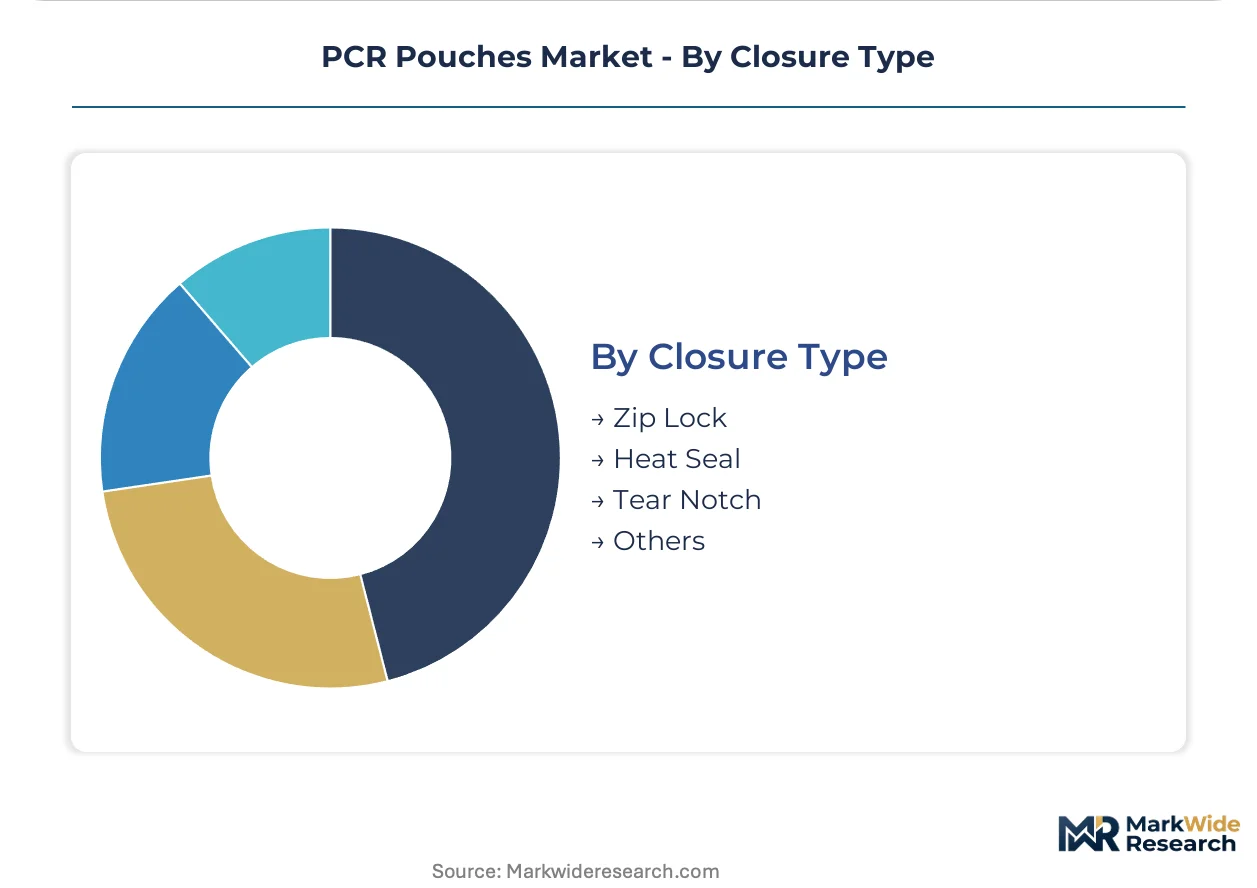
- Heat Seal:Permanent fusion bonding delivers tamper-evidence and hermetic protection for sterile and moisture-critical applications. Pharmaceutical manufacturers in Germany and Switzerland specify heat-sealed formats for moisture-barrier compliance where opening irreversibility signals product integrity.
- Zip Lock:Reclosable interlocking profiles enable portion control and extended product life after initial opening. French and Dutch retail chains are expanding procurement of zip-lock stand-up pouches for private-label nuts, dried fruits, and confectionery where resealability drives repeat purchase.
- Tear Notch:Controlled-initiation features provide consumer-friendly opening without tools while maintaining package integrity during distribution.
- Others:Spouts, fitments, and dispensing closures serve liquid and semi-solid applications requiring controlled flow.
Heat seal leads on scale; zip lock gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail chains and municipal recycling infrastructure anchor PCR pouch procurement intensity across developed markets. Brand-led sustainability commitments in Western Europe outpace regulatory minimums, while North American adoption accelerates through state-level extended producer responsibility frameworks. Converter networks concentrate near advanced optical sorting facilities that achieve food-grade resin purity.
Germany
Discounter chains and organic food brands drive 50-70% PCR procurement commitments for private-label packaging. EU Green Deal and PPWR timelines tighten recycled-content mandates ahead of enforcement dates. Sorting facilities in North Rhine-Westphalia deploy near-infrared polymer identification at commercial scale, enabling rPE output purity above 99.5% that bypasses traditional resin brokers.
United States
California and New York state-level EPR frameworks create first-mover advantages for West Coast mechanical recycling partnerships. FDA no-objection letter timelines for novel recycling processes extend 18-24 months, delaying market entry for European converters. Midwest converter clusters maintain dual virgin-PCR inventory positions to hedge against municipal collection program interruptions.
France
Centralized sustainability procurement functions at major retailers formalize direct converter-brand sourcing mandates. REACH authorization requirements for recycled content additives add 8-12 weeks to batch release cycles that converters absorb to maintain shelf placement. Paris-based retail chains are expanding multi-year offtake agreements with certified converters, displacing spot-market purchasing.
Switzerland
Pharmaceutical manufacturers specify heat-sealed formats for unit-dose medications where seal integrity validation overrides convenience features. Swissmedic guidance on recycled content additives shapes batch release testing protocols for sterilizable medical device pouches. Basel-area packaging converters lead adoption of barrier-grade PCR formats for over-the-counter compliance packaging.
Netherlands
French and Dutch retail chains expand procurement of zip-lock stand-up pouches for private-label nuts and dried fruits where resealability drives repeat purchase. EMA guidance on recycled content additives influences converter qualification protocols. Rotterdam-area logistics hubs facilitate direct converter-brand procurement relationships that compress traditional distributor intermediaries.
PCR Pouches Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chemical recycling integration and pharmaceutical compliance specializations. The supplier base organizes around three archetypes: integrated multinational converters with global recycling partnerships, regional mechanical recycling specialists with municipal collection alliances, and hybrid material innovators combining kraft-PCR structures. Dominant competitive moves include backward integration into resin purification assets and multi-year offtake agreements with retail sustainability procurement functions.
Among integrated multinational converters, Amcor Limited, Berry Global Inc., and Mondi Group exemplify distinct strategic positions. Amcor leverages global recycling partnerships to secure food-grade rPE volumes. Berry anchors North American capacity through mechanical recycling alliances. Mondi differentiates via integrated kraft-PCR hybrid structures that reduce plastic intensity. These three represent the archetype spectrum spanning resin security, regional scale, and material innovation.
| Leading Market Players |
|---|
| Amcor Limited |
| Berry Global Inc. |
| Mondi Group |
| Sonoco Products Company |
| Constantia Flexibles |
| Sealed Air Corporation |
| Uflex Ltd. |
| ProAmpac |
| Huhtamaki Group |
| Others |
Value Network & Pricing Analysis
Advanced optical sorting with near-infrared polymer identification is compressing resin purification economics while simultaneously concentrating supply leverage among German and Dutch facilities achieving food-grade rPE purity above 99.5%. This technological transition rewards converters with direct municipal collection alliances, forcing spot-market dependent competitors into cost-disadvantaged inventory positions.
Pricing Analysis
Input-cost pass-through from post-consumer resin volatility dominates pricing structures, with mechanical recycling output premiums tethered to municipal collection program stability. Three-tier pricing structure across premium certified-food-grade, standard industrial-grade, and economy non-certified tiers reflects certification investment recovery and batch testing overhead. Pricing pressure stems from fiber-based flexible packaging substitutes capturing premium shelf-space commitments from sustainability-focused CPG brands. Private-label retail buyers exhibit highest price sensitivity, while pharmaceutical compliance packaging buyers accept material premiums for FDA-validated structures.
Supply Chain Analysis
Reverse-logistics integration through municipal collection program partnerships anchors converter resin security, with post-consumer film recovery flows feeding mechanical recycling purification assets. Supply concentrates in Germany, the Netherlands, and France where optical sorting infrastructure achieves food-grade output purity. Raw material dependencies center on post-consumer polyethylene film streams, polypropylene retort-grade resins, and certified additive packages for REACH compliance. Single-source vulnerability to municipal collection program interruptions forces dual virgin-PCR inventory strategies. Distribution runs through direct converter-brand procurement relationships that displace traditional resin broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PCR pouches market functions as a regulatory compounder, with EU Green Deal and PPWR enforcement timelines mandating recycled content thresholds that pre-structure procurement decisions regardless of underlying cost economics.
For Market Incumbents: Deploy backward integration into optical sorting and resin purification assets to secure food-grade rPE volumes ahead of EU Green Deal enforcement. Cement multi-year offtake agreements with German and French retail sustainability procurement functions before direct sourcing mandates formalize. Counter fiber-based substitute threats by accelerating kraft-PCR hybrid structure development to reduce plastic intensity while preserving barrier performance. For New Entrants and Emerging Players: Capture California and New York state-level EPR framework advantages by establishing West Coast mechanical recycling partnerships before compliance deadlines formalize. Target pharmaceutical compliance packaging segments where FDA no-objection letter scarcity creates qualification moats against commodity converters. Lead with chemical recycling integration propositions that expand food-contact eligible supply beyond current mechanical recycling contamination limits. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mechanical recycling specialists with municipal collection alliances but lacking converter downstream integration. Five-to-ten year viability hinges on certification infrastructure ownership rather than commodity resin trading. Monitor FDA no-objection letter issuance velocity for novel recycling processes as the signal indicating U.S. market access expansion for European technology licensors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Purification | Secures food-grade rPE volumes ahead of EU Green Deal enforcement timelines. |
| Multi-Year Retail Offtake Agreements | Locks shelf placement with German discounters exceeding regulatory PCR minimums. |
| Chemical Recycling Technology Licensing | Expands food-contact eligible supply beyond mechanical recycling contamination limits. |
| Pharmaceutical Compliance Certification Investment | Addresses unmet demand for FDA-validated rPE structures in over-the-counter medication. |
| Kraft-PCR Hybrid Structure Development | Reduces plastic intensity while preserving barrier performance against fiber substitutes. |
Research Methodology
Coverage spans Western Europe, North America, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with converter procurement directors, sustainability officers at major retail chains, mechanical recycling plant managers, and regulatory affairs specialists at packaging trade associations. Secondary sources included EU Green Deal implementation guidance, FDA no-objection letter databases, ECHA REACH authorization filings, and municipal recycling program performance reports. Bottom-up resin volume modeling triangulated against top-down packaging demand projections.
Rate-of-change decomposition across the analysis window separated volume growth drivers by product type, material chemistry, end-use regulatory stringency, and closure mechanism complexity. Segmentation dimensions modeled included stand-up versus heat-sealed formats, polyethylene versus polypropylene resin streams, food versus pharmaceutical end-use certification tiers, and heat seal versus zip-lock closure types. CAGRs derived from regression analysis of historical procurement patterns against regulatory milestone schedules. Industry-specific forecast inputs incorporated EU PPWR enforcement timeline assumptions and FDA food-contact approval velocity.
Municipal collection program interruptions, FDA no-objection letter timeline extensions, and REACH authorization requirement tightening are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding optical sorting technology deployment rates and chemical recycling commercialization trajectories. Practitioners should monitor EU member state transposition timing, California EPR framework implementation, and pharmaceutical converter qualification protocols for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pre-Made Pouch Packaging Market
Pouch
Foil Zipper Bags Market
Pouch
Latin America Pouch Packaging Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Spout Pouch Market
Pouch
Sterilization Pouches Market
Pouch
Europe Pouch Packaging Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Stand Up Paper Pouches Market
Pouch
Kraft Pouch Market
Pouch
Zipper Pouch Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Squeeze Pouch Market
Pouch
Retort Pouch Market
Pouch
Global Boil-In Bags Market
Pouch
Inverted Pouch Market