
 North America Lithium-Ion Battery Pouch Film Market | 2026-2036
North America Lithium-Ion Battery Pouch Film Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lithium-Ion Battery Pouch Film Market Outlook
North American polymer film converters is recalibrating capacity plans as original equipment manufacturers demand thicker, multi-layer barrier specifications for next-generation cells. Toray Industries sustains technology leadership in polyamide base films through integrated resin-to-film operations in Mexico. Kolon Industries competes on dry-process lamination expertise, leveraging proprietary adhesive chemistry developed for Korean cell makers now supplying U.S. assembly plants. DNP Group anchors regional supply through its Alabama conversion facility, which controls distribution channels to southeastern battery factories.
Lithium-ion battery pouch film consists of aluminum-laminated multilayer flexible packaging, typically comprising cast polypropylene, aluminum foil, and nylon or polyethylene terephthalate outer layers bonded through dry or wet adhesive processes, designed to contain electrolyte and enable gas venting while maintaining hermetic seal integrity across thousands of charge cycles. Dry process technology dominates current North American supply due to lower capital intensity and compatibility with existing coating infrastructure, though coating technology lines are expanding fastest as cell producers specify higher puncture resistance for electric vehicle modules. PET-based outer layers occupy the largest product type position because of dimensional stability during vacuum forming, while 100 μm and 200 μm thickness grades capture disproportionate margin pools as tier-one suppliers qualify narrower tolerances for automotive customers.
The U.S. Environmental Protection Agency oversees chemical emissions from solvent-based lamination processes, while OSHA regulates worker exposure to N-methyl-2-pyrrolidone in coating operations, both frameworks elevating capital costs for new entrants without compliant infrastructure. Health Canada and PMRA coordinate cross-border standards for electrolyte barrier performance, creating dual-certification requirements for suppliers serving Ontario's emerging cell manufacturing cluster. Stakeholders must monitor how evolving U.S. domestic content thresholds under the Inflation Reduction Act reshape qualification timelines for imported base films versus converted domestic product.
Market Dynamics
Cell-to-pack architecture migration across Michigan and Ontario automotive corridors is compressing qualification timelines for aluminum-laminated pouch films as electric vehicle manufacturers eliminate module housings and demand direct cell integration.
Growth Catalysts
- Domestic Content Incentives:The U.S. Inflation Reduction Act's domestic content thresholds redirect supply chain investments toward North American conversion facilities, accelerating localized film lamination capacity.
- Electrolyte Barrier Performance Standards:Health Canada and PMRA coordination on cross-border certification requirements creates qualified supplier preference for Ontario-bound cell manufacturing clusters.
- Dry Process Technology:Lower capital intensity and compatibility with existing coating infrastructure enables rapid capacity scaling across southeastern U.S. battery factory supply zones.
Market Restraints
- Aluminum Foil Supply Concentration:Asian smelter dominance in battery-grade foil creates input cost volatility and qualification delays for North American laminators.
- OSHA N-Methyl-2-Pyrrolidone Exposure Limits:Worker safety regulations elevate capital costs for wet adhesive coating lines, constraining new entrant participation.
- Prismatic Cell Substitution:Cylindrical and prismatic formats adjacent to pouch designs capture share in high-volume automotive programs, limiting pouch film addressable market expansion.
Strategic Opportunities
- Southeastern U.S. Conversion Capacity:Alabama and Tennessee positioning for distribution channel control to regional battery factories creates greenfield lamination site viability.
- 100 μm and 200 μm Thickness Grades:Narrower tolerance qualification requirements for automotive customers open margin pool capture for tier-one suppliers with metrology capabilities.
- PET-Based Outer Layer Specification:Dimensional stability advantages during vacuum forming processes attract solid-state cell development programs seeking format flexibility.
Industry Challenges
- Multi-Layer Barrier Coating Expertise:Polymer film converters face talent scarcity in adhesive chemistry and vacuum metallization process control for next-generation cell specifications.
- Dual-Certification Timeline Compression:Simultaneous U.S. EPA emissions compliance and Health Canada electrolyte barrier validation extends product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lithium-Ion Battery Pouch Film Market |
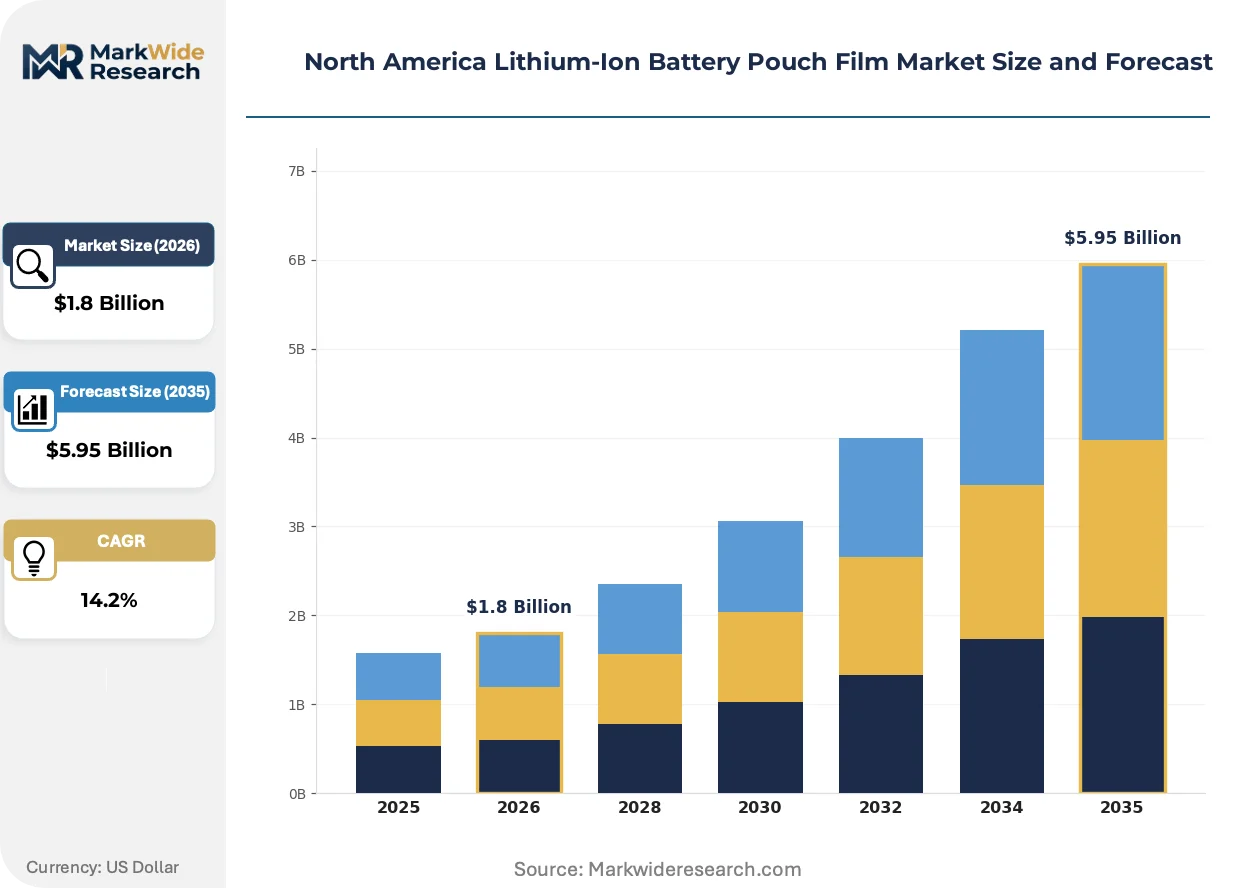
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, PE, PA, Others Technology: Dry Process, Wet Process, Coating Technology, Laminating Technology Thickness: 50 μm, 100 μm, 200 μm, 250 μm End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Applications |
| Companies Covered | Ube Industries, Ltd., Kolon Industries, Inc., Toray Industries, Inc., Targray, DNP Group, SK Innovation Co., Ltd., Kureha Corporation, MTI Corporation, Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lithium-Ion Battery Pouch Film Market Strategic Shifts
Active materials science advancement and regulatory recalibration are compressing traditional lamination process timelines while opening specification windows for novel barrier architectures.
Coating technology lines are electrifying next-generation pouch film performance as cell producers specify higher puncture resistance for electric vehicle modules. Automotive battery pack engineers at Detroit and Lordstown facilities are specifying these upgraded lines within eighteen-month qualification cycles. The technology is electrifying competitive positioning among regional converters by compressing the performance gap between dry and wet process outputs.
The U.S. Environmental Protection Agency's solvent-based lamination emissions oversight tightens operational parameters for existing facilities while grandfathering compliant infrastructure. Wet adhesive process operators face incremental monitoring and abatement capital requirements that dry process competitors avoid. Southeastern U.S. battery factory supply zones show fastest response through conversion facility equipment refresh cycles.
Buyer concentration around Great Lakes automotive corridors concentrates procurement leverage among cell plant engineering teams, compressing supplier negotiation positions. Long-term supply agreements with volume-tiered pricing are displacing spot market transactions for base film and converted product. Michigan and Ontario manufacturing clusters exhibit the most visible contract structure migration as cell capacity scales toward gigafactory thresholds.
North America Lithium-Ion Battery Pouch Film Market Segmentation
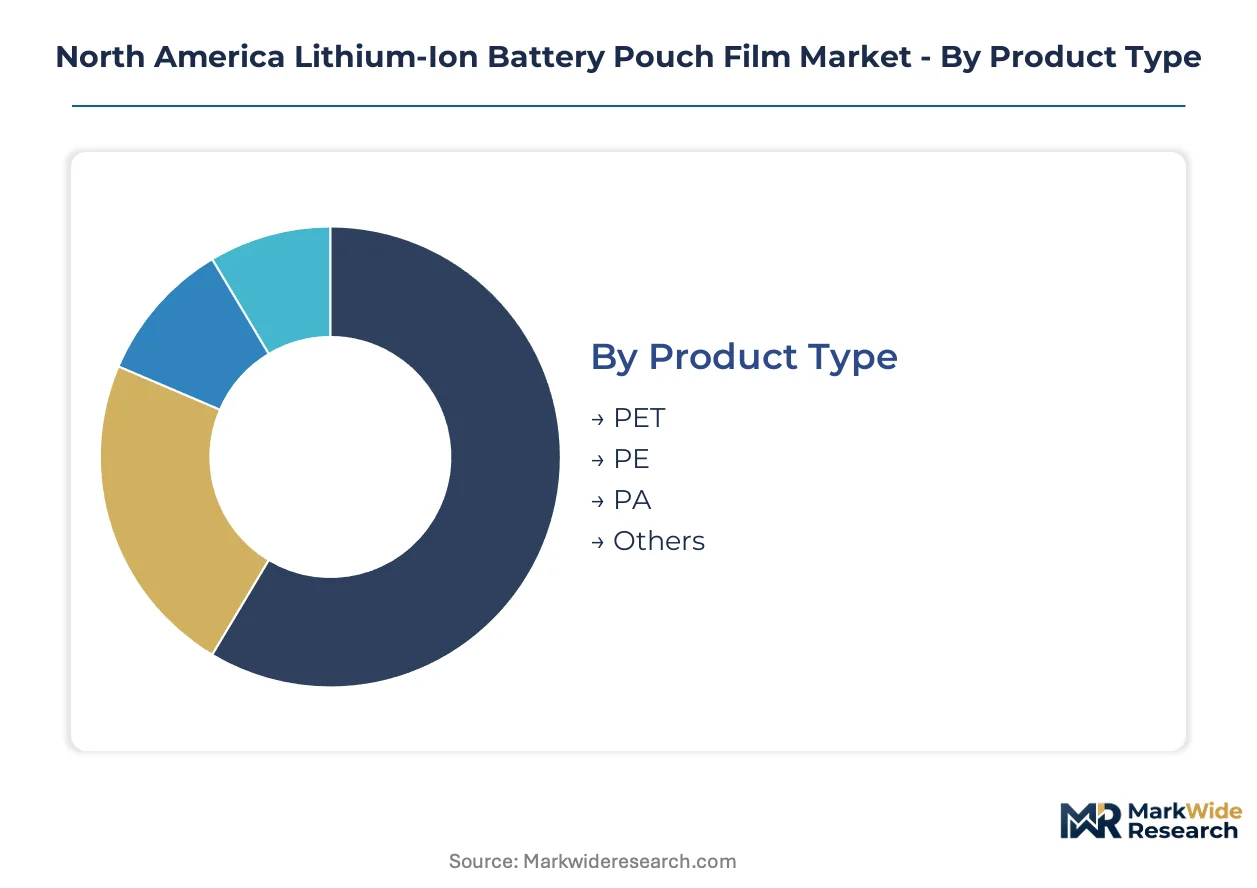
Segmentation in North American pouch film markets reveals how material specifications, process technologies, and end-use requirements create distinct competitive arenas. Each dimension carries different margin profiles, qualification barriers, and supply chain dependencies that shape supplier positioning.
Product Type:
PET dominates volume tiers while premium specifications command narrower tolerance premiums across automotive qualification programs.
- PET:Polyethylene terephthalate outer layers provide dimensional stability during vacuum forming operations. Demand concentrates in Detroit and Lordstown cell plants where solid-state development programs seek format flexibility for next-generation pack architectures.
- PA:Polyamide base films from Toray's integrated Mexico operations deliver superior puncture resistance. Michigan OEMs specify these for cell-to-pack designs that eliminate module housings and expose films to direct mechanical stress.
- PE:Polyethylene variants serve cost-sensitive consumer electronics applications with lower barrier requirements.
- Others:Specialty polymer blends address niche industrial applications requiring chemical resistance or extreme temperature performance.
Mature deployment sits with PET. Newer deployment is concentrated in PA.
Technology:
Dry process capacity scales fastest where capital constraints limit greenfield investment, while coating lines attract automotive specification upgrades.
- Dry Process:Lower capital intensity and compatibility with existing coating infrastructure enables rapid scaling across southeastern U.S. battery factory supply zones. Alabama and Tennessee converters favor this approach for IRA-compliant domestic content qualification.
- Wet Process:Solvent-based adhesive lamination delivers superior bond strength for high-voltage automotive cells. OSHA N-methyl-2-pyrrolidone exposure limits elevate capital costs, restricting new entrant participation to established players with compliant infrastructure.
- Coating Technology:Electrifying competitive positioning by compressing performance gaps between dry and wet outputs as cell producers specify higher puncture resistance.
- Laminating Technology:Multi-layer barrier expertise faces talent scarcity in adhesive chemistry and vacuum metallization process control.
Volume leadership belongs to dry process. Capability investment is accelerating fastest in coating technology.
Thickness:
Mid-range specifications capture disproportionate margin pools as tier-one suppliers qualify narrower tolerances for automotive customers.
- 100 μm:Automotive tier-one qualification requirements for electric vehicle modules concentrate procurement leverage among Great Lakes engineering teams. Long-term supply agreements with volume-tiered pricing displace spot market transactions.
- 200 μm:Premium thickness grades serve heavy-duty energy storage systems and commercial vehicle applications requiring enhanced mechanical protection. Ontario's emerging cell manufacturing cluster specifies these for cross-border certification alignment.
- 50 μm:Ultra-thin variants address consumer electronics weight and space constraints with reduced barrier performance trade-offs.
- 250 μm:Maximum protection specifications serve industrial applications with extreme puncture risk or extended cycle life requirements.
Established production scales at 100 μm. Capacity expansion is concentrating at 200 μm.
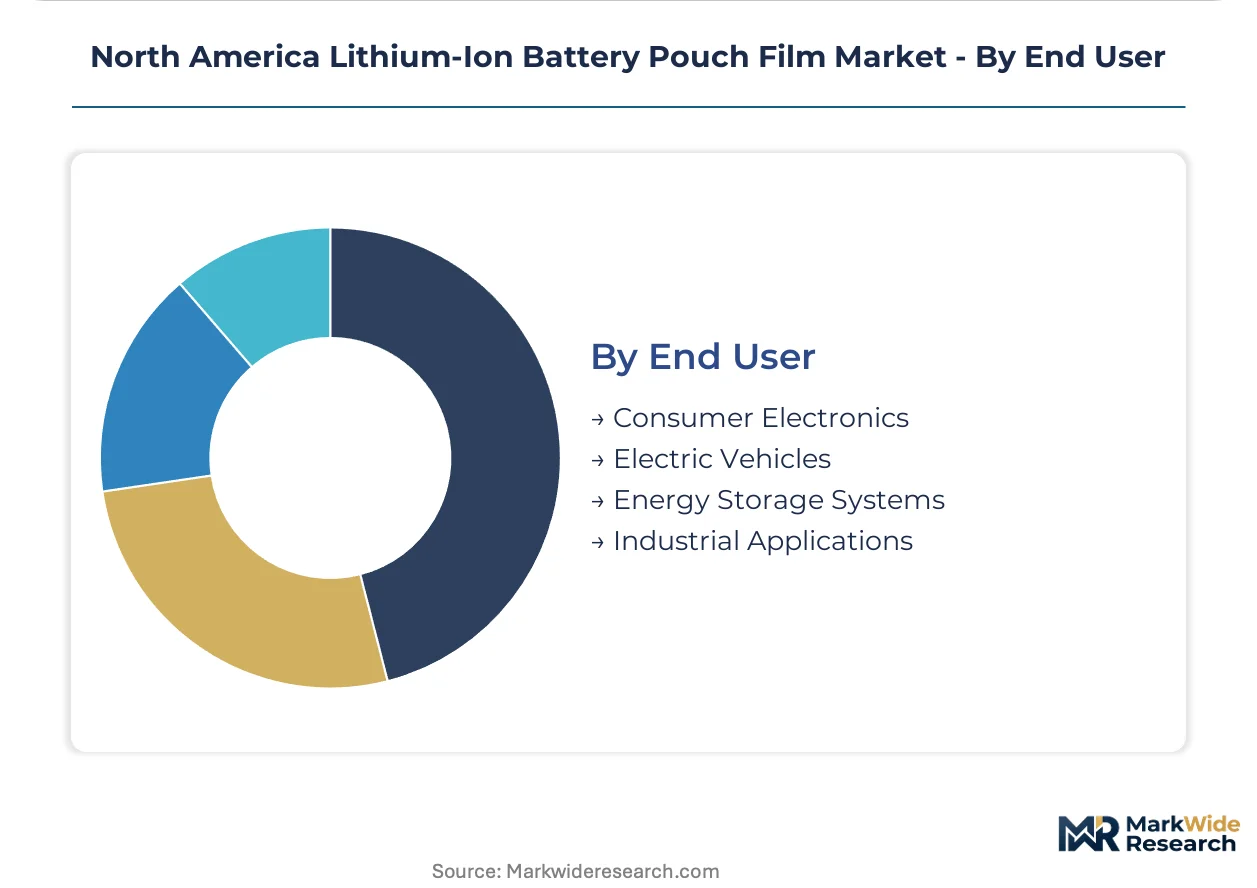
End User:
Automotive procurement is displacing consumer electronics as the primary demand driver, reshaping supplier qualification priorities.
- Electric Vehicles:Cell-to-pack architecture migration across Michigan and Ontario corridors compresses qualification timelines as manufacturers eliminate module housings. Domestic content thresholds under the Inflation Reduction Act redirect supply chain investments toward North American conversion facilities.
- Consumer Electronics:Legacy smartphone and laptop applications face procurement compression as film converters prioritize automotive volume commitments. Spot market transactions persist for smaller batch requirements.
- Energy Storage Systems:Grid-scale and residential battery installations specify intermediate thickness grades with cost-performance balancing.
- Industrial Applications:Material handling equipment and stationary power systems require specialized chemical resistance and extended temperature range performance.
Contract structure maturity sits with consumer electronics. Procurement volume is climbing the fastest in electric vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum foil feedstock from Asian smelters anchors North American pouch film supply chains, creating input dependencies that shape regional conversion capacity decisions. The U.S. Inflation Reduction Act's domestic content thresholds redirect investment toward localized lamination facilities across the Great Lakes and southeastern corridors.
United States
EPA solvent-based lamination emissions oversight tightens operational parameters for existing facilities in Alabama and Tennessee while grandfathering compliant infrastructure. OSHA N-methyl-2-pyrrolidone exposure limits elevate capital costs for wet adhesive coating lines, restricting new entrant participation. The southeastern battery factory supply zone shows fastest response through conversion facility equipment refresh cycles.
Canada
Health Canada and PMRA coordinate cross-border standards for electrolyte barrier performance, creating dual-certification requirements for suppliers serving Ontario's emerging cell manufacturing cluster. The country's national pharmaceutical regulator framework extends to battery material safety assessments. Windsor and Hamilton industrial corridors concentrate procurement activity as cell plants scale toward gigafactory thresholds.
Mexico
Toray Industries sustains technology leadership in polyamide base films through integrated resin-to-film operations in Mexican manufacturing zones. The country's industrial standards body aligns with North American automotive certification requirements. Baja California and central Mexican states host film conversion capacity serving cross-border automotive supply chains.
North America Lithium-Ion Battery Pouch Film Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue coating technology specialization and regional distribution control. The market structure concentrates among integrated resin-to-film operators and dry-process laminators with compliant infrastructure. Three archetypes dominate: Asian-headquartered multinationals with captive raw material supply, North American converters leveraging IRA domestic content qualification, and coating technology specialists compressing performance gaps between process types. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification timelines compress.
Within the multinational tier, Toray Industries, Kolon Industries, and DNP Group represent distinct geographic anchoring strategies. Toray exemplifies integrated manufacturing archetypes through resin-to-film operations. Kolon occupies a position emphasizing dry-process lamination expertise. DNP anchors regional supply through southeastern U.S. conversion facility positioning. These players illustrate how technology specialization and geographic proximity to automotive clusters determine competitive positioning.
| Leading Market Players |
|---|
| Ube Industries, Ltd. |
| Kolon Industries, Inc. |
| Toray Industries, Inc. |
| Targray |
| DNP Group |
| SK Innovation Co., Ltd. |
| Kureha Corporation |
| MTI Corporation |
| Sumitomo Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EPA emissions compliance for solvent-based lamination processes gates qualified supply access and premium-tier pricing power, as converters bearing abatement infrastructure costs capture automotive qualification premiums while non-compliant operators retreat to commoditized spot markets.
Pricing Analysis
Warranty and technical service bundling separates tier-one automotive contracts from unbundled spot transactions for consumer electronics batches. Contract-based long-term offtake dominates electric vehicle procurement, with price differentiation hinging on ISO certification tier and volume scale commitments. Cost compression in standard-grade films is intensifying because Asian foil suppliers are passing through energy cost volatility. Consumer electronics buyers exhibit highest price sensitivity, while automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Automotive qualification timelines gate supply chain participation, restricting viable converter pools to established players with Health Canada and EPA dual-certification track records. Aluminum foil feedstock draws from Chinese, South Korean, and Japanese smelter operations, while polyamide base films and adhesive chemistries rest on Japanese and Korean resin supply. Single-source vulnerability in battery-grade foil creates qualification delays when primary suppliers face output constraints. Distribution runs through southeastern U.S. conversion facilities positioned for IRA-compliant domestic content thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where OSHA N-methyl-2-pyrrolidone exposure limits and EPA emissions oversight erect capital barriers that protect incumbent margins from undercapitalized challengers.
For Market Incumbents: Lock in long-term supply agreements with Great Lakes automotive engineering teams before qualification timelines compress further. Expand dry-process capacity in Alabama and Tennessee to capture IRA-compliant domestic content premiums. Coating technology specialists threaten process-based differentiation; defend through metrology investment for 100 μm and 200 μm tolerance bands. For New Entrants and Emerging Players: Coating technology specialization offers the most penetrable wedge against established dry-process laminators. Target southeastern U.S. battery factory supply zones where equipment refresh cycles create greenfield site viability. Pursue joint development programs with solid-state cell developers seeking PET-based outer layer dimensional stability. For Investors and Strategic Acquirers: DNP Group's Alabama facility qualification completion is the leading indicator that southeastern distribution channel control is consolidating. Five-to-ten year viability favors converters with integrated resin-to-film operations or captive adhesive chemistry capabilities. Acquisition targets should display Health Canada electrolyte barrier validation progress. Monitor Toray Industries' Mexico capacity expansion announcements as the inflection signal for polyamide base film supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foil Supply | Mitigates Asian smelter concentration risk for IRA-qualified laminators. |
| Coating Technology Line Electrification | Compresses performance gaps between dry and wet process outputs for automotive puncture resistance specs. |
| Dual-Certification Infrastructure Investment | Enables simultaneous EPA emissions compliance and Health Canada barrier validation for Ontario-bound supply. |
| Long-term Supply Agreement Structuring | Locks in volume-tiered pricing with Great Lakes cell plants scaling toward gigafactory thresholds. |
| Joint Development Partnership with Solid-State Programs | Positions PET-based outer layers for next-generation cell-to-pack architectures in Detroit and Lordstown corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with polymer film plant managers, automotive Tier 1 procurement leads, battery cell engineering directors, and adhesive chemistry R&D specialists. Bottom-up and top-down triangulation validated volume estimates against U.S. EPA emissions disclosures, Health Canada PMRA barrier performance filings, and SEC 10-K supply chain disclosures from listed materials companies.
Granularity-level modeling treated product type, technology process, thickness grade, and end-use application as distinct forecast dimensions across the analysis window. CAGRs derived from segment-level growth trajectory blending, incorporating electric vehicle production schedules, IRA domestic content threshold evolution, and cell-to-pack architecture adoption curves as battery-specific demand drivers.
Several conditions sit outside the modeled scope, including speculative solid-state cell commercialization timelines and potential aluminum foil tariff regime changes. Forecasts reflect documented assumptions about qualification timeline compression and dual-certification harmonization progress. A model refresh is warranted upon material change in Inflation Reduction Act domestic content threshold enforcement or OSHA N-methyl-2-pyrrolidone exposure limit revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
2 Seal Pouches Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Doy Pouch Packaging Market
Pouch
Foil Pouch Packaging Market
Pouch
South Africa Pouch Packaging Market
Pouch
Liquid Pouch Packaging Market
Pouch
Open Mouth Sacks Market
Pouch
Stand-Up Pouches Market
Pouch
France Pouch Packaging Market
Pouch
Wrap-Around Packers Market
Pouch
Squeeze Pouch Market
Pouch
Russia Pouch Packaging Market
Pouch
Sterilization Pouches Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Child Resistant Pouches Market