
 Retort Pouch Packaging Market | 2026-2036
Retort Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Retort Pouch Packaging Market Outlook
The gap between premium retort pouches with high-barrier foil laminates and commodity polypropylene formats is restructuring procurement across the food sector. Amcor leverages its integrated film manufacturing to sustain margin on complex multilayer structures. ProAmpac differentiates through specialized retort-capable printing for brand-sensitive ready-meal clients.
Retort pouch packaging denotes a flexible multilayer container, typically comprising polyester outer web, aluminum foil or metallized barrier core, and polypropylene sealant inner layer, engineered to withstand 121°C steam sterilization while maintaining seal integrity and print quality. Stand-up pouches and zipper-equipped variants now capture the fastest-growing application tier as consumers prioritize convenience and reclosability in ambient-stable food and personal care products. Flat pouches remain the volume anchor in bulk institutional channels where unit cost dominates procurement criteria.
The FDA regulates retort pouch materials under 21 CFR 177.1390 for laminates in contact with food, while the EU F-Gas Regulation and REACH constrain fluorinated barrier chemistries and adhesive systems. Food contact compliance costs are diverting R&D spend toward non-fluorinated high-barrier alternatives. Stakeholders must monitor how evolving extended producer responsibility frameworks in North America and Europe reshape material specifications and recycling infrastructure requirements for multilayer flexible packaging.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing material redesign across multilayer flexible formats, compressing development timelines and diverting R&D budgets toward recyclable barrier alternatives.
Growth Catalysts
- Institutional foodservice procurement:Hospital, military, and airline catering buyers are expanding ambient-stable meal programs. Retort pouches reduce storage footprint and preparation labor compared to canned alternatives.
- REACH fluorinated chemistry constraints:The EU's tightening restrictions on perfluorinated barrier coatings are accelerating investment in silicon oxide and aluminum oxide vapor-deposited alternatives with comparable oxygen transmission rates.
- Southeast Asian export-processing concentration:Thai and Vietnamese seafood processors are converting bulk retort operations to pre-formed pouch formats for direct-to-retail export, capturing higher unit margins.
Market Restraints
- Aluminum foil supply concentration:Over 70% of rolled foil supply for high-barrier laminates originates from Chinese smelters, exposing converters to tariff volatility and energy-cost pass-throughs.
- Multilayer recycling infrastructure gaps:Mechanical separation of polyester-aluminum-polypropylene laminates remains uneconomical at scale, limiting post-consumer recovery rates and inviting extended producer responsibility surcharges.
- Retort sterilization energy intensity:Steam autoclave operations require 121°C sustained thermal input, constraining co-location with renewable-powered facilities and elevating carbon accounting scrutiny.
Strategic Opportunities
- Indian PLI scheme for food processing:Production-linked incentives for ready-to-eat meal manufacturing are attracting retort pouch converters to establish domestic laminating capacity near Maharashtra and Gujarat processing clusters.
- Mono-material polypropylene retort structures:Advances in nucleating agents and orientation technology are enabling full-PP pouches that satisfy existing recycling streams without barrier performance degradation.
- E-commerce ambient meal subscription channels:Direct-to-consumer ready-meal brands are specifying matte-finish retort pouches with high-definition gravure printing to differentiate unboxing experiences.
Industry Challenges
- Migration testing protocol complexity:FDA 21 CFR 177.1390 compliance for new laminate structures requires 6-18 month extraction studies, delaying commercialization of reformulated barrier webs.
- Retort process engineering talent scarcity:Experienced thermal process authorities capable of validating 121°C sterilization cycles for novel pouch geometries command premium compensation and limited geographic mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retort Pouch Packaging Market |
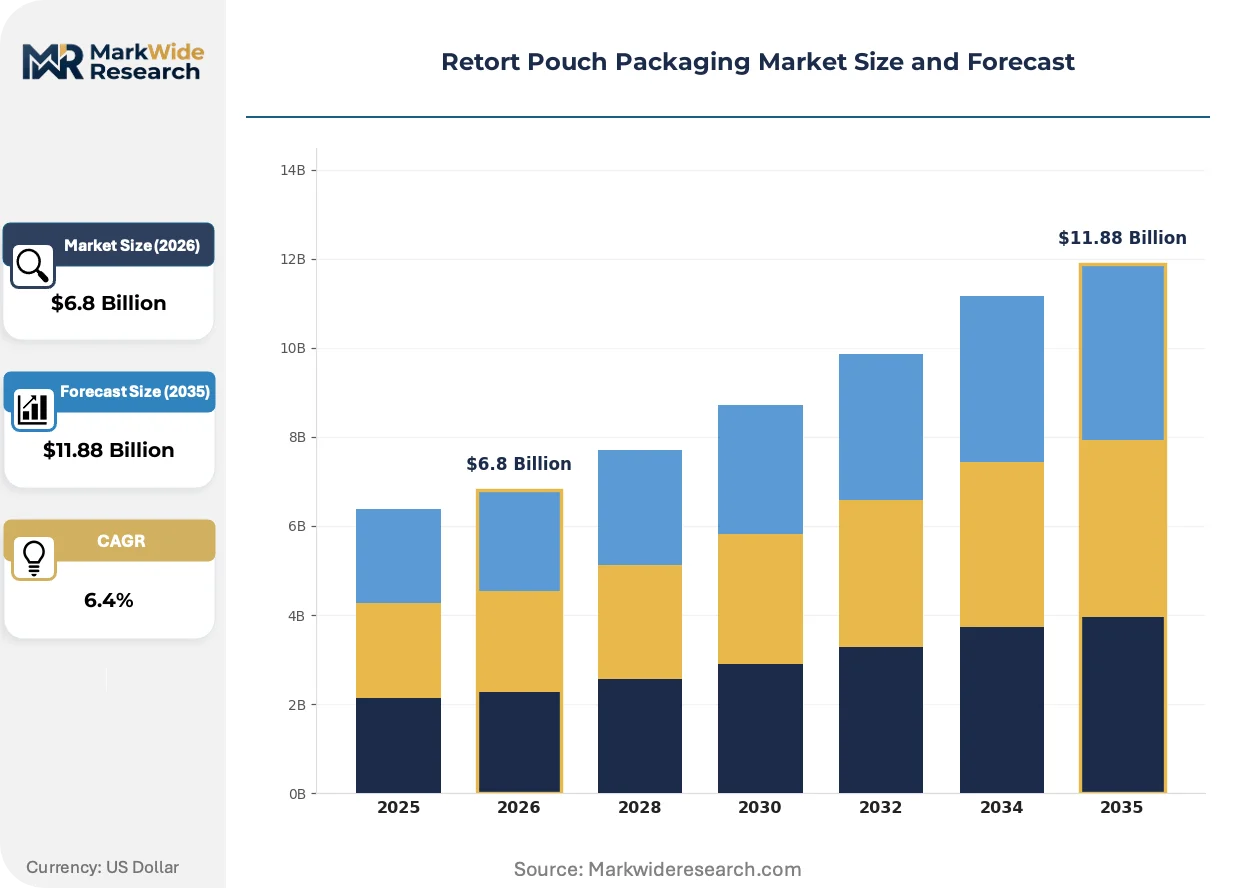
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Gusseted Pouches Material: Polyester, Nylon, Foil Laminates, Polypropylene Application: Food, Beverages, Pharmaceuticals, Personal Care Closure Type: Heat Seal, Zip Lock, Reusable, Tear Notch |
| Companies Covered | Amcor, Mondi Group, Sealed Air, ProAmpac, Huhtamaki, Sonoco Products, Berry Global, Constantia Flexibles, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retort Pouch Packaging Market Strategic Shifts
Digital printing integration and barrier material substitution are compressing minimum order quantities while expanding design flexibility for brand-sensitive ambient food categories.
Laser scoring and precision die-cutting technology is automating easy-open feature integration directly at the converting line, eliminating secondary pouch fabrication steps. Mid-size ready-meal brands are adopting these systems to reduce tooling costs for seasonal SKU proliferation. The technology is automating what previously required manual pouch specification revisions and extended procurement cycles.
The EU F-Gas Regulation phase-down schedules are constraining hydrofluorocarbon-based barrier coating availability, redirecting converter R&D toward plasma-enhanced chemical vapor deposition alternatives. Laminate suppliers are qualifying silicon oxide-coated polyester films at scale to maintain European market access. Premium pet food and organic ready-meal segments are absorbing the 15-20% material cost premium to secure regulatory-compliant packaging.
Buyer consolidation among European grocery private-label operators is compressing supplier rosters and elevating technical service expectations. Retailers are mandating centralized specification management with direct converter relationships, displacing traditional distributor intermediaries. German and Dutch supermarket chains are piloting this model first, with Scandinavian markets following within 18-24 months.
Retort Pouch Packaging Market Segmentation
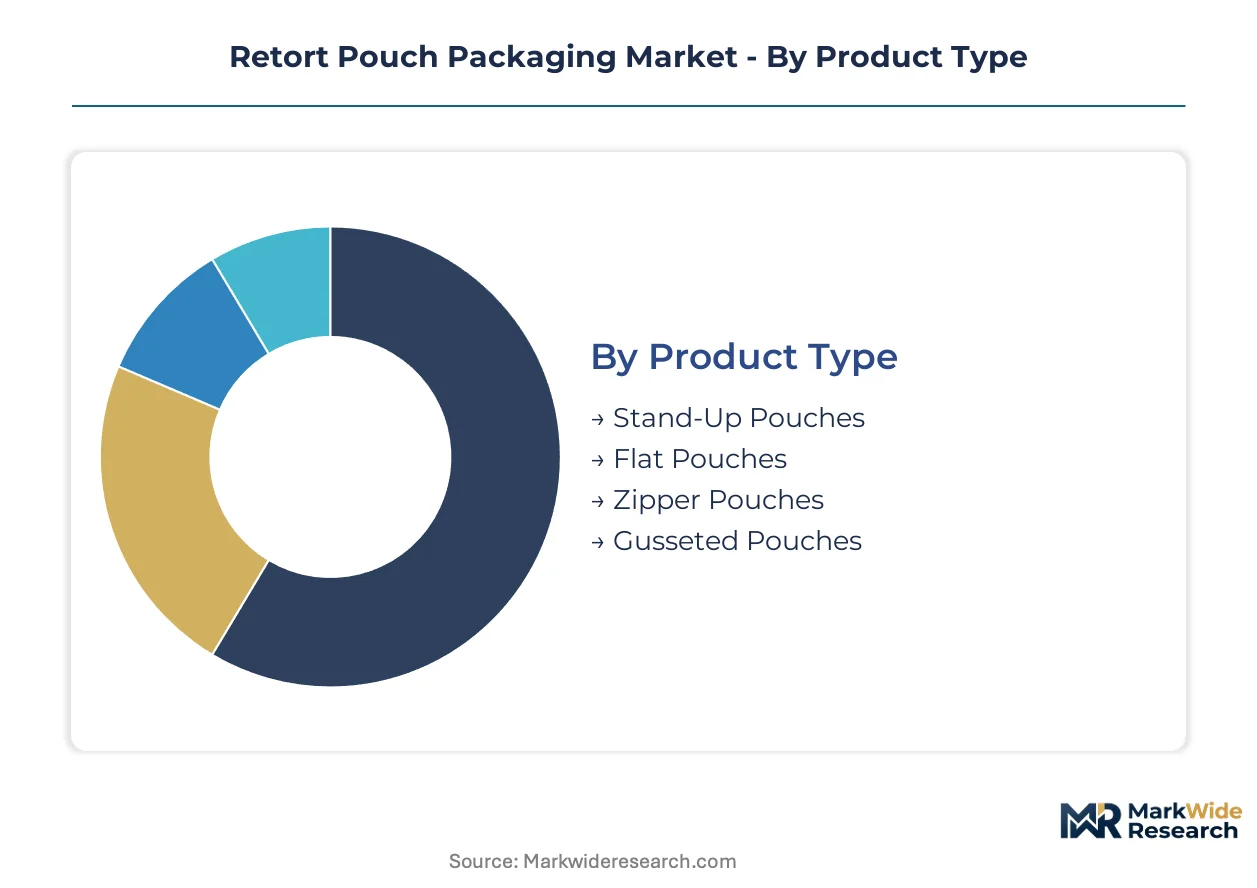
Retort pouch converters face divergent technical specifications across end-use categories. Material selection and pouch geometry decisions cascade through sterilization validation, barrier performance, and recycling compliance requirements.
Product Type:
Upgrade cycles from rigid cans to flexible formats are accelerating as institutional buyers retool meal service infrastructure for reduced storage footprint and labor efficiency.
- Stand-Up Pouches:These structures incorporate bottom gusset folds that enable vertical shelf display and improved cube utilization in retail and foodservice environments. Demand is concentrating in Southeast Asian seafood export operations where Thai and Vietnamese processors convert bulk retort operations to retail-ready formats for direct supermarket distribution in Japan and South Korea.
- Flat Pouches:Two-dimensional laminates minimize material usage and maximize pallet density for bulk institutional shipments. Hospital, military, and airline catering procurement in the United States and Germany prioritizes these configurations where unit cost dominates over shelf presentation.
- Zipper Pouches:Reclosable interlocking profiles extend product usability across multiple consumption occasions. European organic ready-meal brands specify these for premium ambient-stable offerings targeting single-person households.
- Gusseted Pouches:Side-folded expansions accommodate irregular product geometries and volume variations. Indian PLI-supported food processing clusters near Maharashtra are adopting these for curry and rice meal exports.
Volume placements concentrate in Flat Pouches; the faster expansion belongs to Stand-Up Pouches.
Material:
Cost tier stratification separates commodity polypropylene from engineered multilayer structures with vapor-deposited barrier coatings.
- Polyester:Biaxially oriented polyethylene terephthalate provides dimensional stability and print receptivity as the outer web in standard laminates. FDA 21 CFR 177.1390 compliance documentation accompanies most commercial grades.
- Nylon:Polyamide layers contribute puncture resistance and oxygen barrier in thermoformed retort applications. Japanese seafood processors specify nylon-containing structures for bone-in fish products.
- Foil Laminates:Aluminum foil cores deliver near-zero oxygen and moisture transmission for extended shelf-life requirements. Chinese smelter concentration in rolled foil supply exposes converters to tariff volatility and energy-cost fluctuations.
- Polypropylene:Cast and oriented PP sealant layers provide heat-seal integrity at retort temperatures. Mono-material PP structures are gaining traction in German recycling-compliant packaging mandates.
Commodity polypropylene dominates current tonnage; engineered barrier laminates command the steepest expansion trajectory.
Application:
Customer type differentiation separates institutional procurement specifications from brand-sensitive retail requirements.
- Food:Ready-to-eat meals, seafood, and curry products constitute the core demand base. EU Packaging and Packaging Waste Regulation compliance costs are diverting R&D toward recyclable barrier alternatives.
- Beverages:Retort-compatible spouted pouches address ambient-stable liquid nutrition and coffee concentrates. South Korean convenience store chains are piloting these for shelf-stable drink programs.
- Pharmaceuticals:Sterile medical nutrition and enteral feeding products require validated aseptic processing documentation. FDA extraction study protocols demand 6-18 month migration testing timelines.
- Personal Care:High-temperature sterilizable masks and topical treatments represent an emerging specification tier. Premium pet food segments in France and the Netherlands absorb material cost premiums for regulatory-compliant packaging.
Food applications anchor installed capacity; pharmaceutical validation requirements are climbing the fastest.
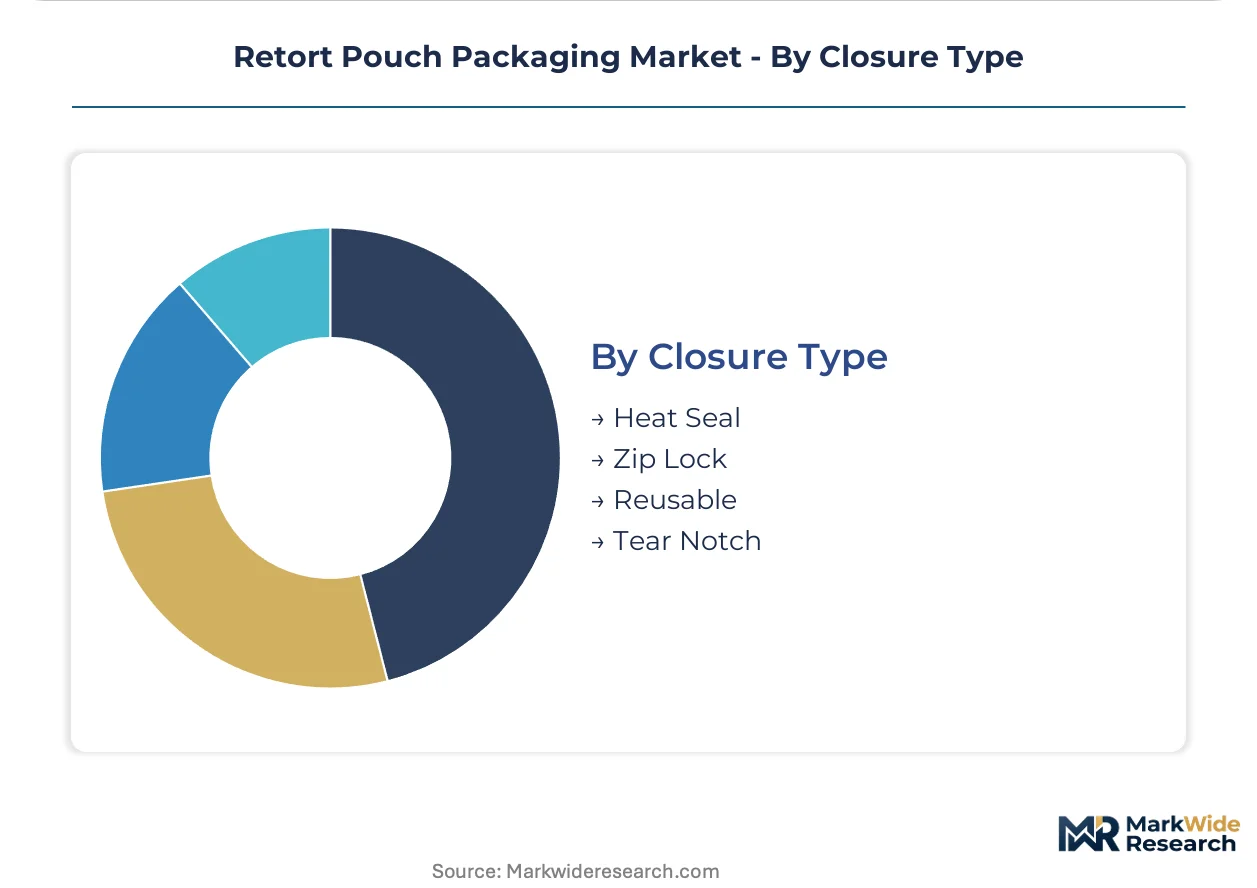
Closure Type:
Margin structure varies sharply between commodity heat-seal specifications and value-added reclosable features.
- Heat Seal:Standard fusion bonds between sealant layers provide tamper-evidence at lowest unit cost. Bulk institutional channels in the United States specify these exclusively.
- Zip Lock:Interlocking plastic profiles enable repeated opening and closing without compromising barrier integrity. Direct-to-consumer ready-meal subscription brands in the United Kingdom specify matte-finish pouches with these features.
- Reusable:Screw-cap and spout assemblies transform single-use pouches into multi-occasion containers. German supermarket private-label operators are mandating these for premium ambient soup lines.
- Tear Notch:Laser-scored or die-cut initiation points enable clean opening without cutting tools. Mid-size ready-meal brands adopt these to reduce tooling costs for seasonal SKU proliferation.
Heat Seal configurations dominate current volume placements; Reusable closure systems are gaining share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok anchors the highest concentration of retort pouch demand, with Thai seafood processors converting bulk retort operations to retail-ready pouch formats for Japanese and South Korean supermarket distribution.
United States
Hospital, military, and airline catering buyers are expanding ambient-stable meal procurement. FDA 21 CFR 177.1390 compliance documentation accompanies most commercial laminate grades. Midwestern foodservice distribution clusters near Chicago are retooling warehouse infrastructure for flexible format storage density.
Germany
Supermarket private-label operators are mandating centralized specification management with direct converter relationships. REACH fluorinated chemistry constraints are accelerating investment in silicon oxide vapor-deposited alternatives. The Ruhr industrial corridor hosts pilot programs for mono-material polypropylene recycling-compliant packaging.
China
Over 70% of rolled aluminum foil supply for high-barrier laminates originates from domestic smelters. The country's national packaging regulator enforces food contact material standards under GB frameworks. Zhejiang and Jiangsu provinces concentrate converting capacity for export-oriented seafood and curry pouch production.
India
Production-linked incentives for ready-to-eat meal manufacturing are attracting retort pouch converters to establish domestic laminating capacity. FSSAI food contact compliance requirements govern multilayer laminate approval timelines. Maharashtra and Gujarat processing clusters are adopting gusseted pouch formats for curry and rice meal exports.
Vietnam
Seafood processors are converting bulk retort operations to pre-formed pouch formats for direct-to-retail export. The country's national trade regulator oversees export-processing zone incentives. Ho Chi Minh City industrial corridors are capturing higher unit margins through retail-format conversion.
Retort Pouch Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier complexity and technical service depth. The vendor base stratifies between integrated film manufacturers, specialized converters, and regional laminators. Three archetypes dominate: multilayer structure specialists, high-definition printing converters, and mono-material recyclability innovators. Consolidation through backward integration into film extrusion and geographic expansion into Southeast Asian processing zones represent the dominant competitive vectors.
Among integrated packaging conglomerates, Amcor, Mondi Group, and ProAmpac occupy positions across the premium-mid-tier spectrum. Amcor exemplifies the integrated film manufacturing archetype with captive supply of complex multilayer structures. Mondi Group represents European-based converters navigating REACH fluorinated chemistry constraints through alternative barrier qualification. ProAmpac anchors the specialized printing tier, serving brand-sensitive ready-meal clients with retort-capable gravure and digital systems.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Sealed Air |
| ProAmpac |
| Huhtamaki |
| Sonoco Products |
| Berry Global |
| Constantia Flexibles |
| Winpak |
| Others |
Value Chain & Pricing Dynamics
Retort process engineering talent scarcity in Germany and the United States widens pricing-tier spreads as experienced thermal process authorities command premium compensation, forcing converters to pass labor-cost differentials downstream or absorb margin compression in commodity polypropylene segments.
Pricing Analysis
Throughput-based sterilization validation pricing anchors the retort pouch market, with converters charging according to autoclave cycle efficiency and documented seal-integrity outcomes rather than material weight alone. Pricing stratifies across premium, standard, and economy tiers driven by barrier complexity and FDA 21 CFR 177.1390 compliance documentation depth. Cost compression in commodity flat pouches is intensifying because Chinese foil supply concentration exposes converters to energy-cost pass-throughs. Institutional foodservice buyers in the United States exhibit the highest price sensitivity, while European organic ready-meal brands absorb material cost premiums for regulatory-compliant packaging.
Supply Chain Analysis
Warehouse-distribution layer reconfiguration around Bangkok, Ho Chi Minh City, and Chicago is reshaping downstream logistics as seafood exporters and institutional foodservice distributors retool for flexible format storage density. Raw material supply draws from Chinese aluminum smelters, German film extrusion facilities, and Indian polymer processing clusters. Tariff exposure on rolled foil imports represents the dominant structural risk. Distribution runs through converter-direct relationships with supermarket private-label operators, displacing traditional distributor intermediaries in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation mandates are compressing development timelines and diverting R&D budgets, forcing sub-scale converters toward exit or acquisition as compliance costs outstrip their capitalization.
For Market Incumbents: Deploy backward integration into captive film manufacturing to defend margin position against commodity polypropylene price erosion. Amcor's integrated multilayer structure approach exemplifies this lever. Accelerate silicon oxide barrier qualification to preempt REACH fluorinated chemistry constraints. Consolidate specification management relationships with German and Dutch supermarket chains before Scandinavian market adoption spreads. For New Entrants and Emerging Players: Begin with mono-material polypropylene retort structures targeting German recycling-compliant packaging mandates, where incumbent qualification timelines create temporary white space. Indian PLI-supported food processing clusters near Maharashtra offer the most penetrable geography for gusseted pouch formats. Pursue direct converter relationships with mid-size ready-meal brands seeking matte-finish gravure differentiation for e-commerce subscription channels. For Investors and Strategic Acquirers: Re-rating potential sits with specialized retort-capable printing converters given digital printing integration compressing minimum order quantities and expanding design flexibility. Long-term viability favors converters with validated FDA extraction study protocols and established Southeast Asian export-processing relationships. Watch for EU extended producer responsibility surcharge implementation as the inflection signal for recyclable barrier alternative adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive supply of polyester and polypropylene webs insulates Amcor from Chinese smelter tariff volatility. |
| Silicon Oxide Barrier Qualification | Mondi Group's alternative coating investment maintains European market access under REACH constraints. |
| Direct Converter Relationships | German supermarket chains piloting centralized specification management displace traditional distributor intermediaries. |
| Mono-Material PP Structure Development | German recycling-compliant mandates accelerate full-polypropylene pouch adoption without barrier degradation. |
| Digital Printing Capability Expansion | ProAmpac's specialized gravure systems capture brand-sensitive ready-meal clients seeking seasonal SKU proliferation. |
Study Parameters
Independent corroboration across converter operations managers, thermal process authorities, supermarket private-label procurement leads, and FDA regulatory consultants underwrites the qualitative findings. Primary interviews with film extrusion technical directors and secondary validation through SEC 10-K filings, customs trade data, and EU Packaging and Packaging Waste Regulation impact assessments anchor the evidence base. Bottom-up shipment data from Southeast Asian export-processing zones triangulates against top-down demand modeling from institutional foodservice procurement databases.
Comparable-period anchoring to historical retort sterilization validation cycles and laminate material cost trajectories structures the projection horizon. Segmentation modeling spans pouch geometry, barrier material complexity, closure type sophistication, and end-use regulatory tier across the analysis window. CAGRs derive from sterilization throughput expansion rates and export-processing zone capacity additions. Migration testing protocol timelines and REACH fluorinated chemistry phase-down schedules feed industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical validation requirements and premium pet food specifications carry tighter precision than commodity institutional flat pouch volumes. Forecasts reflect documented assumptions regarding aluminum foil supply stability and EU extended producer responsibility implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Child Resistant Pouches Market
Pouch
Poland Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
South Africa Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Fin Seal Pouches Market
Pouch
Zipper Pouch Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Russia Pouch Packaging Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Slider Zipper Pouch Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Morocco Pouch Packaging Market
Pouch
Aluminium Bags and Pouches Market
Pouch
OPP Pouches Market