
 Thailand Pouch Packaging Market | 2026-2036
Thailand Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Pouch Packaging Market Insights
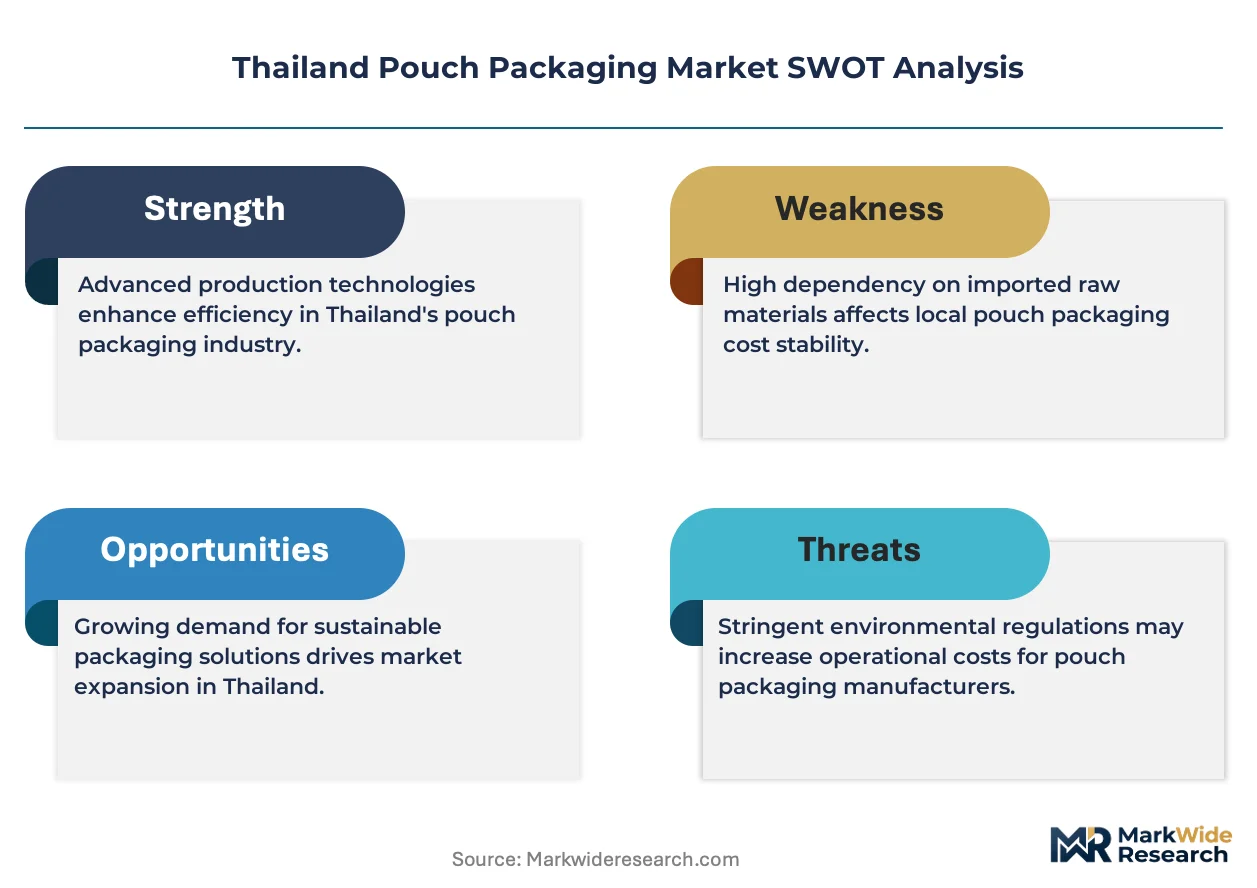
Thailand's Eastern Economic Corridor is fragmenting as new flexible packaging capacity comes online near Rayong and Chonburi. Amcor plc leverages its regional film extrusion network to supply multinational food brands with high-barrier laminates. SCG Packaging anchors domestic demand through its integrated pulp-to-packaging operations serving Thai consumer goods manufacturers. TPBI competes on price in the commodity polyethylene segment for local sauce and condiment producers.
Pouch packaging denotes flexible containers formed from single or multilayer substrates, typically sealed on three or four sides with optional reclosure features, designed to hold solids, liquids, or semi-liquids under ambient or retort conditions. Stand-up pouches with bottom gusset construction dominate shelf presence in Thai retail channels, while retort pouches withstand sterilization temperatures for ambient-stable curry and seafood products. Plastic-based laminates retain the largest volume share, though aluminum-foil composites command premium positioning in pharmaceutical and high-oxygen-barrier food applications. The food and beverage end-use segment drives material innovation, with converters developing thinner gauge coextruded films to meet TISI migration limits without sacrificing shelf life.
TISI standards, FDA Thailand notifications for food-contact substances, and Ministry of Industry waste management directives collectively shape substrate selection and recyclability claims in the Thai market. Compliance costs favor larger converters with in-house testing laboratories, squeezing smaller extrusion houses dependent on imported masterbatch formulations. Stakeholders must monitor pending extended producer responsibility regulations that could restructure collection infrastructure for multilayer flexible waste.
Market Dynamics
TISI's tightening migration limits for food-contact materials is forcing Thai converters to abandon legacy monolayer structures. This regulatory compression is accelerating capital deployment toward multilayer coextrusion and certified substrate qualification.
Growth Catalysts
- Retort pouch sterilization compatibility:Thai ready-to-eat meal processors are expanding ambient-stable curry and seafood packaging runs. This material specification is pulling demand toward high-barrier laminates with aluminum oxide or silicon oxide coatings.
- Eastern Economic Corridor industrial clustering:New flexible packaging capacity near Rayong and Chonburi is shortening logistics loops for Bangkok-based snack food manufacturers. Proximity is reducing working capital requirements for just-in-time procurement.
- Extended producer responsibility preparation:Pending Ministry of Industry waste management directives are incentivizing converters to design for recyclability. Early compliance is creating preferred-supplier status with multinational brand owners.
Market Restraints
- Masterbatch import dependency:Smaller Thai extrusion houses rely on imported colorant and additive formulations from China and South Korea. Currency volatility and shipping delays are compressing margin buffers for sub-scale operators.
- Multilayer film recycling infrastructure gaps:Thailand lacks commercial-scale delamination capacity for post-industrial flexible waste. Landfill diversion rates remain constrained by technical limitations in separating incompatible polymer layers.
- TISI testing cost concentration:Compliance laboratory investments favor integrated converters with captive testing facilities. Independent extruders face structural barriers to certification speed.
Strategic Opportunities
- Isaan region food processing expansion:Northeast Thailand's growing agro-industrial base is underserved by local pouch converters. Greenfield extrusion capacity in Khon Kaen or Nakhon Ratchasima could capture sauce and condiment packaging demand.
- Mono-material polyethylene pouch platforms:TISI recyclability guidelines are creating design space for all-PE structures with compatible sealant and barrier layers. Early movers can secure shelf space with retailers implementing plastic pact commitments.
- Pharmaceutical barrier pouch qualification:Thai generic drug manufacturers are localizing packaging to reduce import lead times. Aluminum-foil composite pouch supply represents an adjacent market with premium pricing.
Industry Challenges
- Coextrusion die design expertise scarcity:Thai technical institutes produce limited polymer processing specialists. Converters are competing for experienced extrusion engineers who can optimize layer distribution for barrier performance.
- Legacy solvent-based lamination asset stranding:Water-based adhesive conversion requires capital-intensive drying system upgrades. Mid-scale operators face execution risk in managing transition downtime without volume loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Pouch Packaging Market |
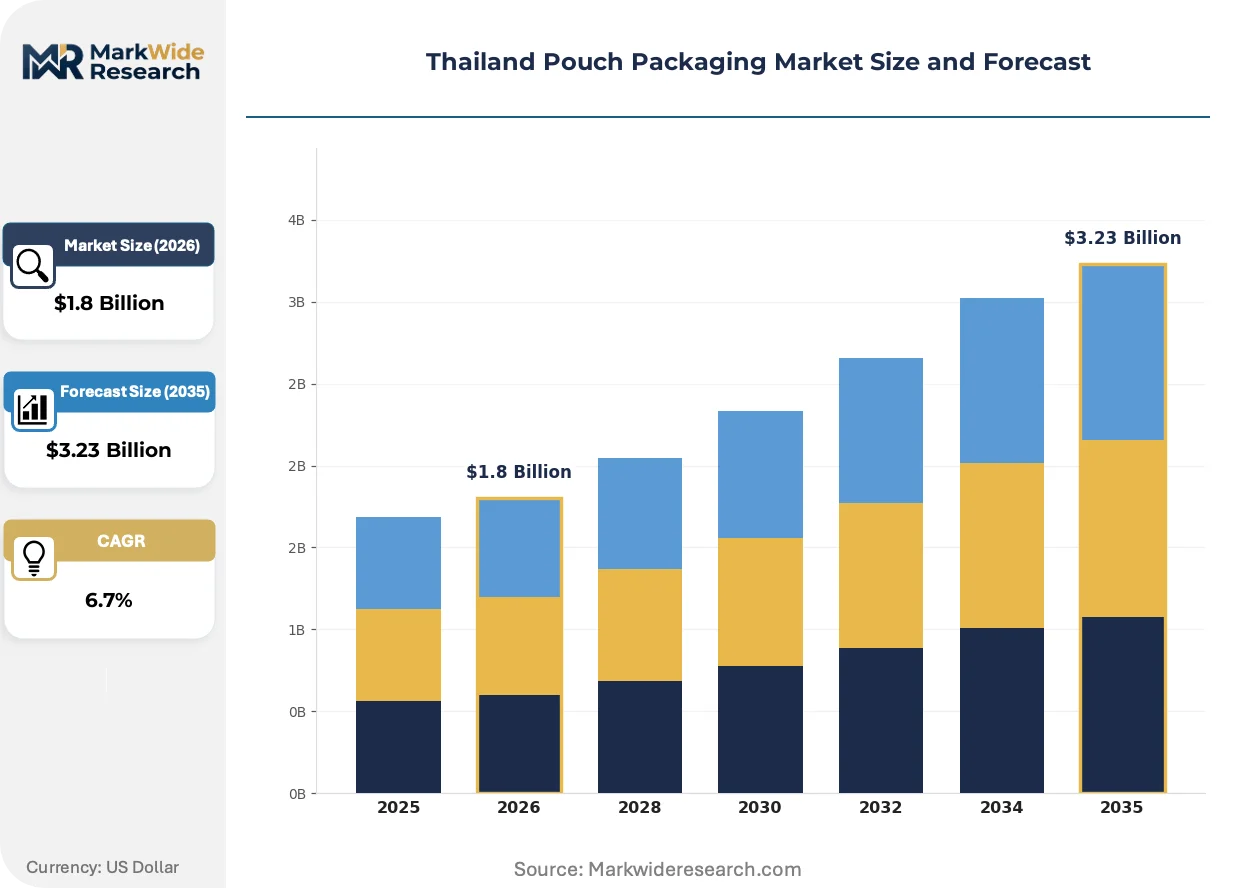
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Retort Pouches, Zip Lock Pouches Material: Plastic, Aluminum, Paper, Composites End Use Industry: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Packaging Size: Small, Medium, Large, Bulk |
| Companies Covered | Amcor plc, Huhtamaki Oyj, Sealed Air Corporation, SCG Packaging, TPBI, Thai Plaspac, Thung Hua Sinn Group, Prepack Thailand Co., Ltd., Thai FlexPack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Pouch Packaging Market Trends and Innovations
Digital prepress workflows and virtual prototyping tools are compressing new product development cycles for Thai brand owners. These capabilities are reducing physical sampling costs and enabling faster graphics versioning for seasonal promotions.
Digital flexographic platemaking is virtualizing the traditional cylinder engraving bottleneck for short-run pouch orders. Thai converters serving regional snack brands are adopting computer-to-plate systems to reduce make-ready waste. This technology is virtualizing the economics of sub-10,000-unit production runs previously dominated by rotogravure.
TISI's 2024 notification on food-contact substance positive lists is restricting unapproved additives in multilayer structures. Converters must reformulate adhesives and coatings to eliminate restricted substances. The ready-to-eat meal segment is responding with accelerated migration testing protocols to maintain export eligibility.
Brand owners in Bangkok are consolidating supplier panels to reduce qualification overhead. Direct contracting with integrated film extruders is displacing distributor-mediated procurement for volume pouch programs. This concentration is most visible among multinational beverage bottlers with centralized packaging specification authority.
Thailand Pouch Packaging Market Segmentation
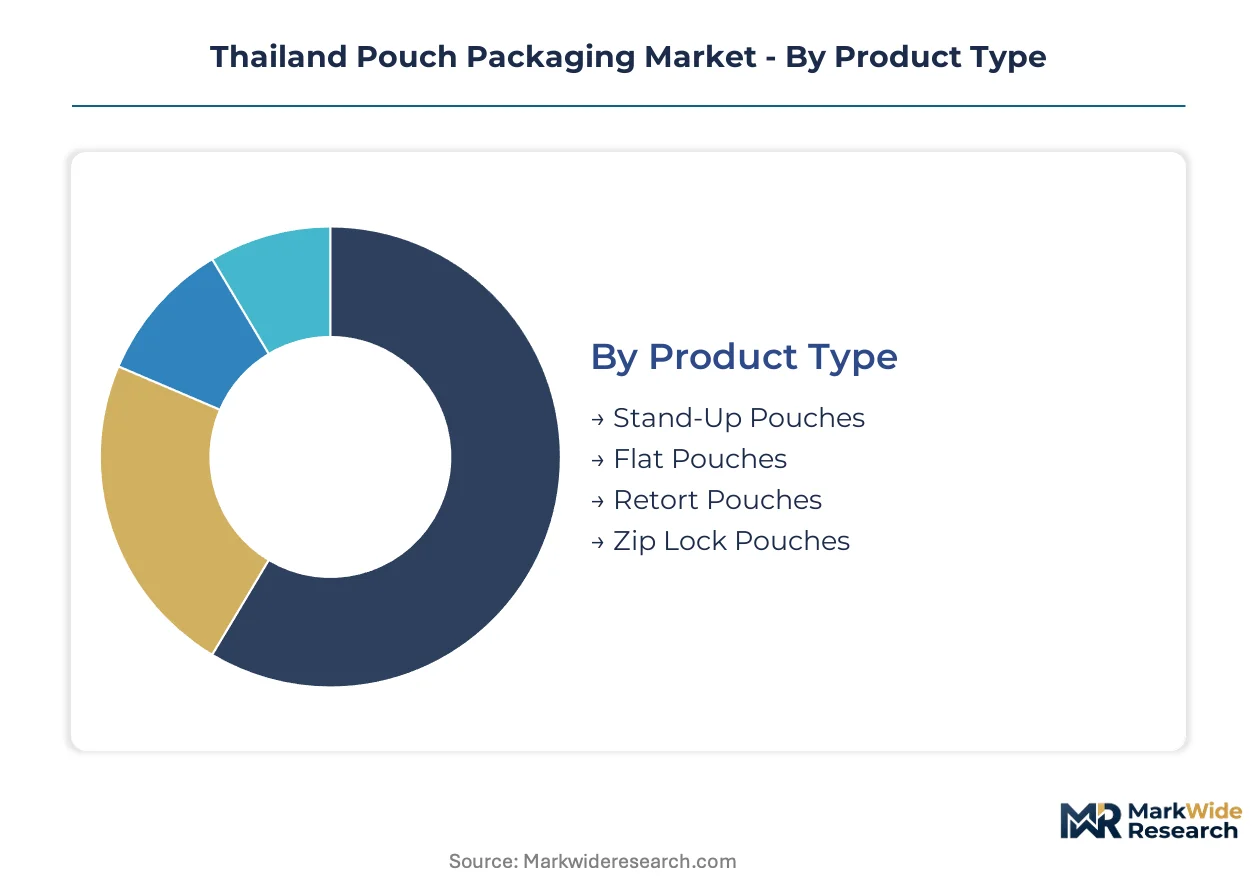
Pouch packaging in Thailand exhibits distinct technical and commercial fault lines across product construction, substrate composition, and end-use application. Understanding these divisions reveals where converter capabilities concentrate and where specification gaps create procurement friction for brand owners.
Product Type:
After-sales service intensity varies sharply across pouch formats, with retort-compatible structures demanding ongoing technical support for sterilization validation and seal integrity monitoring.
- Stand-Up Pouches:Bottom-gusset construction enables vertical shelf display in Thai retail channels. Bangkok-based snack food manufacturers and beverage bottlers concentrate procurement around this format for brand visibility at point of sale.
- Retort Pouches:Multilayer laminates withstand sterilization temperatures for ambient-stable curry and seafood products. Ready-to-eat meal processors in the Eastern Economic Corridor specify high-barrier structures with aluminum oxide or silicon oxide coatings to meet export shelf-life requirements.
- Flat Pouches:Three-side-seal construction dominates commodity sauce and condiment applications. Local producers favor this format for cost-efficient high-volume runs of single-serve portions.
- Zip Lock Pouches:Reclosure features command premium positioning in dried fruit and nut segments. Reusability specifications are gaining traction with retailers implementing plastic pact commitments.
By volume, flat pouches lead. By growth pace, retort pouches are expanding most quickly.
Material:
Substrate selection in Thailand tracks directly against TISI migration compliance burden and recyclability positioning under pending extended producer responsibility frameworks.
- Plastic:Coextruded polyethylene and polypropylene laminates retain the largest volume position. Converters are developing thinner gauge films to meet TISI limits without sacrificing barrier performance for Bangkok-area snack manufacturers.
- Composites:Multilayer structures combining plastic, foil, and paper serve high-barrier pharmaceutical and premium food applications. Certified substrate qualification is accelerating capital deployment toward coextrusion capacity.
- Aluminum:Foil composites command premium pricing in generic drug packaging where moisture and oxygen barrier specifications are critical. Thai pharmaceutical manufacturers are localizing supply to reduce import lead times.
- Paper:Fiber-based substrates with polymer barrier coatings address sustainability positioning for select personal care brands. Limited commercial-scale availability constrains volume expansion.
Plastic dominates current procurement. Composites are climbing the fastest as converters qualify multilayer structures for retort applications.
End Use Industry:
Application-driven specification divergence creates distinct supplier-customer relationships, with food safety certification requirements fragmenting converter capabilities across verticals.
- Food & Beverage:Retort sterilization compatibility and TISI food-contact compliance dominate material specifications. Curry, seafood, and ready-to-eat meal processors in Bangkok and the Eastern Economic Corridor anchor demand for high-barrier laminates.
- Pharmaceuticals:Aluminum-foil composite pouches for generic drug packaging require migration testing protocols that favor integrated converters with captive laboratories. Local manufacturers are displacing imported packaging to shorten supply chains.
- Personal Care:Stand-up pouches with dispensing fitments serve shampoo and conditioner segments. Premium positioning drives specification toward glossy laminates with enhanced graphics capability.
- Household Products:Refill pouches for cleaning concentrates emphasize cost-efficient polyethylene structures. Volume concentration among mass-market retailers favors large extrusion houses with scale economies.
Food and beverage commands the largest share. Pharmaceuticals represent the steepest expansion trajectory as domestic drug packaging localizes.
Packaging Size:
Size-tier economics align with distribution channel requirements, from single-serve convenience formats through institutional bulk packaging for food service operators.
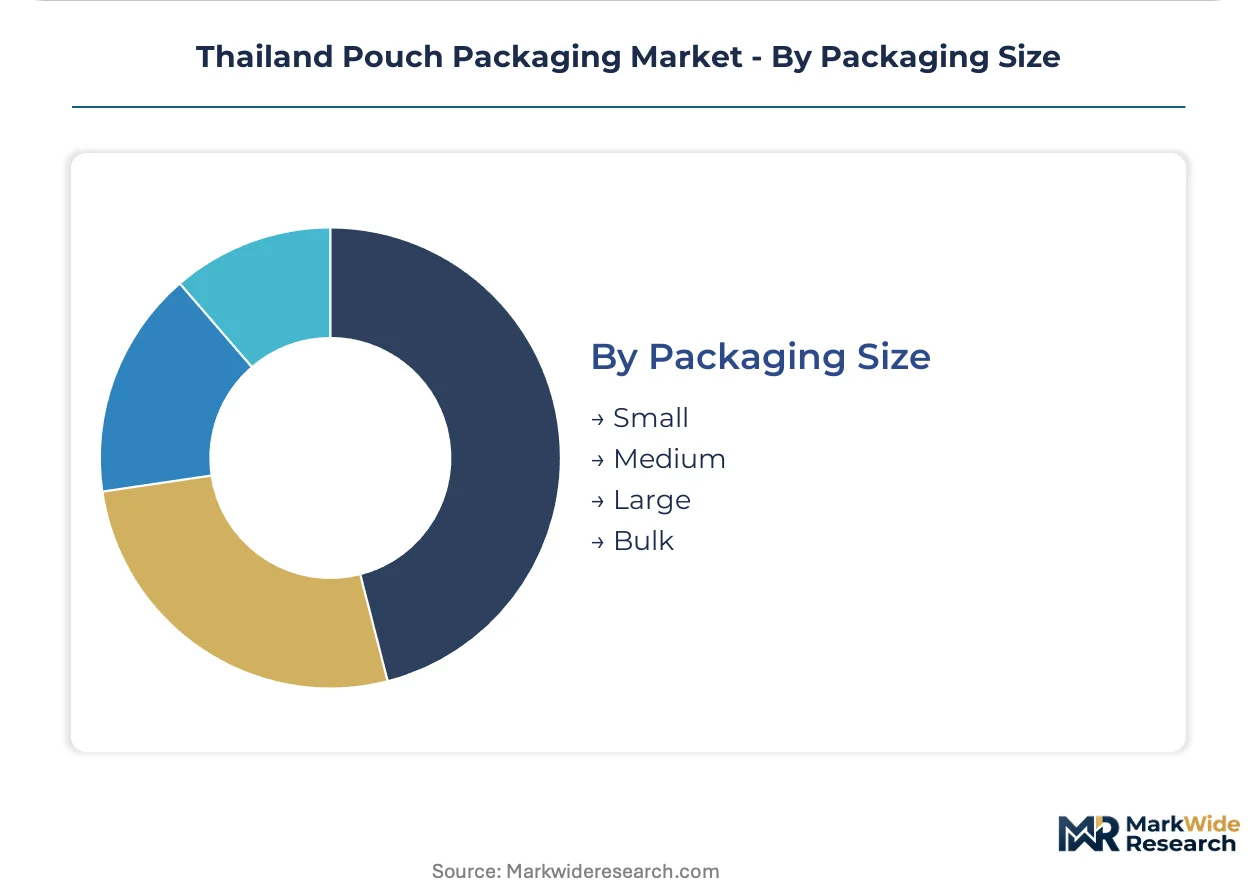
- Small:Single-serve portions for sauces, condiments, and sample products. 7-Eleven and other convenience retail chains in Bangkok drive specification toward portion-controlled formats with high graphics impact.
- Medium:Standard retail sizes for household consumption. This tier captures the broadest converter participation across commodity and specialty producers.
- Large:Family-size and value formats for warehouse club channels. Filling equipment compatibility requirements favor established converters with technical service capabilities.
- Bulk:Institutional and food service quantities. Limited local demand concentrates procurement among specialized industrial packaging suppliers.
Medium sizes lead procurement volume. Small formats are gaining share fastest through convenience retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TISI migration limits and Eastern Economic Corridor industrial clustering anchor Thailand's pouch packaging demand geography. Sub-regional specialization reflects Bangkok's concentration of food processors, Rayong's petrochemical feedstock access, and Isaan's emerging agro-industrial base.
Bangkok Metropolitan Region
Snack food manufacturers and beverage bottlers drive procurement of stand-up pouches with bottom-gusset construction for retail shelf presence. TISI food-contact material rules tighten substrate qualification requirements for converters serving multinational brand owners. Samut Prakan and Pathum Thani industrial estates host integrated film extrusion capacity supplying high-barrier laminates to ready-to-eat meal processors.
Eastern Economic Corridor
Rayong and Chonburi provinces concentrate new flexible packaging capacity near petrochemical feedstock sources. Ministry of Industry waste management directives incentivize design-for-recyclability investments among corridor-based converters. Chonburi's industrial zones shorten logistics loops for just-in-time procurement by Bangkok-based food manufacturers.
Isaan Region
Khon Kaen and Nakhon Ratchasima provinces anchor expanding sauce and condiment processing capacity with limited local pouch converter presence. TISI certification speed disadvantages smaller extrusion houses dependent on imported masterbatch formulations. Greenfield extrusion investment in this corridor could capture underserved agro-industrial packaging demand.
Central Plains
Ayutthaya and Saraburi provinces host secondary food processing clusters requiring medium-volume pouch supply for domestic distribution. Extended producer responsibility preparation creates preferred-supplier screening for converters with recyclability roadmaps. These provinces remain dependent on Bangkok and Eastern Economic Corridor logistics for specialized high-barrier structures.
Southern Thailand
Songkhla and Surat Thani provinces process seafood for domestic and export markets, generating retort pouch specification demand. TISI sterilization validation protocols favor integrated converters with captive testing laboratories over independent operators. Aluminum-oxide-coated laminates for ambient-stable seafood products concentrate procurement among Eastern Economic Corridor suppliers.
Thailand Pouch Packaging Market Competitive Landscape
Capability concentration sits with integrated pulp-to-packaging conglomerates; scale advantage sits with multinational film extrusion networks. The market structures around three tiers: global laminate suppliers with regional extrusion networks, domestic integrated converters with captive testing facilities, and price-competitive commodity extrusion houses. Strategic moves center on multilayer coextrusion capacity deployment and TISI certification speed investments. Water-based adhesive conversion and solvent-based lamination asset transitions create execution risk for mid-scale operators.
Among Thailand-based integrated packaging groups, SCG Packaging anchors domestic demand through pulp-to-packaging operations serving consumer goods manufacturers. TPBI occupies a position within the commodity polyethylene segment for local sauce and condiment producers. Thai FlexPack exemplifies mid-tier converters navigating TISI compliance laboratory investments.
| Leading Market Players |
|---|
| Amcor plc |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| SCG Packaging |
| TPBI |
| Thai Plaspac |
| Thung Hua Sinn Group |
| Prepack Thailand Co., Ltd. |
| Thai FlexPack |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Eastern Economic Corridor flexible packaging is compressing converter margins while simultaneously accelerating price competition for Bangkok-based snack food manufacturers, creating a feedback loop where low utilization drives aggressive bidding for volume contracts.
Pricing Analysis
Bangkok-area converters command premium positioning over Isaan-based competitors due to TISI certification speed and technical service proximity. Three-tier pricing structure across premium, standard, and economy levels separates integrated multilayer specialists from commodity polyethylene extruders and masterbatch-dependent independents. Price differentiation hinges on barrier performance certification and captive laboratory investment. Pricing pressure stems from imported Chinese laminate competition in flat pouch segments. Local sauce and condiment producers exhibit highest price sensitivity; pharmaceutical generic manufacturers show lowest.
Supply Chain Analysis
Extended payment terms from multinational beverage bottlers are squeezing working capital for mid-scale converters dependent on petrochemical feedstock procurement. Raw material sourcing draws from Thailand's Rayong petrochemical complex, South Korean masterbatch suppliers, and Chinese additive formulators. Key inputs include polyethylene resin, aluminum oxide coating substrates, and solvent-based adhesives. Single-source vulnerability concentrates in imported colorant formulations. Distribution runs through converter-direct relationships with Bangkok-based brand owners, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's pouch packaging sector is recovering from a cyclical trough driven by retort pouch sterilization demand expansion in ready-to-eat meal processing.
For Market Incumbents: Insulate margin position through backward integration into multilayer coextrusion capacity and captive TISI testing laboratories. SCG Packaging and Amcor plc anchor competitive position via integrated pulp-to-packaging operations. Threat from Chinese import competition in commodity polyethylene segments demands accelerated certification speed investments. Channel control through direct contracting with multinational beverage bottlers represents the critical defensive lever. For New Entrants and Emerging Players: Mid-market retort pouch supply in Isaan region represents the most penetrable entry point, with Khon Kaen and Nakhon Ratchasima sauce processors underserved by local converter capacity. Mono-material polyethylene platforms for retailer plastic pact compliance offer second white-space target. Go-to-market execution should emphasize TISI pre-certification partnerships with Bangkok-based brand owners seeking supply base diversification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multilayer coextrusion lines as TISI compliance laboratory investments become mandatory. Long-term viability favors integrated converters with captive testing facilities over masterbatch-dependent independents. Acquisition target archetype: mid-tier Thai extruders with qualified barrier laminate capabilities and Eastern Economic Corridor logistics positioning. Signal to watch: Ministry of Industry extended producer responsibility implementation timeline as demand inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Captures retort pouch demand from Thai ready-to-eat meal processors seeking sterilization-compatible barriers. |
| TISI Certification Laboratory Investment | Accelerates substrate qualification speed for converters competing on food-contact compliance. |
| Backward Integration into Masterbatch Formulation | Reduces currency exposure for extruders currently dependent on Chinese and South Korean imports. |
| Mono-Material Polyethylene Platform Development | Aligns converter portfolios with retailer plastic pact commitments and pending extended producer responsibility frameworks. |
| Water-Based Adhesive Conversion | Addresses solvent-based lamination asset stranding risk amid tightening Ministry of Industry environmental directives. |
Research Methodology
The analysis maps stand-up pouch, retort pouch, flat pouch, and zip lock pouch sub-sectors, each validated through converter operations directors, brand owner packaging specification managers, and petrochemical procurement leads. Primary interviews with film extrusion engineers, TISI compliance officers, and Eastern Economic Corridor logistics planners combined with secondary validation from Thai Industrial Standards Institute notifications, FDA Thailand food-contact substance filings, and Ministry of Industry waste management directives. Bottom-up capacity modeling and top-down demand estimation were triangulated across the analysis window.
Assumptions held fixed include TISI migration limit enforcement intensity and Eastern Economic Corridor infrastructure completion timelines; variables included retort pouch sterilization adoption rates and extended producer responsibility implementation pacing. Segmentation dimensions modeled encompass product construction type, substrate material composition, end-use industry vertical, packaging size tier, and regional industrial cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with industry-specific inputs including petrochemical feedstock price trajectories and ready-to-eal meal processing capacity expansion schedules.
Stress conditions across masterbatch import cost volatility, TISI testing backlog durations, and multilayer film recycling infrastructure development were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement and industrial clustering patterns. Macroeconomic deviation, regulatory acceleration, or breakthrough in mono-material barrier technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Europe Retort Pouches Market
Pouch
Fin Seal Pouches Market
Pouch
High-Barrier Pouches Market
Pouch
Slider Pouches Market
Pouch
Foam Pouch Market
Pouch
Zipper Pouch Market
Pouch
United States Pouch Packaging Market
Pouch
Contour Pouches Market
Pouch
South Africa Pouch Packaging Market
Pouch
PCR Pouches Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Compostable Pouches Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Telemetry Pouch Market
Pouch
Brazil Pouch Packaging Market