
 Flexible Water Tanks Market | 2026-2036
Flexible Water Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Water Tanks Market Foresight
Food-grade liner certification is redrawing competitive boundaries in flexible water storage. Xylem Inc. leverages its fluid-handling engineering heritage to dominate municipal and industrial specifications. Labaronne-Citaf anchors European demand with reinforced-fabric tank systems engineered for potable-water compliance. Layfield Group Ltd. specializes in geosynthetic-reinforced designs that extend service life in agricultural and mining deployments across North America.
Flexible water tanks are collapsible, fabric-reinforced reservoirs typically constructed from PVC-coated polyester, polyethylene, or elastomeric rubber composites, with capacities spanning hundreds to millions of liters; they deploy without rigid substructures and fold for transport when empty. Their primary purpose is temporary or semi-permanent liquid containment where fixed infrastructure proves uneconomical or logistically impractical. Pillow tanks lead volume in emergency-response and military logistics due to rapid deployment characteristics, while modular tank configurations capture margin in industrial-scale permanent installations. Agricultural use represents the fastest-expanding application as drip-irrigation networks proliferate in water-stressed growing regions.
The EPA regulates potable-water contact materials in the United States, while the EU Drinking Water Directive harmonizes safety thresholds across member states and Australia's National Health and Medical Research Council publishes comparable guidelines. These frameworks compel manufacturers to certify liner compounds for chemical leaching and microbial resistance, raising barriers for uncertified imports. Stakeholders must monitor evolving material restrictions and regional certification reciprocity to secure procurement contracts with municipal and disaster-relief agencies.
Market Dynamics
EU Drinking Water Directive revisions and Australia's potable-water certification mandates are compressing supplier margins while elevating certified liner manufacturers into municipal procurement channels previously dominated by rigid tank incumbents.
Growth Catalysts
- Drip-irrigation proliferation:Agricultural buyers in water-stressed growing regions are replacing concrete reservoirs with collapsible storage to reduce capital deployment and enable seasonal relocation.
- Emergency-response stockpiling:National disaster-management agencies across multiple continents are mandating rapid-deployment water reserves for drought and wildfire response protocols.
- REACH-compliant material advances:European chemical safety frameworks are accelerating substitution of legacy PVC formulations with bio-based elastomeric composites certified for potable contact.
Market Restraints
- Petrochemical input volatility:Polyester reinforcement fabrics and PVC coatings track crude-oil derivatives, exposing fabricators to margin compression without pass-through pricing power.
- Certification reciprocity gaps:Australia's National Health and Medical Research Council potable-water guidelines lack mutual recognition with EU Drinking Water Directive standards, fragmenting export economics.
- Concrete tank residual preference:Municipal engineers in established infrastructure markets retain specification bias toward permanent rigid structures for multi-decade asset-life accounting.
Strategic Opportunities
- Remote mining logistics:Pilbara and Atacama desert operations require collapsible million-liter systems that eliminate concrete curing delays and reduce transport costs for isolated sites.
- Solar-powered desalination pairing:Photovoltaic-integrated reverse osmosis units are creating demand for buffer storage that flexible tanks supply without foundation requirements.
- EU Green Deal circularity mandates:End-of-life liner recycling specifications are opening procurement preference for manufacturers with closed-loop material recovery programs.
Industry Challenges
- Welding technician scarcity:RF-sealing and hot-air bonding of coated fabrics require specialized skills that vocational pipelines have not scaled to match fabrication demand.
- Multi-jurisdiction certification lag:Simultaneous compliance with EPA, EU Drinking Water Directive, and TGA potable-water protocols extends product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Water Tanks Market |
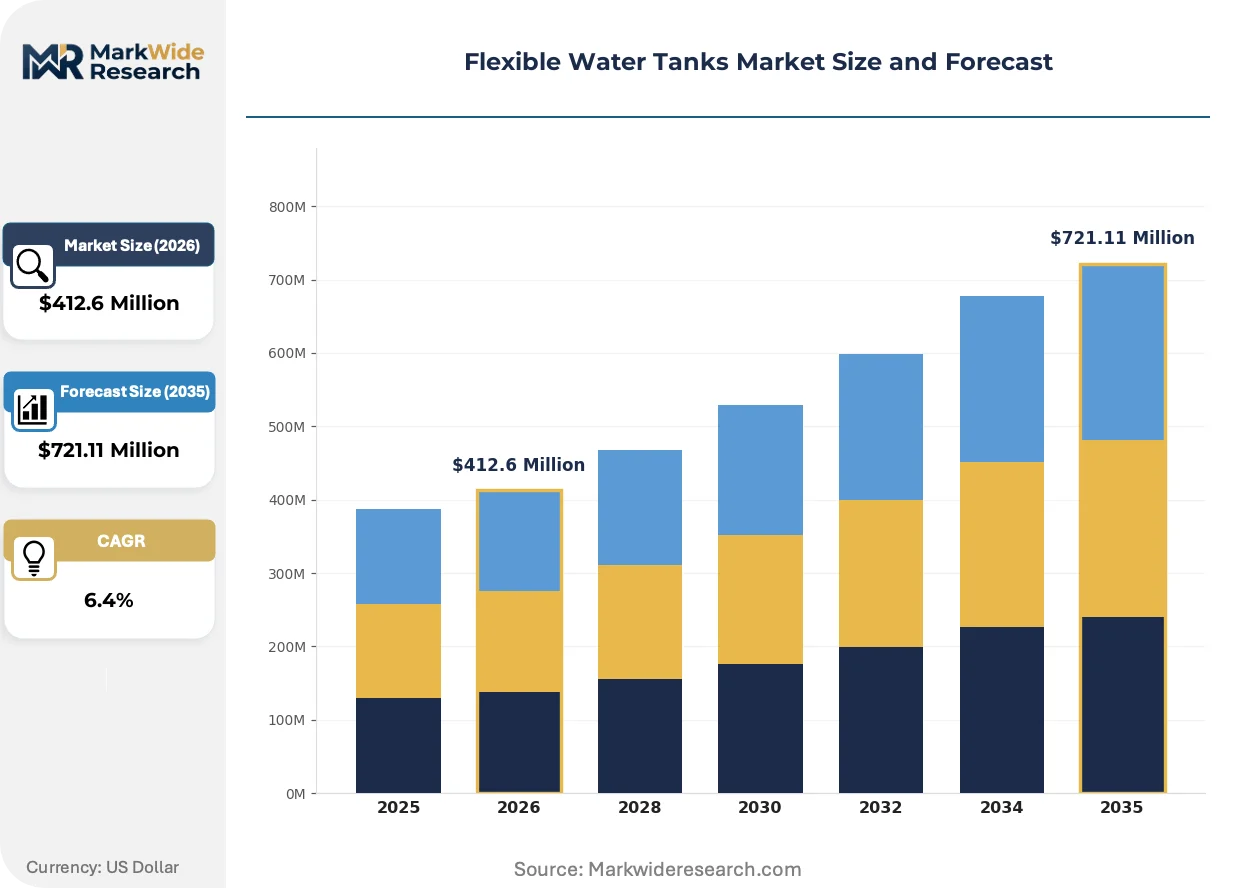
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $721.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tanks, Collapsible Tanks, Pillow Tanks, Modular Tanks Application: Agricultural Use, Industrial Storage, Emergency Response, Recreational Activities End User: Municipalities, Construction Sites, Camps, Disaster Relief Organizations Material: Polyethylene, PVC, Reinforced Fabric, Rubber |
| Companies Covered | Xylem Inc., Plastimo, Layfield Group Ltd., FLEXSOL, Gundle Environmental, Polyfabrics, Labaronne-Citaf, Emiliana Serbatoi, Pronal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Water Tanks Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are restructuring how fabricators compete on certification depth rather than unit economics alone.
Thermoplastic polyurethane (TPU) liner laminates are decomposing the historical PVC-polyester dominance in potable-water applications. Agricultural cooperatives in Spain and California are specifying TPU for its enhanced puncture resistance and reduced plasticizer migration. The technology is decomposing price-based competition into certification-tier segmentation where food-grade material traceability commands procurement preference.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin (HFO) blowing-agent adoption in insulated tank jacketing. Fabricators serving Nordic district-heating buffer storage must reformulate thermal barriers or forfeit public-utility contracts. Cold-climate deployments in Finland and Norway are driving first-mover advantage for HFO-compliant suppliers.
Digital twin integration is compressing engineering-validation cycles for custom tank geometries. Mining operators in Western Australia now require finite-element stress modeling before field deployment, displacing empirical sizing rules. This specification shift favors fabricators with in-house simulation capability over catalog-based competitors.
Flexible Water Tanks Market Segmentation
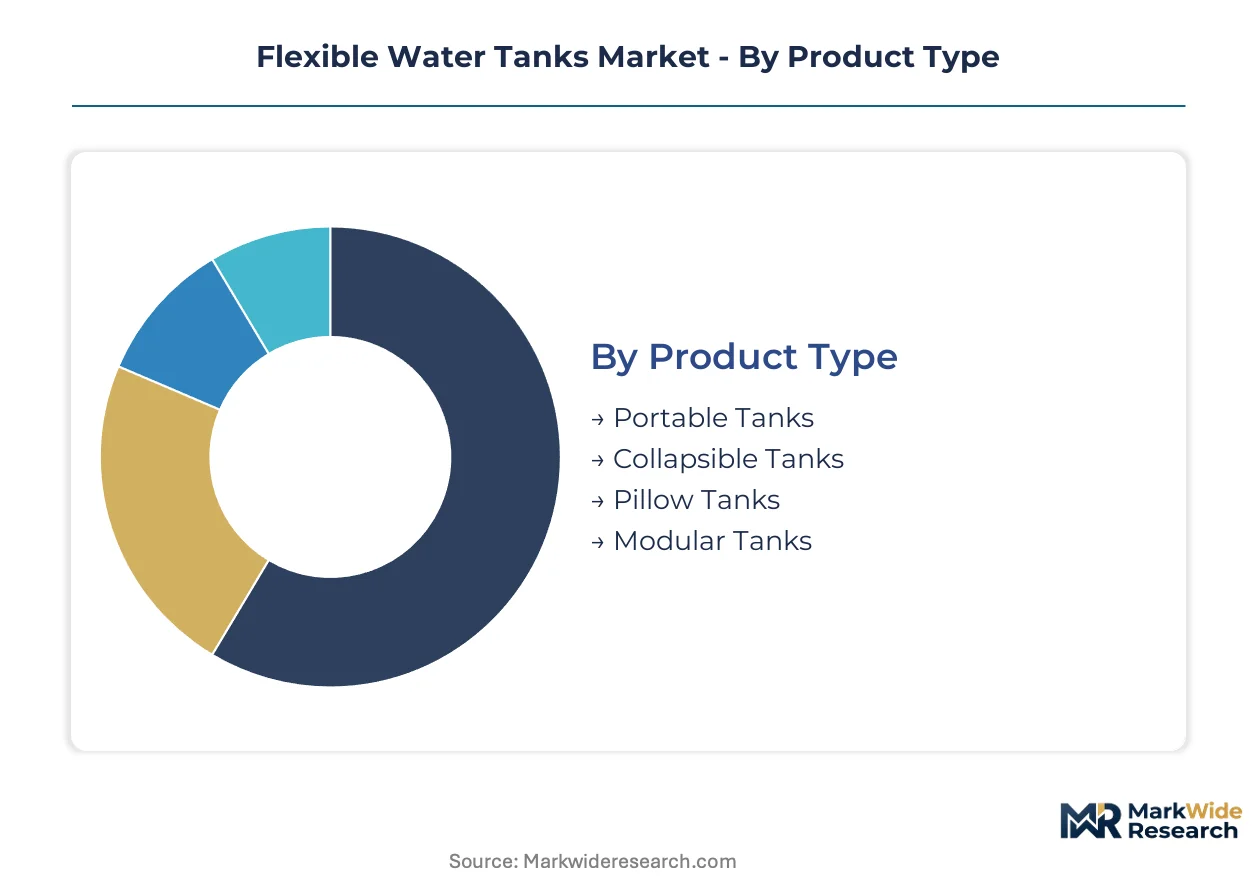
Segmentation in flexible water storage reveals divergent engineering requirements across deployment contexts. Product architecture, liner chemistry, and end-use durability standards fragment procurement specifications. Manufacturers must align fabrication capabilities with distinct compliance regimes rather than pursuing universal designs.
Product Type:
Domestic fabrication concentrates on pillow and collapsible formats for rapid-deployment contracts, while modular systems increasingly serve export markets requiring permanent infrastructure alternatives.
- Portable Tanks:Compact, frame-supported reservoirs designed for manual transport and quick assembly without heavy equipment. Australian mining contractors specify these for exploration camps requiring seasonal relocation across the Pilbara and Queensland coal basins.
- Collapsible Tanks:Fabric-reinforced reservoirs that fold flat for transport and deploy without rigid substructures. Spanish agricultural cooperatives dominate procurement for drip-irrigation networks replacing concrete reservoirs in Andalusia and Murcia.
- Pillow Tanks:Low-profile, flexible reservoirs that maximize stability on uneven terrain through distributed weight.
- Modular Tanks:Interconnectable panel systems enabling million-liter capacities with standardized expansion protocols.
Collapsible tanks command the established base. The steepest expansion runs through modular configurations.
Application:
Cost tiering separates specification-grade potable systems from utility-grade agricultural and emergency deployments, with certification burden driving margin stratification.
- Agricultural Use:Seasonal irrigation storage replacing fixed concrete infrastructure in water-stressed growing regions. California Central Valley operators and Spanish horticultural zones lead procurement volume as groundwater regulations tighten.
- Industrial Storage:Process water and containment for mining, energy, and manufacturing sites requiring chemical-resistant liners. Chilean copper operations and Western Australian iron ore projects specify reinforced fabrics for acid mine drainage protocols.
- Emergency Response:Rapid-deployment reserves for wildfire suppression, drought relief, and humanitarian logistics.
- Recreational Activities:Temporary water supply for outdoor events, film productions, and remote tourism infrastructure.
Emergency response commands the established base. The steepest expansion runs through agricultural use.
End User:
Customer type determines procurement channel structure, with municipal tenders demanding certification depth that disqualifies catalog-based suppliers.
- Municipalities:Urban water departments specifying potable-grade liners for distribution system redundancy. German and French utilities enforce EU Drinking Water Directive compliance through multi-year framework agreements.
- Construction Sites:Temporary dust suppression and concrete curing water for infrastructure projects. UAE and Saudi Arabia megaproject contractors drive volume through rapid-deployment requirements.
- Camps:Military, mining, and exploration facilities requiring relocatable storage without foundation preparation.
- Disaster Relief Organizations:Humanitarian agencies stockpiling rapid-response water reserves for drought and seismic events.
Construction sites command the established base. The steepest expansion runs through municipalities.
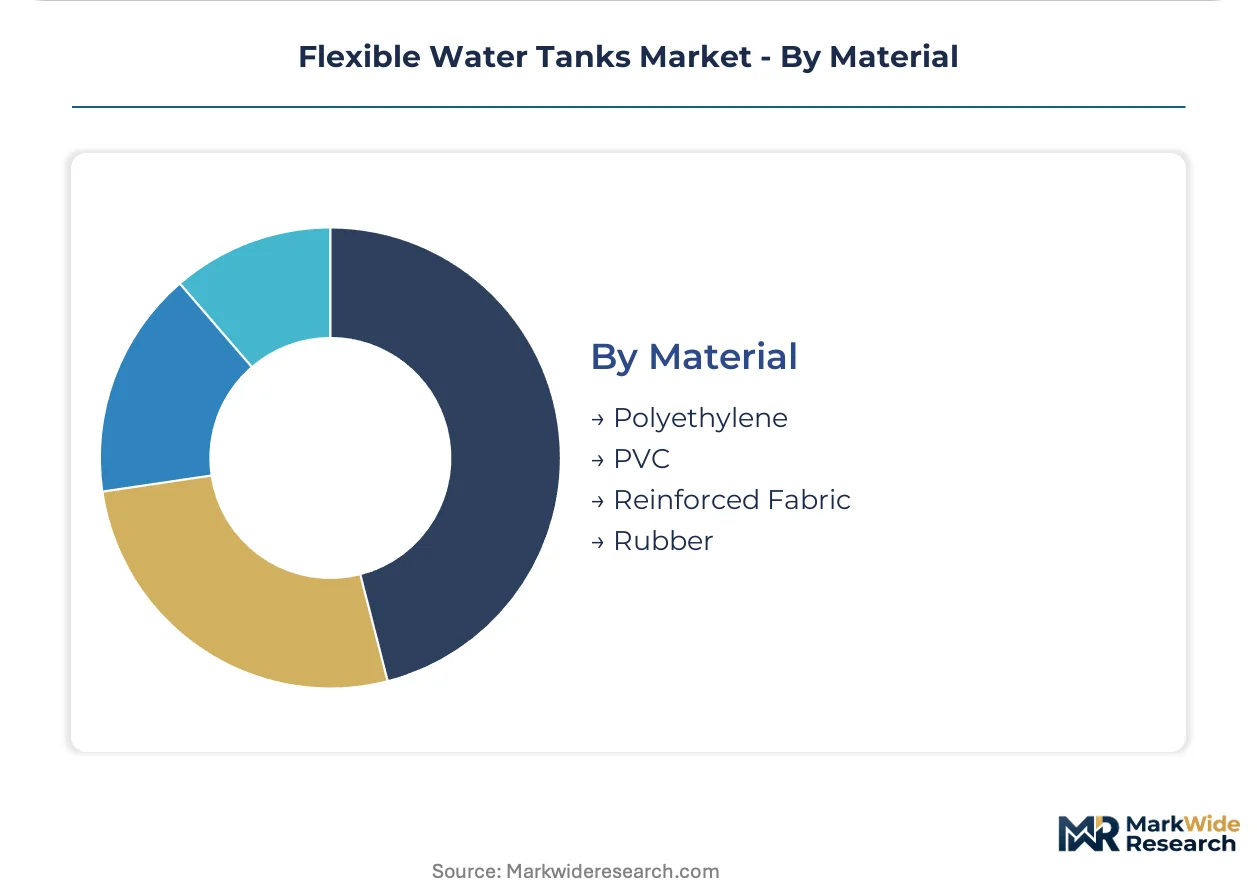
Material:
Supply concentration in petrochemical feedstocks exposes fabricators to margin volatility, with bio-based alternatives gaining procurement preference under circularity mandates.
- Polyethylene:Rotationally molded or welded sheet construction offering chemical inertness and weld inspection transparency. Australian TGA potable-water certification drives specification in municipal and healthcare applications.
- PVC:Coated polyester laminates with established supply chains and cost efficiency, now facing substitution pressure from plasticizer migration concerns under REACH frameworks.
- Reinforced Fabric:High-tenacity polyester or aramid scrims with elastomeric coatings for puncture resistance and flex fatigue durability.
- Rubber:EPDM and nitrile formulations for extreme temperature cycling and hydrocarbon exposure.
PVC commands the established base. The steepest expansion runs through reinforced fabric.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor Australian and European fabricators supplying remote mining and agricultural markets, while North American producers serve domestic irrigation and emergency-response demand through localized manufacturing.
Australia
Pilbara iron ore operators and Queensland coal contractors drive collapsible tank procurement for seasonal camp relocations. The National Health and Medical Research Council potable-water guidelines enforce TGA-level certification for municipal and healthcare applications. Perth-based fabricators concentrate production for export to Southeast Asian mining operations.
United States
California Central Valley agricultural cooperatives replace concrete reservoirs with collapsible storage under tightening groundwater regulations. EPA potable-water contact material standards compel liner certification for municipal procurement channels. Texas and Arizona desert agriculture clusters expand drip-irrigation buffer storage deployments.
Germany
German municipal utilities enforce EU Drinking Water Directive compliance through multi-year framework agreements for distribution redundancy. REACH chemical safety frameworks accelerate substitution of legacy PVC formulations with bio-based alternatives. Bavarian and North Rhine-Westphalian fabricators lead insulated tank jacketing for Nordic district-heating applications.
Spain
Andalusian and Murcian horticultural zones dominate collapsible tank adoption for drip-irrigation networks replacing fixed infrastructure. Spanish agricultural cooperatives specify TPU liners for enhanced puncture resistance under EU Green Deal circularity mandates. Valencia-based manufacturers serve Mediterranean basin export demand.
Chile
Atacama copper operations require million-liter collapsible systems eliminating concrete curing delays in isolated desert sites. Chilean mining regulators enforce acid mine drainage containment protocols driving reinforced-fabric specifications. Antofagasta and Calama industrial clusters anchor South American procurement volume.
Flexible Water Tanks Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic reach, creating a tiered structure where potable-grade compliance separates premium fabricators from utility-grade competitors. The vendor base fragments across three strategic archetypes: fluid-handling conglomerates with municipal specification heritage, reinforced-fabric specialists with regional compliance anchors, and geosynthetic engineers serving mining and agricultural deployment. Dominant competitive moves include backward integration into coated-fabric manufacturing and strategic partnerships with desalination equipment suppliers.
Within the fluid-handling tier, Xylem Inc. represents the listed multinational archetype with specification heritage in municipal and industrial channels. Labaronne-Citaf and Layfield Group Ltd. exemplify regional specialists—French and Canadian fabricators respectively—whose reinforced-fabric and geosynthetic expertise anchors compliance-driven procurement in European and North American markets.
| Leading Market Players |
|---|
| Xylem Inc. |
| Plastimo |
| Layfield Group Ltd. |
| FLEXSOL |
| Gundle Environmental |
| Polyfabrics |
| Labaronne-Citaf |
| Emiliana Serbatoi |
| Pronal |
| Others |
Supply & Pricing Matrix
TPU liner substitution for legacy PVC-polyester laminates is redrawing supply geography toward German and Spanish coating specialists while compressing margin structures for uncertified Asian fabricators unable to absorb REACH compliance costs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates food-grade TPU systems with EU Drinking Water Directive certification from utility-grade PVC-polyester alternatives. Cost compression in the economy tier is intensifying because Australian and Chilean mining contractors are consolidating procurement volumes. Municipal buyers exhibit the lowest price sensitivity due to multi-year framework agreements, while agricultural cooperatives drive hard volume negotiations.
Supply Chain Analysis
Inventory cycles for coated fabric rolls now stretch 14-20 weeks as REACH-compliant elastomeric compound availability tightens. Manufacturing concentrates in Germany, Spain, and Australia where TGA and EU certification infrastructure anchors production. Raw material dependencies include thermoplastic polyurethane resin, high-tenacity polyester scrim, and HFO-based thermal insulation blowing agents. Single-source vulnerability runs through Chinese TPU resin supply for European fabricators. Distribution runs through direct municipal tender channels and mining contractor framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
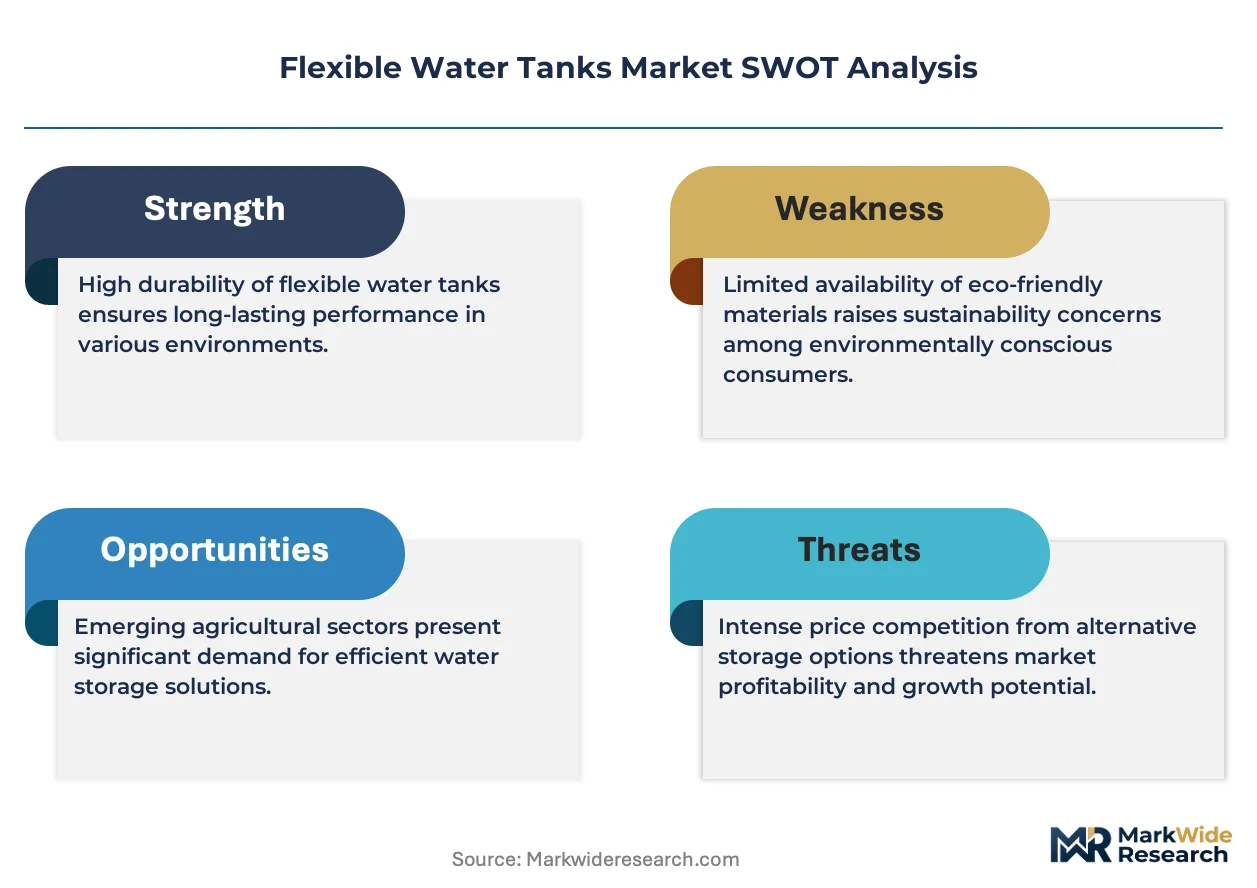
The market sits at a regulatory inflection where potable-water certification is displacing price-based procurement, creating first-mover advantage for compliant fabricators.
For Market Incumbents: Secure backward integration into coated-fabric manufacturing to capture margin from TPU liner substitution. Lock multi-year framework agreements with German and French municipal utilities before REACH circularity mandates tighten further. Defend against emerging geosynthetic specialists by accelerating TGA certification for Australian export channels. For New Entrants and Emerging Players: TGA fast-track certification for polyethylene liners opens procurement channels with Australian healthcare and municipal buyers currently underserved by European incumbents. Target Spanish agricultural cooperatives specifying TPU for drip-irrigation networks. Pursue white-label manufacturing partnerships with established coating facilities to bypass 18-24 month multi-jurisdiction launch timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized fabricators with captive certification infrastructure. Long-term viability hinges on circular material recovery capabilities under EU Green Deal mandates. Watch for Australian NHMRC-EU Drinking Water Directive reciprocity agreements as the signal for export economics normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coated-Fabric Manufacturing | Captures margin from TPU substitution while securing REACH-compliant supply. |
| Multi-Jurisdiction Certification Fast-Track | Compresses 18-24 month launch timelines for municipal procurement access. |
| Closed-Loop Liner Recycling Program | Secures preference under EU Green Deal circularity mandates. |
| Digital Twin Engineering Capability | Meets Western Australian mining finite-element modeling requirements. |
| Solar Desalination Buffer Storage Partnership | Captures emerging demand from photovoltaic-integrated reverse osmosis deployments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal procurement officers, mining camp logistics managers, agricultural cooperative technical directors, and coated-fabric plant engineers. Secondary validation drew from EPA potable-water contact material filings, EU Drinking Water Directive compliance registries, Australian TGA certification databases, and customs trade data for TPU resin and polyester scrim imports. Bottom-up unit economics triangulated against top-down market sizing across product type, application, end user, and material segmentation dimensions.
Across the analysis window, volume and value outputs reflect a structured approach modeling collapsible tank deployments, modular system expansions, and pillow tank emergency stockpiles alongside liner chemistry substitution patterns. CAGRs were derived from segment-level growth trajectory analysis. Key inputs included drip-irrigation network expansion rates in water-stressed growing regions and remote mining camp relocation frequencies.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement and continued Australian drought cycles; material deviation in petrochemical input costs or certification reciprocity agreements would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Bulk Containers Market
Containers
Cubitainer Market
Containers
Sanitary Cans Market
Containers
Insert Trays Market
Containers
Snap Secure Containers Market
Containers
Snap-Lock Container Market
Containers
Americas Container Technology Market
Containers
Hinged Lid Compostable Container Market
Containers
Car Lube Container Market
Containers
Die Cut Display Container Market
Containers
Intermediate Bulk Container Liner Market
Containers
Gable Top Container Market
Containers
Container Market
Containers
Jerry Cans Market
Containers
Straight Sided Glass Jar Market
Containers
Trigger Sprayer Market