
 Asia-Pacific Pouch Packaging Market | 2026-2036
Asia-Pacific Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pouch Packaging Market Insights
Southeast Asian flexible film producers is realigning capacity toward multilayer coextrusion lines to serve surging pouch orders from condiment and instant noodle brands. Amcor Group GmbH leverages its regional extrusion network to supply high-barrier films for retort applications across Thailand and Vietnam. Huhtamaki Oyj anchors its position through specialized printing and forming operations in China and Australia. UFlex Limited competes on cost-optimized laminate structures for domestic Indian snack brands.
Asia-Pacific pouch packaging comprises flexible, sealed containers typically constructed from oriented polypropylene, polyethylene terephthalate, or aluminum-composite laminates, formed through flat-web conversion or blow-extrusion methods, designed to protect oxygen-sensitive and moisture-critical contents during distribution and shelf storage. Stand-up pouches with spout closures command premium positioning in liquid food and personal care segments due to consumer convenience and retail shelf differentiation. Retort pouches sustain the fastest application growth as ambient meal solutions penetrate urban markets across Indonesia and the Philippines. Composites containing aluminum foil layers retain margin concentration where pharmaceutical and high-value food producers require extended shelf stability.
China's SAMR enforces GB standards for food-contact plastics and composite materials, while India's FSSAI mandates specific migration limits and labeling disclosures that filter non-compliant laminate suppliers from institutional supply chains. Japan's METI circular economy guidelines for packaging recyclability are pressuring brand owners to redesign multi-material pouches toward mono-polymer or paper-hybrid alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and material substitution timelines to align capital allocation with compliance windows.
Market Dynamics
Retort pouch adoption for ambient meal solutions is compressing traditional canning capacity across Southeast Asian food processing clusters while forcing laminate suppliers to requalify barrier specifications under tightening GB standards and FSSAI migration limits.
Growth Catalysts
- Urban convenience consumption:Working populations in Indonesia and the Philippines are pivoting toward shelf-stable prepared meals, driving institutional procurement of high-barrier retort formats.
- FSSAI packaging safety mandates:India's food regulator now enforces specific migration limits and labeling disclosures that filter non-compliant suppliers from organized retail supply chains.
- Polymer film manufacturing co-location:Maharashtra and Gujarat host converging food processing clusters and flexible film production, reducing logistics costs for domestic snack brands.
Market Restraints
- Aluminum foil supply concentration:High-value pharmaceutical and extended-shelf-life food producers depend on imported foil laminates, exposing margin pressure from currency volatility and raw material availability.
- Multi-material recyclability friction:Japan's METI circular economy guidelines pressure brand owners to redesign composite pouches, yet mono-polymer alternatives currently sacrifice barrier performance for oxygen-sensitive contents.
- Retort equipment capex intensity:Small and mid-sized converters face prohibitive capital requirements for autoclave systems and multilayer coextrusion lines needed for commercial-scale thermal processing.
Strategic Opportunities
- Stand-up spout penetration in personal care:Liquid detergent and cosmetic brands across Thailand and Vietnam are converting from rigid bottles to flexible formats for retail shelf differentiation.
- China's dual carbon goals:Beijing's emissions reduction framework is accelerating demand for lightweight, transport-efficient flexible packaging versus glass and metal alternatives.
- Pharmaceutical compliance specialization:India's CDSCO and China's NMPA are tightening primary packaging standards for moisture-critical drug products, creating premium positioning for validated barrier suppliers.
Industry Challenges
- Multilayer coextrusion technician scarcity:Southeast Asian converters report acute shortages of process engineers capable of calibrating barrier layer ratios for retort applications.
- Extended producer responsibility compliance timelines:Australia's state-level container deposit schemes and pending federal packaging reforms require rapid redesign of existing laminate structures without guaranteed recycling infrastructure.
- Legacy printing-to-digital workflow migration:Rotogravure-dependent operations in China and India face integration complexity when adopting digital printing for shorter-run customized pouch campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pouch Packaging Market |
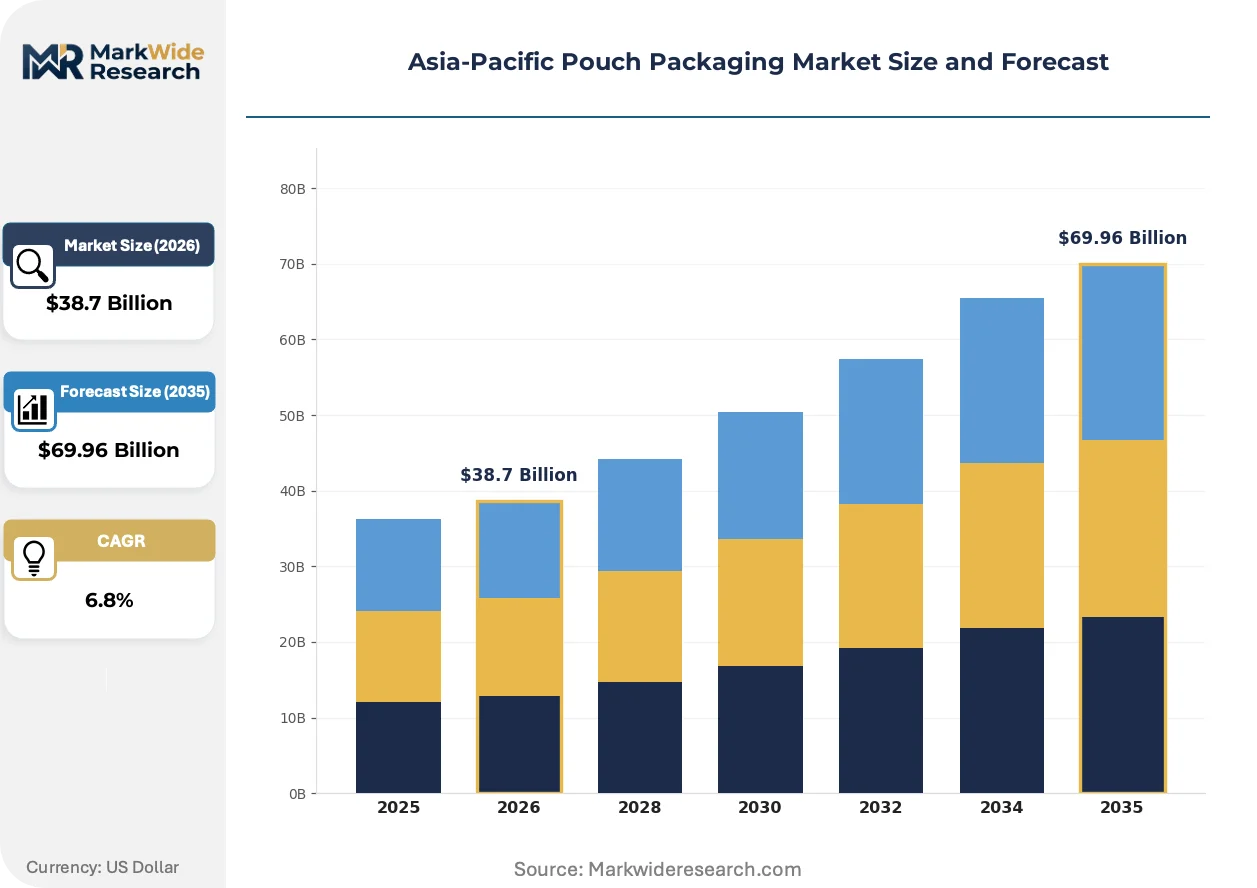
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Vacuum Pouches, Retort Pouches Material: Plastic, Aluminum Foil, Paper, Composites Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Zip Lock, Heat Seal, Spout, Adhesive |
| Companies Covered | Amcor Group GmbH, Huhtamaki Oyj, Toyo Seikan Group Holdings Ltd., Sonoco Products Company, Toppan Holdings Inc., SCG Packaging, UFlex Limited, Packman Industries, Logos Packaging Holdings Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pouch Packaging Market Trends and Innovations
Active barrier technologies and forming equipment advances are compressing traditional converting economics while regulatory pressure on recyclability forces material science reinvention across the Asia-Pacific flexible packaging value chain.
High-barrier ethylene vinyl alcohol copolymers are replacing aluminum foil in select oxygen-sensitive applications. Japanese pharmaceutical and premium food brands are piloting these transparent alternatives for microwaveable retort pouches. This substitution is integrating optical inspection systems into forming lines that previously relied on foil's electromagnetic detection properties.
China's SAMR enforcement of updated GB standards for food-contact plastics and composite materials is disqualifying legacy laminate formulations from institutional supply chains. Domestic dairy and sauce brands must now document compliance through third-party testing protocols. The regulatory compression most affects small converters in Zhejiang and Guangdong who lack in-house migration testing laboratories.
Direct-to-retail procurement models are displacing traditional distributor networks for private-label pouch programs. Australian supermarket chains and Indonesian convenience store operators now specify laminate structures and commission production through approved converter panels rather than trading houses. This channel consolidation concentrates volume with extrusion-capable suppliers in Sydney and Jakarta who can guarantee lot traceability and shorter lead times.
Asia-Pacific Pouch Packaging Market Segmentation
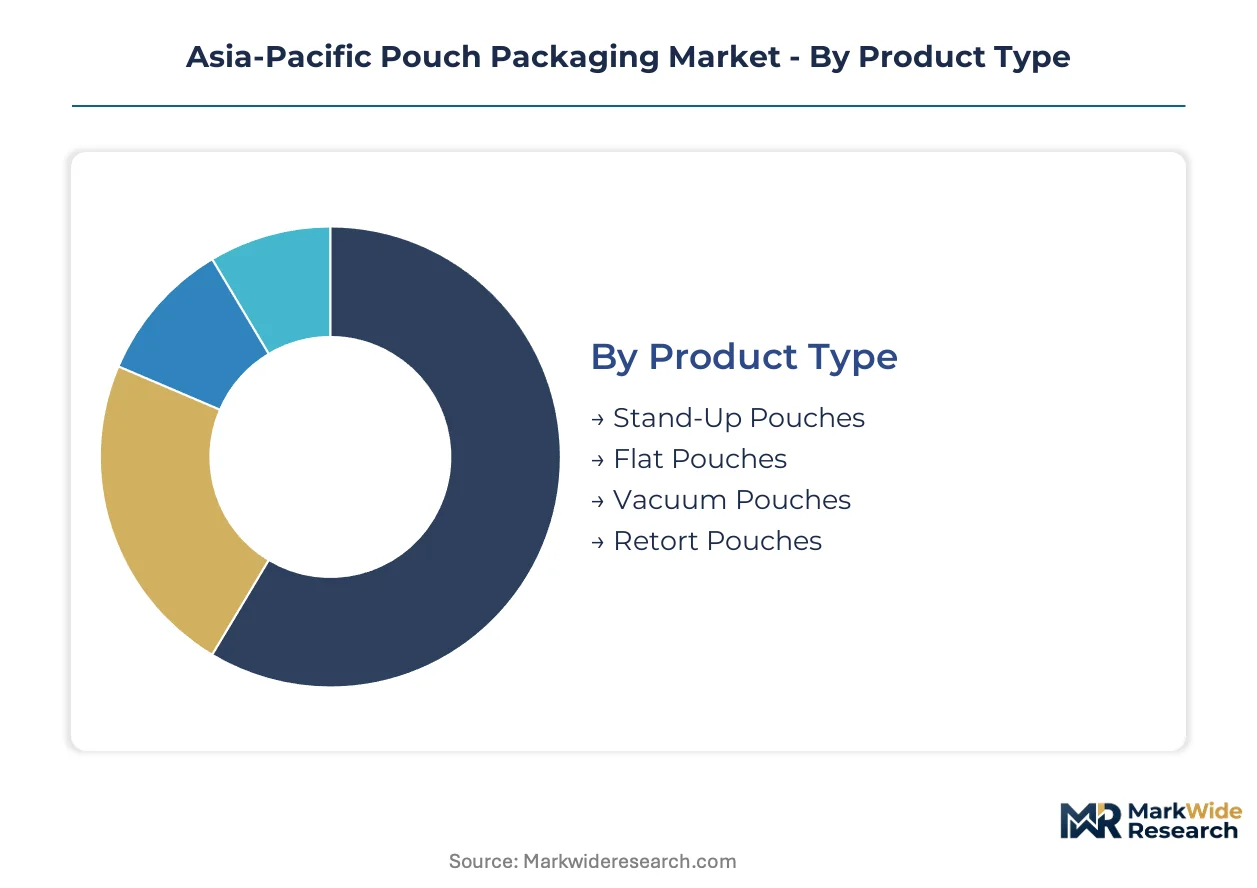
Segmentation in Asia-Pacific pouch packaging reveals how converter capacity, regulatory compliance, and end-use performance requirements stratify competitive position. Material choices and closure configurations directly determine which suppliers qualify for institutional procurement versus commodity spot markets.
Product Type:
Supply concentration among multilayer coextrusion-capable converters favors formats demanding precision barrier calibration and forming equipment.
- Stand-Up Pouches:These gusseted-bottom structures with front-facing billboard panels command premium shelf positioning. Thai and Vietnamese liquid detergent brands are converting rigid bottle lines to spout-equipped stand-up formats for retail differentiation and logistics efficiency.
- Retort Pouches:Laminate structures withstand 121°C autoclave processing for ambient meal stability. Indonesia's instant noodle and ready-meal processors are compressing traditional canning capacity, forcing laminate suppliers to requalify barrier specifications under tightening GB standards and FSSAI migration limits.
- Flat Pouches:Three-side-seal and four-side-seal configurations dominate cost-sensitive snack applications across India's Maharashtra and Gujarat processing clusters.
- Vacuum Pouches:Multi-layer barrier films with oxygen scavenging layers preserve cured meats and cheese in Australian and Japanese distribution channels.
Today's leader: Retort pouches. Tomorrow's challenger: Stand-up pouches with integrated spout systems.
Material:
Raw material sourcing geography and regulatory migration limits are bifurcating the supplier base between integrated film producers and trading-dependent converters.
- Plastic:Oriented polypropylene and polyethylene terephthalate films form the substrate backbone. China's Zhejiang and Guangdong converters face SAMR disqualification of legacy formulations lacking third-party migration documentation.
- Composites:Multi-polymer laminates with adhesive interlayers balance cost and barrier performance. These structures dominate India's domestic snack supply chains where Maharashtra-based film production co-locates with food processing.
- Aluminum Foil:Seven-micron and nine-micron gauges provide absolute oxygen and light barriers. Pharmaceutical and premium food producers depend on imported foil laminates, exposing margin pressure from currency volatility.
- Paper:Fiber-based substrates with polymer barrier coatings are gaining trial in Japan's METI-influenced circular economy redesigns, though oxygen sensitivity limits application scope.
Composites dominate volume. Plastic films are gaining regulatory pressure. Aluminum retains pharmaceutical premium positioning.
Application:
End-use performance specifications and compliance intensity create tiered procurement channels that filter supplier participation.
- Food & Beverage:Oxygen and moisture-critical contents drive barrier specification. FSSAI packaging safety mandates and China's GB standards for food-contact materials are tightening material compliance requirements across institutional supply chains.
- Pharmaceuticals:CDSCO and NMPA primary packaging standards for moisture-critical drug products create premium positioning for validated barrier suppliers with documented stability testing.
- Personal Care:Liquid detergent and cosmetic brands across Thailand and Vietnam are converting from rigid bottles to flexible formats for retail shelf differentiation and e-commerce shipping efficiency.
- Household Products:Concentrated refill pouches for surface cleaners and laundry detergents reduce plastic intensity versus primary rigid packaging.
Food & Beverage anchors volume concentration. Pharmaceuticals extract margin premium. Personal Care represents the steepest expansion trajectory for stand-up spout adoption.
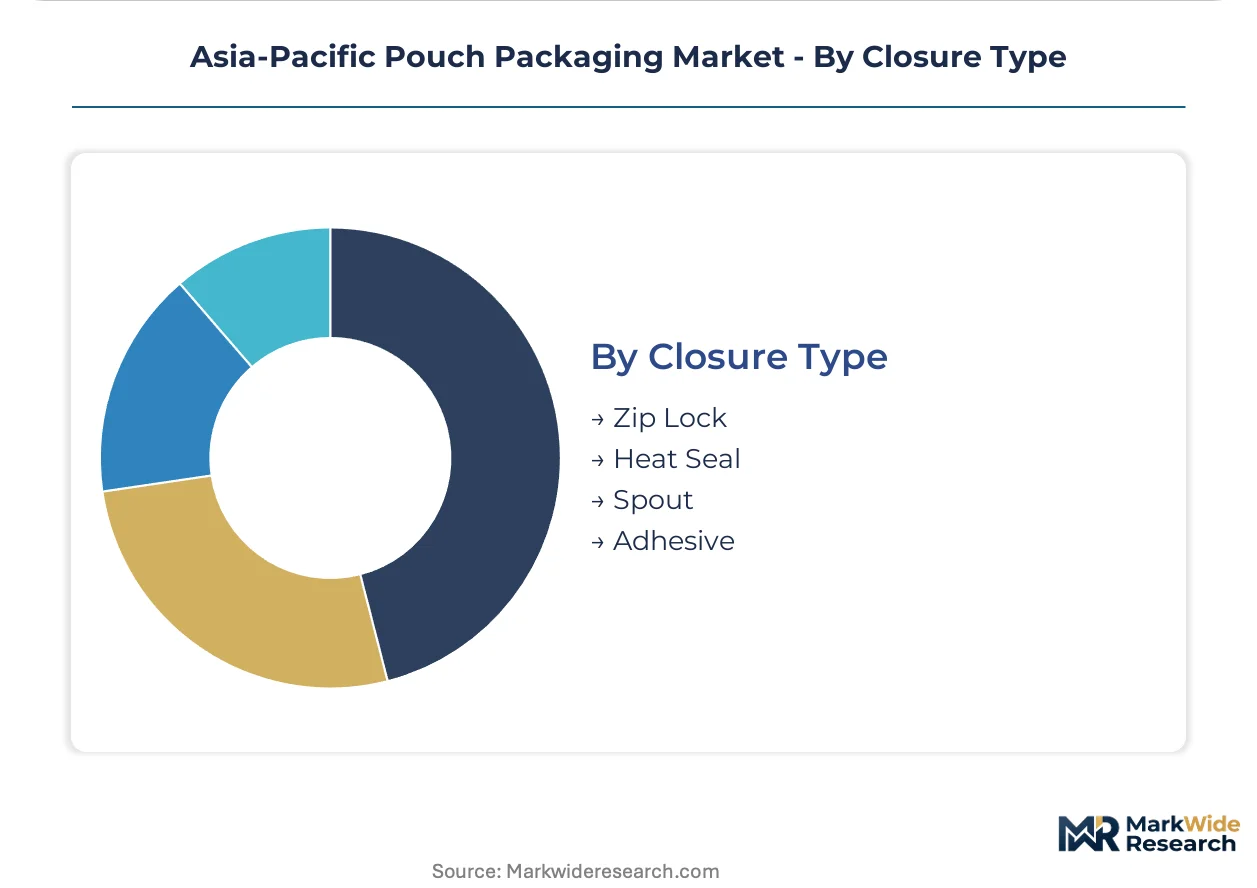
Closure Type:
Consumer convenience functionality and line speed compatibility determine converter equipment investment and brand owner specification authority.
- Spout:Injection-molded fitments with tamper-evident rings enable controlled dispensing and reclosure. Premium positioning in liquid food and personal care segments drives specification by Australian supermarket chains and Indonesian convenience store operators.
- Zip Lock:Interlocking plastic profiles provide resealability for multi-serve snacks and frozen foods. Common in Japanese and South Korean retail formats where portion control influences purchase decisions.
- Heat Seal:Thermal fusion of laminate layers offers lowest unit cost and maximum line speed. Dominates single-serve condiments and instant noodle seasoning sachets.
- Adhesive:Pressure-sensitive or cohesive closures provide limited resealability for dry goods and non-critical applications.
Heat Seal maintains volume dominance. Spout closures are climbing the fastest as liquid categories convert from rigid formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing pouch packaging capacity across Asia-Pacific as converters migrate toward jurisdictions with lower compliance costs or stronger polymer film manufacturing ecosystems. Production clusters in western India and eastern China capture volume from Southeast Asian brand owners seeking cost-optimized laminate sourcing.
China
Retort pouch demand from dairy and sauce processors in Zhejiang and Guangdong provinces is accelerating as domestic brands expand ambient meal portfolios. SAMR enforcement of updated GB standards for food-contact plastics is disqualifying legacy laminate formulations lacking third-party migration documentation. Shanghai and Shenzhen converters are investing in multilayer coextrusion lines to serve institutional procurement channels requiring documented compliance.
India
Maharashtra and Gujarat host converging food processing clusters and flexible film production, reducing logistics costs for domestic snack brands sourcing cost-optimized laminate structures. FSSAI packaging safety mandates now enforce specific migration limits and labeling disclosures that filter non-compliant suppliers from organized retail supply chains. Mumbai and Ahmedabad-based converters are consolidating volume through direct-to-brand procurement relationships.
Japan
Premium food and pharmaceutical brands in the Kanto region are piloting transparent ethylene vinyl alcohol copolymer barriers as aluminum foil replacements for microwaveable retort applications. METI circular economy guidelines for packaging recyclability are pressuring brand owners to redesign multi-material pouches toward mono-polymer or paper-hybrid alternatives. Osaka and Nagoya converters face integration complexity when adopting digital printing for shorter-run customized pouch campaigns.
Indonesia
Urban working populations in Jakarta and Surabaya are pivoting toward shelf-stable prepared meals, driving institutional procurement of high-barrier retort formats from domestic and Thai converters. The national food and drug regulator enforces progressively tighter food-contact material standards that mirror ASEAN harmonization frameworks. Batam and Surabaya processing clusters are compressing traditional canning capacity as ambient meal solutions penetrate modern retail channels.
Australia
Supermarket chains in Sydney and Melbourne are displacing traditional distributor networks through direct-to-retail procurement models for private-label pouch programs. State-level container deposit schemes and pending federal packaging reforms require rapid redesign of existing laminate structures without guaranteed recycling infrastructure. Sydney-based extrusion-capable suppliers are consolidating volume through guaranteed lot traceability and shorter lead times.
Asia-Pacific Pouch Packaging Market Competitive Landscape
Chinese and Indian producers anchor the cost-optimized laminate tier; Australian and Japanese specialists hold premium barrier positioning. The vendor base stratifies between integrated film extruders with multilayer coextrusion capability and trading-dependent converters sourcing commodity substrates. Three archetypes dominate: multinational converters with regional extrusion networks, domestic specialists serving institutional compliance requirements, and trading houses pivoting toward approved converter panels. Competitive intensity centers on capacity expansion for retort-qualified lines and strategic partnerships with brand owners seeking direct procurement relationships.
Within the multinational converter tier, Amcor Group GmbH and Huhtamaki Oyj exemplify divergent geographic anchoring strategies. Amcor leverages regional extrusion infrastructure across Thailand and Vietnam to supply high-barrier films for retort applications. Huhtamaki anchors through specialized printing and forming operations in China and Australia. Among domestic specialists, UFlex Limited occupies a position representing cost-optimized laminate structures for India's Maharashtra and Gujarat-based snack brands. These three entities collectively illustrate how compliance capability, geographic proximity to film manufacturing, and direct brand relationships stratify competitive position.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Huhtamaki Oyj |
| Toyo Seikan Group Holdings Ltd. |
| Sonoco Products Company |
| Toppan Holdings Inc. |
| SCG Packaging |
| UFlex Limited |
| Packman Industries |
| Logos Packaging Holdings Ltd. |
| Others |
Pricing and Supply Chain Analysis
Polymer resin costs originating from petrochemical complexes in eastern China and western India cascade through laminate pricing tiers, with integrated extruders capturing margin buffers that trading-dependent converters forfeit to spot-market volatility.
Pricing Analysis
Distributor margins in Southeast Asian procurement channels compress pricing for commodity snack laminates while direct-to-retail relationships in Australia and Indonesia secure volume discounts for private-label programs. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade foil laminates from domestic snack composites and bulk condiment films. Cost compression in standard-tier composites intensifies because Maharashtra-based film producers expand coextrusion capacity. Brand owners in India's organized retail channels exhibit highest price sensitivity, whereas CDSCO-validated pharmaceutical suppliers accept premium positioning for documented barrier stability.
Supply Chain Analysis
Workforce availability for multilayer coextrusion technicians concentrates in China's Zhejiang province and India's Gujarat state, where vocational pipelines feed specialized forming operations. Raw material sourcing draws from Saudi Arabian polyethylene feedstock, Thai biaxially oriented polypropylene film, and imported Japanese ethylene vinyl alcohol copolymers. Single-source vulnerability around seven-micron aluminum foil laminates exposes margin pressure from currency fluctuations. Distribution runs through approved converter panels in Sydney and Jakarta rather than traditional trading houses, consolidating volume with extrusion-capable suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific pouch packaging rests on aluminum foil substitution with transparent barrier polymers and premium-tier penetration in pharmaceutical validation protocols.
For Market Incumbents: Anticipate regulatory compression from China's SAMR migration documentation requirements and Japan's METI circular economy redesign deadlines by investing in in-house testing laboratories and mono-polymer pilot lines. Backward integration into ethylene vinyl alcohol copolymer compounding secures supply continuity for transparent retort applications. Channel control through direct procurement relationships with Australian supermarket chains defends position against trading-house displacement. For New Entrants and Emerging Players: E-commerce platform procurement for personal care refill pouches in Thailand and Vietnam offers lowest barrier-to-entry with minimal retort equipment requirements. White-space concentration sits in stand-up spout formats for liquid detergent brands converting from rigid bottles. Specialty digital printing capabilities for short-run customized campaigns address Japanese premium food segment needs without rotogravure capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where multilayer coextrusion technician scarcity constrains Southeast Asian converter expansion. Long-term viability favors integrated film extruders with validated pharmaceutical barrier protocols over trading-dependent laminate assemblers. Acquisition target archetype: domestic specialists in Maharashtra or Gujarat with FSSAI-compliant migration testing and direct brand relationships. Signal to watch: CDSCO and NMPA tightening moisture-critical drug packaging standards accelerating premium-tier supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Thai and Vietnamese converters qualify for high-barrier retort procurement from Indonesian instant noodle processors. |
| Transparent Barrier Polymer Substitution | Japanese pharmaceutical brands pilot ethylene vinyl alcohol copolymers to replace aluminum foil in microwaveable formats. |
| In-House Migration Testing Investment | Zhejiang and Guangdong converters secure SAMR compliance documentation for institutional dairy and sauce supply chains. |
| Direct-to-Retail Procurement Model | Australian supermarket chains consolidate volume with Sydney extrusion-capable suppliers guaranteeing lot traceability. |
| Digital Printing Workflow Migration | Osaka and Nagoya converters address shorter-run customized pouch demand without rotogravure integration complexity. |
Research Methodology
Bottom-up food and beverage application modeling reconciled against top-down polymer film production tracking forms the analytical core of this study. Primary interviews with multilayer coextrusion plant managers, FSSAI compliance officers at Indian snack brands, Thai liquid detergent procurement leads, and Japanese pharmaceutical packaging engineers combined with secondary validation from SAMR GB standard filings, FSSAI migration limit notifications, METI circular economy guidelines, and customs records for oriented polypropylene trade flows.
Input-output matrices mapping laminate structure specifications to end-use barrier requirements, converter equipment capabilities, and regulatory compliance tiers generated volume and value projections across the analysis window. Segmentation dimensions modeled include product format, material substrate, application sector, closure configuration, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating urban convenience consumption penetration rates and retort equipment installation trajectories.
The model assumes a particular technology adoption path; alternative pathways for mono-polymer barrier development would alter the outlook if oxygen transmission rate performance achieves pharmaceutical-grade thresholds. Forecasts reflect assumptions regarding SAMR enforcement consistency, FSSAI migration limit implementation timelines, and aluminum foil import tariff stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Kraft Paper Pouch Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Inverted Pouch Market
Pouch
Argentina Pouch Packaging Market
Pouch
Pillow Pouch Packaging Market
Pouch
Compostable Pouches Market
Pouch
UAE Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Global Boil-In Bags Market
Pouch
Kraft Pouch Market
Pouch
Foil Pouch Packaging Market
Pouch
GCC Retort Pouches Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Russia Pouch Packaging Market