
 Sterilization Roll Market | 2026-2036
Sterilization Roll Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Roll Market Analytics
The EU Green Deal's packaging waste reduction targets is decoupling sterilization roll demand from single-use plastics across European healthcare procurement. Cardinal Health leverages its distribution scale to sustain contract positions with integrated delivery networks in the United States. Ahlstrom-Munksjo anchors its competitiveness through specialty paper-based breathable substrates that compete against synthetic alternatives in steam sterilization cycles. 3M differentiates via adhesive and film technology leadership in heat-sealable sterile barrier systems.
Sterilization rolls are continuous-format flexible packaging engineered from medical-grade papers, polypropylene films, or laminated composites designed to permit sterilant penetration while maintaining microbial barrier integrity after sealing. These products typically withstand steam exposure at 121–134°C or ethylene oxide cycles, serving as critical sterile barrier systems for surgical instruments and implantable devices prior to aseptic presentation. Steam roll configurations lead volume demand due to their compatibility with the most widely deployed hospital autoclave infrastructure, while hydrogen peroxide roll formats represent the fastest-expanding segment as vaporized hydrogen peroxide sterilizers displace ethylene oxide in orthopedic and cardiovascular device manufacturing. Margin pools concentrate in laminated film constructions where multi-layer coextrusion technology creates higher switching costs for healthcare converters.
FDA enforcement of sterile barrier integrity standards shapes product qualification timelines for US market entry, while the EU Medical Device Regulation (MDR) reclassifies packaging as a critical accessory subject to notified body oversight. ISO 11607 maintains global harmonization of materials testing and seal strength validation protocols that manufacturers must satisfy across jurisdictions. Stakeholders should monitor how emerging state-level pharmaceutical packaging regulations in India and China's NMPA updates on sterile barrier labeling requirements reshape qualification burdens for exporters serving Asian manufacturing hubs.
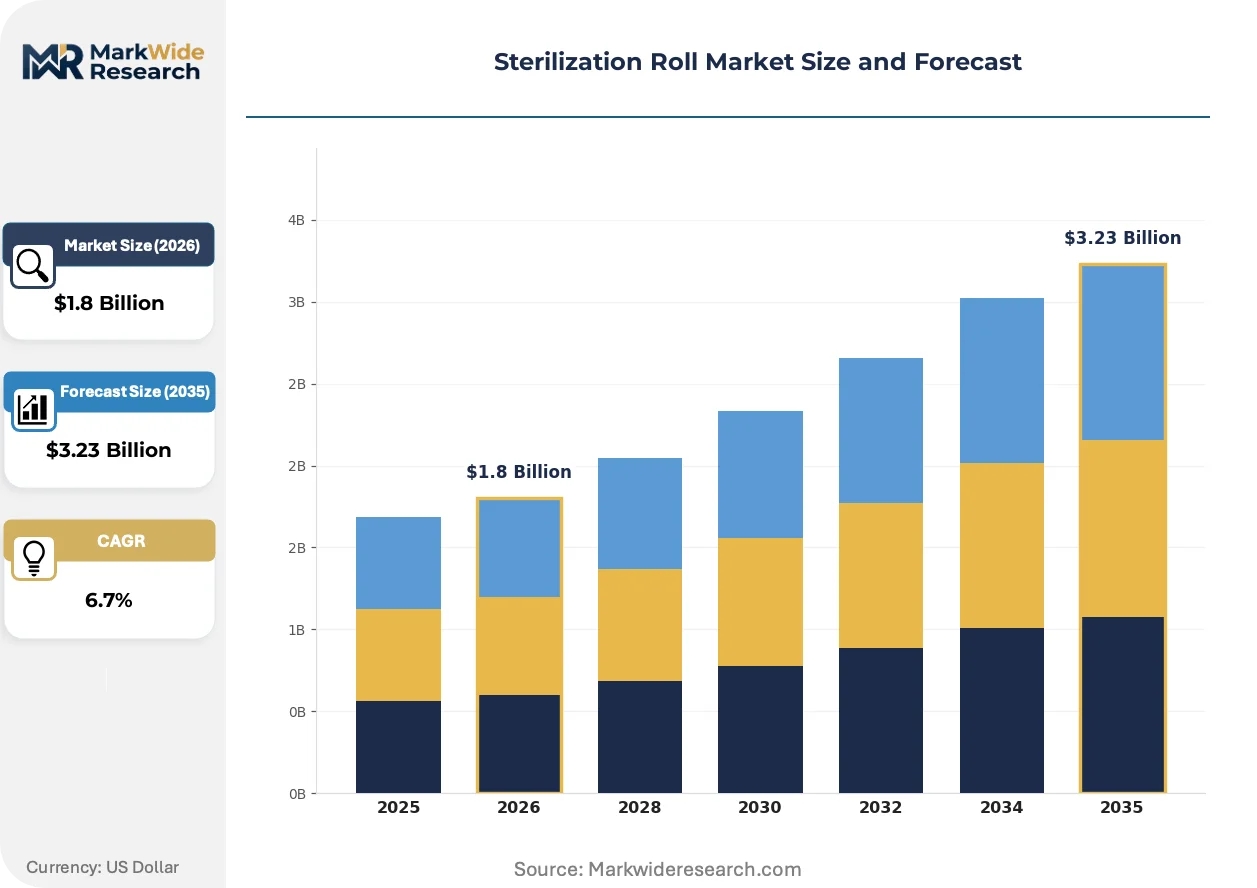
Market Dynamics
FDA sterile barrier integrity enforcement and the EU MDR reclassification of packaging as critical accessories are compressing qualification timelines while elevating technical specifications for converters serving hospital networks and device manufacturers.
Growth Catalysts
- Steam sterilization infrastructure:Hospital autoclave fleets at 121–134°C compatibility sustain baseline demand for medical-grade paper rolls across North American surgical services.
- EU Green Deal packaging targets:The decoupling mandate from single-use plastics is accelerating breathable substrate innovation in German and French central sterile supply departments.
- Vaporized hydrogen peroxide sterilizers:Orthopedic and cardiovascular device manufacturers are displacing ethylene oxide cycles, expanding specialty roll formats for low-temperature sterilization.
Market Restraints
- Medical-grade pulp volatility:Specialty paper substrate costs fluctuate with Nordic forestry supply constraints and energy-intensive bleaching processes.
- Multi-layer film concentration:Coextrusion technology for laminated sterile barriers concentrates among European and Japanese polymer converters, creating supply vulnerability.
- Ethylene oxide regulatory friction:EPA residual gas exposure limits extend validation timelines for legacy roll formats in US device manufacturing.
Strategic Opportunities
- Indian pharmaceutical packaging regulations:Emerging state-level mandates for sterile barrier labeling create first-mover qualification advantages for exporters.
- Central sterile supply consolidation:German hospital network procurement centralization favors roll suppliers with validated sterile barrier system portfolios.
- Heat-sealable adhesive convergence:Film-to-film sealing technology integration with breathable paper substrates opens hybrid format development.
Industry Challenges
- ISO 11607 validation expertise:Seal strength testing and microbial barrier assessment capabilities remain scarce among mid-tier healthcare converters.
- Legacy autoclave integration:Steam roll format compatibility with aging hospital infrastructure complicates next-generation substrate rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Roll Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Sealable Roll, Ethylene Oxide Roll, Steam Roll, Hydrogen Peroxide Roll Material: Polypropylene, Polyethylene, Paper, Laminated Film End User: Hospitals, Laboratories, Dental Clinics, Veterinary Clinics Application: Surgical Instrument, Medical Device, Laboratory Equipment, Pharmaceutical Packaging |
| Companies Covered | STERIS, Cardinal Health, Ahlstrom-Munksjo, Dynarex Corporation, Medline Industries, 3M, Amcor, Mondi Group, Certol International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Roll Market Evolving Landscape
Laminated composite engineering and sterilization modality diversification are compressing product development cycles while fragmenting technical requirements across hospital, pharmaceutical, and device manufacturing verticals.
Multi-layer coextruded films with tunable moisture vapor transmission rates are modularizing sterile barrier design. Device manufacturers in cardiovascular and orthopedic segments are adopting these formats fastest. The technology is modularizing converter R&D roadmaps around application-specific barrier properties rather than universal steam compatibility.
The EU Medical Device Regulation reclassifies sterile barrier systems as critical accessories requiring notified body oversight. This elevates documentation burdens for packaging converters serving European device manufacturers. Small and mid-tier suppliers are responding by consolidating validation capabilities or exiting the accessory category entirely.
Hospital network procurement centralization is compressing supplier rosters and extending contract durations. Integrated delivery networks in the United States are displacing decentralized purchasing by individual surgical departments. Germany exhibits the most advanced consolidation, with Rhineland and Bavarian hospital groups consolidating sterile supply procurement across fifty-plus facility networks.
Sterilization Roll Market Segmentation
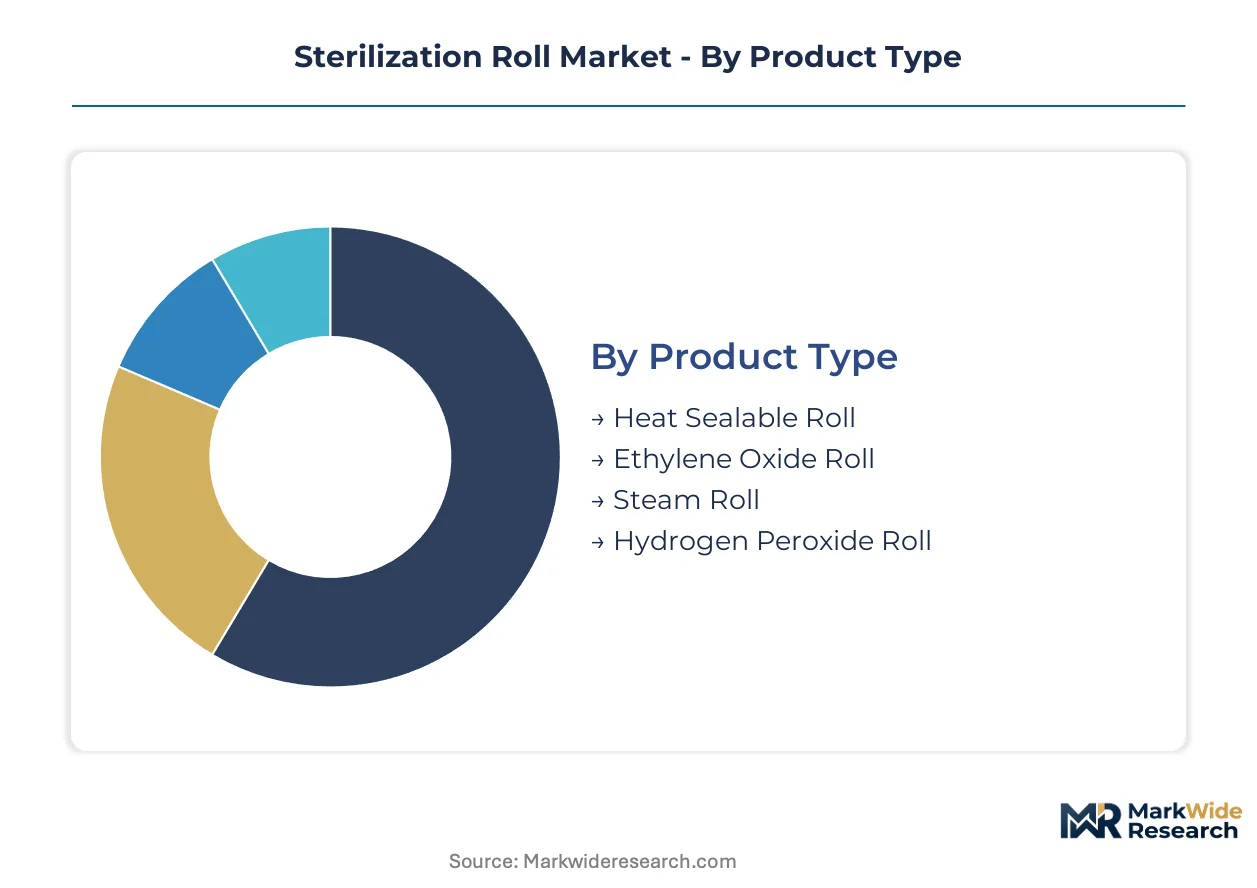
Sterilization roll segmentation reflects divergent qualification burdens across sterilization modalities and material platforms. FDA and EU MDR requirements fragment product development roadmaps, while end-use concentration in hospital networks versus device manufacturing reshapes margin structures.
Product Type:
ISO 11607 validation intensity varies sharply across sterilization modalities, with steam-compatible formats facing baseline documentation while hydrogen peroxide formats navigate emerging low-temperature protocols.
- Heat Sealable Roll:Multi-layer coextruded films with tunable adhesive layers dominate device manufacturing workflows. FDA sterile barrier integrity guidance elevates seal strength testing requirements for orthopedic and cardiovascular device packagers in the United States.
- Hydrogen Peroxide Roll:Tyvek and synthetic substrate combinations engineered for vaporized hydrogen peroxide penetration at 30-35°C. German and French central sterile supply departments are adopting these formats fastest as low-temperature sterilizers displace ethylene oxide infrastructure.
- Steam Roll:Medical-grade paper and breathable film laminates withstand 121-134°C autoclave cycles.
- Ethylene Oxide Roll:Gas-permeable constructions with residual absorption layers face EPA exposure limit compliance burdens.
Leading the category by volume: Steam Roll. Growing fastest: Hydrogen Peroxide Roll.
Material:
Raw material cost tiers stratify converter margins, with specialty paper substrates commanding premium positions against commodity polymer alternatives.
- Laminated Film:Three-to-five layer coextrusions combining polyethylene sealant webs with polypropylene structural layers and breathable microporous films. Japanese and European polymer converters concentrate supply, creating switching costs for healthcare packaging specialists.
- Paper:Medical-grade kraft and sulfate pulps with controlled porosity for steam penetration. Nordic forestry supply constraints and energy-intensive bleaching processes inject cost volatility into hospital procurement contracts.
- Polypropylene:Cast and oriented films serving as moisture barrier layers in composite constructions.
- Polyethylene:Sealant-grade resins providing heat-activation compatibility across autoclave and chemical sterilization formats.
Highest margin capture: Laminated Film. Most exposed to input cost swings: Paper.
End User:
Procurement centralization intensity distinguishes customer segments, with integrated delivery networks imposing qualification consolidation distinct from fragmented clinic purchasing.
- Hospitals:Central sterile supply departments across fifty-plus facility networks in Germany's Rhineland and Bavarian regions are consolidating vendor rosters. Reusable surgical instrument programs require validated sterile barrier systems with extended contract durations.
- Laboratories:Research and diagnostic facilities with decentralized purchasing patterns and lower volume per-site consumption.
- Dental Clinics:Small-format roll demand concentrated in autoclave-compatible paper substrates.
- Veterinary Clinics:Emerging segment with reduced regulatory documentation requirements compared to human healthcare.
Dominant volume concentration: Hospitals. Fastest contract consolidation: German hospital networks.
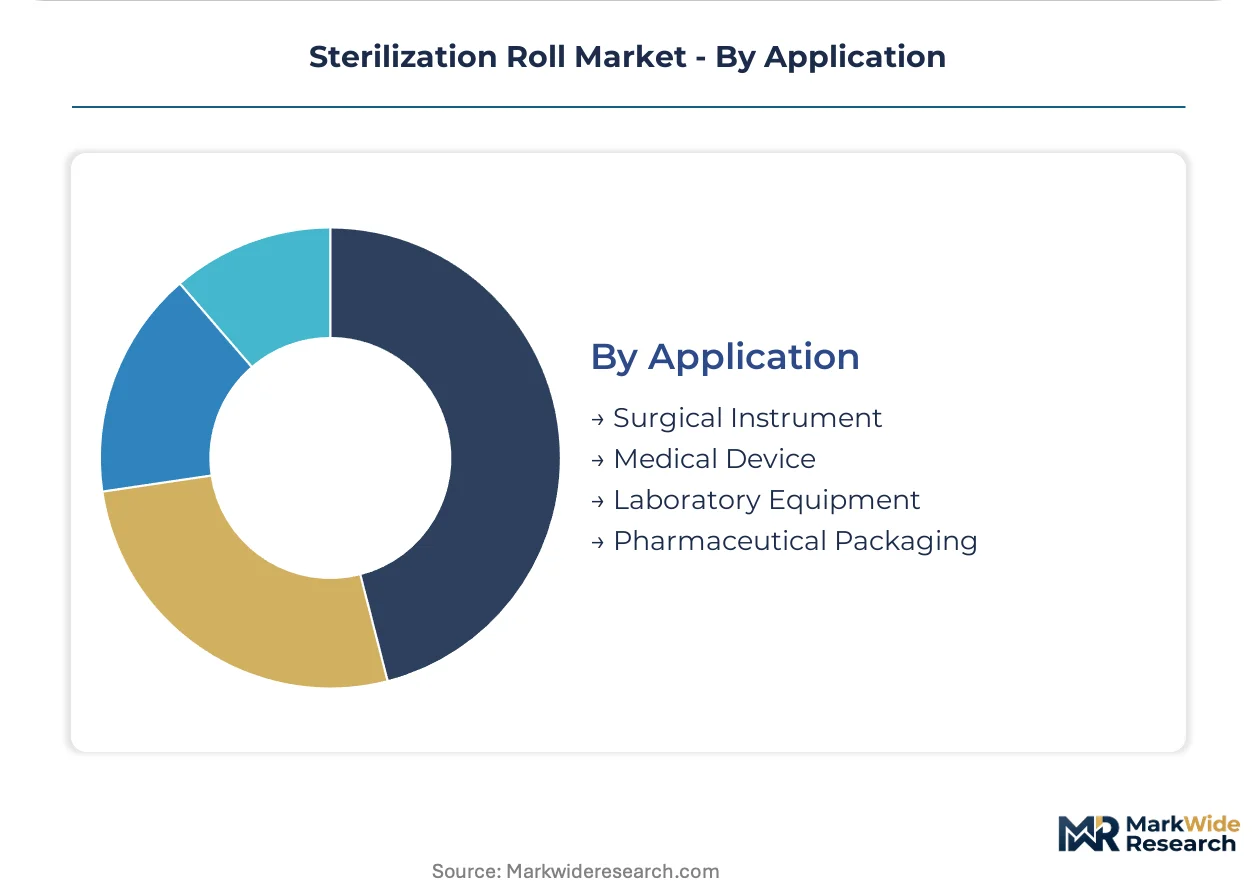
Application:
Device classification under EU MDR determines accessory documentation burdens, with implantable applications triggering notified body oversight absent from non-critical equipment packaging.
- Medical Device:Sterile barrier systems for implantable cardiovascular and orthopedic hardware face elevated seal integrity validation. EU MDR reclassification as critical accessories compresses qualification timelines for packaging converters serving European device manufacturers.
- Surgical Instrument:Reusable instrument sets for hospital operating rooms require steam-compatible formats with aseptic presentation characteristics.
- Pharmaceutical Packaging:Emerging state-level regulations in India impose sterile barrier labeling mandates for exporters.
- Laboratory Equipment:Cell culture and analytical instrument packaging with reduced sterility assurance level requirements.
Steepest regulatory escalation: Medical Device. Emerging qualification frontier: Pharmaceutical Packaging in India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Essen's Ruhr industrial corridor anchors European sterilization roll demand through consolidated hospital procurement networks serving the Rhineland region.
United States
FDA sterile barrier integrity enforcement compresses qualification timelines for converters supplying orthopedic device manufacturers. Hospital autoclave fleets in the Upper Midwest sustain baseline demand for steam-compatible formats. Cardinal Health leverages distribution scale across integrated delivery networks concentrated in Chicago and Cleveland metropolitan clusters.
Germany
Rhineland and Bavarian hospital groups consolidate sterile supply procurement across fifty-plus facility networks. EU Green Deal packaging waste reduction targets accelerate breathable substrate innovation in central sterile supply departments. Munich's medical technology corridor hosts specialty converters developing laminated film alternatives to single-use plastics.
China
NMPA updates on sterile barrier labeling requirements reshape qualification burdens for exporters serving pharmaceutical manufacturing hubs. Yangtze River Delta device manufacturers adopt vaporized hydrogen peroxide formats fastest. Shanghai's polymer converter cluster concentrates multi-layer coextrusion capacity for heat-sealable sterile barrier systems.
India
Emerging state-level pharmaceutical packaging regulations create first-mover qualification advantages for exporters targeting sterile barrier labeling mandates. Mumbai-Pune corridor device manufacturers expand low-temperature sterilization infrastructure. Gujarat's specialty paper converters navigate medical-grade pulp volatility through Nordic forestry supply contracts.
Japan
METI industrial standards harmonization with ISO 11607 protocols streamlines validation for converters serving domestic device manufacturers. Osaka-Kobe polymer engineering cluster concentrates laminated film expertise for hydrogen peroxide roll formats. Tokyo metropolitan hospital networks consolidate procurement through centralized sterile supply departments.
Sterilization Roll Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and validation capability tiers. The vendor base stratifies between multi-layer film specialists with captive coextrusion technology and paper-based substrate converters exposed to pulp cost volatility. Three archetypes dominate: integrated healthcare distributors with contract manufacturing arms, specialty material converters with ISO 11607 validation depth, and diversified packaging conglomerates with polymer science capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, with converters seeking backward integration into film extrusion or forward integration into sterile barrier system assembly.
Among US-based healthcare distributors, Cardinal Health and STERIS exemplify integrated service models spanning sterile barrier supply through central sterile supply department contracting. Finnish specialty material group Ahlstrom-Munksjo anchors the breathable substrate tier through medical-grade paper leadership competing against synthetic alternatives in steam sterilization cycles. 3M occupies a position in adhesive and film technology convergence for heat-sealable sterile barrier systems serving device manufacturers with elevated seal integrity requirements.
| Leading Market Players |
|---|
| STERIS |
| Cardinal Health |
| Ahlstrom-Munksjo |
| Dynarex Corporation |
| Medline Industries |
| 3M |
| Amcor |
| Mondi Group |
| Certol International |
| Others |
Value Network & Pricing Analysis
Nordic bleached kraft pulp futures cascade through sterilization roll manufacturing into three distinct pricing tiers, with medical-grade paper converters absorbing volatility while laminated film specialists capture margin premiums through captive coextrusion technology.
Pricing Analysis
Steam sterilization cycle throughput anchors value-based pricing for hospital central sterile supply departments, with validated sterile barrier systems commanding premiums against commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11607-certified laminates from validated paper substrates and unvalidated imports. Cost compression in economy-grade paper rolls is intensifying because Nordic forestry supply constraints and energy-intensive bleaching processes inflate specialty pulp costs. Dental clinics and veterinary practices exhibit highest price sensitivity, while orthopedic device manufacturers demonstrate lowest sensitivity due to FDA sterile barrier integrity enforcement.
Supply Chain Analysis
Medical-grade paper supply rests on Nordic forestry operations in Finland and Sweden, while multi-layer coextruded film production concentrates in Germany and Japan. Laminated film converters draw from polyethylene sealant resins, polypropylene structural webs, and breathable microporous films as primary inputs. Single-source vulnerability pervades Japanese and European polymer converter capacity for heat-sealable sterile barrier systems. Distribution runs through integrated healthcare distributors and direct hospital network contracts, with German Rhineland-Bavarian procurement consolidation favoring suppliers with validated sterile barrier system portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with multi-layer coextrusion capacity concentration among European and Japanese polymer converters propping pricing premiums for laminated film formats.
For Market Incumbents: Anchor competitiveness through backward integration into film extrusion or forward integration into sterile barrier system assembly. Defend against emerging low-temperature sterilization specialists by investing in vaporized hydrogen peroxide roll validation capabilities. Prioritize ISO 11607 seal strength testing infrastructure as a barrier to mid-tier converter expansion.
For New Entrants and Emerging Players: Begin with Indian state-level pharmaceutical packaging regulations, where emerging sterile barrier labeling mandates create first-mover qualification advantages for exporters. Target veterinary clinics as the most penetrable segment given reduced regulatory documentation requirements compared to human healthcare. Pursue heat-sealable adhesive convergence with breathable paper substrates as a hybrid format development angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty material converters with ISO 11607 validation depth in Germany, where EU MDR reclassification compresses qualification timelines and pressures mid-tier suppliers toward exit. Long-term viability centers on laminated film expertise given higher switching costs and margin capture. Watch NMPA updates on sterile barrier labeling requirements in China as an inflection indicator for Asian manufacturing hub qualification burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive multi-layer coextrusion capacity insulates margin from Japanese and European polymer converter concentration. |
| ISO 11607 Validation Infrastructure Expansion | Seal strength testing capabilities address scarcity among mid-tier healthcare converters serving FDA-enforced markets. |
| Low-Temperature Sterilization Format Development | Hydrogen peroxide roll engineering aligns with orthopedic and cardiovascular device manufacturer cycle displacement. |
| Hospital Network Direct Contracting | German Rhineland-Bavarian procurement consolidation rewards suppliers with fifty-plus facility network coverage. |
| Sustainable Substrate Innovation | Breathable paper alternatives to single-use plastics capture EU Green Deal packaging waste reduction procurement mandates. |
Research Methodology
Document review covered FDA sterile barrier integrity guidance, EU MDR accessory reclassification texts, and ISO 11607 validation protocols, complemented by interviews with central sterile supply department managers, biomedical engineers at orthopedic device manufacturers, GPO contracts managers, and polymer converter technical directors. Secondary validation drew from hospital procurement databases, customs trade data on medical-grade pulp imports, and notified body certification records. Bottom-up demand modeling across sterilization modalities triangulated against top-down healthcare expenditure allocation estimates.
Segment-level volume and value trajectories emerged from disaggregated modeling across steam, hydrogen peroxide, and ethylene oxide roll formats, with material tiers stratified by laminated film, paper, and polymer constructions. End-use segmentation distinguished hospital networks, device manufacturers, and pharmaceutical packaging verticals. CAGRs derived from fitted growth curves incorporating sterilization infrastructure deployment rates and regulatory qualification timeline compression. Forecast inputs included autoclave fleet replacement cycles in North American hospitals and vaporized hydrogen peroxide sterilizer adoption curves in German central sterile supply departments.
Underlying measurement precision varies by segment; steam roll formats carry tighter precision given mature hospital autoclave infrastructure visibility, while hydrogen peroxide roll projections reflect greater uncertainty around low-temperature sterilization displacement timelines. Forecasts incorporate assumptions regarding EU Green Deal implementation pacing and FDA enforcement continuity. A small set of triggers warrants ongoing watch: NMPA labeling requirement finalization, Nordic forestry supply disruptions, and EPA ethylene oxide residual exposure limit adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Crimped End Mailing Tubes Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
United States Single Use Packaging Market