
 Aluminum Foil Market | 2026-2036
Aluminum Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Foil Market Intelligence
Plastic film is restructuring competitive economics across barrier-packaging segments as brand owners face mounting Extended Producer Responsibility obligations. Novelis leverages closed-loop recycling to secure aerospace-grade scrap flows for downstream foil thinning. Hindalco Industries anchors South Asian supply through integrated alumina-to-foil smelter complexes in Odisha and Uttar Pradesh. Reynolds Consumer Products dominates North American retail channels through private-label and branded household foil positioning.
Aluminum foil consists of cold-rolled aluminum alloy strips typically ranging from 0.006 mm to 0.2 mm thickness, manufactured through successive rolling and annealing cycles to achieve precise gauge control and surface finish for moisture, light, and gas barrier protection. Flexible packaging and pharmaceutical foil command the deepest margin pools as pharmaceutical serialization mandates and food shelf-life extension requirements multiply specification complexity. Household foil remains the highest-volume category but faces compressing margins as private-label penetration intensifies in mass retail. Electrical foil is gaining traction from EV battery cell wrapping and capacitor separator applications where thermal stability requirements exceed polymer film limits.
FDA 21 CFR 177.1390 governs laminate structures in food-contact applications while REACH restricts certain rolling-oil chemistries and EU F-Gas Regulation phases down blowing agents used in insulation-foil bonded panels. India's BIS certification for aluminum and aluminum alloys adds compliance layers for imports targeting construction and electrical end uses. Stakeholders must monitor evolving battery-grade foil specifications from cell manufacturers and pre-position annealing capacity for ultra-thin gauges before qualification windows close.
Market Dynamics
Ultra-thin gauge development below 6 micrometers is compressing material intensity per package while multiplying annealing cycles and yield loss, forcing capital reallocation toward precision rolling assets.
Growth Catalysts
- Pharmaceutical serialization mandates:Track-and-trace regulations in the EU and India are expanding demand for premium-grade barrier foil with embedded authentication layers and tamper-evident structures.
- EV battery cell wrapping:Thermal runaway protection requirements in cylindrical and pouch cell formats are displacing polymer films with aluminum foil separators in high-nickel cathode configurations.
- Cold-chain infrastructure buildout:India's food processing sector is scaling refrigerated logistics, multiplying demand for high-barrier laminates in dairy, ready-to-eat meals, and pharmaceutical distribution.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings and alumina refining energy costs in Australia and Guinea are compressing rolling margins and hedging effectiveness.
- Scrap availability concentration:Aerospace-grade alloy scrap flows concentrate in the US Pacific Northwest and Toulouse-Blagnac corridor, creating geographic chokepoints for closed-loop recycling.
- Polymer film substitution:Metallized PET and EVOH coextrusions are capturing mid-tier barrier applications where moisture transmission rates above 0.1 g/m²/day prove acceptable.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya lack domestic foil rolling capacity, creating import substitution openings for Indian and Gulf suppliers with BIS-equivalent certification pathways.
- EU Green Deal carbon border adjustments:The Carbon Border Adjustment Mechanism will penalize high-emission primary aluminum, rewarding European rolling mills with renewable-powered smelter linkages.
- Smart packaging integration:RFID inlays and printed electronics are converging with foil substrates in pharmaceutical and luxury goods, enabling item-level authentication and cold-chain monitoring.
Industry Challenges
- Ultra-thin gauge annealing expertise:Sub-6 micrometer foil requires atmosphere-controlled continuous annealing lines with hydrogen-nitrogen mixtures, a skillset concentrated in Germany and Japan.
- Battery-grade qualification timelines:Cell manufacturers demand 18-24 month stability testing for foil used in high-voltage electrolyte environments, locking out new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Foil Market |
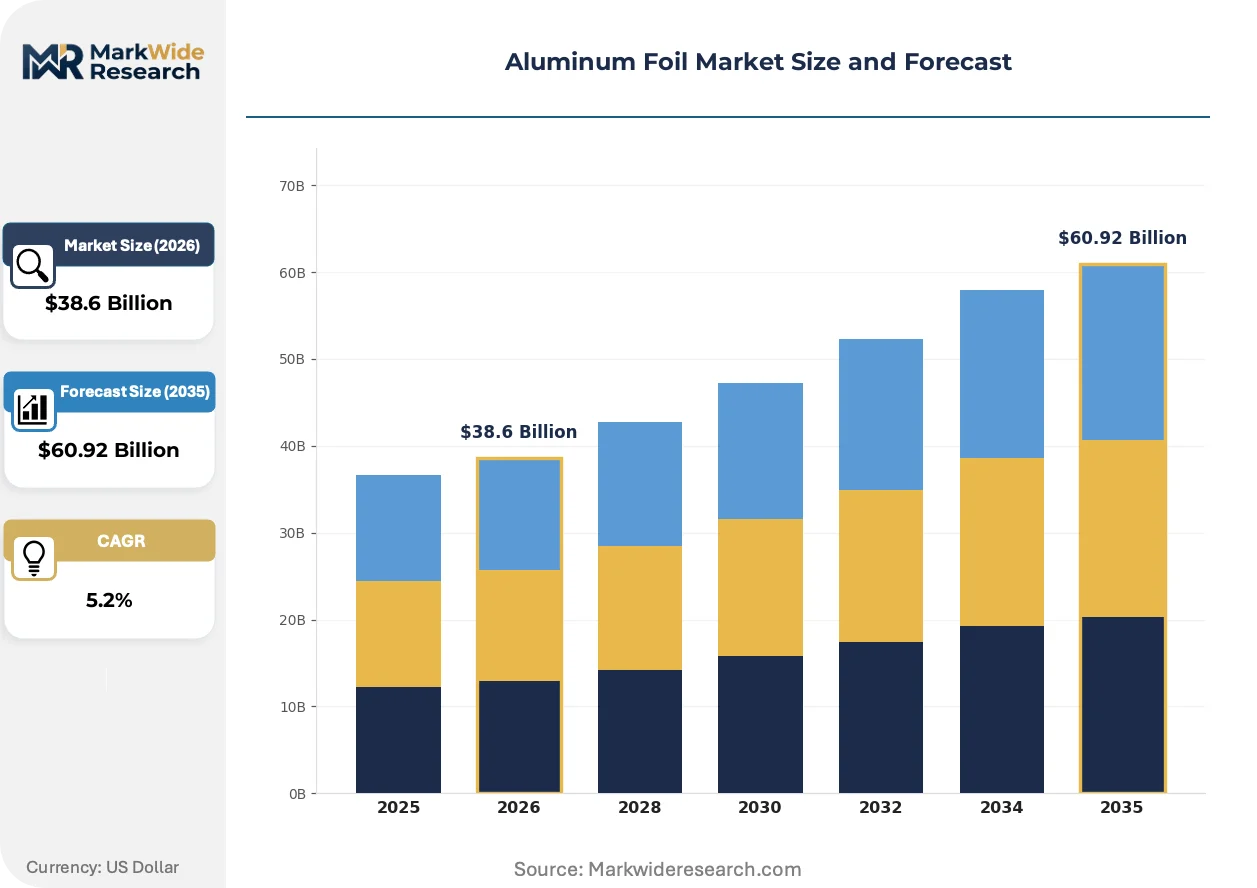
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $60.92 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Household Foil, Pharmaceutical Foil, Flexible Packaging, Insulation Foil, Labeling Foil, Electrical Foil Form: Rolls, Sheets, Laminated Foil, Embossed Foil, Plain Foil, Coated Foil Application: Food Packaging, Pharmaceutical Packaging, Cosmetics Packaging, Electrical Insulation, Construction Insulation, Decorative Uses End User: Food & Beverage Manufacturers, Pharmaceutical Companies, Construction Firms, Consumer Goods Producers, Electrical Equipment Makers, Cosmetic Brands |
| Companies Covered | Assan Aluminium, Reynolds Consumer Products, Novelis, Amcor, Henan Mingtai Aluminum Industry, Hindalco Industries, Norsk Hydro, Constellium, UACJ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Foil Market Strategic Shifts & Innovations
Rolling technology and surface engineering are advancing faster than end-use specification cycles, creating capability gaps between what mills can produce and what buyers have qualified.
Atomic layer deposition (ALD) of alumina and silica barrier coatings is converging with conventional foil substrates to achieve oxygen transmission rates below 0.001 cc/m²/day. Pharmaceutical blister pack manufacturers in Germany and Switzerland are piloting ALD-foil laminates for moisture-sensitive biologics. This convergence is compressing the addressable market for conventional thick-gauge foil in premium pharmaceutical applications.
REACH restrictions on rolling oil chemistries containing polycyclic aromatic hydrocarbons are forcing reformulation of lubricant systems across European cold rolling mills. ECHA's 2023 update to Annex XVII limits specific mineral oil saturated hydrocarbons in food-contact materials. Foil producers are responding with synthetic ester-based lubricants that require modified annealing atmospheres and extended degassing cycles.
Brand owners in North American food retail are consolidating supplier bases and demanding mill-direct relationships with documented carbon intensity scores. Mass-market retailers are displacing traditional distributor networks with approved vendor lists that require ISO 14064-verified emissions data and third-party lifecycle assessments. This pattern is most visible in private-label household foil and flexible snack packaging categories.
Aluminum Foil Market Segmentation
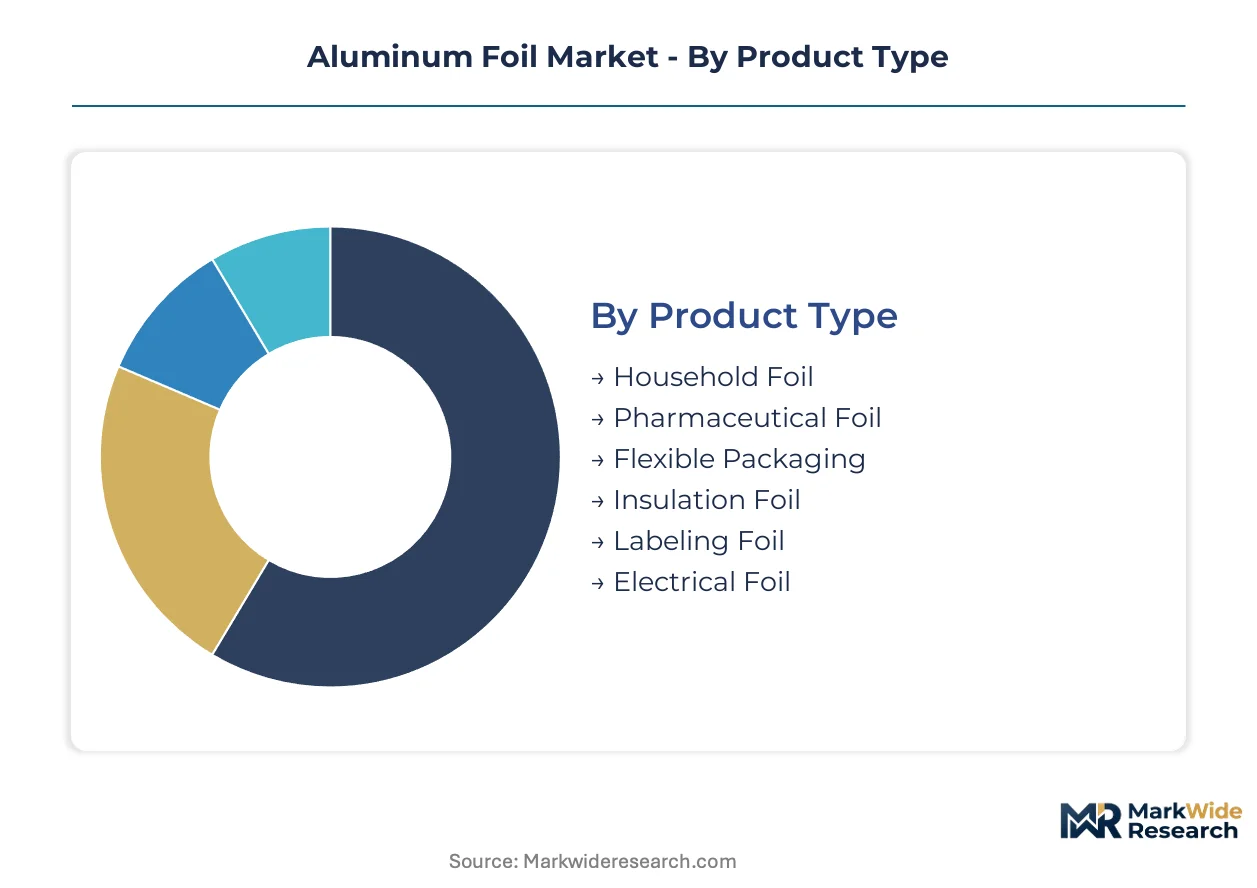
Aluminum foil demand fragments across product specifications that determine rolling mill investment priorities and margin profiles. Segmentation by product type, form, application, and end user reveals where technical differentiation commands price premiums versus commodity competition.
Product Type:
Standalone foil products dominate mass-market volumes, while embedded foil systems in multi-layer laminates capture premium pricing in regulated end uses.
- Flexible Packaging:Multi-layer laminates combining foil with polymer films achieve oxygen transmission rates below 0.01 cc/m²/day. Cold-chain expansion in India and pharmaceutical serialization mandates in the EU are concentrating specification complexity here.
- Pharmaceutical Foil:Cold-formed blister foils and push-through lidding materials require pinhole-free gauge control below 25 micrometers. Track-and-trace regulations in Germany and Switzerland are expanding demand for tamper-evident and authentication-enabled structures.
- Household Foil:Standard gauge retail rolls face margin compression from private-label penetration in US and European mass retail channels.
- Insulation Foil:Reflective barrier layers in HVAC and building envelopes require corrugation resistance and thermal stability across temperature cycling.
- Labeling Foil:Dead-soft annealed foils for pressure-sensitive adhesive applications demand precise surface energy control for printability.
- Electrical Foil:Ultra-thin gauges for EV battery cell wrapping and capacitor separators displace polymer films where thermal runaway protection exceeds 150°C stability thresholds.
Household foil leads volumes today; electrical foil is gaining share fastest.
Form:
Form selection tracks downstream processing intensity, with unconverted rolls serving toll converters and pre-converted formats capturing value-add at the mill.
- Rolls:Master coils in widths from 300mm to 1650mm feed slitting and converting operations across flexible packaging and industrial applications. Toll converters in India and Germany concentrate procurement of wide-width rolls for downstream lamination.
- Laminated Foil:Pre-bonded structures with PET, PE, or paper substrates eliminate converting steps for mid-tier food and pharmaceutical packagers.
- Sheets:Pre-cut formats for artisanal food service and small-batch pharmaceutical operations trade convenience for per-unit premium.
- Plain Foil:Unconverted, uncoated surfaces for general industrial barrier applications with minimal surface treatment requirements.
- Coated Foil:Heat-seal lacquers and primers applied in-line for direct food contact or pharmaceutical compatibility.
- Embossed Foil:Patterned surfaces for decorative packaging and improved handling characteristics in household and institutional formats.
Rolls dominate procurement tonnage; laminated foil commands the steepest value expansion trajectory.
Application:
Application segmentation maps directly to regulatory exposure, with food and pharmaceutical contact triggering the most stringent compliance burdens.
- Food Packaging:Retort pouches, lidding, and wrap formats require FDA 21 CFR 177.1390 compliance for laminate structures. Extended shelf-life demands in India's dairy sector are multiplying high-barrier specification requirements.
- Pharmaceutical Packaging:Blister packs, sachets, and cold-form foils must satisfy EMA stability guidelines and CDSCO serialization mandates. Moisture-sensitive biologics in Germany and Switzerland are piloting ALD-coated barrier enhancements.
- Electrical Insulation:Capacitor separators and cable shielding exploit aluminum's thermal conductivity and electromagnetic interference attenuation.
- Construction Insulation:Reflective radiant barriers and HVAC duct lining leverage foil's low emissivity in energy-efficient building envelopes.
- Cosmetics Packaging:Premium tube laminates and sachet structures for active-ingredient protection in skincare formulations.
- Decorative Uses:Gift wrap, Christmas ornaments, and architectural finishes exploit surface reflectivity and formability.
Food packaging anchors current volume; pharmaceutical packaging shows the most rapid specification upgrading.
End User:
End-user concentration determines contract structure, with multinational food and pharma manufacturers consolidating supplier bases and demanding mill-direct relationships.
- Food & Beverage Manufacturers:Multinational snack, dairy, and ready-meal producers specify high-barrier laminates with documented carbon intensity scores. Mass-market retailers in the US are displacing traditional distributor networks with approved vendor lists requiring ISO 14064 verification.
- Pharmaceutical Companies:Serialization mandates from EMA and CDSCO are expanding demand for premium-grade foil with embedded authentication layers. Cell manufacturers demand 18-24 month stability testing for battery-grade foil qualification.
- Electrical Equipment Makers:EV battery producers and capacitor manufacturers drive ultra-thin gauge development below 6 micrometers.
- Construction Firms:Energy-efficient building codes in the EU and India are expanding reflective insulation specification.
- Consumer Goods Producers:Household product and personal care brands source converted foil formats through packaging distributors.
- Cosmetic Brands:Premium skincare and fragrance houses specify decorative and barrier-enhanced foil for brand differentiation.
Food and beverage manufacturers represent the largest procurement base; pharmaceutical companies are driving the fastest specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Odisha-Uttar Pradesh smelter corridor anchors Indian aluminum foil capacity expansion as domestic pharma and food processing sectors scale cold-chain infrastructure. Regional demand patterns diverge sharply between mature markets facing carbon compliance costs and emerging economies building first-generation rolling capacity.
United States
Mass-market retailers in the US are consolidating household foil procurement through approved vendor lists requiring ISO 14064-verified emissions documentation. FDA 21 CFR 177.1390 compliance costs are rising for laminate structures in food-contact applications. The Pacific Northwest concentrates aerospace-grade scrap flows that feed closed-loop recycling operations for downstream gauge thinning.
Germany
Pharmaceutical blister pack manufacturers in Germany are piloting atomic layer deposition-coated foil laminates for moisture-sensitive biologics. REACH restrictions on rolling oil chemistries containing polycyclic aromatic hydrocarbons are forcing synthetic ester-based lubricant reformulations across cold rolling mills. The Rhine-Ruhr industrial cluster hosts atmosphere-controlled continuous annealing lines with hydrogen-nitrogen mixtures for sub-6 micrometer foil production.
India
Cold-chain infrastructure buildout in India's food processing sector is multiplying demand for high-barrier laminates in dairy and ready-to-eat meal distribution. CDSCO serialization mandates are expanding premium-grade foil demand with embedded authentication layers. Hindalco Industries anchors South Asian supply through integrated alumina-to-foil smelter complexes in Odisha and Uttar Pradesh.
Switzerland
Pharmaceutical foil specifications in Switzerland are upgrading fastest among European markets as track-and-trace regulations tighten. Swissmedic stability guidelines for moisture-sensitive biologics are accelerating ALD-coated barrier adoption. The Basel-Zurich corridor concentrates pilot production for tamper-evident and authentication-enabled foil structures.
China
Henan Province-based rolling mills are scaling output for flexible packaging and electrical foil segments serving domestic EV battery cell manufacturers. GB standards for aluminum and aluminum alloys are converging with international certification pathways to support export qualification. The Yangtze River Delta hosts toll converting operations that laminate foil with PET and PE substrates for mid-tier food packagers.
Aluminum Foil Market Key Industry Players
Global majors compete with regional champions across integrated smelter-to-foil operations versus toll-converter dependent models. The vendor base stratifies into three tiers: multinational aluminum conglomerates with captive primary metal supply, mid-scale regional rollers with backward integration into alumina refining, and specialist converters without rolling assets. Archetypes include carbon-accounting leaders leveraging renewable-powered smelter linkages, gauge-thinning specialists controlling sub-6 micrometer annealing expertise, and retail-channel dominants with private-label household foil positioning. Dominant competitive moves center on M&A for aerospace scrap access and capacity expansion for battery-grade foil qualification timelines.
Among the multinational conglomerates, Novelis and Norsk Hydro occupy positions as archetypes of closed-loop recycling and renewable-powered primary metal integration respectively. Hindalco Industries represents the regional integrated champion model with captive smelter complexes. Reynolds Consumer Products exemplifies retail-channel dominance through branded and private-label household foil positioning. These three anchors illustrate how competitive positioning diverges between upstream metal control, downstream channel access, and technical specification leadership in pharmaceutical and battery-grade segments.
| Leading Market Players |
|---|
| Assan Aluminium |
| Reynolds Consumer Products |
| Novelis |
| Amcor |
| Henan Mingtai Aluminum Industry |
| Hindalco Industries |
| Norsk Hydro |
| Constellium |
| UACJ Corporation |
| Others |
Cost & Logistics Intelligence
Multinational food and pharmaceutical manufacturers dominate procurement volumes and enforce contract-based long-term offtake agreements that index rolling margins to LME aluminum benchmarks. Their consolidated supplier base demands documented carbon intensity scores and ISO 14064 verification, compressing pricing power for mills without renewable-powered smelter linkages.
Pricing Analysis
Input-cost pass-through from primary aluminum and alumina refining energy expenses anchors contract negotiations, with LME contract swings transmitted directly to rolling mill quotations. Three-tier pricing structure across pharmaceutical-grade, flexible packaging-grade, and household-grade specifications reflects certification complexity and gauge precision requirements. Price differentiation hinges on REACH compliance for rolling oil chemistries and BIS certification for Indian market access. Margins are tightening in standard household foil as private-label penetration intensifies in US and European mass retail channels. Food and beverage manufacturers exhibit highest price sensitivity due to volume scale and distributor network alternatives, while pharmaceutical companies accept premium pricing for serialization-enabled authentication layers.
Supply Chain Analysis
Freight costs from bauxite extraction in Guinea and Australia to alumina refining hubs concentrate geographic risk in ocean freight lanes and port congestion points. Supply concentrates in India through Hindalco's Odisha-Uttar Pradesh smelter corridor, Germany's Rhine-Ruhr rolling cluster, and China's Henan Province mill networks. Raw material flows draw from Australian bauxite, Guinean alumina, and aerospace-grade scrap concentrated in the US Pacific Northwest and Toulouse-Blagnac corridor. Single-source vulnerability in sub-6 micrometer annealing expertise—concentrated in Germany and Japan—creates qualification bottlenecks for battery-grade foil. Distribution runs through toll converters in India and Germany for wide-width roll slitting, with pre-laminated formats bypassing converter networks for mid-tier food packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum foil has entered a late-cycle quality phase where pharmaceutical serialization mandates and EV battery thermal runaway specifications are displacing commodity-grade volumes with premium barrier and ultra-thin gauge requirements.
For Market Incumbents: To counter polymer film substitution in mid-tier barrier applications, secure aerospace-grade scrap flows through closed-loop recycling partnerships in the Pacific Northwest and Toulouse-Blagnac corridor. Expand atmosphere-controlled continuous annealing capacity for sub-6 micrometer qualification before battery manufacturer stability testing windows close. Backward integration into renewable-powered smelter linkages will defend margin position as EU Carbon Border Adjustment Mechanism penalties phase in. For New Entrants and Emerging Players: Launch via BIS-equivalent certification pathways targeting underpenetrated African import substitution in Nigeria and Kenya, where domestic rolling capacity remains absent. Focus initial capacity on laminated foil formats for mid-tier Indian food packagers scaling cold-chain infrastructure. Partner with toll converters in the Yangtze River Delta to bypass capital-intensive rolling assets and accelerate market entry. For Investors and Strategic Acquirers: Battery cell manufacturers and pharmaceutical packaging conglomerates are the most active acquirers in this space, seeking captive supply of qualified ultra-thin gauge capacity. Five-to-ten-year viability favors targets with annealing expertise for sub-6 micrometer production and established CDSCO or EMA qualification pathways. Monitor EV battery cell format shifts toward high-nickel cathode configurations as the inflection signal for separator foil demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Expansion | Novelis secures aerospace scrap flows for downstream gauge thinning in premium applications. |
| Ultra-Thin Gauge Capacity Addition | German and Japanese mills pre-position annealing lines for battery-grade qualification timelines. |
| Renewable-Powered Smelter Linkage | Norsk Hydro anchors carbon-accounting leadership for EU Green Deal compliance. |
| Smart Packaging Integration | Swiss and German manufacturers pilot RFID-enabled pharmaceutical foil for track-and-trace mandates. |
| African Market Entry Partnership | Indian suppliers leverage BIS-equivalent certification to displace import-dependent Nigerian and Kenyan demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rolling mill operations directors, pharmaceutical packaging procurement managers, EV battery cell engineering leads, and flexible packaging converters with secondary validation. Rolling oil chemistry databases, REACH Annex XVII updates, CDSCO serialization guidelines, LME aluminum contract archives, and customs trade flow records anchored supply-side modeling. Bottom-up capacity assessments across Odisha-Uttar Pradesh, Rhine-Ruhr, and Henan Province mill networks were triangulated against top-down demand projections from food processing and pharmaceutical sector forecasts.
Historical reference periods established baseline capacity utilization and margin structures across pharmaceutical-grade, flexible packaging-grade, and household-grade specifications. The projection horizon models demand evolution across product type, form, application, and end-user segments, with specific attention to battery-grade foil gauge requirements and ALD-coated barrier adoption in moisture-sensitive biologics. CAGRs were derived from rolling mill capacity expansion announcements, pharmaceutical serialization mandate implementation schedules, and EV battery cell format penetration curves.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to REACH rolling oil restrictions, abrupt LME aluminum price dislocations, and breakthrough polymer film barrier technologies exceeding current aluminum foil transmission rate thresholds. Forecasts reflect documented assumptions about qualification timeline stability and carbon border adjustment implementation pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Metal Food Cans Market
Metal Packaging
Collapsible Aluminium Tube Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Metal Cans Market
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Latin America Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Europe Metal Cans Market