
 Telemetry Pouch Market | 2026-2036
Telemetry Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Telemetry Pouch Market Analytics
The gap between premium customizable telemetry pouches and commodity standard-grade alternatives is expanding as hospital procurement teams sharpen price sensitivity while cardiac monitoring programs demand biometric-optimized fits. Medtronic leverages its vertically integrated cardiac device ecosystem to bundle pouches with telemetry hardware, sustaining higher attach rates across integrated delivery networks. Philips Healthcare competes through specialized R&D in medical-grade silicone interfaces, differentiating its offerings for extended-wear Holter monitoring applications.
A telemetry pouch is a wearable enclosure engineered to secure portable cardiac and physiological monitoring devices against patient skin or clothing, typically fabricated from medical-grade silicone or breathable polyester blends with moisture-wicking substrates to ensure signal integrity during ambulatory electrocardiography. The product category serves the primary commercial purpose of maintaining electrode-to-skin contact stability across mobile patient populations in clinical and home settings. Single-use pouches dominate hospital procurement volumes due to infection control protocols, while reusable variants command stronger margin pools in home healthcare where patients bear replacement costs directly. The telehealth application segment shows the fastest structural growth as virtual care platforms integrate continuous monitoring workflows, though emergency services still anchors absolute unit demand through ambulance-based cardiac event response.
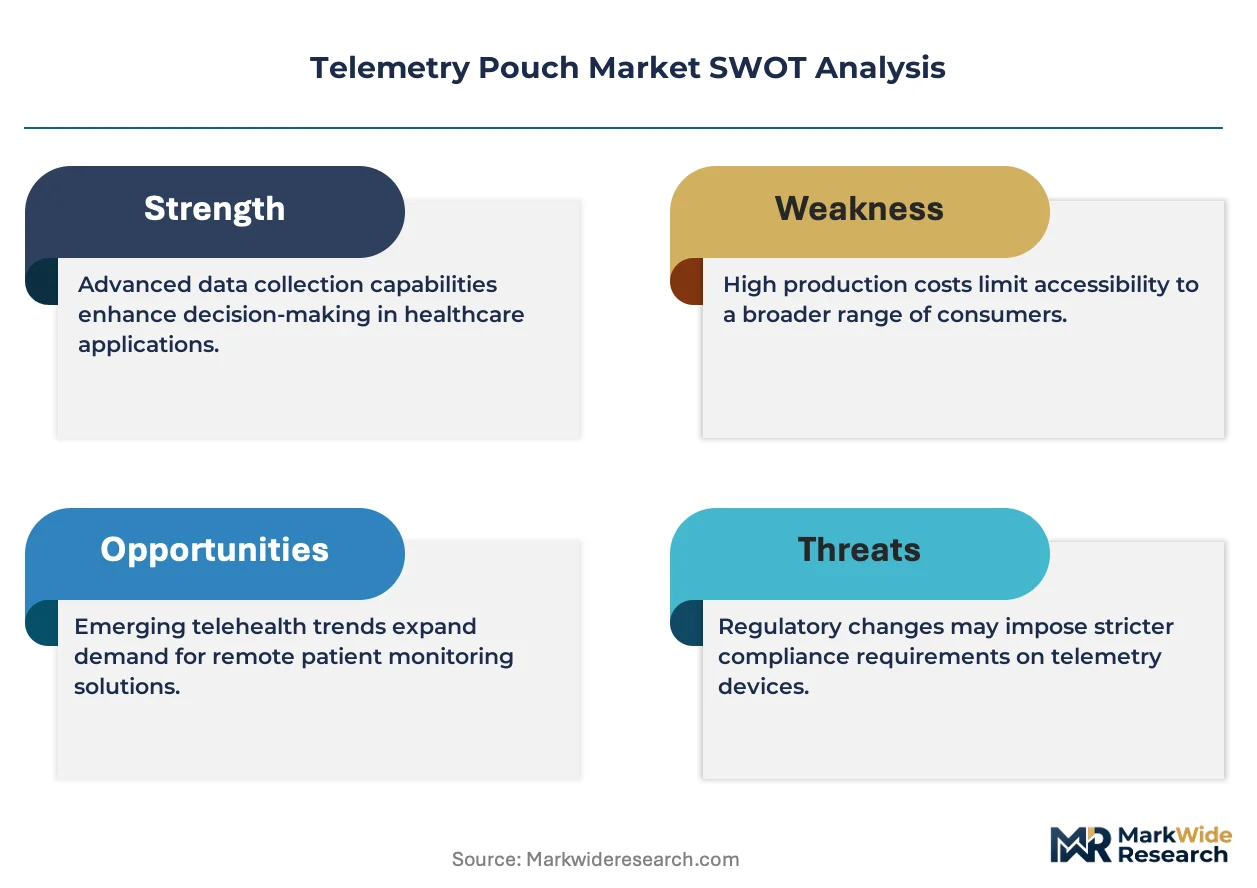
FDA digital health pre-certification programs and HIPAA data security frameworks shape product development roadmaps by mandating biocompatible materials and encrypted transmission pathways in connected pouch designs. The EU MDR and REACH chemical compliance standards govern market access for European distribution, requiring exhaustive material traceability from silicone suppliers through finished goods. Stakeholders must monitor evolving reimbursement codes for remote cardiac monitoring as payer decisions will determine whether premium pouch tiers achieve sustainable adoption against commoditized alternatives.
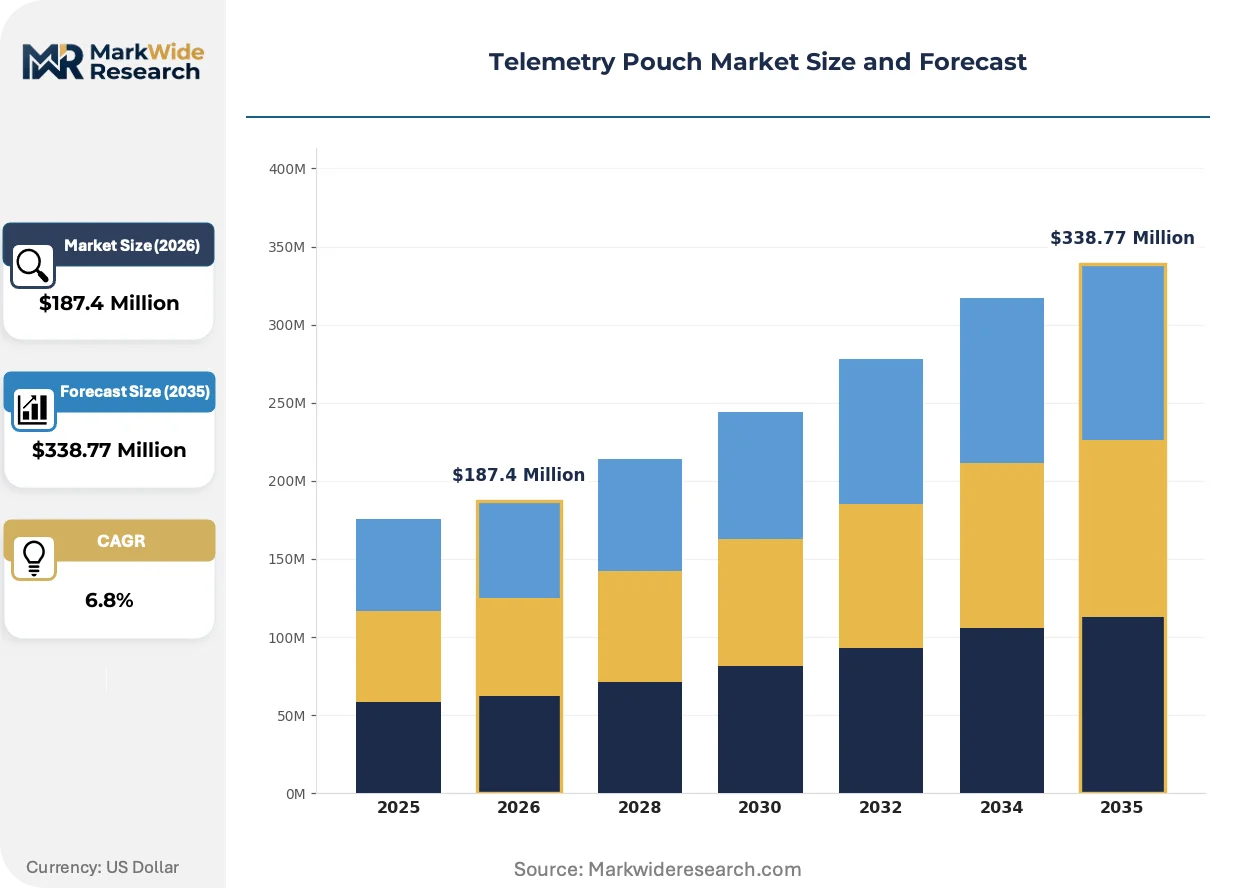
Market Dynamics
Medicare reimbursement codes for remote cardiac monitoring are compressing procurement cycles while simultaneously fragmenting supplier tiers as hospitals balance infection control mandates against total cost of ownership pressures in telemetry pouch selection.
Growth Catalysts
- FDA Digital Health Pre-Certification:Streamlined pathways for connected monitoring devices accelerate hospital adoption of encrypted telemetry pouches that integrate with cloud-based cardiac platforms.
- Home Healthcare Expansion:Ambulatory monitoring programs shift patient volumes from acute settings to residential environments, generating recurring demand for reusable pouch variants with extended-wear silicone interfaces.
- Silicone Biocompatibility Standards:ISO 10993 testing protocols elevate material specifications, forcing commoditized polyester suppliers to upgrade substrates or exit hospital procurement channels.
Market Restraints
- Medical-Grade Silicone Concentration:Supply of platinum-cured silicone concentrates among three specialty chemical manufacturers in Germany and the United States, exposing pouch fabricators to input price volatility.
- EU MDR Compliance Burden:Exhaustive material traceability requirements from REACH-registered suppliers through finished goods extend certification timelines and freeze smaller competitors from European distribution.
- Electrode Gel Substitution Risk:Dry-electrode ECG technologies eliminate conductive gel dependencies, potentially obviating moisture-wicking pouch substrates in next-generation cardiac monitors.
Strategic Opportunities
- Pediatric Telemetry Undersupply:Neonatal and adolescent cardiac monitoring applications lack biometric-optimized pouch geometries, creating white space for anatomically specialized product development.
- India PLI Medical Device Incentives:Production-linked incentive schemes for domestic manufacturing of monitoring accessories attract contract manufacturers seeking cost-competitive export bases.
- AI-Enabled Predictive Fitting:Machine learning algorithms analyzing patient anthropometric data converge with 3D-printed pouch prototyping to deliver custom-fit enclosures for bariatric and geriatric populations.
Industry Challenges
- Biomedical Textile Engineering Talent Scarcity:Cross-functional expertise spanning polymer science, dermatological safety, and RF transmission properties remains concentrated among a narrow cohort of specialized researchers.
- Legacy Hospital Inventory Systems:ERP platforms designed for pharmaceutical procurement lack SKU granularity for device accessories, forcing manual reconciliation of pouch consumption against telemetry hardware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemetry Pouch Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Customizable, Standard Application: Clinical Monitoring, Home Healthcare, Emergency Services, Telehealth Material: Polyester, Nylon, Medical-Grade Silicone, PVC End User: Hospitals, Home Care Providers, Ambulance Services, Research Institutions |
| Companies Covered | Medtronic, GE Healthcare, Philips Healthcare, Siemens Healthineers, Zoll Medical, Hill-Rom, Smiths Medical, Mindray, Draeger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemetry Pouch Market Evolving Landscape
Material science breakthroughs and reimbursement-driven care model transitions are compressing product lifecycles while elevating performance specifications for ambulatory cardiac monitoring accessories.
Antimicrobial silver-ion infused silicone substrates are overtaking standard medical-grade elastomers in premium telemetry pouch segments. Cardiac monitoring programs at integrated delivery networks adopt these interfaces to reduce dermatological adverse events during extended Holter studies. The technology is overtaking commodity alternatives by enabling 14-day wear protocols that lower per-patient pouch consumption.
REACH chemical compliance standards are tightening restrictions on plasticizer migration from PVC-based pouch components into patient contact layers. European manufacturers reformulate substrate formulations or pivot entirely to thermoplastic elastomer alternatives to maintain market access. Home healthcare distributors in Germany and France now demand full material disclosure documentation upstream of procurement decisions.
Hospital supply chain consolidation is compressing vendor panels for telemetry accessories as group purchasing organizations aggregate demand across multi-hospital systems. Independent pouch specialists face exclusion from contracts favoring bundled hardware-accessory agreements with telemetry device OEMs. The phenomenon concentrates procurement leverage most visibly in United States IDNs managing Medicare Advantage populations under risk-based contracts.
Telemetry Pouch Market Segmentation
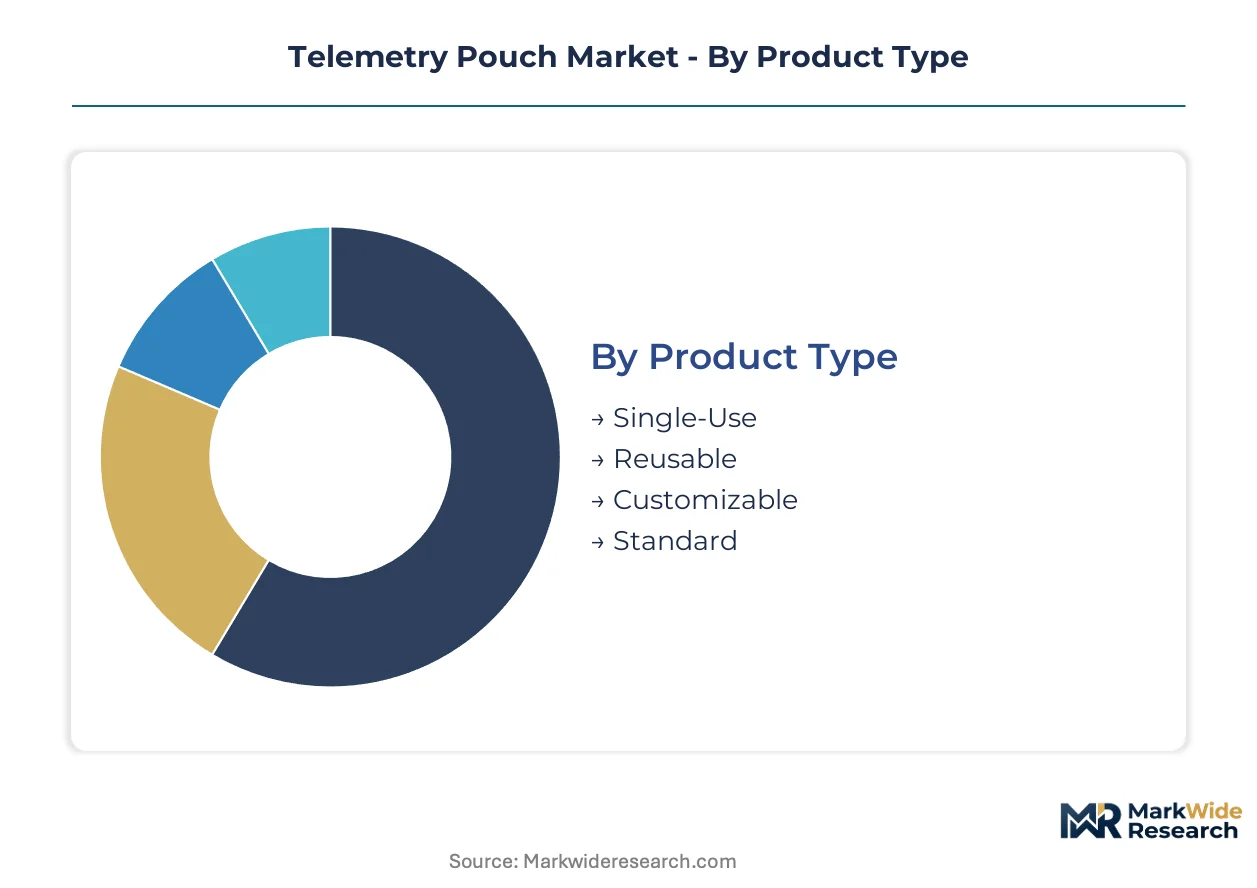
Telemetry pouch segmentation reflects divergent clinical workflows across acute and ambulatory settings. Material specifications and usage protocols vary sharply between infection-controlled hospital environments and cost-sensitive home healthcare deployments.
Product Type:
Technology and specification axes differentiate pouch architectures across disposable and durable design paradigms.
- Single-Use:Polyester-blend substrates with moisture-wicking layers dominate hospital procurement where FDA infection control protocols mandate per-patient disposal. United States acute care systems anchor absolute volume through Medicare reimbursement for inpatient cardiac monitoring.
- Reusable:Medical-grade silicone enclosures withstand 50+ sterilization cycles, concentrating demand in home healthcare where patients absorb replacement economics. Extended-wear Holter applications favor these variants for 14-day monitoring protocols.
- Customizable:Anatomically adapted geometries serve bariatric and pediatric populations with biometric-optimized electrode positioning.
- Standard:Commodity-grade universal-fit pouches compete on unit cost for high-volume emergency services deployment.
Single-Use leads on scale; Reusable leads on momentum.
Application:
Care setting transitions reshape demand concentration across institutional and residential monitoring workflows.
- Clinical Monitoring:Inpatient telemetry units at integrated delivery networks specify pouches with antimicrobial silver-ion interfaces to minimize dermatological adverse events during extended cardiac surveillance.
- Home Healthcare:Ambulatory patient populations drive recurring demand for comfortable extended-wear designs as remote monitoring programs mature under FDA digital health guidance.
- Emergency Services:Ambulance-based cardiac response teams prioritize rapid-application pouches with universal electrode compatibility for field deployment.
- Telehealth:Virtual care platforms integrating continuous monitoring represent the steepest expansion trajectory as cloud-based cardiac workflows gain payer reimbursement traction.
Clinical Monitoring leads on scale; Telehealth leads on momentum.
Material:
Substrate biocompatibility and regulatory compliance determine market access across regional chemical safety frameworks.
- Medical-Grade Silicone:Platinum-cured elastomers with ISO 10993 certification command premium positioning for extended-wear applications requiring 14-day skin contact without irritation.
- Polyester:Breathable woven substrates with moisture-wicking finishes balance cost and performance for high-turnover hospital environments.
- Nylon:Durable synthetic weaves resist mechanical stress in emergency services applications with frequent patient transfer cycles.
- PVC:REACH-regulated formulations face migration restrictions in European markets, forcing reformulation or substitution with thermoplastic elastomer alternatives.
Polyester leads on scale; Medical-Grade Silicone leads on momentum.
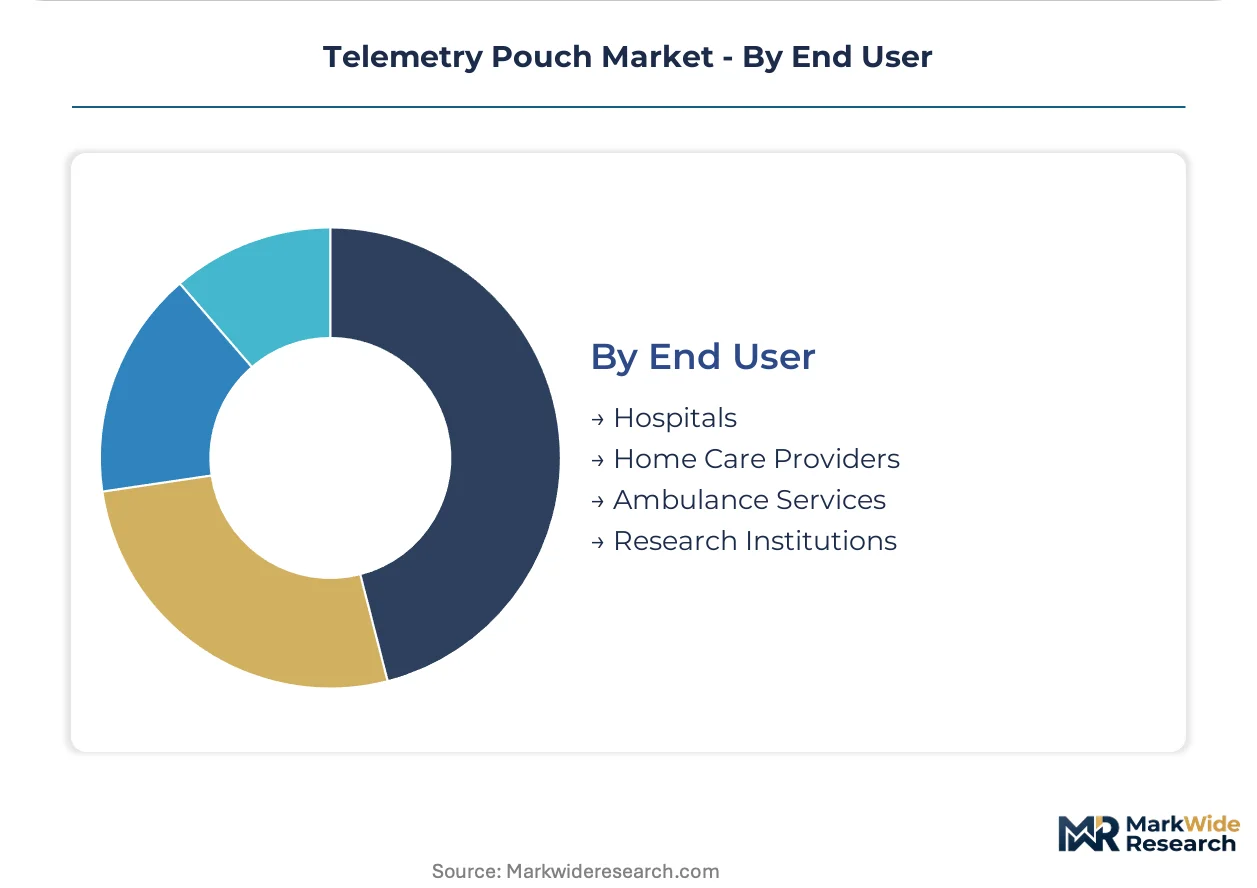
End User:
Procurement authority and reimbursement pathways fragment demand across institutional purchasing hierarchies.
- Hospitals:Group purchasing organizations aggregate demand across multi-hospital systems, favoring bundled contracts with telemetry device OEMs over independent pouch suppliers.
- Home Care Providers:Durable medical equipment distributors specify reusable silicone variants for Medicare Advantage populations under risk-based contracts.
- Ambulance Services:Municipal and private emergency medical services prioritize unit cost minimization for single-use deployment in high-turnover field settings.
- Research Institutions:Academic medical centers drive demand for customizable prototypes in clinical trial protocols evaluating novel cardiac biomarkers.
Hospitals lead on scale; Home Care Providers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes exceed German hospital demand by a factor of three, yet Indian production-linked incentive schemes are attracting contract manufacturers seeking cost-competitive export bases for reusable silicone variants.
United States
Medicare Advantage risk-based contracts and integrated delivery network consolidation drive demand for antimicrobial silver-ion interfaces. FDA digital health pre-certification programs streamline encrypted telemetry pouch adoption. Minneapolis and Boston cardiac device clusters concentrate OEM bundling agreements with major hospital systems.
Germany
REACH chemical compliance mandates and ISO 10993 biocompatibility standards elevate material specifications for platinum-cured silicone suppliers. EU MDR traceability requirements extend certification timelines for pouch fabricators. Freiburg and Munich medical technology corridors host specialty chemical manufacturers supplying concentrated elastomer inputs.
India
Domestic manufacturing of monitoring accessories accelerates under PLI medical device incentive schemes targeting export markets. CDSCO regulatory harmonization with ISO standards facilitates market access for contract manufacturers. Gujarat and Karnataka industrial zones attract foreign direct investment in silicone processing capabilities.
Japan
Aging demographics and home healthcare expansion generate recurring demand for extended-wear reusable designs. PMDA streamlined approval pathways for digital health devices integrate telemetry accessories into reimbursement frameworks. Osaka and Nagoya precision manufacturing clusters specialize in medical-grade elastomer fabrication.
United Kingdom
NHS supply chain consolidation favors bundled procurement of cardiac monitoring hardware with compatible pouch systems. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR material safety standards. Cambridge and Oxford medical research corridors drive clinical trial demand for customizable pediatric telemetry prototypes.
Telemetry Pouch Market Competitive Landscape
Top-tier vendors anchor integrated device ecosystems, while independent pouch specialists compete on material innovation and anatomical customization. The market structures around three tiers: cardiac device OEMs with captive accessory lines, medical-grade silicone fabricators with ISO-certified substrates, and commodity polyester converters serving emergency services. Strategic moves concentrate on backward integration into platinum-cured silicone supply and AI-enabled fitting algorithms for bariatric populations.
Within the integrated device tier, Medtronic and Philips Healthcare exemplify ecosystem bundling strategies that attach pouches to telemetry hardware deployments. Siemens Healthineers occupies a position bridging European regulatory expertise with Asian manufacturing scale. These three entities represent distinct competitive archetypes: vertical device-accessory integration, specialized biocompatible interface development, and transcontinental regulatory-navigated production.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Zoll Medical |
| Hill-Rom |
| Smiths Medical |
| Mindray |
| Draeger |
| Others |
Value Network & Pricing Analysis
Captive integration of platinum-cured silicone production by German and United States specialty chemical manufacturers anchors both supply security and premium pricing power for medical-grade telemetry pouch tiers. Hospital procurement teams facing Medicare reimbursement compression respond by bifurcating purchases between antimicrobial silver-ion interfaces for extended Holter studies and commodity polyester alternatives for high-turnover inpatient monitoring.
Pricing Analysis
Capacity additions in India under PLI medical device incentives are reshaping price floors for reusable silicone variants while premium antimicrobial tiers sustain margin pools through ISO 10993 certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone with silver-ion substrates from medical-grade polyester blends and commodity PVC alternatives. Cost compression in standard-grade tiers is intensifying because group purchasing organizations aggregate demand across multi-hospital systems. Emergency services buyers exhibit highest price sensitivity; cardiac monitoring programs at integrated delivery networks show lowest.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are reshaping sourcing patterns for contract manufacturers seeking cost-competitive export bases. Platinum-cured silicone concentrates draw from Germany, United States, and Japan; breathable polyester substrates source from China and Vietnam; antimicrobial silver-ion additives hinge on South Korean specialty chemical suppliers. Single-source vulnerability concentrates in platinum-cured silicone feedstock among three manufacturers. Distribution runs through group purchasing organizations for hospital systems and durable medical equipment distributors for home healthcare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telemetry pouch market functions as a stable compounder, with Medicare reimbursement expansion for remote cardiac monitoring generating predictable recurring demand across ambulatory care transitions.
For Market Incumbents: Hedge against dry-electrode ECG substitution risk by deepening R&D in biometric-optimized silicone interfaces for extended-wear applications. Secure backward integration into platinum-cured silicone supply through offtake agreements with Freiburg and Munich specialty chemical manufacturers. Channel control through bundled telemetry hardware-accessory contracts with United States integrated delivery networks reinforces switching costs.
For New Entrants and Emerging Players: Begin with pediatric telemetry geometries where anatomically specialized pouch designs face minimal incumbent competition. India's PLI manufacturing incentives offer the most penetrable geography for cost-competitive reusable silicone production. A go-to-market angle targeting academic medical centers with customizable prototypes for clinical trial protocols bypasses GPO exclusion barriers.
For Investors and Strategic Acquirers: Roll-up economics work for ISO 10993-certified silicone fabricators because EU MDR compliance burdens freeze smaller competitors from European distribution. Five-to-ten year viability rests on telehealth platform integration expanding addressable patient populations. The signal to watch is CMS reimbursement code expansion for remote cardiac monitoring, which would accelerate premium pouch tier adoption against commoditized alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification Pathway | Streamlines encrypted telemetry pouch integration with cloud-based cardiac platforms at United States hospitals. |
| Antimicrobial Silver-Ion Substrate Development | Enables 14-day Holter wear protocols that reduce per-patient pouch consumption for extended monitoring. |
| India PLI Manufacturing Scale-Up | Attracts contract manufacturers seeking cost-competitive export bases for reusable silicone variants. |
| AI-Enabled Predictive Fitting Platform | Converges machine learning with 3D-printed prototyping for bariatric and geriatric biometric optimization. |
| EU MDR Material Traceability Investment | Extends certification timelines but freezes commodity competitors from REACH-regulated European distribution. |
Research Methodology
Coverage spans United States, Germany, India, Japan, and United Kingdom markets, with primary inputs from each region combined with secondary validation. Interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and home healthcare durable medical equipment distributors informed demand-side dynamics. Secondary sources include FDA 510(k) filings for telemetry accessories, CMS Medicare reimbursement code databases, EU MDR technical documentation requirements, and hospital procurement contract aggregators. Bottom-up unit demand modeling triangulates against top-down market sizing across material and application segments.
Granularity-level modeling disaggregates volume and value outputs by product type, application, material substrate, and end-user procurement channel across the analysis window. Segment-specific CAGRs derive from regression analysis of historical Medicare reimbursement expansion, FDA digital health guidance implementation timelines, and EU MDR compliance cost absorption curves. Industry-specific forecast inputs incorporate platinum-cured silicone supply elasticity and telehealth platform integration adoption curves.
Several conditions sit outside the modeled scope, including disruptive dry-electrode ECG technology maturation, unforeseen REACH chemical restriction amendments, and acute platinum-cured silicone supply disruptions. Forecasts reflect documented assumptions regarding reimbursement code stability and material certification pathway continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
North America Lithium-Ion Battery Pouch Film Market
Pouch
Paper Pouch Market
Pouch
Aluminum Pouches Market
Pouch
PCR Pouches Market
Pouch
Kraft Pouch Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Germany Pouch Packaging Market
Pouch
OPP Pouches Market
Pouch
Box Pouch Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Liquid Pouch Market
Pouch
Doy Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market