
 Retinal Vein Occlusion Treatment Market | 2026-2036
Retinal Vein Occlusion Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Vein Occlusion Treatment Market Intelligence
Aflibercept is decoupling from bevacizumab as the preferred anti-VEGF agent in retinal vein occlusion protocols, altering cost structures and reimbursement negotiations across payer systems. Regeneron Pharmaceuticals leverages its EYLEA franchise to anchor premium positioning in intravitreal therapy. Novartis competes through sustained investment in sustained-release delivery platforms that reduce injection burden. Bayer differentiates via geographic dominance in European ophthalmology markets where access programs shape prescribing behavior.
Retinal vein occlusion treatment encompasses pharmacologic and procedural interventions targeting macular edema and neovascular complications arising from venous outflow obstruction in the retinal circulation. Anti-VEGF therapies function by inhibiting vascular endothelial growth factor signaling to reduce vascular permeability and leakage, administered via intravitreal injection at intervals determined by optical coherence tomography monitoring of central retinal thickness. Anti-VEGF Therapy leads the treatment type segment due to established efficacy in CRVO and BRVO subtypes, while Corticosteroids occupy a narrower niche in pseudophakic patients or anti-VEGF non-responders. Intravitreal Injection dominates the administration route dimension, though sustained-release implants represent the fastest-growing margin pool as manufacturers seek to extend dosing intervals beyond quarterly regimens.
The FDA, EMA, and WHO prequalification standards collectively shape ocular biologic development requirements, with the FDA's Breakthrough Therapy designation compressing Phase III timelines for novel VEGF inhibitors. EMA's MDR and CE marking requirements for intravitreal injection devices add compliance layers that favor established manufacturers with dedicated ophthalmology regulatory affairs capacity. Stakeholders must monitor biosimilar entry timelines for aflibercept and ranibizumab, as these will force portfolio decisions around pipeline prioritization and geographic resource allocation before patent cliffs materialize.
Market Dynamics
The Retinal Vein Occlusion Treatment Market is reshaping around sustained-release delivery platforms that compress injection frequency from monthly to semi-annual intervals, fundamentally altering clinic workflow economics and patient adherence profiles across ophthalmology practices.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated approval pathway compresses Phase III timelines for novel VEGF inhibitors, enabling faster market entry for intravitreal biologics targeting macular edema.
- Optical Coherence Tomography Integration:Real-time retinal thickness monitoring protocols are personalizing anti-VEGF dosing intervals, extending treatment durability and reducing clinic visit burden for BRVO and CRVO patients.
- Medicare Reimbursement Stability:Sustained physician fee schedule support for intravitreal injection procedures ensures consistent access for aging populations with comorbid vascular disease in the United States.
Market Restraints
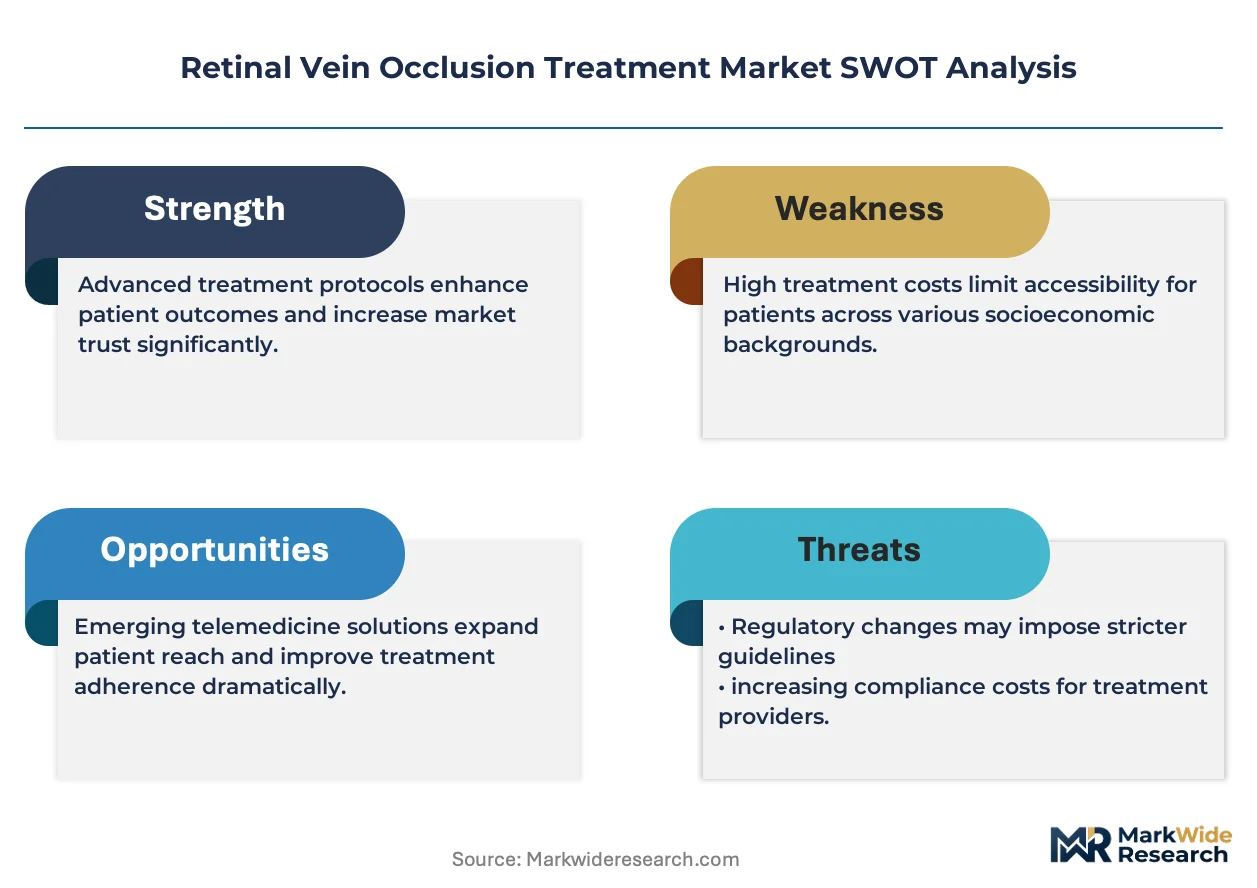
- Anti-VEGF Biosimilar Entry:Patent expiration timelines for aflibercept and ranibizumab will compress originator pricing power and force portfolio reallocation decisions before 2030.
- European CE Marking Burden:EMA's MDR compliance requirements for intravitreal injection devices favor established manufacturers with dedicated ophthalmology regulatory affairs capacity, raising barriers for new entrants.
- Corticosteroid Substitution Ceiling:Pseudophakic patient eligibility limits and intraocular pressure elevation risks constrain steroid implant adoption to narrow anti-VEGF non-responder populations.
Strategic Opportunities
- Gene Therapy Convergence:Combination of sustained-release depot technology with anti-VEGF gene silencing vectors offers potential for multi-year dosing intervals in treatment-naive CRVO patients.
- Home Monitoring Devices:Patient-operated optical coherence tomography peripherals are enabling remote disease activity surveillance, reducing injection visit frequency for stable BRVO cases.
- Indian Ophthalmology Expansion:CDSCO streamlined biologic approval pathways and growing private retina clinic networks are creating accessible volume pools for cost-optimized anti-VEGF formulations.
Industry Challenges
- Vitreoretinal Surgeon Training Bottleneck:Specialized intravitreal injection certification requirements and limited fellowship slots constrain clinic capacity expansion in secondary ophthalmology markets.
- Cold Chain Integrity Complexity:Temperature-sensitive biologic storage and multi-dose vial contamination protocols demand capital-intensive infrastructure investments for outpatient surgical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Vein Occlusion Treatment Market |
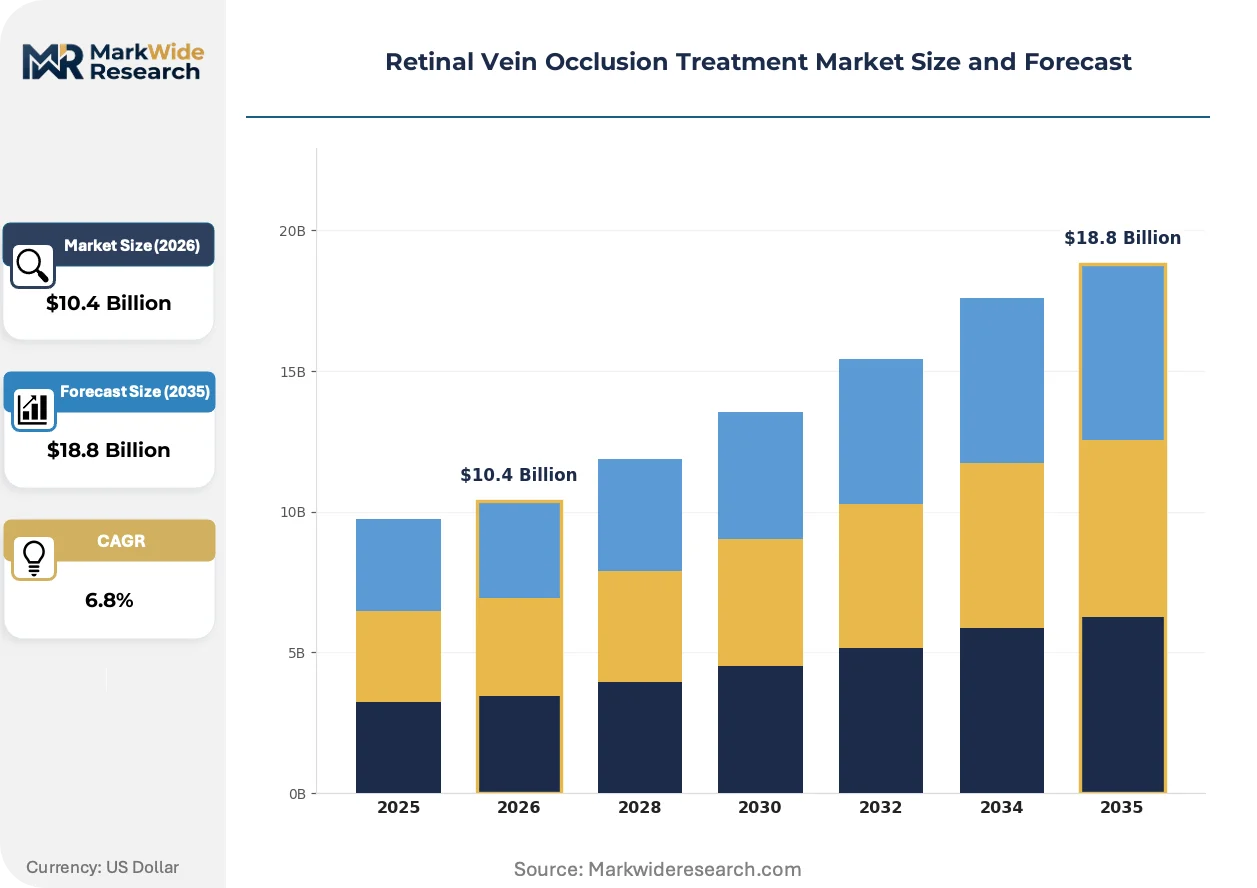
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $18.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Anti-VEGF Therapy, Laser Therapy, Corticosteroids, Surgical Interventions Administration Route: Intravitreal Injection, Topical, Systemic, Oral End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Product Type: Injectables, Devices, Pharmaceuticals, Combination Therapies |
| Companies Covered | Regeneron Pharmaceuticals, F. Hoffmann-La Roche Ltd., Novartis, Bayer, AbbVie Inc., Santen Pharmaceutical, Chugai Pharmaceutical Co., Ltd., Allergan, Apellis Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Vein Occlusion Treatment Market Strategic Shifts & Innovations
Retinal vein occlusion therapy is converging on extended-interval dosing paradigms that reduce treatment burden while preserving visual outcomes, driven by device-biologic integration and real-world evidence generation.
Sustained-release anti-VEGF implants are electrifying the standard of care for chronic macular edema management. Ophthalmology clinics in the United States and Germany are adopting port delivery systems and refillable reservoirs at accelerating pace. This technology is electrifying competitive positioning by decoupling treatment efficacy from patient visit compliance, enabling premium pricing for reduced-injection regimens.
EMA's Medical Device Regulation (MDR) is tightening post-market surveillance requirements for intravitreal injection systems, mandating enhanced clinical follow-up data collection. Device manufacturers must now demonstrate long-term biocompatibility and explant safety profiles beyond initial CE marking. European ophthalmology clinics are responding by consolidating procurement around suppliers with established MDR technical documentation capabilities.
Patient self-advocacy for injection interval extension is intensifying as real-world visual acuity data disseminates through retina patient advocacy networks. Traditional fixed-interval protocols are yielding to treat-and-extend algorithms guided by optical coherence tomography stability criteria. This behavioral shift is most pronounced in United States Medicare populations where transportation barriers and copay accumulation drive preference for fewer clinic visits.
Retinal Vein Occlusion Treatment Market Segmentation
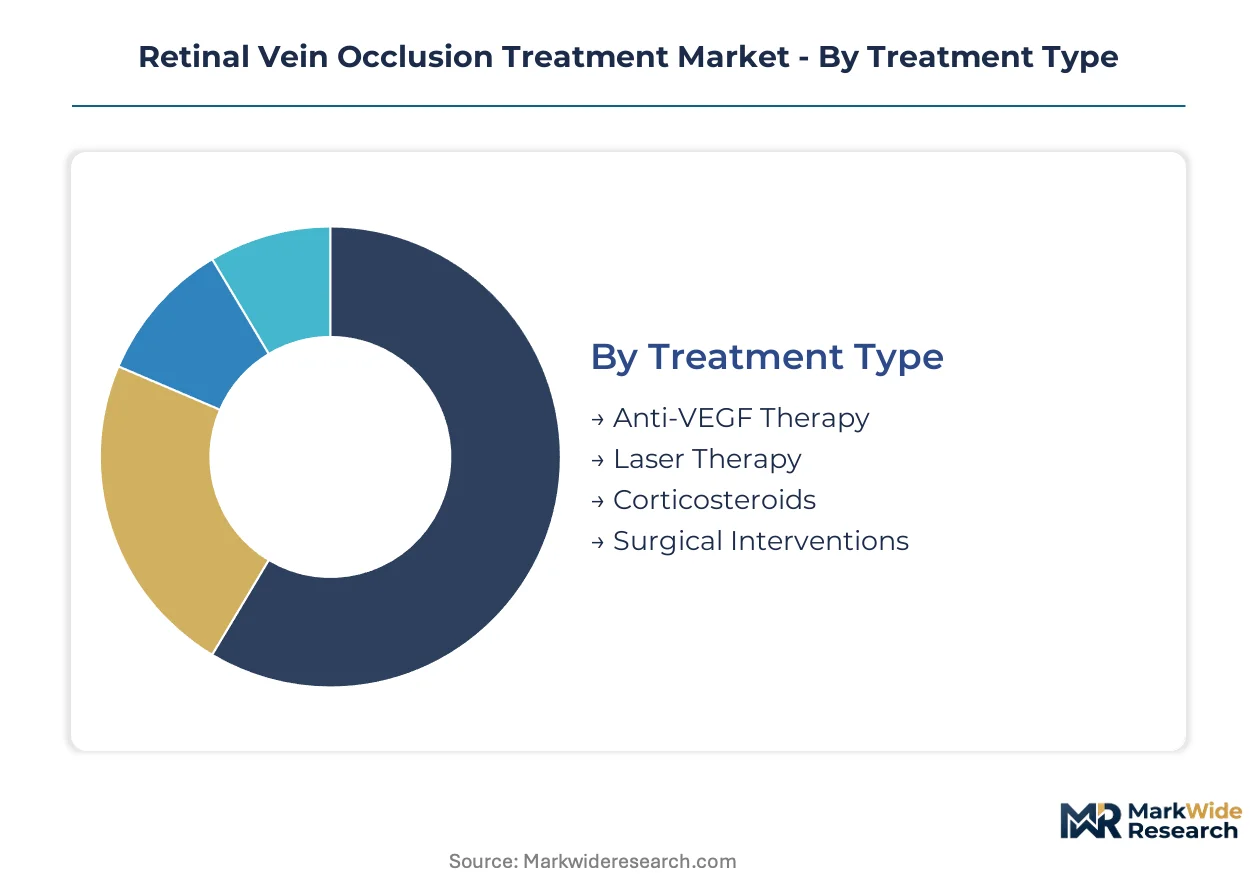
Retinal vein occlusion treatment markets fragment across therapeutic modality, delivery mechanism, and care setting. Each segmentation axis reveals distinct margin structures, regulatory pathways, and competitive intensity profiles that shape portfolio allocation decisions.
Treatment Type:
Supply concentration clusters around biologic manufacturing capacity, with sterile fill-finish capabilities and cold chain infrastructure determining competitive access.
- Anti-VEGF Therapy:Intravitreal biologics targeting vascular endothelial growth factor signaling reduce macular edema through vascular permeability inhibition. Demand concentrates in United States Medicare populations where reimbursement stability supports sustained injection regimens for aging patients with comorbid diabetes and hypertension.
- Corticosteroids:Intraocular steroid implants and triamcinolone acetonide formulations address anti-VEGF non-responders and pseudophakic patients. European ophthalmology practices in Germany and France drive adoption where EMA post-market surveillance frameworks guide steroid selection for elevated intraocular pressure risk management.
- Laser Therapy:Panretinal photocoagulation and macular grid laser procedures target ischemic complications in branch retinal vein occlusion subtypes.
- Surgical Interventions:Vitrectomy with radial optic neurotomy or sheathotomy addresses refractory cases with tractional complications.
Today's leader: Anti-VEGF Therapy. Tomorrow's challenger: Corticosteroids in sustained-release formulations.
Administration Route:
Cost tier differentiation separates capital-intensive depot systems from commodity injection procedures, with reimbursement bandwidth determining accessible technology tiers.
- Intravitreal Injection:Direct vitreal cavity delivery via pars plana puncture enables therapeutic concentrations at the retinal pigment epithelium. Ophthalmology clinics in the United States and Germany are expanding injection suite capacity to accommodate treat-and-extend protocols driven by optical coherence tomography monitoring integration.
- Topical:Periocular and trans-scleral delivery routes remain investigational for large-molecule biologics with limited corneal penetration.
- Systemic:Intravenous anti-VEGF administration is restricted to oncology indications with unacceptable ocular risk profiles for retinal vascular disease.
- Oral:Small-molecule VEGF receptor tyrosine kinase inhibitors face blood-retinal barrier penetration challenges and systemic toxicity limitations.
Intravitreal Injection commands current volume. Sustained-release implants are climbing the fastest toward extended-interval paradigms.
End User:
Application concentration varies by procedure complexity, with surgical volume and biologic handling capabilities filtering patient flow across facility types.
- Ophthalmology Clinics:Dedicated retina practices in urban United States markets concentrate anti-VEGF injection volume through streamlined optical coherence tomography workflow integration and specialized nursing staff.
- Hospitals:Academic medical centers manage complex CRVO cases requiring combined surgical-pharmacologic intervention and fellowship training pipelines.
- Ambulatory Surgical Centers:Outpatient facilities capture corticosteroid implant procedures and laser photocoagulation with favorable site-of-service reimbursement differentials.
- Research Institutions:Phase III trial sites and investigator-initiated studies drive novel agent validation through FDA Breakthrough Therapy designation pathways.
Ophthalmology Clinics anchor present utilization. Ambulatory Surgical Centers are gaining share fastest through procedure migration and cost efficiency.
Product Type:
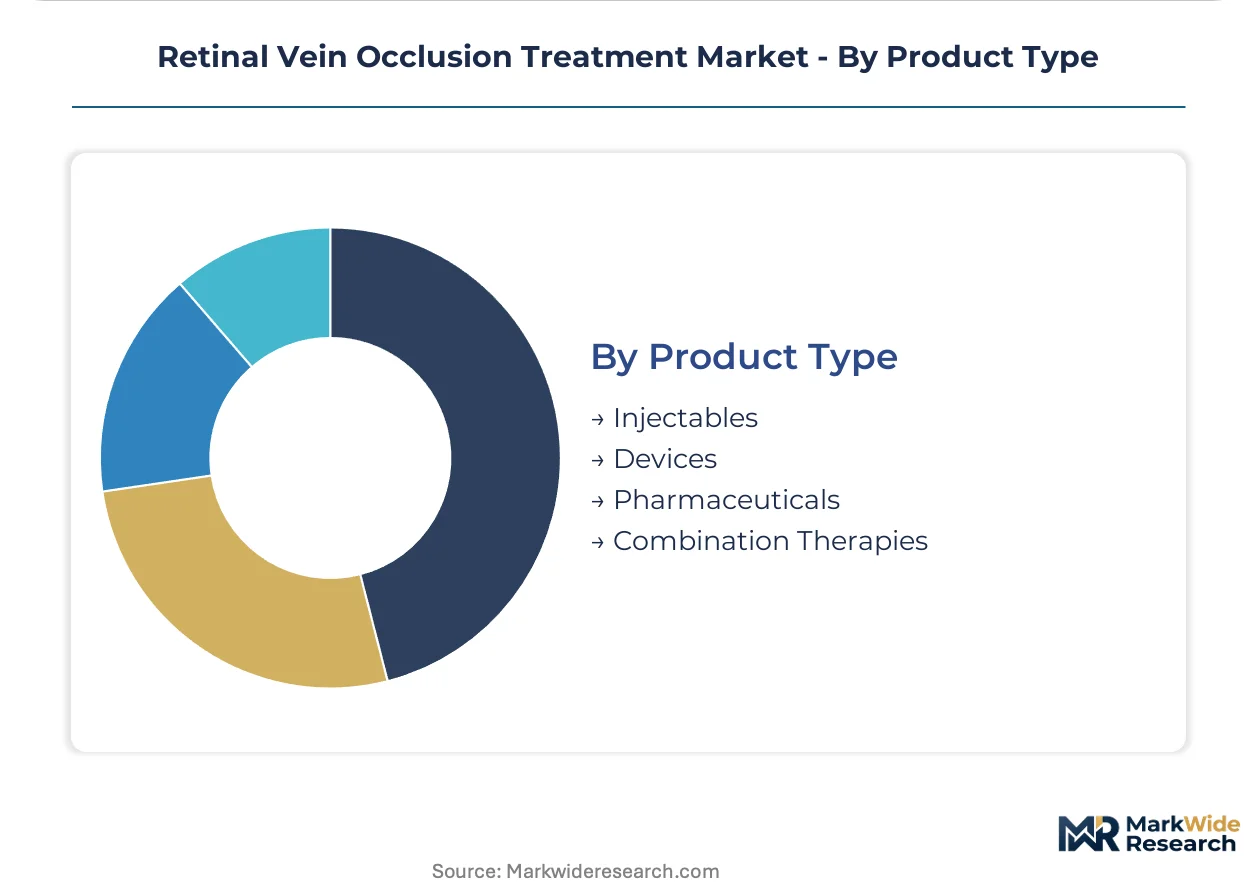
Margin concentration favors integrated delivery systems over commodity pharmaceuticals, with device-biologic combinations capturing premium positioning.
- Injectables:Vial and prefilled syringe formulations of ranibizumab, aflibercept, and biosimilar candidates dominate procurement volumes.
- Devices:Intravitreal injection systems, sustained-release ports, and refillable reservoirs represent the steepest expansion trajectory as EMA MDR compliance requirements favor established technical documentation capabilities.
- Pharmaceuticals:Small-molecule adjuncts and combination therapies address inflammatory mediators beyond VEGF signaling pathways.
- Combination Therapies:Anti-VEGF plus corticosteroid protocols and photodynamic laser adjuncts target recalcitrant macular edema in treatment-experienced populations.
Injectables maintain current revenue leadership. Devices are expanding most quickly through extended-interval value propositions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ophthalmology practices concentrate intravitreal injection volume through Medicare reimbursement stability and specialized retina clinic networks in metropolitan corridors.
United States
Medicare Part B physician fee schedules sustain anti-VEGF injection access for aging populations with diabetic and hypertensive comorbidities. FDA Breakthrough Therapy designations compress Phase III timelines for novel VEGF inhibitors entering macular edema protocols. Boston and New York City retina practices pioneer treat-and-extend algorithms guided by optical coherence tomography monitoring integration.
Germany
Statutory health insurance frameworks reimburse intravitreal therapies with minimal prior authorization barriers for branch and central retinal vein occlusion subtypes. EMA MDR compliance requirements for sustained-release injection devices favor established technical documentation capabilities. Heidelberg and Munich academic medical centers anchor clinical trial recruitment for extended-interval depot formulations.
Japan
Aging demographics and high diabetic retinopathy prevalence generate sustained demand for macular edema interventions across prefectural hospital networks. PMDA priority review vouchers accelerate approval timelines for novel anti-VEGF biologics demonstrating superior durability. Tokyo and Osaka retina specialists concentrate injection volume through streamlined optical coherence tomography workflow protocols.
India
Private ophthalmology chains expand retina clinic capacity to address undertreated branch retinal vein occlusion in tier-1 and tier-2 urban markets. CDSCO streamlined biologic approval pathways reduce regulatory lag for cost-optimized anti-VEGF formulations. Chennai and Hyderabad surgical centers adopt intravitreal injection suites with cold chain infrastructure for temperature-sensitive biologic storage.
United Kingdom
NICE technology appraisals guide formulary positioning for ranibizumab and aflibercept across integrated care systems managing retinal vascular disease. MHRA post-Brexit regulatory autonomy maintains alignment with EMA safety surveillance standards for ocular biologics. London Moorfields Eye Hospital and Manchester Royal Eye Hospital anchor fellowship training pipelines for vitreoretinal surgical specialization.
Retinal Vein Occlusion Treatment Market Key Industry Players
Global majors compete with regional champions across intravitreal therapy development and sustained-release delivery platform commercialization. Market structure tilts toward concentrated biologic manufacturing capacity controlled by vertically integrated pharmaceutical conglomerates with dedicated ophthalmology franchises. Three archetypes dominate: originator biologic developers with patent-protected VEGF inhibitors, sustained-release device innovators seeking extended-interval dosing differentiation, and biosimilar manufacturers preparing for post-patent entry. Competitive intensity centers on M&A activity targeting gene therapy pipelines and strategic partnerships combining biologic assets with refillable reservoir technologies.
Within the originator biologic tier, Regeneron Pharmaceuticals and Novartis exemplify divergent strategic positioning. Regeneron anchors premium market presence through established intravitreal franchise penetration in United States retina practices. Novartis occupies a position emphasizing sustained-release delivery platform investment to reduce injection burden and extend dosing intervals. Roche subsidiary Genentech represents the integrated big-pharma archetype with global manufacturing scale and cross-indication VEGF inhibitor development capabilities.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| F. Hoffmann-La Roche Ltd. |
| Novartis |
| Bayer |
| AbbVie Inc. |
| Santen Pharmaceutical |
| Chugai Pharmaceutical Co., Ltd. |
| Allergan |
| Apellis Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Cold chain logistics costs for temperature-sensitive biologics cascade through three pricing tiers, with originator anti-VEGF therapies commanding premium positioning against biosimilar-ready standard formulations and cost-optimized economy alternatives in emerging markets.
Pricing Analysis
Input-cost pass-through from sterile fill-finish capacity and aseptic manufacturing infrastructure shapes tiered pricing across intravitreal therapy markets. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected originators from imminent biosimilars and regional cost-optimized formulations. Pricing pressure stems from aflibercept and ranibizumab patent expiration timelines compressing originator margins before substitution accelerates. Ophthalmology clinics in Medicare-saturated United States markets exhibit lowest price sensitivity, while private retina practices in India and Southeast Asia face acute cost constraints driving formulary substitution.
Supply Chain Analysis
Single-source vulnerability sits with concentrated sterile manufacturing capacity in United States, Germany, and Switzerland for active pharmaceutical ingredient synthesis and aseptic filling operations. Raw material dependencies center on recombinant protein expression systems, pharmaceutical-grade polysorbate surfactants, and borosilicate glass syringe components. Supply chain risk hinges on cold chain integrity failures during multi-dose vial distribution to outpatient surgical centers. Distribution runs through specialized ophthalmology distributor networks with temperature-controlled logistics rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended-interval dosing platforms are expanding addressable margins by decoupling revenue from injection visit frequency, with sustained-release device-biologic combinations capturing premium positioning against commodity intravitreal formulations.
For Market Incumbents: Cement franchise durability through backward integration into refillable reservoir manufacturing and exclusive optical coherence tomography workflow partnerships with leading United States retina practices. Biosimilar entry timelines for core anti-VEGF assets threaten pricing power, requiring pre-emptive portfolio diversification into gene therapy pipelines and sustained-release delivery platforms before patent cliffs materialize.
For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer lowest-friction entry into ambulatory surgical center segments underserved by incumbent field forces. White-space concentration in Indian private ophthalmology chains and Southeast Asian retina clinic networks presents accessible volume pools for cost-optimized formulations, with CDSCO streamlined pathways reducing regulatory lag versus FDA or EMA timelines.
For Investors and Strategic Acquirers: Roll-up economics work for sustained-release device innovators because extended-interval value propositions command durable premium pricing against commodity injection regimens. Five-to-ten year viability centers on patent-protected delivery platform assets with demonstrated explant safety profiles. The signal to watch is EMA MDR technical documentation completion rates as a proxy for competitive moat sustainability in European ophthalmology procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Accelerated Phase III timelines compress development cycles for novel VEGF inhibitors targeting macular edema protocols. |
| Sustained-Release Device Development | Refillable reservoir platforms extend dosing intervals beyond quarterly regimens, reducing clinic visit burden. |
| Reimbursement Strategy Optimization | Medicare Part B physician fee schedule alignment ensures consistent access for aging populations with vascular comorbidities. |
| Manufacturing Scale-Up | Sterile fill-finish capacity expansion supports treat-and-extend protocol adoption across United States retina practices. |
| Pipeline Diversification | Gene therapy and anti-VEGF gene silencing vectors address multi-year dosing interval demand in treatment-naive patients. |
Research Approach
Bottom-up ophthalmology clinic and hospital procurement modeling reconciled against top-down biologic manufacturer shipment tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity across treatment type, administration route, and end-user dimensions.
Input-output matrix framing connects patient population epidemiology, injection visit frequency assumptions, and optical coherence tomography monitoring protocol adoption to derive volume and value trajectories across the projection horizon. Segmentation dimensions modeled encompass treatment line, dosage form, administration route, patient population comorbidity profiles, and regional regulatory cluster variations. CAGRs were synthesized from procedure volume elasticity analysis and pricing tier migration patterns, with specific weighting applied to sustained-release implant adoption curves and biosimilar substitution elasticity assumptions.
Regulatory approval delays, biosimilar entry acceleration, and sustained-release device safety signal emergence are the dominant revision risks to modeled trajectories. Forecasts reflect documented assumptions regarding reimbursement stability, injection suite capacity expansion, and cold chain infrastructure investment pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Lazy Eye Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Ophthalmic Eye Drops Market