
 Australia Ophthalmic Devices Market | 2026-2036
Australia Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Ophthalmic Devices Market Analysis
Silicone hydrogel is broadening the economics of contact lens portfolios across Australia by displacing conventional hydrogel formulations in premium daily disposable lines. Alcon leverages its upstream control over silicone hydrogel polymer supply to sustain margin advantages in the therapeutic contact lens segment. EssilorLuxottica anchors its position through vertically integrated lens design and retail channel dominance across Australian optometry chains. Carl Zeiss Meditec differentiates via high-R&D-intensity optical coherence tomography platforms that occupy the premium diagnostic tier in tertiary eye hospitals.
Ophthalmic devices comprise precision-engineered instruments, implants, and optical systems designed for the diagnosis, surgical intervention, and therapeutic management of ocular conditions, typically manufactured to tolerances within micrometers and sterilized to ISO 14155 standards for clinical deployment. These devices serve the primary commercial purpose of restoring, preserving, or enhancing visual function across institutional and ambulatory care settings. Diagnostic instruments lead current revenue pools due to replacement cycles tied to software-upgrade pathways, while surgical robotics within the technology dimension represents the fastest-growing structural segment as Australian hospitals prioritize capital expenditure on automated cataract and retinal platforms. Contact lenses maintain mature, high-volume characteristics with margin concentration in silicone hydrogel daily disposables, whereas retinal imaging applications command premium pricing through integration with AI-assisted diagnostic workflows.
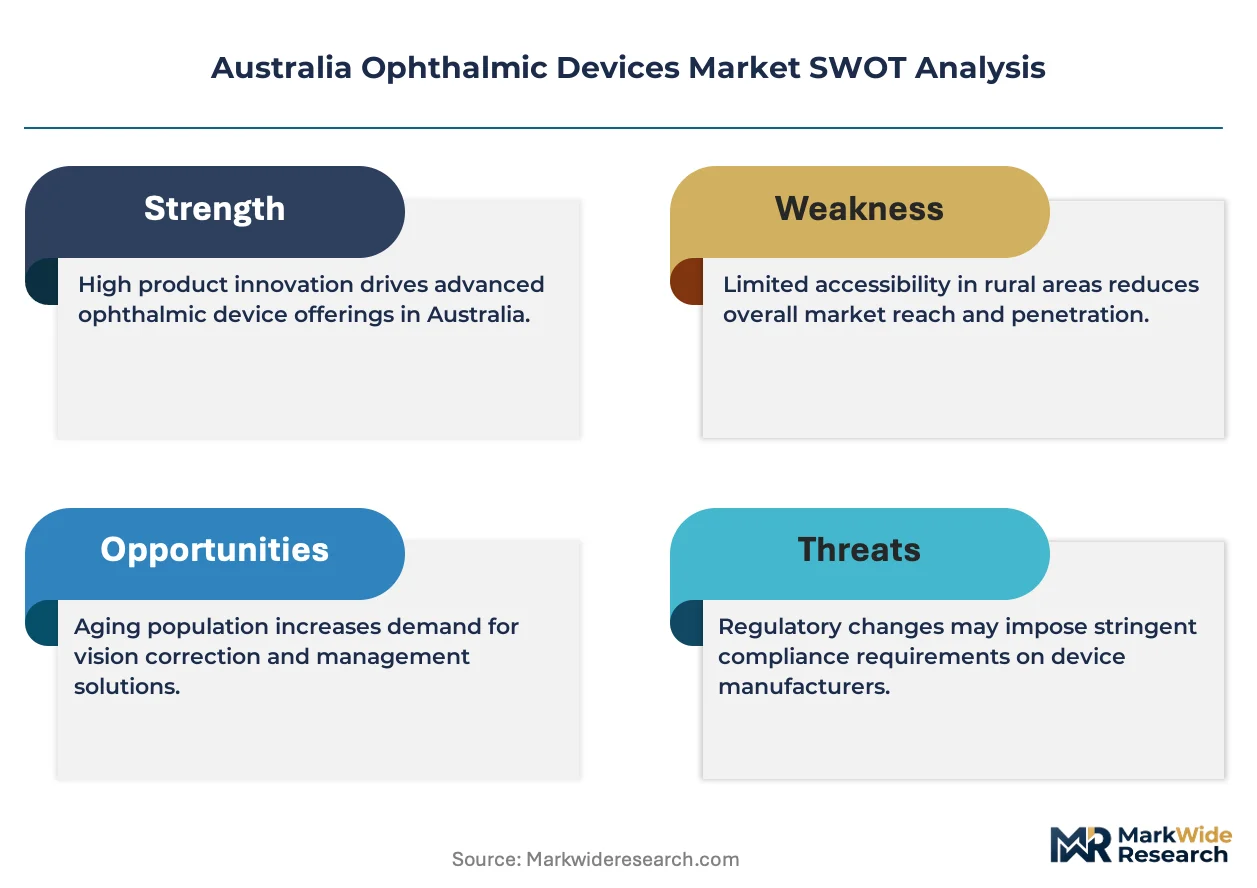
TGA medical device regulations, coupled with the Medical Device Single Audit Program and ISO 13485 quality management standards, shape product registration timelines and post-market surveillance obligations for manufacturers supplying the Australian market. The Therapeutic Goods Administration's alignment with EU MDR transition pathways is forcing early-stage design-control investments from imported device portfolios. Stakeholders must monitor how TGA's evolving software-as-a-medical-device guidance intersects with AI-enabled diagnostic platforms to determine regulatory capital allocation and local partnership strategies.
Market Dynamics
Silicone hydrogel polymer chemistry is consolidating supplier power upstream while TGA's compressed approval timelines for laser platforms accelerate capital deployment cycles across private ophthalmology networks in New South Wales and Victoria.
Growth Catalysts
- TGA pathway compression:The Therapeutic Goods Administration's streamlined registration for novel laser platforms reduces time-to-revenue for manufacturers targeting cataract surgery applications.
- Private clinic expansion:Sydney and Melbourne ophthalmology practices are scaling diagnostic instrument fleets to capture referral volume from aging populations in southeastern states.
- AI diagnostic integration:Optical coherence tomography platforms with embedded machine learning algorithms are pulling replacement demand in tertiary eye hospitals seeking workflow automation.
Market Restraints
- Silicone hydrogel supply concentration:Upstream polymer production concentrates among a limited set of chemical suppliers, creating margin pressure for downstream contact lens manufacturers.
- ISO 13485 compliance burden:Quality management system certification requirements impose fixed-cost barriers on mid-scale device importers without established Australian regulatory infrastructure.
- Conventional hydrogel displacement:Legacy hydrogel formulations face rapid demand erosion as daily disposable silicone hydrogel lines capture premium positioning in optometry retail channels.
Strategic Opportunities
- Western Australia underpenetration:Perth and regional centers maintain lower diagnostic instrument density per capita than Sydney-Melbourne corridors, creating whitespace for capital deployment.
- Surgical robotics convergence:Automated cataract and retinal platforms combining femtosecond lasers with intraoperative guidance systems represent unclaimed premium tier positioning.
- Software-as-a-medical-device guidance:TGA's evolving framework for AI-enabled diagnostic workflows creates first-mover advantage for platforms with embedded regulatory compliance architecture.
Industry Challenges
- Specialized technician scarcity:Optical coherence tomography platform maintenance and calibration requires trained biomedical engineers concentrated in major metropolitan centers.
- Legacy system integration friction:New diagnostic instruments must interface with hospital information systems and picture archiving infrastructure built on decade-old architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Ophthalmic Devices Market |
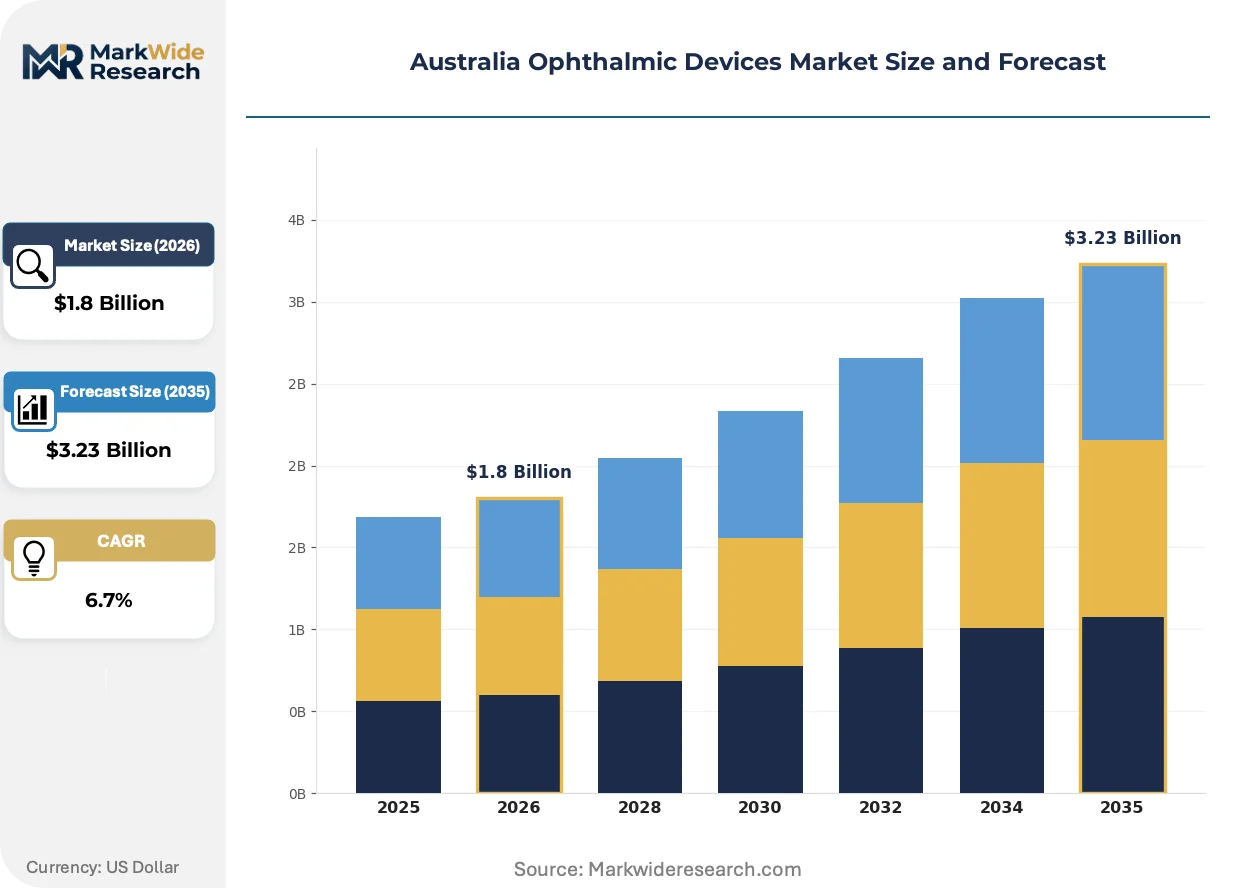
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Instruments, Surgical Instruments, Therapeutic Devices, Contact Lenses Technology: Laser Technology, Optical Coherence Tomography, Retinal Imaging, Surgical Robotics End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutes Application: Cataract Surgery, Retinal Detachment, Glaucoma Treatment, Vision Correction |
| Companies Covered | Carl Zeiss Meditec, EssilorLuxottica, Alcon, HAAG-Streit Group, Nidek Co., Ltd., Bausch + Lomb, Topcon Corporation, Ziemer Ophthalmic Systems, Johnson & Johnson Vision, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Ophthalmic Devices Market Emerging Trajectories
Technological consolidation across diagnostic imaging, regulatory acceleration of software-enabled devices, and procurement model evolution in private practice networks are reshaping competitive positioning in Australian ophthalmic care delivery.
Femtosecond laser platforms for cataract surgery is consolidating market structure by compressing procedure variability and reducing surgeon learning curves. Private ophthalmology clinics in Sydney and Melbourne are adopting these systems at accelerated replacement cycles. The technology is consolidating premium-tier surgical volume into capital-intensive practices capable of absorbing platform depreciation.
TGA alignment with EU MDR transition pathways is forcing design-control investments from imported device portfolios. Manufacturers must restructure technical documentation and clinical evidence packages to maintain market access. Surgical implant categories face the steepest compliance burden as biocompatibility testing requirements expand.
After-sales service unbundling is disrupting traditional capital equipment purchasing in tertiary eye hospitals. Buyers now separate hardware acquisition from maintenance contracts and software upgrade subscriptions. Queensland and South Australian public hospital networks are piloting performance-based service agreements that tie vendor payments to equipment uptime metrics.
Australia Ophthalmic Devices Market Segmentation
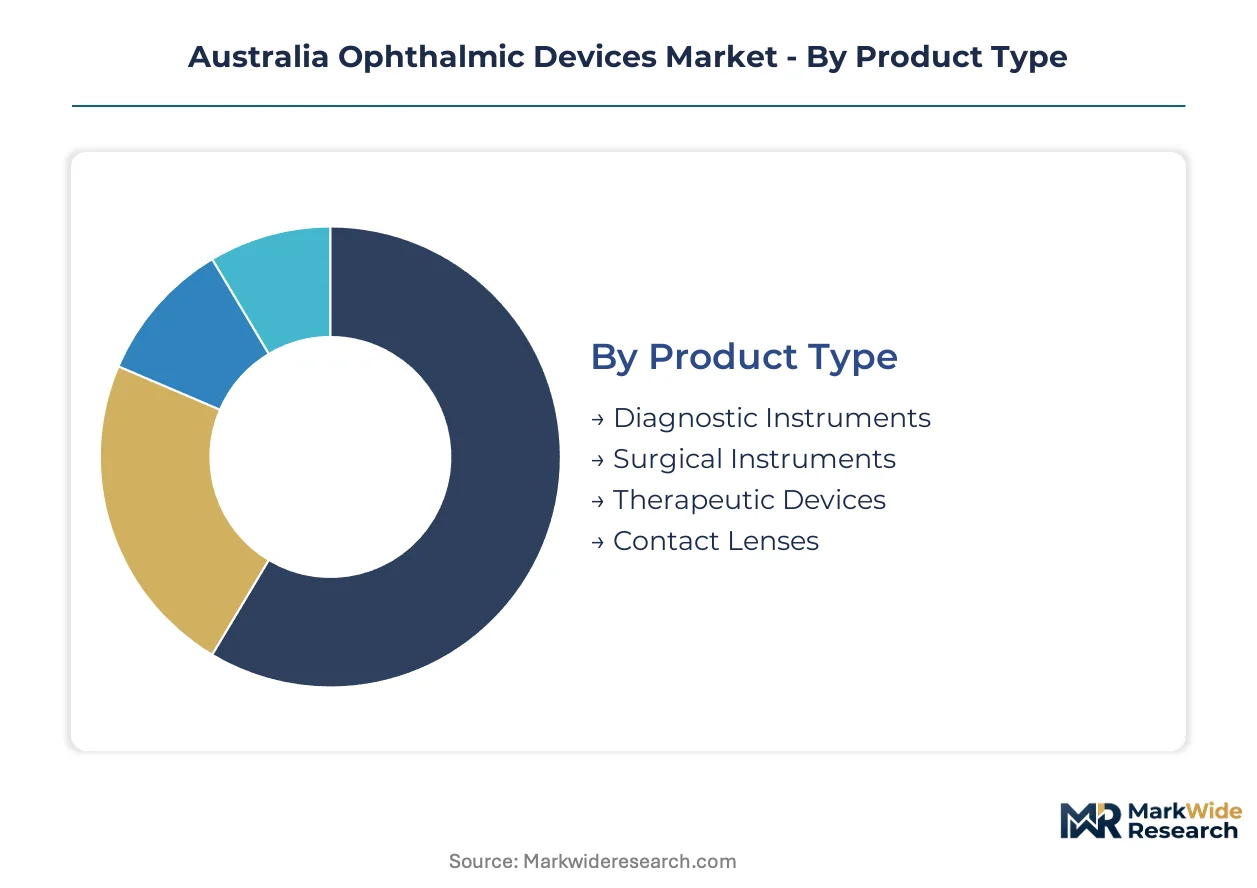
Ophthalmic device purchasing in Australia splits sharply between high-volume consumables and premium capital platforms. Understanding where procurement budgets concentrate across product, technology, and care settings reveals where margin pools accrue for manufacturers.
Product Type:
Volume leadership sits with disposable lines, while premium positioning concentrates in capital equipment with extended depreciation cycles.
- Diagnostic Instruments:Optical coherence tomography and fundus cameras dominate hospital procurement in New South Wales and Victoria. Replacement demand accelerates where software-upgrade pathways lock tertiary eye hospitals into vendor ecosystems.
- Surgical Instruments:Femtosecond laser platforms and phacoemulsification systems command capital budgets in private Sydney and Melbourne ophthalmology clinics. TGA pathway compression for novel laser registrations is shortening deployment timelines across southeastern states.
- Therapeutic Devices:Intraocular lenses and sustained-release drug delivery implants serve post-surgical recovery protocols.
- Contact Lenses:Silicone hydrogel daily disposables capture margin concentration through upstream polymer supply control.
Mature deployment sits with Contact Lenses. Newer deployment is concentrated in Diagnostic Instruments.
Technology:
Capital intensity separates established imaging modalities from emerging automated platforms requiring specialized biomedical engineering support.
- Laser Technology:Femtosecond and excimer systems enable precise corneal and capsular interventions. Private clinic networks in Melbourne prioritize these platforms for cataract surgery volume capture.
- Optical Coherence Tomography:High-R&D-intensity spectral-domain and swept-source systems occupy the premium diagnostic tier in tertiary eye hospitals. AI-assisted diagnostic workflows are pulling replacement demand where machine learning algorithms automate pathology detection.
- Retinal Imaging:Wide-field angiography and adaptive optics serve specialized retinal disease management.
- Surgical Robotics:Automated cataract and retinal platforms combining femtosecond lasers with intraoperative guidance systems are expanding most quickly as Australian hospitals prioritize capital expenditure on workflow automation.
Established deployment sits with Laser Technology. Emerging deployment is concentrated in Surgical Robotics.
End User:
Procurement authority fragments between public hospital networks with formal tender processes and private clinics with discretionary capital deployment.
- Hospitals:Tertiary eye hospitals in Queensland and South Australia pilot performance-based service agreements tying vendor payments to equipment uptime metrics. After-sales service unbundling is disrupting traditional capital equipment purchasing.
- Clinics:Private ophthalmology practices in Sydney and Melbourne scale diagnostic instrument fleets to capture aging population referral volume. These buyers move faster on capital deployment than public procurement cycles permit.
- Ambulatory Surgical Centers:Day-procedure facilities concentrate cataract surgery volume with streamlined patient throughput.
- Research Institutes:Academic medical centers drive early adoption of experimental diagnostic platforms.
Volume concentration sits with Hospitals. Margin expansion is concentrated in Clinics.
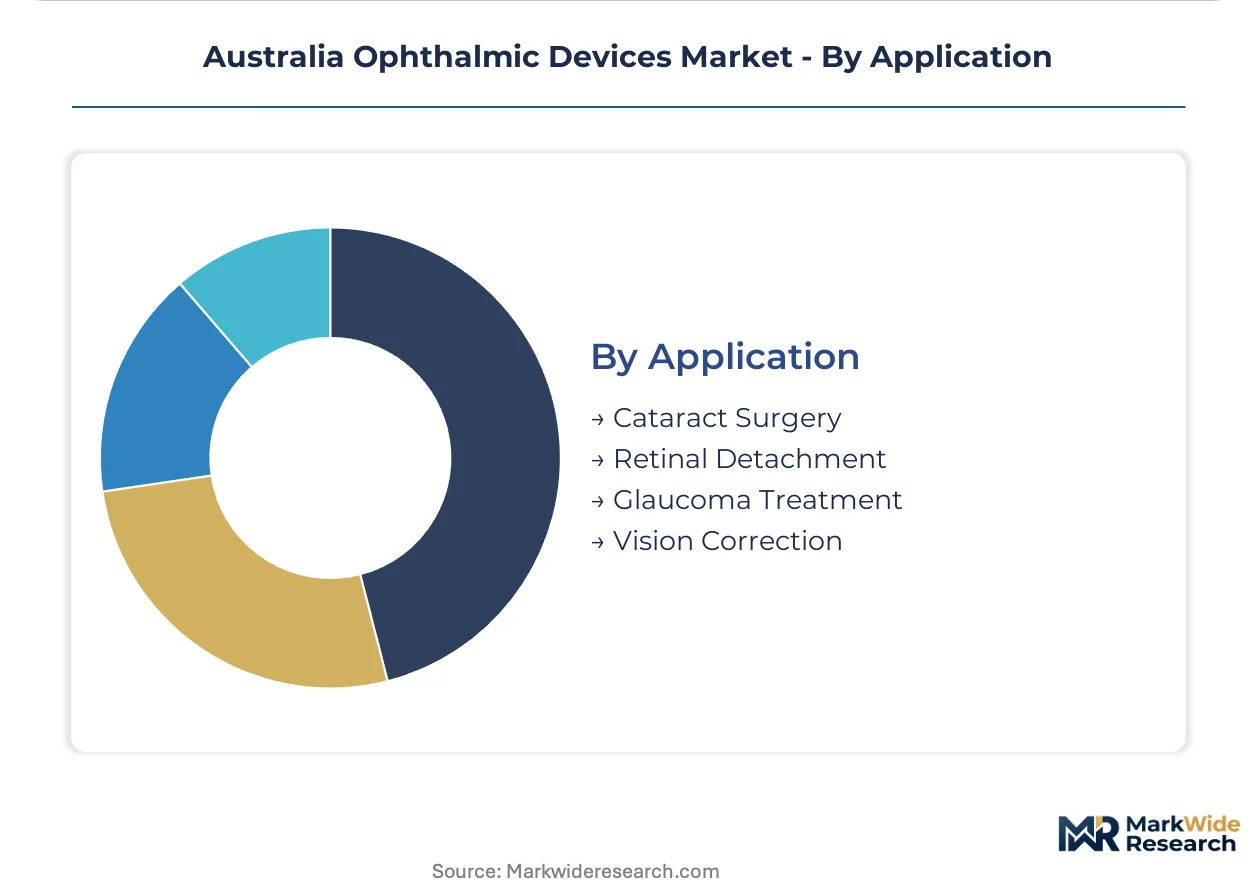
Application:
Procedure reimbursement rates and patient demographics determine where device manufacturers allocate clinical education resources.
- Cataract Surgery:Femtosecond laser platforms compress procedure variability while consolidating premium-tier surgical volume into capital-intensive practices. New South Wales and Victoria account for disproportionate demand concentration.
- Retinal Detachment:Vitrectomy systems and scleral buckling hardware serve urgent surgical interventions. Specialized technician scarcity for platform maintenance concentrates service capacity in major metropolitan centers.
- Glaucoma Treatment:Minimally invasive stents and sustained-release drug delivery address chronic pressure management.
- Vision Correction:LASIK and PRK laser platforms serve elective refractive procedures with consumer-direct marketing dynamics.
Procedure volume sits with Cataract Surgery. Technology upgrade intensity is concentrated in Retinal Detachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australian government's Medical Research Future Fund and state-level health infrastructure programs concentrate ophthalmic device procurement in designated hospital networks across southeastern states. TGA regulatory alignment with international standards accelerates deployment timelines for manufacturers targeting these corridors.
New South Wales
Sydney's private ophthalmology clinics drive diagnostic instrument replacement cycles as aging populations expand cataract surgery queues. TGA streamlined registration pathways compress approval timelines for femtosecond laser platforms entering this market. The Sydney-Metro hospital network anchors premium-tier optical coherence tomography deployment in tertiary eye centers.
Victoria
Melbourne's specialist eye hospitals pull AI-integrated retinal imaging systems through performance-based procurement pilots. State health procurement frameworks favor equipment vendors offering unbundled service contracts with uptime guarantees. The Parkville biomedical precinct concentrates maintenance technician capacity for complex diagnostic platforms.
Queensland
Brisbane's public hospital networks experiment with outcome-based vendor agreements tying payments to equipment availability metrics. TGA software-as-a-medical-device guidance creates compliance complexity for AI-enabled diagnostic platforms entering procurement cycles. The Gold Coast corridor maintains lower diagnostic instrument density per capita than Sydney-Melbourne benchmarks.
Western Australia
Perth's ophthalmology service networks present whitespace for capital equipment deployment given underpenetrated diagnostic infrastructure relative to eastern states. State health department tender processes lag private clinic procurement velocity in instrument replacement decisions. Regional centers outside Perth face specialized technician scarcity for platform maintenance and calibration.
South Australia
Adelaide's hospital networks pilot subscription-based service models separating hardware acquisition from software upgrade pathways. TGA post-market surveillance obligations concentrate compliance investment among suppliers with established Australian regulatory infrastructure. The Adelaide biomedical manufacturing zone hosts limited domestic device assembly capacity relative to import-dependent supply chains.
Australia Ophthalmic Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium diagnostic platforms consolidating around capital-intensive players while contact lens supply chains fragment across polymer chemistry specialists. The market structure favors incumbents with TGA-established regulatory infrastructure and hospital procurement relationships. Three archetypes dominate: vertically integrated optical conglomerates controlling retail distribution, high-R&D-intensity diagnostic platform specialists, and upstream polymer suppliers capturing margin in silicone hydrogel formulations. Competitive moves concentrate on software-upgrade pathway lock-in and service contract unbundling.
Among the named players, Carl Zeiss Meditec and EssilorLuxottica occupy distinct positioning archetypes within the premium tier. Carl Zeiss Meditec exemplifies the high-R&D-intensity diagnostic specialist model through its spectral-domain optical coherence tomography platforms. EssilorLuxottica represents vertically integrated control spanning lens design through optometry retail channel dominance. Alcon anchors the upstream-controlled contact lens segment through silicone hydrogel polymer supply positioning.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| EssilorLuxottica |
| Alcon |
| HAAG-Streit Group |
| Nidek Co., Ltd. |
| Bausch + Lomb |
| Topcon Corporation |
| Ziemer Ophthalmic Systems |
| Johnson & Johnson Vision |
| Others |
Supply Flow & Price Mechanics
Femtosecond laser platform adoption across Sydney and Melbourne ophthalmology networks is simultaneously compressing per-procedure cost curves and consolidating procurement authority into capital-intensive practice groups capable of absorbing platform depreciation schedules.
Pricing Analysis
Volume leadership sits with high-turnover consumables while margin concentration accrues to premium capital platforms with extended replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated optical coherence tomography systems from conventional imaging hardware and entry-level fundus cameras. Price differentiation hinges on software-upgrade pathway lock-in and TGA registration tier. Pricing pressure stems from silicone hydrogel polymer supply concentration among limited chemical suppliers. Public hospital procurement committees exhibit highest price sensitivity due to formal tender processes, while private Sydney-Melbourne clinics demonstrate lowest sensitivity given discretionary capital deployment authority.
Supply Chain Analysis
TGA alignment with EU MDR transition pathways is forcing design-control investments that reshape sourcing decisions for imported device portfolios. Manufacturing concentration rests on Germany, Switzerland, and Japan for precision optical components and laser systems. Raw material dependencies center on silicone hydrogel polymer feedstocks, high-purity optical glass, and semiconductor-grade sensors. Single-source vulnerability runs through femtosecond laser oscillator suppliers with limited qualified alternatives. Distribution runs through hospital procurement frameworks in Queensland and South Australia alongside direct sales relationships with private Melbourne-Sydney clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance scale as TGA's compressed approval timelines and ISO 13485 certification burdens force mid-scale importers toward exit or acquisition.
For Market Incumbents: Anchor software-upgrade pathway lock-in to sustain replacement demand from tertiary eye hospitals seeking workflow automation. Deepen TGA regulatory infrastructure investment to accelerate novel laser platform registrations ahead of competitor timelines. Acquire mid-scale diagnostic instrument importers facing ISO 13485 compliance barriers to consolidate hospital procurement relationships.
For New Entrants and Emerging Players: The mid-tier pricing gap between Carl Zeiss Meditec premium platforms and economy-grade alternatives creates whitespace for AI-enabled optical coherence tomography systems with embedded diagnostic algorithms. Target Western Australia diagnostic infrastructure gaps where Perth and regional centers maintain lower instrument density per capita than eastern state benchmarks. Pursue performance-based service agreements tying vendor payments to equipment uptime metrics as the go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in high-R&D-intensity diagnostic platform specialists with established TGA registration portfolios and tertiary hospital installed bases. Long-term viability favors manufacturers with captive silicone hydrogel polymer supply or vertically integrated lens design-through-retail control. Watch TGA software-as-a-medical-device guidance finalization as the inflection signal for AI-enabled diagnostic platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| TGA Registration Acceleration | Compressed approval timelines for femtosecond laser platforms shorten time-to-revenue for manufacturers targeting New South Wales cataract surgery volume. |
| Software Companion Development | AI-embedded optical coherence tomography systems automate pathology detection and pull replacement demand from tertiary eye hospitals. |
| Hospital System Partnership | Performance-based service agreements with Queensland public networks tie vendor payments to equipment uptime metrics. |
| Backward Integration into Polymer Supply | Captive silicone hydrogel production insulates contact lens margins from upstream chemical supplier concentration. |
| Reimbursement Strategy | Cataract surgery procedure codes determine capital equipment depreciation schedules across private Melbourne-Sydney clinic networks. |
Methodological Framework
Multi-period observation of TGA registration timelines, diagnostic instrument replacement cycles, and private clinic capital deployment patterns anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, ophthalmology clinic directors, and GPO contracts managers. Secondary validation drew from TGA public registration databases, hospital procurement disclosure records, ISO 13485 certification registries, and trade data on optical component imports. Bottom-up installed base modeling and top-down expenditure flow analysis were triangulated to cross-verify segment sizing.
Segment-weighting approaches allocated analytical priority to diagnostic instruments and surgical robotics based on capital intensity differential and replacement velocity variance across the projection horizon. Product type, technology modality, end-user procurement authority, and application procedure volume dimensions structured the modeling framework. CAGRs were derived from trend extrapolation of historical deployment rates adjusted for regulatory pathway compression effects and AI diagnostic integration penetration curves.
Underlying measurement precision varies by segment; diagnostic instruments and surgical robotics carry tighter precision than contact lens consumables given more transparent procurement records. Forecasts reflect assumptions on TGA regulatory alignment continuity, silicone hydrogel polymer supply stability, and private clinic expansion velocity in southeastern states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Nystagmus Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Light Therapy Glasses Market