
 Allergy Relieving Eye Drops Market | 2026-2036
Allergy Relieving Eye Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy Relieving Eye Drops Market Outlook
Subscription-based auto-refill programs for chronic allergy sufferers is realigning how manufacturers secure recurring revenue beyond initial pharmacy transactions. Alcon leverages its direct-to-patient digital platforms to sustain repeat purchase loyalty across seasonal cycles. Johnson & Johnson anchors retail shelf presence through pharmacy chain exclusivity agreements that control point-of-sale visibility.
Allergy relieving eye drops are sterile aqueous ophthalmic solutions containing antihistamines, mast cell stabilizers, or vasoconstrictors, formulated at pH 6.5-7.5 with osmolality matched to tear film physiology, designed to interrupt histamine-mediated conjunctival inflammation and provide rapid symptomatic relief. Combination drops that merge antihistamine activity with mast cell stabilization now command the deepest margin pools as clinicians prefer single-bottle simplicity for moderate-to-severe allergic conjunctivitis. Pharmacy chains as a distribution channel dominate volume throughput, though e-commerce is capturing the fastest growth among younger demographics seeking price transparency and home delivery convenience.
The FDA ophthalmic monograph governs active ingredient safety and labeling for OTC allergy drops in the United States, while the EMA's MDR framework imposes stricter clinical evidence requirements on preservative-free formulations entering European markets. These dual regulatory architectures shape R&D allocation, with manufacturers prioritizing benzalkonium chloride-free formulations to preempt compliance friction across jurisdictions. Stakeholders must monitor how pharmacovigilance databases flag emerging hypersensitivity signals, as regulatory response timelines will determine which preservative systems retain market access.
Market Dynamics
Preservative-free formulation migration is compressing legacy benzalkonium chloride supply chains while forcing manufacturers to rebuild sterile manufacturing infrastructure around single-dose vial systems and multi-dose bottle technologies that exclude traditional antimicrobial agents.
Growth Catalysts
- Pollen index volatility:Managed care plans in the United States are accelerating prescription-to-OTC switching behaviors as seasonal allergen severity strains specialty ophthalmology appointment capacity.
- EMA MDR framework:Stricter clinical evidence requirements for preservative-free formulations in European markets are creating compliance moats that favor established sterile manufacturers with dedicated ophthalmic filling lines.
- Direct-to-patient platforms:Digital auto-refill programs for chronic sufferers are expanding recurring revenue capture beyond initial pharmacy transactions through subscription lock-in across seasonal cycles.
Market Restraints
- Active ingredient purity thresholds:The FDA's updated OTC ophthalmic monograph reformulation is tightening manufacturing specifications and disqualifying legacy active pharmaceutical ingredient suppliers lacking analytical capability upgrades.
- Single-dose vial cost structure:Polypropylene blow-fill-seal unit packaging carries 3-4x per-dose cost versus multi-dose bottles, compressing margin pools in price-sensitive retail channels.
- Substitution by intranasal antihistamines:Fluticasone and azelastine nasal sprays are capturing ocular symptom relief demand among patients seeking single-product convenience for rhinoconjunctivitis clusters.
Strategic Opportunities
- Pediatric formulary expansion:Children's ophthalmology clinics are broadening preservative-free antihistamine inclusion, creating dedicated SKU demand with premium pricing tolerance from parent purchasers.
- E-commerce channel maturation:Pharmacy chain websites and pure-play health platforms are capturing younger demographic volume through price transparency tools and subscription bundling with contact lens solutions.
- Combination mechanism convergence:Antihistamine-mast cell stabilizer single-bottle formulations are commanding clinician preference for moderate-to-severe allergic conjunctivitis, displacing dual-bottle regimens.
Industry Challenges
- Sterile manufacturing talent scarcity:Aseptic processing engineers and ophthalmic formulation chemists command premium compensation as FDA warning letter activity tightens around particulate control.
- Pharmacovigilance signal monitoring:Hypersensitivity reporting databases require dedicated regulatory affairs bandwidth to preempt preservative system access restrictions across dual jurisdiction architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy Relieving Eye Drops Market |
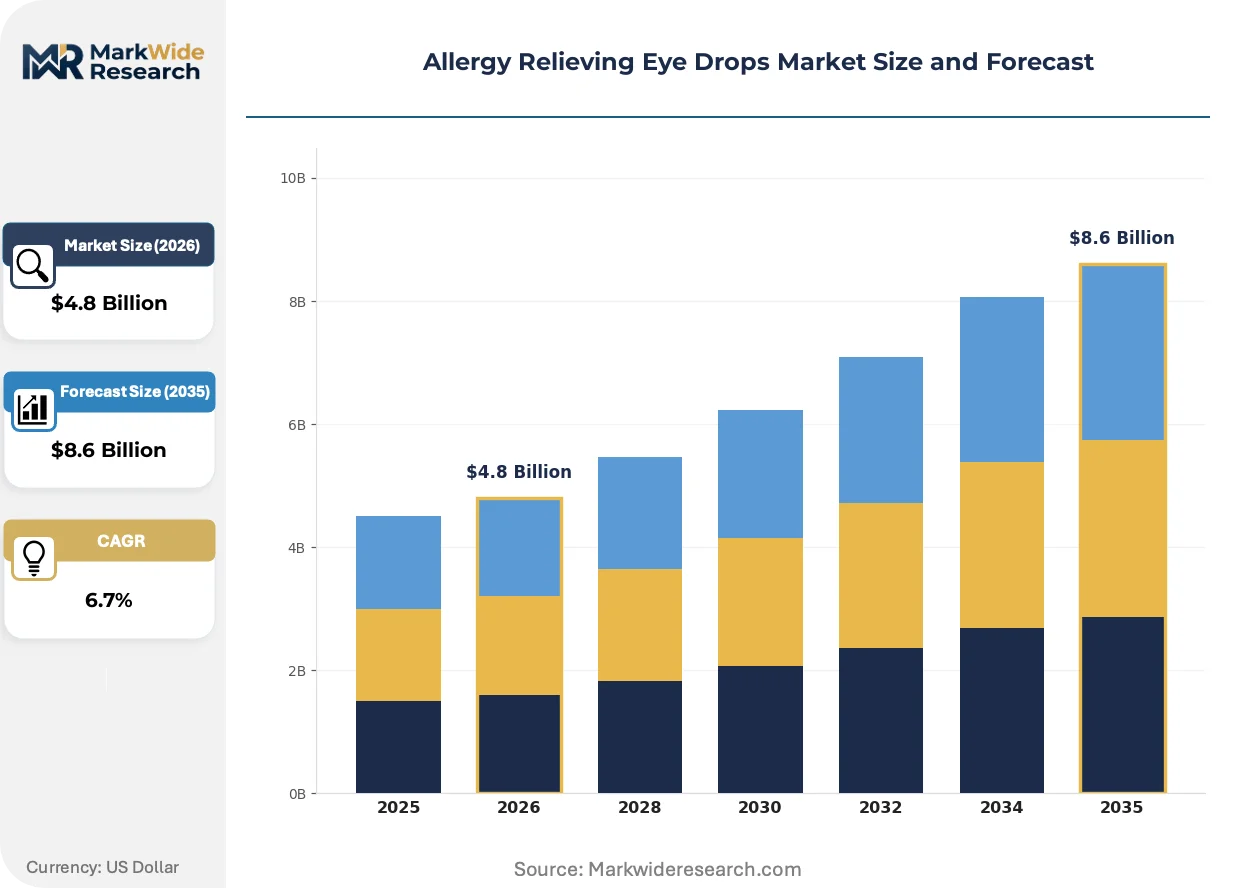
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Decongestants, Mast Cell Stabilizers, Combination Drops Application: Seasonal Allergies, Perennial Allergies, Contact Lens Related, Eye Irritation End User: Retail Consumers, Hospitals, Pharmacies, Online Shoppers Distribution Channel: Direct Sales, E-commerce, Wholesale, Pharmacy Chains |
| Companies Covered | Santen Pharmaceutical, Alcon, AbbVie, F. Hoffmann-La Roche, Pfizer, Johnson & Johnson, Novartis, Regeneron Pharmaceuticals, Bausch Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy Relieving Eye Drops Market Strategic Shifts
Formulation science and distribution architecture are diverging from legacy ophthalmic paradigms as manufacturers confront the technical complexity of antimicrobial-free preservation alongside channel fragmentation between retail pharmacy and direct fulfillment models.
Polyquaternium-1 and sodium perborate oxidative preservation systems are expanding into multi-dose bottle designs that maintain sterility without benzalkonium chloride's epithelial toxicity profile. Pediatric ophthalmology practices and contact lens wearers are adopting these alternatives at accelerating rates. The technology is expanding into premium tier positioning that commands 25-40% price elevation over conventional formulations.
The FDA ophthalmic monograph reformulation process is compressing OTC active ingredient approval timelines while elevating stability data requirements. Manufacturers are reallocating R&D budgets toward accelerated aging studies and forced degradation protocols. United States market entrants face the steepest compliance curve as the agency finalizes purity threshold guidance.
Younger allergy sufferers are bypassing pharmacy counter intermediation through direct-to-patient digital platforms that bundle auto-refill scheduling with telehealth symptom triage. Retail chain exclusivity agreements are losing grip on point-of-sale visibility as search-engine price comparison tools erode shelf-space leverage. This behavioral pivot concentrates fastest in United States metropolitan markets with same-day delivery infrastructure density.
Allergy Relieving Eye Drops Market Segmentation
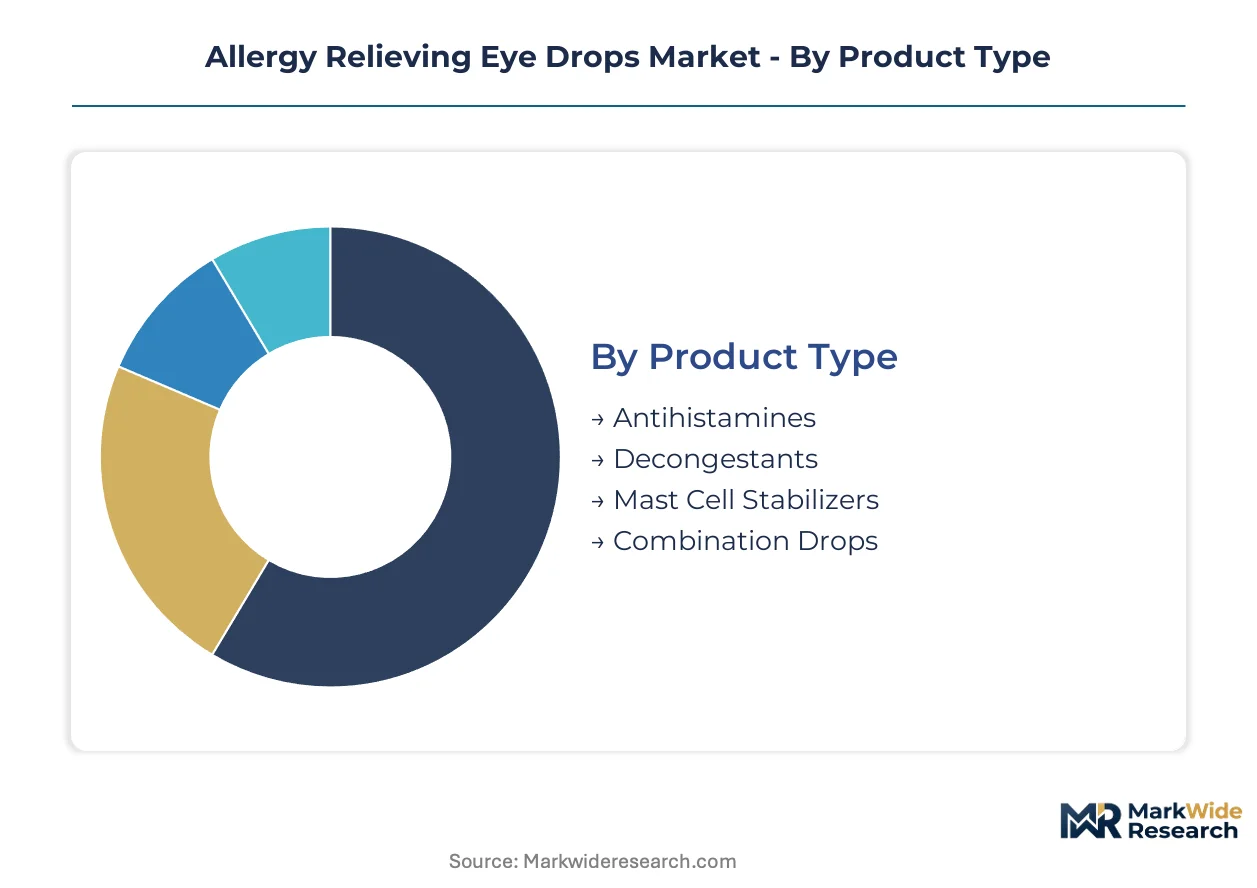
Product differentiation in allergy relieving eye drops hinges on mechanism specificity, preservative architecture, and dosing convenience. Manufacturers calibrate portfolios across these axes to capture distinct patient severity profiles and purchasing behaviors.
Product Type:
Standardization dominates antihistamine formulations, while customization intensity escalates through combination mechanisms and preservative-free variants.
- Antihistamines:First-generation H1 receptor antagonists like ketotifen and olopatadine interrupt histamine-mediated vasodilation within minutes of instillation. Managed care plans in the United States favor these for prescription-to-OTC switching protocols as seasonal pollen indices strain ophthalmology appointment capacity.
- Combination Drops:Dual-mechanism formulations merge antihistamine activity with mast cell stabilization in single-bottle regimens, commanding clinician preference for moderate-to-severe allergic conjunctivitis. Pediatric ophthalmology clinics and contact lens wearers drive premium pricing tolerance for these simplified therapeutic approaches.
- Decongestants:Vasoconstrictor-based redness relief carries rebound hyperemia risks that limit chronic use duration.
- Mast Cell Stabilizers:Cromolyn sodium and lodoxamide tromethamine require pre-season loading periods, constraining acute symptom adoption.
Leading the category by volume: Antihistamines. Growing fastest: Combination Drops.
Application:
Volume concentration aligns with allergen exposure patterns, while margin pools concentrate in chronic and iatrogenic indications requiring sustained therapeutic relationships.
- Seasonal Allergies:Pollen-driven acute episodes generate the highest absolute prescription volumes, with ragweed and grass allergen peaks in North American and European markets driving predictable demand surges. Auto-refill subscription programs capture recurring revenue by locking patient loyalty across annual cycles.
- Perennial Allergies:Dust mite and pet dander sensitization demands year-round prophylaxis, creating stable baseline consumption that resists seasonal volatility. Parents of pediatric patients demonstrate premium pricing tolerance for preservative-free formulations in this chronic management context.
- Contact Lens Related:Giant papillary conjunctivitis and solution sensitivity drive specialty formulation demand among silicone hydrogel wearers.
- Eye Irritation:Non-allergic triggers including dry eye overlap and environmental pollutants expand addressable market boundaries.
Dominant by prescription volume: Seasonal Allergies. Steepest expansion trajectory: Perennial Allergies.
End User:
Purchasing authority fragmentation separates clinical decision-makers from retail self-selectors, with reimbursement status determining channel economics.
- Retail Consumers:Self-directed OTC purchases dominate unit volume, with pharmacy chain shelf placement and direct-to-patient digital platforms competing for point-of-decision influence. Younger demographics bypass traditional intermediation through e-commerce price comparison tools.
- Pharmacies:Pharmacist counseling intermediation shapes brand selection in managed care networks with formulary restrictions.
- Hospitals:Emergency department and ambulatory surgery center formulary inclusion requires sterile manufacturing documentation and lot traceability systems.
- Online Shoppers:Subscription bundling with contact lens solutions and same-day delivery infrastructure concentrates in United States metropolitan markets.
Highest transaction frequency: Retail Consumers. Fastest channel shift: Online Shoppers.
Distribution Channel:
Physical inventory carrying costs versus digital fulfillment speed tradeoffs are restructuring last-mile economics for preservative-sensitive formulations.
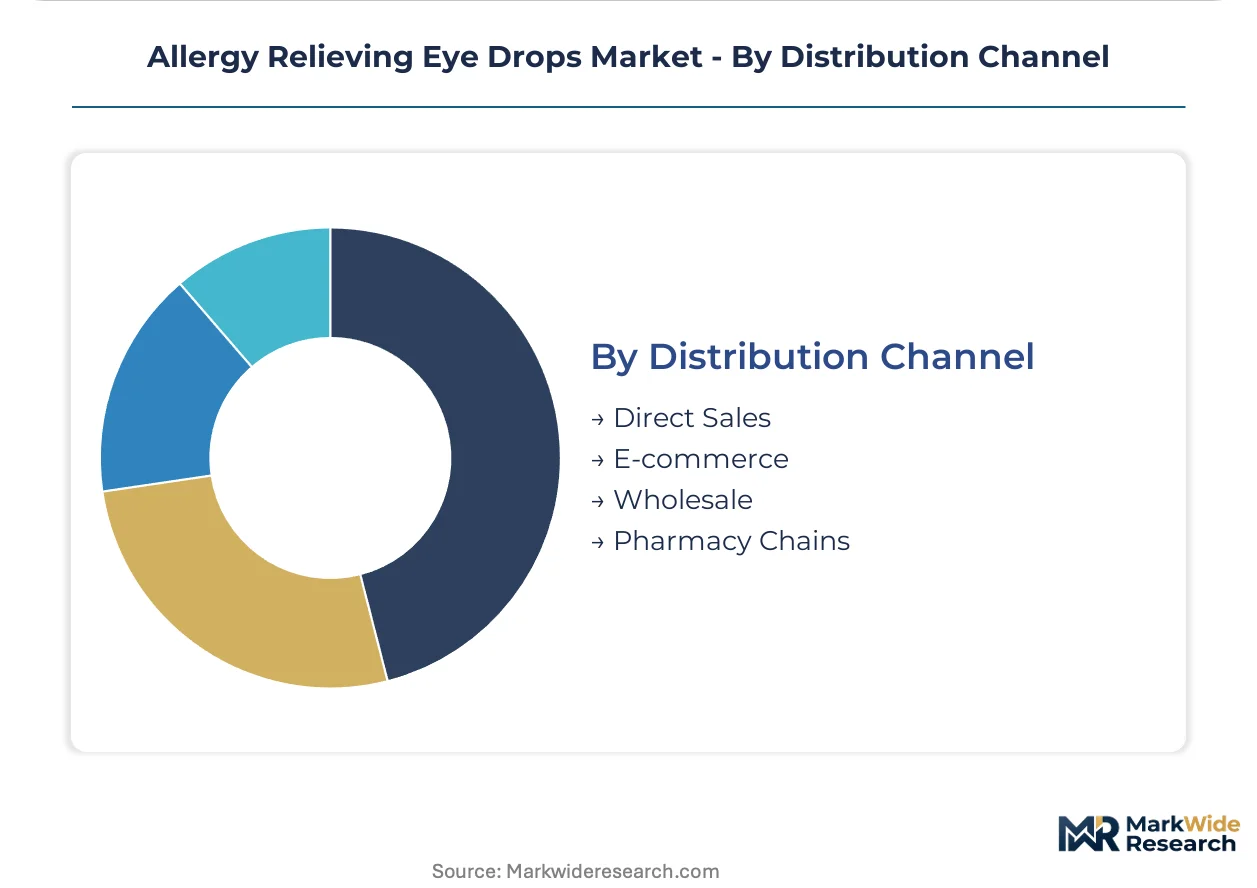
- Pharmacy Chains:CVS, Walgreens, and Rite Aid control United States point-of-sale visibility through exclusivity agreements that secure prime shelf positioning. Cold chain requirements for preservative-free single-dose vials strain inventory turnover metrics in these high-rent retail environments.
- E-commerce:Amazon, 1-800 Contacts, and pure-play health platforms capture younger demographic volume through subscription bundling and telehealth symptom triage integration.
- Direct Sales:Manufacturer-owned digital platforms bypass wholesale markups while capturing patient adherence data.
- Wholesale:McKesson and Cardinal Health distribute to independent pharmacies and institutional accounts with consolidated purchasing power.
Controlling current volume: Pharmacy Chains. Expanding most quickly: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Switzerland, Germany, and Japan where sterile ophthalmic filling infrastructure commands regulatory premiums, while consumption tilts toward the United States and Western European markets with elevated seasonal allergen exposure and managed care switching behaviors.
United States
Pollen index volatility and prescription-to-OTC switching by managed care plans drive volume concentration. FDA ophthalmic monograph reformulation tightens active ingredient purity thresholds, disqualifying legacy suppliers. Research Triangle Park and Boston-Worcester corridor host sterile manufacturing clusters where blow-fill-seal capacity expands.
Germany
EMA MDR framework compliance creates moats favoring established sterile manufacturers. Federal Institute for Drugs and Medical Devices enforces stricter clinical evidence requirements for preservative-free formulations. Baden-Württemberg and Bavaria concentrate ophthalmic contract manufacturing organizations serving pan-European distribution.
Japan
Contact lens wearer density and hay fever prevalence sustain per-capita consumption leadership. Pharmaceuticals and Medical Devices Agency mandates stability data protocols that elevate R&D fixed costs. Osaka-Kobe pharmaceutical cluster specializes in unit-dose vial technologies for premium export markets.
Switzerland
Specialty chemical and sterile formulation expertise anchors high-margin preservative-free production. Swissmedic maintains alignment with EMA MDR while offering accelerated review pathways for novel preservation systems. Basel region concentrates ophthalmic R&D headquarters of multinational pharmaceutical groups.
India
Domestic allergic rhinitis prevalence and expanding private pharmacy chains drive volume growth. Central Drugs Standard Control Organization harmonizes with ICH stability guidelines for export-oriented manufacturers. Hyderabad and Ahmedabad clusters scale benzalkonium chloride-free filling lines for regulated market access.
Allergy Relieving Eye Drops Market Competitive Environment
Top-tier vendors anchor premium preservative-free and combination-mechanism segments, while mid-tier regional specialists compete on price-sensitive antihistamine commoditization. The vendor base stratifies across three archetypes: integrated pharmaceutical conglomerates with ophthalmic divisions, dedicated eye care pure-plays, and contract development and manufacturing organizations with sterile filling specialization. Dominant competitive moves include pharmacy chain exclusivity agreements controlling point-of-sale visibility and direct-to-patient digital platform investments capturing subscription auto-refill revenue.
Among integrated pharmaceutical conglomerates, Alcon and Novartis exemplify scale-driven positioning with dedicated ophthalmic portfolios spanning prescription and OTC channels. Johnson & Johnson occupies a position bridging consumer health and specialty pharmaceutical segments. Santen Pharmaceutical represents the dedicated eye care pure-play archetype with concentrated R&D allocation toward ocular surface disease.
| Leading Market Players |
|---|
| Santen Pharmaceutical |
| Alcon |
| AbbVie |
| F. Hoffmann-La Roche |
| Pfizer |
| Johnson & Johnson |
| Novartis |
| Regeneron Pharmaceuticals |
| Bausch Health |
| Others |
Value Chain & Pricing Dynamics
Benzalkonium chloride feedstock costs propagate through three-tier pricing structure across premium, standard, and economy levels, with polypropylene single-dose vial packaging commanding 25-40% elevation over multi-dose alternatives as sterile filling capacity bottlenecks in Switzerland and Germany constrain downstream volume.
Pricing Analysis
Margin tightening in preservative-free tiers reflects blow-fill-seal equipment scarcity and aseptic engineer premium compensation. Price differentiation separates benzalkonium chloride-based economy formulations from polyquaternium-1 stabilized premium SKUs, with pediatric ophthalmology clinics demonstrating lowest price sensitivity due to parent-driven safety preferences. Cost-down pressure on standard antihistamine commoditization accelerates because managed care prescription-to-OTC switching protocols narrow reimbursement coverage.
Supply Chain Analysis
Direct-to-patient digital platforms handle chronic sufferer auto-refill demand, while pharmacy chains manage acute seasonal surges through exclusivity-governed shelf positioning. Supply concentrates in Switzerland, Germany, and Japan where sterile ophthalmic filling infrastructure draws from specialized polymer suppliers and purified active pharmaceutical ingredient manufacturers. Single-source vulnerability permeates polypropylene blow-fill-seal vial sourcing as FDA warning letter activity tightens around particulate control standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile manufacturing talent scarcity props pricing power across preservative-free segments, with aseptic processing engineer availability constraining capacity expansion timelines regardless of capital deployment.
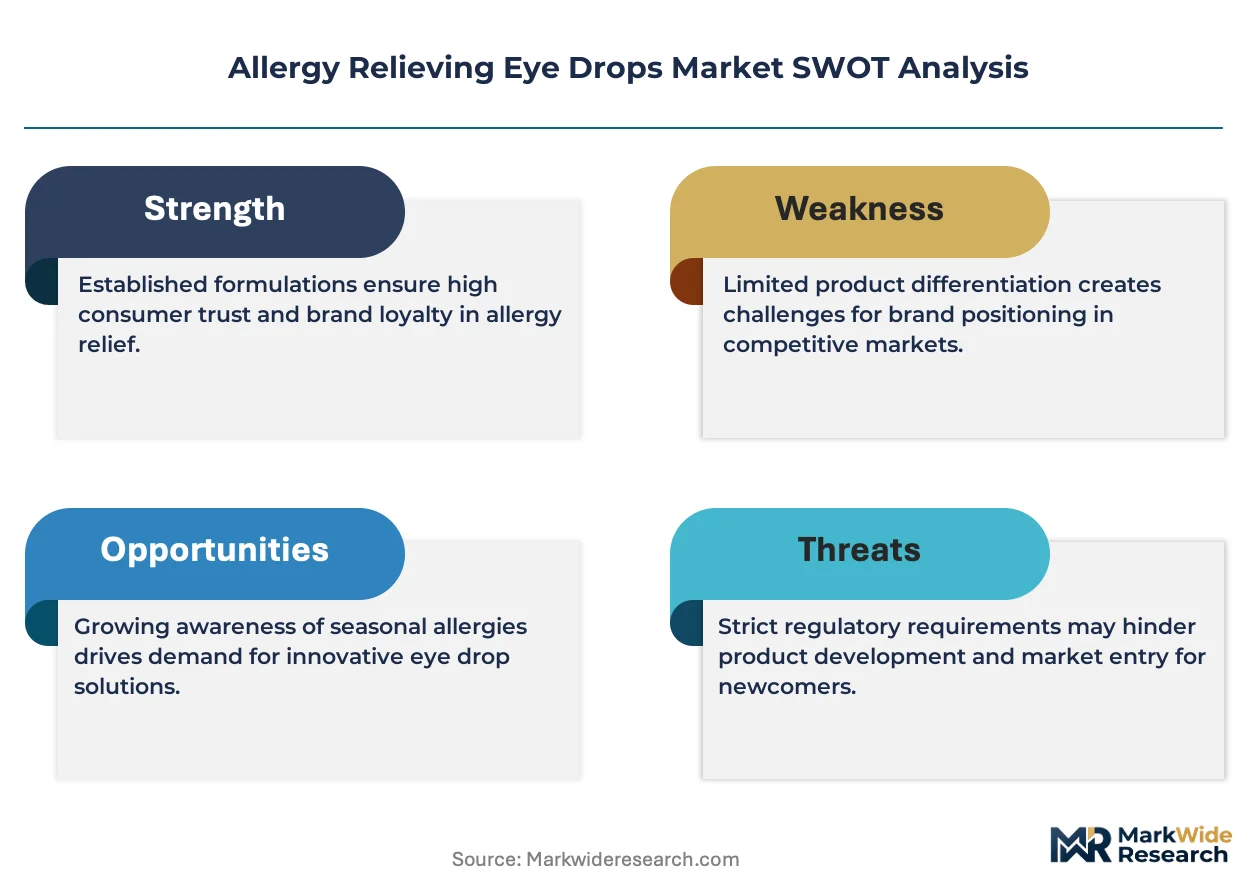
For Market Incumbents: To counter intranasal antihistamine substitution by fluticasone and azelastine nasal sprays, anchor formulary position through pharmacy chain exclusivity agreements controlling point-of-sale visibility, and deepen backward integration into polyquaternium-1 preservation chemistry to preempt regulatory friction across FDA and EMA jurisdictions. For New Entrants and Emerging Players: Begin with pediatric preservative-free antihistamine SKUs as the most penetrable white-space target, leveraging parent purchaser premium pricing tolerance and children's ophthalmology clinic formulary expansion trends; deploy telehealth symptom triage integration as the go-to-market angle to bypass retail shelf intermediation. For Investors and Strategic Acquirers: FDA ophthalmic monograph reformulation finalization is the leading indicator that active ingredient purity threshold compliance will separate viable acquisition targets from stranded legacy suppliers; prioritize sterile manufacturing organizations with dedicated ophthalmic filling lines and existing EMA MDR documentation over the mid-term horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Migration | Polyquaternium-1 and sodium perborate systems command 25-40% price premiums in pediatric and contact lens wearer segments. |
| Direct-to-Patient Platform Investment | Alcon's digital auto-refill programs capture recurring revenue across seasonal pollen cycles in United States metropolitan markets. |
| Pharmacy Chain Exclusivity Agreement | Johnson & Johnson's CVS and Walgreens shelf positioning controls point-of-sale visibility against e-commerce price transparency erosion. |
| EMA MDR Compliance Certification | Stricter clinical evidence requirements for preservative-free formulations create compliance moats favoring established sterile manufacturers. |
| Combination Mechanism R&D Allocation | Antihistamine-mast cell stabilizer single-bottle formulations displace dual-bottle regimens in moderate-to-severe allergic conjunctivitis. |
Study Parameters
Multi-period observation of seasonal pollen indices, prescription-to-OTC switching protocols, and sterile manufacturing capacity utilization anchored the trend analysis, supplemented by interviews with ophthalmic formulation chemists, aseptic processing engineers, pharmacy chain formulary directors, and pediatric ophthalmology clinic administrators. Secondary validation drew from FDA ophthalmic monograph filings, EMA MDR submission databases, ClinicalTrials.gov stability study registrations, and pharmacy benefit manager formulary restriction announcements. Bottom-up patient volume modeling and top-down pharmaceutical manufacturer revenue triangulation converged on segment-level estimates.
Input-output matrices mapped active pharmaceutical ingredient purity grades through finished product pricing tiers across mechanism type, preservative architecture, and distribution channel dimensions over the projection horizon. CAGRs were derived from segmented demand elasticity modeling against pollen index volatility and managed care reimbursement policy trajectories. Forecast inputs incorporated sterile filling line capacity expansion announcements and regulatory affairs bandwidth allocation patterns.
Underlying measurement precision varies by segment; preservative-free and combination mechanism categories carry tighter precision than commoditized antihistamine standard formulations due to concentrated manufacturer disclosure. Forecasts reflect assumptions around EMA MDR enforcement consistency and FDA monograph reformulation timelines, with pharmacovigilance hypersensitivity signal emergence representing a specific risk factor that could revise access restrictions across jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Ophthalmic Devices Market