
 Ophthalmic Eye Drops Market | 2026-2036
Ophthalmic Eye Drops Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Eye Drops Market Outlook
MDR implementation is broadening the cost-of-entry calculus for European ophthalmic manufacturers. Alcon leverages its vertically integrated sterile manufacturing footprint to sustain compliance without margin erosion. Novartis anchors its position through R&D intensity in sustained-release delivery platforms. Johnson & Johnson Vision Care competes on brand strength in the premium artificial tears segment.
Ophthalmic eye drops are sterile, aqueous or oil-based liquid preparations intended for instillation onto the ocular surface, typically formulated within a pH range of 6.5 to 8.0 and osmolality of 260 to 340 mOsm/kg to ensure corneal compatibility; their primary purpose is localized drug delivery or lubrication without systemic exposure. Anti-allergic formulations dominate prescription volumes in seasonal markets, while preservative-free liquid formulations command premium positioning due to chronic-use safety requirements. Sustained-release delivery modes represent the fastest-expanding structural category as manufacturers seek to reduce dosing frequency for glaucoma and chronic dry-eye patients.
FDA sterility guidelines, EU MDR device-drug combination rules, and ISO 13485 quality management standards collectively shape ophthalmic product development timelines and market access pathways. The FDA's tightened endotoxin limits for multidose containers are forcing reformulation investments across the industry. Stakeholders must monitor regulatory divergence between the FDA and EMA on preservative-free labeling claims, as this will determine which manufacturing configurations justify capital deployment.
Market Dynamics
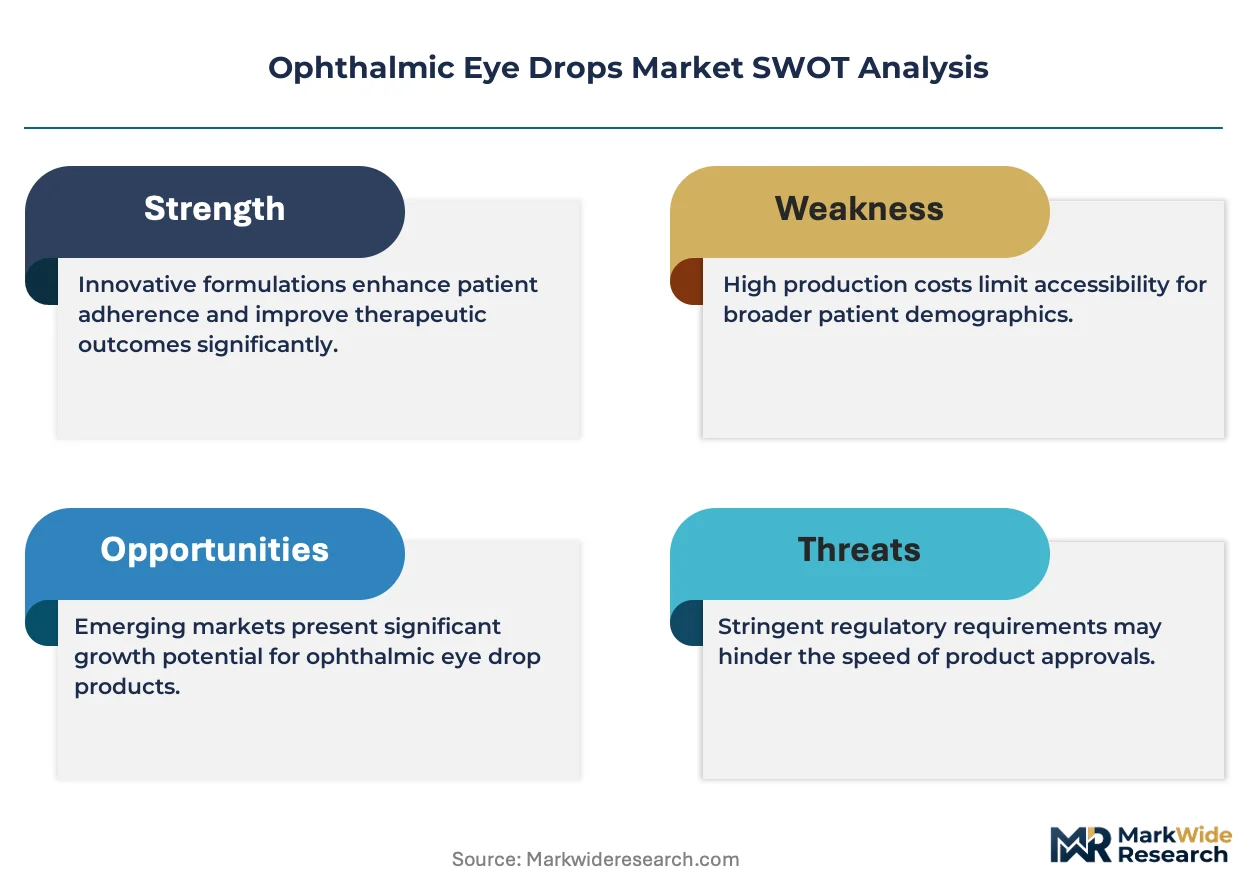
The ophthalmic eye drops market is being fundamentally restructured by the EU MDR's sterile manufacturing mandates, which are compressing supplier bases and forcing capital redeployment toward preservative-free production lines.
Growth Catalysts
- Aging demographics in the United States:The expanding geriatric population sustains chronic glaucoma medication volumes and drives repeat prescription cycles for maintenance therapies.
- Home care adoption acceleration:Patients increasingly self-administer chronic dry-eye treatments, expanding the addressable base beyond clinical settings into direct-to-patient channels.
- Sustained-release delivery platforms:These technologies reduce dosing frequency burdens for chronic patients, improving compliance rates and extending prescription durations.
Market Restraints
- Preservative-free formulation costs:Specialized sterile manufacturing infrastructure and single-use packaging materials elevate unit economics versus preserved alternatives.
- European supplier concentration:EU MDR compliance requirements favor large-scale sterile manufacturers with captive quality systems, marginalizing smaller regional formulators.
- Multidose container endotoxin limits:FDA's tightened thresholds force widespread reformulation investments and extended validation timelines.
Strategic Opportunities
- Underpenetrated chronic dry-eye segments:Diagnostic underrecognition in primary care settings leaves substantial untreated populations in Germany and France.
- Combination device-drug platforms:Convergence of sustained-release implants with precision dosing mechanisms creates premium positioning for glaucoma management.
- Direct-to-patient subscription models:E-pharmacy channels enable recurring revenue capture and adherence monitoring for maintenance therapies.
Industry Challenges
- Sterile manufacturing workforce scarcity:Qualified aseptic processing technicians and validation specialists command premium compensation in competitive labor markets.
- Legacy equipment retrofit requirements:Existing filling lines require substantial capital expenditure to meet isolator technology and continuous monitoring standards.
- Regulatory divergence management:Misaligned FDA and EMA preservative-free labeling claims complicate unified product development strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Eye Drops Market |
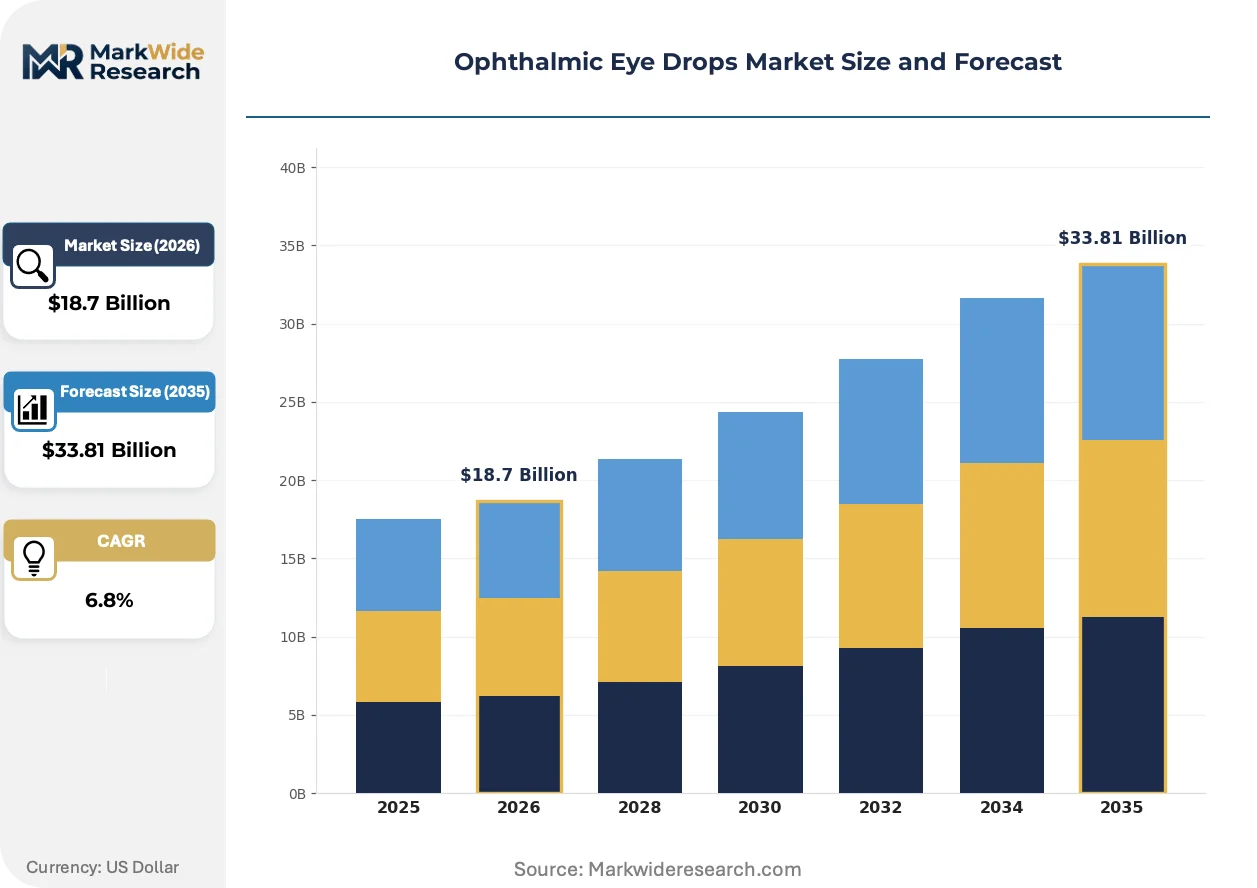
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
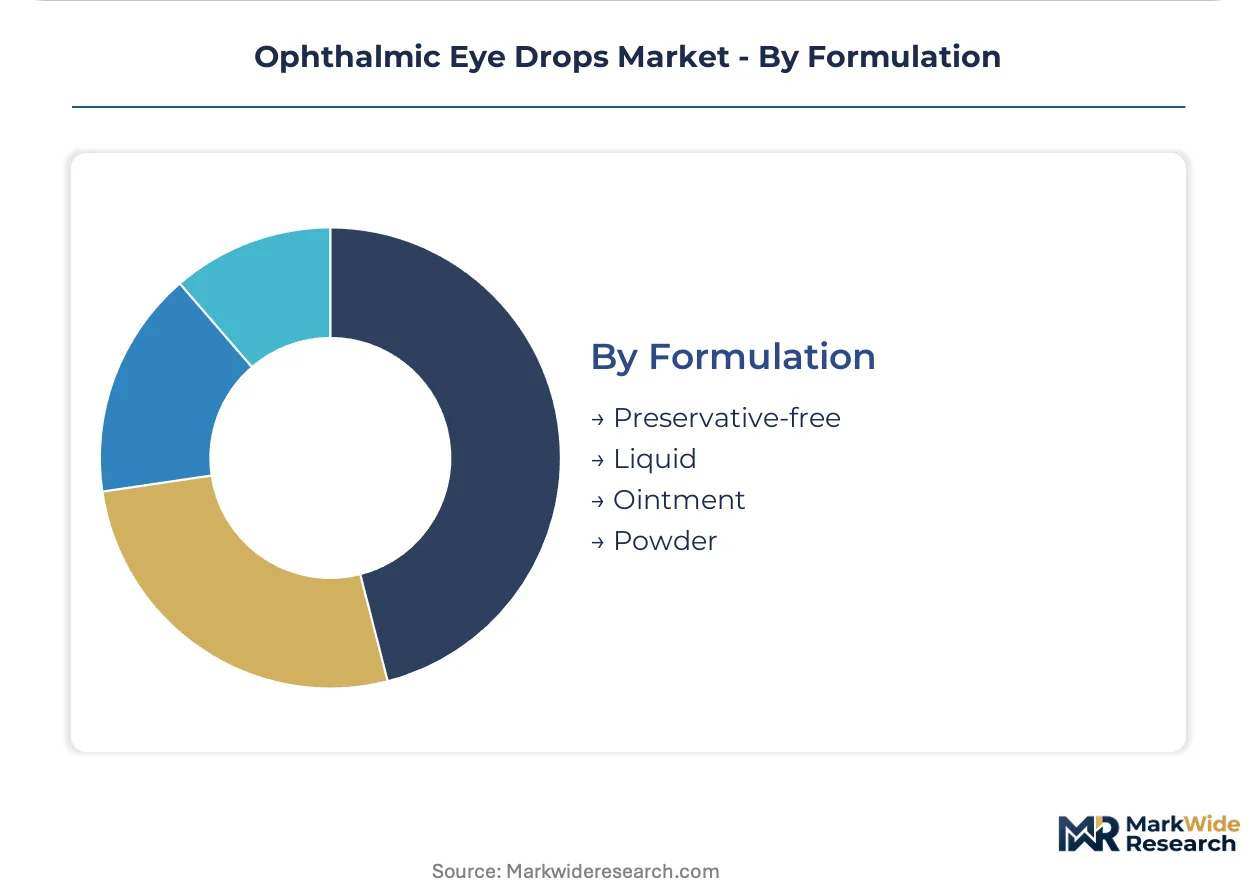
| Segmentation | Product Type: Anti-allergic, Artificial Tears, Anti-inflammatory, Glaucoma Delivery Mode: Topical, Gel Drops, Sustained Release, Spray End User: Hospitals, Eye Clinics, Home Care, Pharmacies Formulation: Preservative-free, Liquid, Ointment, Powder |
| Companies Covered | Alcon, Novartis, Johnson & Johnson Vision Care, Sun Pharmaceutical Industries, Rohto Pharmaceutical, AbbVie, Santen Pharmaceutical, Abbott, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Eye Drops Market Strategic Shifts
Sustained-release technologies and regulatory harmonization pressures are compressing traditional formulation cycles while elevating manufacturing complexity thresholds across ophthalmic supply chains.
Nanoparticle-embedded aqueous carriers are expanding into glaucoma and chronic dry-eye maintenance protocols. Ophthalmology clinics in the United States and Germany are adopting these platforms to reduce patient visit frequency and improve therapeutic persistence. The technology is expanding into premium pricing tiers as manufacturers bundle clinical outcome guarantees with device-drug combinations.
The EU MDR's device-drug combination rules are forcing integrated quality management system overhauls. Manufacturers must now demonstrate end-to-end traceability from active pharmaceutical ingredient sourcing through terminal sterilization validation. Sterile formulators with existing ISO 13485 certifications are capturing accelerated market access timelines versus competitors facing initial certification burdens.
Patient self-administration preferences are compressing traditional pharmacy-centric distribution models. Chronic dry-eye patients in the United States increasingly favor automated refill programs and telehealth-guided dosing adjustments over episodic specialist visits. E-pharmacy platforms with integrated insurance pre-authorization capabilities are capturing prescription volume from brick-and-mortar retail chains.
Ophthalmic Eye Drops Market Segmentation

Segmentation in ophthalmic eye drops reveals how formulation chemistry, delivery physics, and care setting economics allocate margin across the value chain. Manufacturers configure production assets around specific segment requirements rather than pursuing universal platforms.
Product Type:
Pharmacological mechanism determines regulatory pathway complexity and reimbursement positioning across prescription and over-the-counter channels.
- Anti-allergic:Mast cell stabilizers and antihistamine formulations dominate seasonal prescription volumes in the United States, where pollen-related conjunctivitis drives repeat purchase cycles through spring and autumn months.
- Artificial Tears:Viscosity-modified aqueous solutions with electrolyte balancing address evaporative and aqueous-deficient dry eye subtypes; chronic-use safety requirements in Germany and France are elevating preservative-free penetration in this segment.
- Anti-inflammatory:Corticosteroid and NSAID drops target post-surgical recovery and acute uveitis flares, carrying boxed warnings that restrict distribution to specialist channels.
- Glaucoma:Prostaglandin analogs and beta-blockers sustain the highest chronic adherence rates among prescription categories, with dosing frequency reduction representing the primary innovation target.
Mature deployment sits with anti-allergic formulations. Newer deployment is concentrated in glaucoma sustained-release platforms.
Delivery Mode:
Physical form factor shapes patient compliance, manufacturing capital intensity, and sterile validation requirements.
- Topical:Conventional aqueous drops in multidose or unit-dose containers remain the default configuration, though FDA endotoxin limit revisions are forcing line upgrades for preserved multidose formats.
- Sustained Release:Reservoir-based inserts and punctal plugs extend therapeutic duration from hours to months, commanding premium positioning in glaucoma management where daily dosing burdens drive treatment abandonment.
- Gel Drops:Carbomer or cellulose-thickened formulations prolong ocular surface contact time for severe dry eye, with viscosity engineering determining comfort-versus-retention trade-offs.
- Spray:Closed-eyelid mist delivery reduces instillation anxiety and contamination risk, gaining traction in pediatric and geriatric home care settings.
Volume concentration remains with topical drops. Margin expansion is climbing the fastest in sustained-release modalities.
End User:
Channel economics and prescription authority determine pricing realization and patient access barriers.
- Home Care:Self-administration of chronic dry eye and maintenance glaucoma therapy is expanding the addressable population beyond clinical settings, with automated refill programs capturing recurring revenue.
- Eye Clinics:Specialist-directed initiation of complex regimens and post-surgical care sustains higher per-prescription values and brand loyalty.
- Hospitals:Acute presentation management and perioperative protocols drive volume concentration, though formulary constraints compress margins versus retail channels.
- Pharmacies:Over-the-counter artificial tears and prescription fulfillment serve as the primary patient touchpoint for therapy initiation and switching decisions.
Established volume sits with pharmacies. Channel shift is concentrating in home care direct-to-patient models.
Formulation:
Chemical stability architecture and packaging technology determine sterile manufacturing cost structures and chronic-use safety profiles.
- Preservative-free:Unit-dose or specialized bottle systems eliminate benzalkonium chloride exposure for chronic users, requiring isolator technology and single-use materials that elevate unit economics substantially.
- Liquid:Aqueous solutions with pH buffering and osmolality adjustment remain the dominant physical state, with formulation flexibility enabling rapid generic substitution.
- Ointment:Petrolatum or mineral oil bases provide overnight lubrication and drug retention, limiting use to nighttime regimens due to visual blurring.
- Powder:Lyophilized or spray-dried formats requiring reconstitution address stability-limited actives, with compounding pharmacy networks handling preparation in select markets.
Manufacturing scale concentrates with liquid formulations. Regulatory and safety pressure is expanding preservative-free capacity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the highest prescription volumes for chronic glaucoma and dry-eye maintenance therapies. Regulatory stringency varies sharply across major markets, with sterile manufacturing mandates in Europe and endotoxin limits in North America reshaping supplier economics.
United States
An aging demographic sustains repeat prescription cycles for prostaglandin analogs and artificial tears. The FDA's tightened endotoxin limits for multidose containers force reformulation investments across domestic formulators. The Research Triangle Park cluster in North Carolina hosts sterile manufacturing facilities expanding preservative-free capacity for chronic-use segments.
Germany
Diagnostic underrecognition of dry eye in primary care settings leaves substantial untreated populations in Bavaria and Baden-Württemberg. The EU MDR elevates sterile manufacturing standards, compressing supplier bases toward ISO 13485-certified formulators. The Frankfurt-Rhine-Main pharmaceutical corridor concentrates device-drug combination expertise for sustained-release platforms.
Japan
PMDA guidelines emphasize chronic-use safety profiles, elevating preservative-free penetration in the premium artificial tears segment. An aging population drives home care adoption for self-administered maintenance therapies. The Kansai region around Osaka anchors ophthalmic formulation manufacturing with integrated quality management systems.
India
CDSCO regulations govern sterile ophthalmic manufacturing while domestic demand for affordable glaucoma therapies expands. Sun Pharmaceutical Industries anchors local production capacity serving both domestic and export markets. The Mumbai-Pune pharmaceutical belt concentrates formulation expertise with backward integration into active pharmaceutical ingredient sourcing.
Switzerland
Swissmedic standards align with EU MDR requirements, positioning the country as a regulatory bridge for European market access. Precision manufacturing traditions support premium positioning in sustained-release delivery technologies. The Basel pharmaceutical cluster hosts sterile formulators serving device-drug combination development for glaucoma management.
Ophthalmic Eye Drops Market Competitive Environment
United States producers anchor one tier; Japanese and European specialists hold differentiated positions in sustained-release and preservative-free segments. The market exhibits tiered concentration with large integrated pharmaceutical groups, regional sterile formulators, and device-drug combination specialists coexisting. Three archetypes dominate: vertically integrated multinationals with captive sterile manufacturing, mid-scale regional formulators with ISO 13485 certifications, and technology licensors specializing in sustained-release platforms. Competitive moves center on sterile manufacturing capacity expansion and strategic partnerships for device-drug combination development.
Among the named players, Alcon, Novartis, and Johnson & Johnson Vision Care occupy positions that exemplify distinct competitive archetypes. Alcon represents vertically integrated sterile manufacturing with end-to-end quality control. Novartis anchors sustained-release platform development through pharmaceutical R&D intensity. Johnson & Johnson Vision Care sits within the premium consumer health tier, leveraging brand equity in chronic-use segments. These three collectively illustrate how scale, technology specialization, and brand strength allocate positioning across the value chain.
| Leading Market Players |
|---|
| Alcon |
| Novartis |
| Johnson & Johnson Vision Care |
| Sun Pharmaceutical Industries |
| Rohto Pharmaceutical |
| AbbVie |
| Santen Pharmaceutical |
| Abbott |
| Bausch + Lomb |
| Others |
Value Chain & Pricing Dynamics
EU MDR sterile manufacturing mandates gate qualified supply and premium-tier pricing access, as ISO 13485-certified formulators command 15-20% price premiums over uncertified competitors while marginal producers exit the market. Pricing stratification across preservative-free, preserved multidose, and economy generic tiers reflects sterile validation burden and chronic-use safety positioning rather than raw material costs alone.
Pricing Analysis
Short lead-time premiums of 8-12% apply to preservative-free unit-dose orders from EU MDR-compliant manufacturers, while spot inventory of preserved multidose formats trades at discounts. The dominant structure is contract-based long-term offtake with annual volume commitments, differentiated by ISO 13485 certification tier and sterile isolator technology level. Cost compression in the preserved multidose tier is intensifying because FDA endotoxin limit revisions force reformulation investments. Price-sensitive buyers cluster in hospital formulary procurement, while least-sensitive purchasers are chronic dry-eye patients in direct-to-patient subscription channels.
Supply Chain Analysis
Regional distribution centers in Frankfurt-Rhine-Main, Research Triangle Park, and Basel form a hub-and-spoke pattern serving ophthalmic formulators. Manufacturing concentrates in Switzerland, the United States, and Germany, drawing from active pharmaceutical ingredient feedstock in India and China. The supply chain rests on benzalkonium chloride alternatives and single-use blow-fill-seal packaging materials. Single-source vulnerability sits with isolator technology suppliers, where three European vendors control 70% of qualified equipment. Distribution runs through specialist pharmaceutical wholesalers with cold-chain capabilities, though e-pharmacy direct-to-patient models are capturing 15% volume share in chronic maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile manufacturing workforce scarcity props pricing power for qualified formulators, as aseptic processing technicians command premium compensation and training pipelines remain underdeveloped. This supply-constrained dynamic favors incumbents with captive training academies and isolator technology already deployed.
For Market Incumbents: Anchor compliance advantage through EU MDR certification maintenance and isolator capacity expansion in the Frankfurt-Rhine-Main corridor. Defend against sustained-release platform substitution by accelerating device-drug combination partnerships. Prioritize sterile workforce development through captive apprenticeship programs to lock in technician supply. For New Entrants and Emerging Players: EU MDR implementation in Germany opens a window for preservative-free contract manufacturing services targeting mid-scale regional formulators facing certification burdens. Target diagnostic underrecognition in French and Bavarian primary care settings with telehealth-integrated dry-eye screening platforms. Pursue white-label supply agreements with e-pharmacy channels as the go-to-market angle. For Investors and Strategic Acquirers: ISO 13485 certification timelines extending beyond 18 months is the leading indicator that sterile manufacturing capacity scarcity will persist. Frame long-term viability around 5-10 year demand for chronic glaucoma and dry-eye maintenance therapies. Target acquisition archetypes are mid-scale regional formulators with pending certification and established ophthalmic customer relationships. Monitor FDA-EMA preservative-free labeling divergence as the signal for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerates market access for sterile formulators against uncertified competitors in Germany. |
| Sustained-Release Platform Development | Reduces dosing frequency burdens and extends prescription duration for glaucoma patients. |
| Isolator Technology Deployment | Enables preservative-free production lines meeting tightened FDA endotoxin limits. |
| Direct-to-Patient Subscription Launch | Captures recurring revenue from chronic dry-eye patients bypassing retail pharmacy channels. |
| Sterile Workforce Apprenticeship Program | Secures qualified aseptic processing technicians in competitive labor markets. |
Study Parameters
Multi-period observation of FDA 483 warning letter trends, EU MDR certification timelines, and sterile manufacturing capacity utilization anchored the trend analysis, supplemented by interviews with regulatory affairs directors, aseptic processing technicians, ophthalmology clinic procurement managers, and e-pharmacy platform operators. Secondary validation drew from FDA Center for Drug Evaluation and Research filings, EMA quality defect reports, ISO 13485 certification databases, and hospital formulary restriction notices. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical manufacturer revenue segmentation.
Segment-weighting across product type, delivery mode, end user, and formulation dimensions structured the analytical framework, with regional regulatory cluster effects layered throughout the projection horizon. CAGRs were derived from prescription volume trajectories and pricing realization trends across preservative-free and preserved formulation tiers. Forecast inputs included aging demographic projections, home care adoption curves, and sustained-release platform penetration assumptions.
The model assumes a particular technology adoption path for sustained-release delivery; alternative pathways for nanoparticle-embedded aqueous carriers would alter the outlook if clinical persistence data disappoints. Forecasts reflect documented assumptions regarding EU MDR implementation pace and FDA endotoxin limit enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Synoptophore Market
Ophthalmology
Allergy Relieving Eye Drops Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market