
 Lazy Eye Market | 2026-2036
Lazy Eye Market Size, Share, and Industry Trends Forecast 2026-2036
Lazy Eye Market Outlook
Aftermarket service revenue from vision therapy software subscriptions is narrowing the margin gap with traditional device sales. Novartis leverages its ophthalmology franchise to sustain research pipelines across pharmacological interventions for amblyopia. Vivid Vision competes through specialized virtual reality platforms that anchor digital treatment protocols in clinical workflows. Luminopia differentiates by occupying the pediatric prescription digital therapeutic segment with content-partnership models.
Amblyopia, commonly termed lazy eye, represents a neurodevelopmental vision disorder characterized by reduced visual acuity in one eye due to disrupted binocular input during critical cortical development periods, typically diagnosed through visual acuity testing below age-normative thresholds despite optical correction. The condition demands early intervention to prevent permanent cortical suppression and restore binocular function. Vision therapy tools capture expanding margin pools as digital therapeutics gain prescription status, while patch therapy remains the mature baseline with eroding adherence economics. The children segment anchors volume demand due to neuroplasticity windows, whereas adults represent an emerging addressable population as perceptual learning protocols demonstrate efficacy in older cohorts.
The FDA breakthrough device program and CE marking under the EU MDR create divergent compliance burdens for developers pursuing transatlantic market access, with European notified body backlogs extending certification timelines. The country's national pharmaceutical regulator in Japan evaluates pharmacological amblyopia therapies under orphan drug frameworks that compress review periods for pediatric indications. Stakeholders must monitor reimbursement code creation for digital therapeutics and decide between direct-to-clinic deployment or pharmacy-benefit integration before competitive prescribing patterns solidify.
Market Dynamics
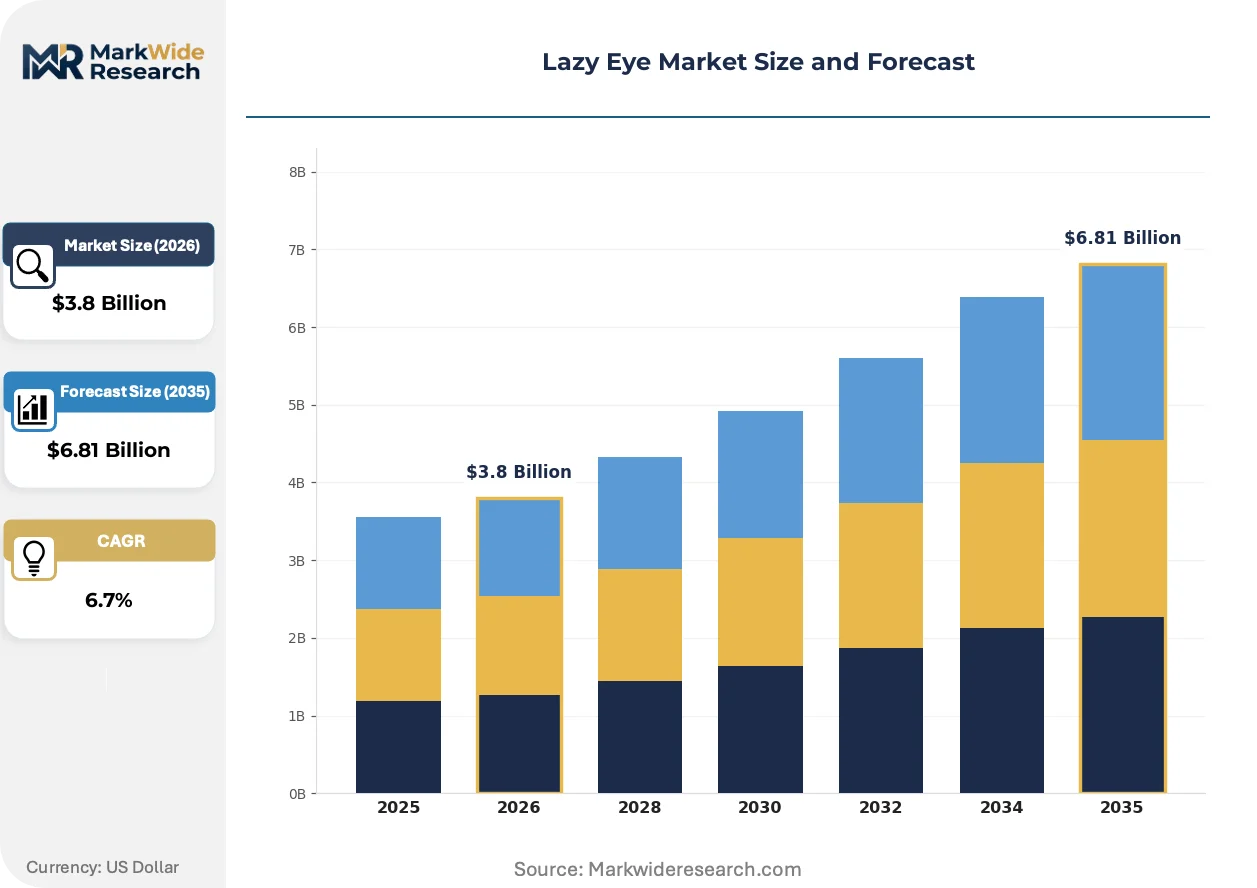
Digital therapeutic platforms are compressing traditional device economics as prescription-grade software claims reimbursement parity with hardware-based vision therapy, forcing incumbents to restructure revenue models around recurring subscriptions rather than one-time capital sales.
Growth Catalysts
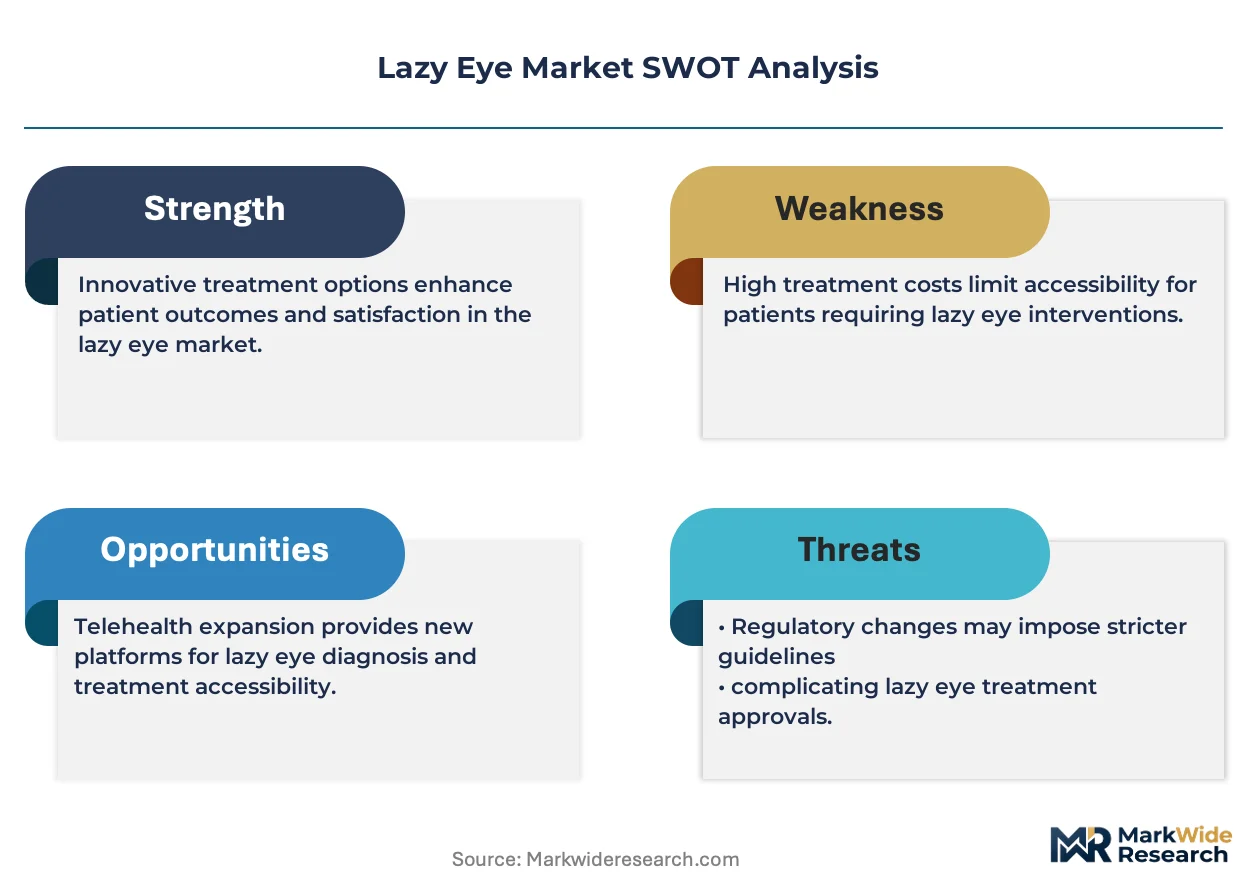
- FDA Breakthrough Device Designation:The accelerated review pathway compresses commercialization timelines for novel amblyopia interventions, reducing regulatory capital requirements for developers targeting pediatric neuroplasticity windows.
- EU MDR CE Marking Convergence:Harmonized safety standards across European notified bodies enable cross-border platform deployment, expanding addressable clinic networks for digital vision therapy providers.
- Perceptual Learning Protocols:Adult neuroplasticity research is extending treatment candidacy beyond traditional age cutoffs, opening incremental volume pools in previously excluded demographic cohorts.
Market Restraints
- Reimbursement Code Fragmentation:Inconsistent CPT and HCPCS coverage for digital therapeutics across US state Medicaid programs creates prescribing friction and delays provider adoption.
- Optical Component Supply Concentration:Specialized VR headset displays and eye-tracking sensors concentrate manufacturing in East Asian electronics clusters, exposing therapy platform margins to input volatility.
- Patch Therapy Substitution Economics:Low-cost occlusion remains the first-line standard in resource-constrained settings, limiting premium digital therapeutic penetration in price-sensitive segments.
Strategic Opportunities
- Japan Orphan Drug Framework:PMDA's compressed review timelines for pediatric indications create regulatory arbitrage for pharmacological amblyopia candidates seeking faster market access than US or EU pathways.
- Pharmacy Benefit Integration:Embedding digital therapeutics within PBM formularies displaces direct-to-clinic sales friction, capturing prescription flow through established retail pharmacy networks.
- Binocular Treatment Convergence:Synthesis of dichoptic gaming with active shutter glasses technology enables at-home compliance monitoring, reducing clinic dependency and expanding rural access.
Industry Challenges
- Pediatric Ophthalmologist Training Bottlenecks:Limited fellowship slots and uneven digital therapeutic certification programs constrain prescriber pool expansion, particularly in non-academic practice settings.
- Legacy EHR Integration Complexity:Vision therapy platforms face interoperability friction with dominant electronic health record systems, requiring costly custom API development for seamless clinical workflow embedding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lazy Eye Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eyeglasses, Contact Lenses, Surgical Devices, Vision Therapy Tools Age Group: Children, Adolescents, Adults, Seniors Treatment Method: Patch Therapy, Optical Treatment, Surgery, Pharmacological Distribution Channel: Online Retail, Optical Stores, Hospitals, Clinics |
| Companies Covered | Novartis, Bausch & Lomb, Vivid Vision, RevitalVision, CooperVision, Johnson & Johnson Vision, Alcon, Luminopia, Good-Lite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lazy Eye Market Strategic Shifts
Prescription digital therapeutics are capturing margin pools historically reserved for hardware devices, while regulatory frameworks race to accommodate software-as-medical-device classification without choking innovation velocity.
Virtual reality-based dichoptic treatment protocols are digitizing the delivery of binocular vision therapy, replacing patch-based occlusion with immersive gaming environments. Pediatric ophthalmology clinics in the United States are adopting these platforms at accelerating cadence as FDA clearance validates clinical efficacy. This shift is digitizing revenue recognition from one-time hardware sales toward recurring software subscriptions, compressing working capital requirements but extending customer lifetime value horizons.
The EU MDR's software classification rules are tightening clinical evidence requirements for vision therapy applications, forcing developers to generate prospective trial data rather than rely on predicate device pathways. European notified body backlogs are extending certification timelines by twelve to eighteen months for novel digital therapeutic submissions. Small-cap developers are responding by sequencing market entry to prioritize US FDA clearance before pursuing CE marking, reversing traditional transatlantic launch patterns.
Parental compliance monitoring through smartphone-connected therapy platforms is displacing clinic-based supervision as the dominant adherence assurance mechanism. Direct-to-consumer channels are capturing prescription flow through telehealth ophthalmology networks, bypassing traditional brick-and-mortar pediatric eye care gatekeepers. This behavioral pivot is most pronounced in the United States, where asynchronous telemedicine regulations and pharmacy benefit manager digital health carve-outs enable remote prescribing at scale.
Lazy Eye Market Segmentation
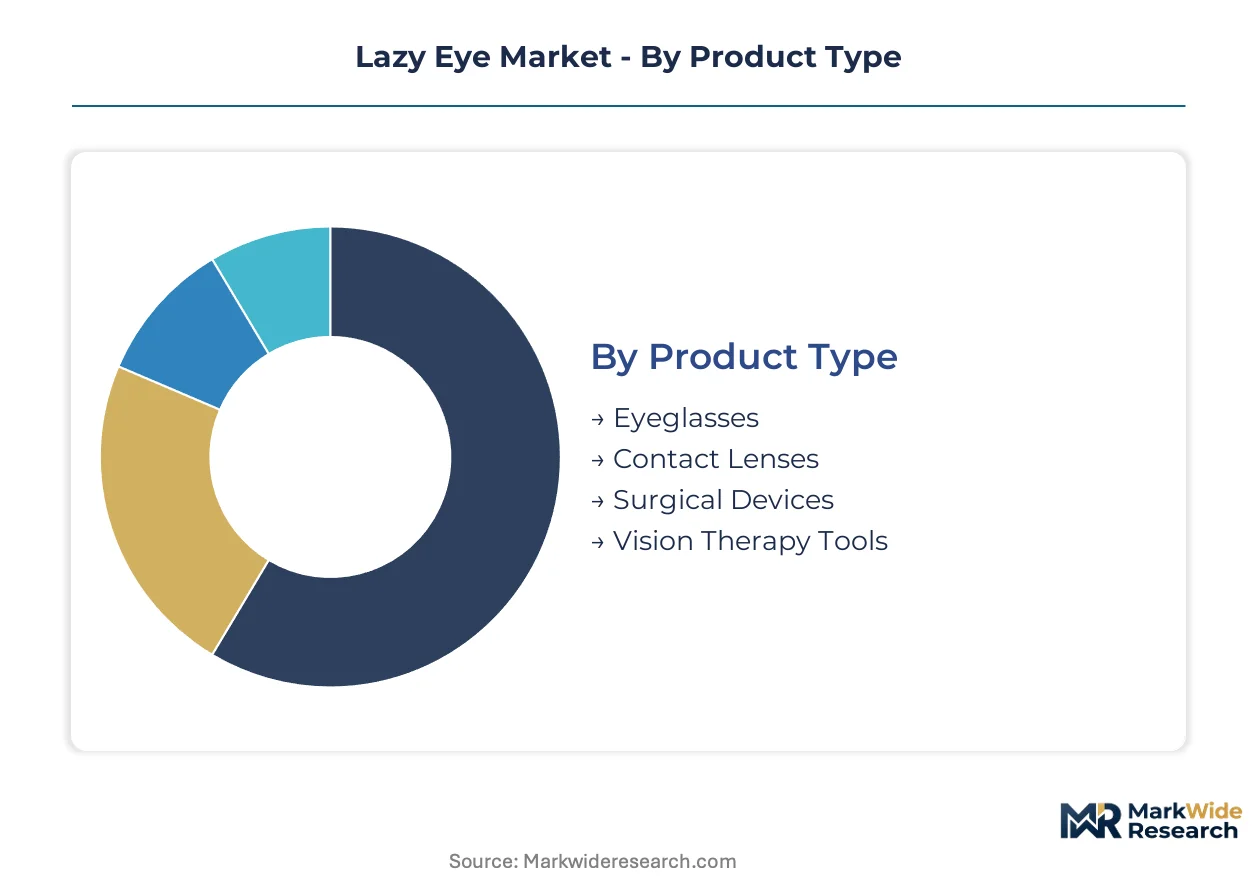
Lazy eye treatment protocols fragment across hardware, pharmaceutical, and digital modalities, each commanding distinct margin profiles and reimbursement pathways. Segmentation clarity enables stakeholders to align R&D investment with neuroplasticity windows and regulatory velocity.
Product Type:
Cost tier stratification separates mature hardware categories from emerging digital platforms with recurring revenue economics.
- Vision Therapy Tools:Digital therapeutic platforms integrate eye-tracking sensors with dichoptic gaming software. Demand concentrates in United States pediatric ophthalmology clinics where FDA breakthrough designation accelerates prescribing confidence. Subscription models displace one-time capital sales.
- Eyeglasses:Optical correction devices incorporate prism lenses and bifocal configurations to manage refractive amblyopia. Volume anchors in Medicaid-covered children populations where patch therapy adherence failures drive prescription of specialized spectacle alternatives.
- Contact Lenses:Disposable and rigid gas-permeable variants deliver occlusion therapy without cosmetic stigma. Penetration rises among adolescent cohorts rejecting patch visibility.
- Surgical Devices:Strabismus correction instruments and adjustable suture systems address structural etiologies. Utilization concentrates in academic medical centers with fellowship-trained pediatric ophthalmology departments.
Vision therapy tools hold installed capacity. Eyeglasses is rotating up the share rankings.
Age Group:
Neuroplasticity windows dictate treatment candidacy and reimbursement policy design across demographic cohorts.
- Children:Patients below age eight retain maximal cortical plasticity, making early intervention critical for permanent visual acuity restoration. United States volume concentrates in urban pediatric ophthalmology networks with embedded orthoptist staffing.
- Adults:Perceptual learning protocols now demonstrate measurable efficacy in patients beyond traditional age cutoffs. Emerging demand centers on United States military veterans and occupational vision rehabilitation programs.
- Adolescents:Transitional cohorts present adherence challenges as peer visibility concerns intersect with declining neuroplasticity. Digital therapeutic platforms with smartphone connectivity address compliance monitoring gaps.
- Seniors:Late-onset amblyopia detection in cataract surgery workups creates incidental treatment demand. Medicare reimbursement for vision rehabilitation services remains narrower than pediatric Medicaid coverage.
Children commands volume concentration. Adults is expanding most quickly as perceptual learning protocols mature.
Treatment Method:
Application modality determines clinical workflow integration and competitive substitution risk from low-cost alternatives.
- Patch Therapy:Occlusion of the dominant eye using adhesive patches remains first-line standard for unilateral amblyopia. Cost concentration in developing markets limits premium therapeutic penetration where optical shops dispense generic patches.
- Optical Treatment:Refractive correction through spectacle or contact lens prescription addresses anisometropic amblyopia. United States optometry chains capture recurring exam revenue through managed vision care contracts.
- Pharmacological:Atropine penalization drops blur the dominant eye as an occlusion alternative. Compounding pharmacies in United States serve pediatric prescriptions as commercial manufacturing concentrates on glaucoma indications.
- Surgery:Strabismus correction procedures restore binocular alignment in structural amblyopia etiologies. Academic medical centers in Boston and Philadelphia anchor United States surgical volume.
Patch therapy holds installed capacity. Optical treatment is rotating up the share rankings.
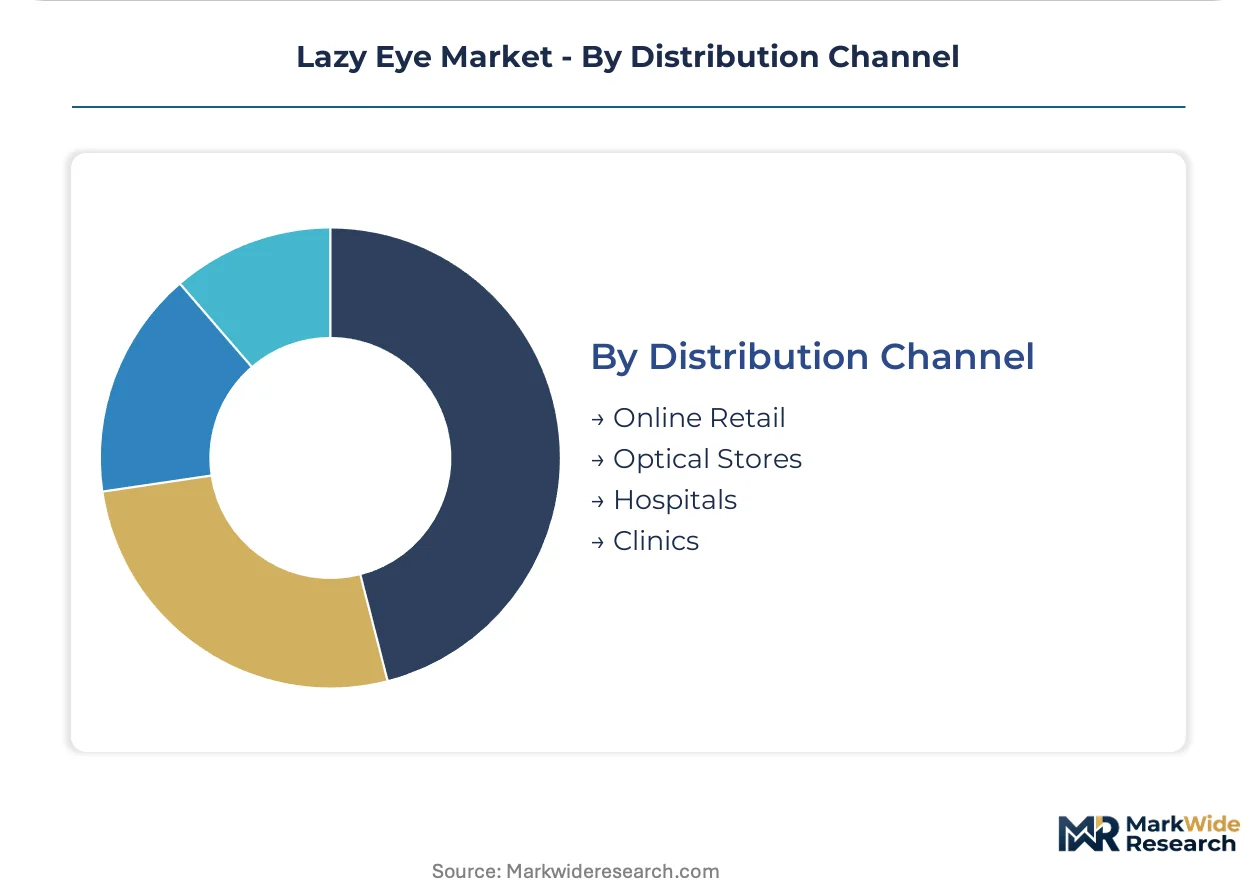
Distribution Channel:
Channel configuration determines patient access friction and margin capture for device versus pharmaceutical modalities.
- Clinics:Pediatric ophthalmology and optometry practices deliver prescription digital therapeutics with embedded compliance monitoring. United States reimbursement codes for vision therapy services concentrate volume in metropolitan clinic networks.
- Hospitals:Academic medical centers integrate surgical and complex amblyopia management with fellowship training programs. Surgical device procurement flows through hospital value analysis committees.
- Optical Stores:Retail chains dispense refractive correction and low-vision aids with managed care contract participation. Independent opticians in Germany and France retain stronger amblyopia screening roles than United States counterparts.
- Online Retail:Direct-to-consumer channels capture patch and low-vision accessory sales. Telehealth prescribing platforms in United States enable remote digital therapeutic distribution bypassing brick-and-mortar gatekeepers.
Clinics holds installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between reimbursement-rich markets where digital therapeutics penetrate pediatric clinics and cost-sensitive regions where patch therapy dominates first-line treatment protocols.
United States
FDA breakthrough device designations compress commercialization timelines for novel amblyopia platforms. Medicare Advantage and state Medicaid programs create uneven coverage landscapes for vision rehabilitation services. Boston and Philadelphia anchor surgical volume through academic medical centers with fellowship-trained pediatric ophthalmology departments.
Germany
Independent opticians retain stronger amblyopia screening roles than their United States counterparts within retail optical networks. EU MDR CE marking convergence under harmonized safety standards enables cross-border platform deployment. The Eindhoven Region electronics cluster supplies specialized VR headset displays to therapy platform manufacturers.
Japan
PMDA's orphan drug framework compresses review timelines for pediatric pharmacological indications. Perceptual learning protocols for adult neuroplasticity attract military veteran and occupational rehabilitation demand. Tokyo's Kanto region concentrates digital health venture investment for ophthalmology applications.
United Kingdom
NHS England's specialized commissioning frameworks govern access to complex strabismus surgical interventions. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR certification pathways for software-as-medical-device classifications. London's Moorfields Eye Hospital anchors national referral networks for pediatric neuro-ophthalmology.
India
CDSCO evaluates pharmacological amblyopia therapies under pediatric orphan drug analogues with accelerated review provisions. Low-cost occlusion patches from domestic manufacturers limit premium therapeutic penetration in government hospital settings. Maharashtra's Mumbai-Pune corridor concentrates private pediatric ophthalmology clinic networks with embedded orthoptist staffing.
Lazy Eye Market Competitive Environment
Capability concentration sits with specialized digital therapeutic developers; scale advantage sits with diversified ophthalmology conglomerates. The market structures around three tiers: pharmaceutical majors with neuro-ophthalmology research pipelines, dedicated vision therapy platform developers with FDA-cleared software, and optical device manufacturers with distribution infrastructure. Competitive moves center on pharmacy benefit integration partnerships and telehealth prescribing network expansion.
Within the pharmaceutical tier, Novartis leverages its ophthalmology franchise to sustain research pipelines. Among specialized digital therapeutic developers, Vivid Vision and Luminopia occupy distinct positioning vectors. Vivid Vision exemplifies the virtual reality platform archetype with clinical workflow embedding. Luminopia represents the pediatric prescription digital therapeutic segment with content-partnership commercial models. Both developers face strategic decisions between direct-to-clinic deployment and pharmacy-benefit manager integration before competitive prescribing patterns solidify.
| Leading Market Players |
|---|
| Novartis |
| Bausch & Lomb |
| Vivid Vision |
| RevitalVision |
| CooperVision |
| Johnson & Johnson Vision |
| Alcon |
| Luminopia |
| Good-Lite |
| Others |
Value Chain & Pricing Dynamics
Specialized VR headset displays and eye-tracking sensors concentrate manufacturing in East Asian electronics clusters, anchoring margin volatility for digital therapeutic platforms downstream in United States pediatric ophthalmology networks.
Pricing Analysis
Long-term subscription contracts with embedded hardware refresh cycles dominate digital therapeutic pricing, displacing one-time capital sales. Price differentiation rests on FDA breakthrough designation status and embedded compliance monitoring capabilities. Cost compression in patch therapy segments stems from generic adhesive occlusion alternatives flooding developing markets. Medicaid-covered children populations exhibit highest price sensitivity, while self-pay adult perceptual learning protocols command premium positioning.
Supply Chain Analysis
Export controls on advanced eye-tracking sensors and micro-OLED displays constrain component flows from Taiwan, South Korea, and Japan to therapy platform assemblers. Raw material dependencies center on rare-earth phosphors for display backlights, precision optical coatings, and medical-grade polymers for disposable contact lenses. Single-source vulnerability concentrates in Taiwanese semiconductor foundries supplying sensor fusion chips. Distribution runs through pediatric ophthalmology clinic networks with orthoptist staffing, bypassing traditional optical retail for prescription digital therapeutics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as prescription-grade software claims reimbursement parity with hardware, creating interoperability dependencies between digital therapeutic developers and dominant electronic health record systems.
For Market Incumbents: Insulate installed base relationships by embedding FDA-cleared platforms directly into pediatric ophthalmology clinic workflows before competitive prescribing patterns solidify. Deepen backward integration into eye-tracking sensor supply through strategic partnerships with Taiwanese component manufacturers. Prioritize certification investment for EHR interoperability APIs to reduce workflow friction.
For New Entrants and Emerging Players: Pursue white-space opportunity in adult perceptual learning protocols for United States military veteran rehabilitation programs, where neuroplasticity research has extended treatment candidacy beyond traditional age cutoffs. Target pharmacy benefit manager formulary integration as the most penetrable channel, leveraging remote prescribing enabled by asynchronous telemedicine regulations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed digital therapeutic developers holding FDA breakthrough designation but lacking pharmacy benefit integration scale. Five-to-ten-year viability hinges on reimbursement code creation velocity for software-as-medical-device classifications. Monitor PBM digital health carve-out announcements as the signal to watch for inflection in prescription flow capture.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses commercialization timelines for pediatric neuroplasticity windows. |
| CE Marking Pathway under EU MDR | Harmonized software classification rules enable cross-border deployment to European clinic networks. |
| Hospital System Partnership | Academic medical centers anchor surgical volume and fellowship training program referrals. |
| Software Companion Development | Smartphone-connected compliance monitoring displaces clinic-based supervision for adherence assurance. |
| Reimbursement Strategy | CPT and HCPCS code creation determines Medicaid coverage for vision rehabilitation services. |
Study Parameters
A spread of perspectives from pediatric ophthalmologists, orthoptists, pharmacy benefit managers, and digital therapeutic product managers converged on the working assumptions driving this analysis. Primary interviews with clinic network administrators and biomedical engineers responsible for EHR integration were cross-validated against FDA 510(k) filings, ClinicalTrials.gov amblyopia protocol registrations, CMS Medicare reimbursement databases, and state Medicaid vision therapy coverage policies. Bottom-up prescription volume estimates were triangulated with top-down market sizing from hardware shipment data and software subscription disclosures.
Demand-supply balance across the projection horizon was modeled through segmented adoption curves for children, adolescents, and adult cohorts, with neuroplasticity windows and reimbursement policy design as cross-cutting dimensions. CAGRs were derived from fitted growth trajectories accounting for FDA clearance velocity and PBM formulary integration timing. Industry-specific forecast inputs included pediatric ophthalmologist fellowship graduation rates and EU MDR notified body backlog projections.
Sensitivities concentrate around reimbursement code creation timelines and export control expansions affecting eye-tracking sensor supply. Forecasts reflect assumptions about telemedicine regulatory stability and pediatric neuroplasticity research validation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Tonometry Market