
 Hypertensive Emergency Medications Market | 2026-2036
Hypertensive Emergency Medications Market Size, Share, and Industry Trends Forecast 2026-2036
Hypertensive Emergency Medications Market Analytics
The manufacturing capability gap between fully integrated parenteral drug producers and contract-dependent formulators is collapsing as sterile injectable capacity becomes the binding constraint. Novartis AG leverages its global sterile manufacturing network to sustain hospital channel dominance across North American and European markets. Pfizer Inc. anchors its position through backward integration into active pharmaceutical ingredient supply for calcium channel blockers. Daiichi Sankyo Company Limited competes in Asia-Pacific markets with specialized esmolol formulations designed for perioperative hypertensive crises.
Hypertensive emergency medications comprise rapid-onset pharmacological agents administered to reduce mean arterial pressure by specific percentages within controlled timeframes, typically targeting reduction thresholds of 10-20 percent in the first hour depending on end-organ involvement. Intravenous labetalol and nicardipine formulations serve as first-line agents in protocols requiring titratable blood pressure control with minimal reflex tachycardia. Among administration routes, intravenous delivery leads in value contribution due to ICU and emergency department protocol requirements, while sublingual formulations represent the fastest-growing category for pre-hospital and transitional care settings where vascular access remains limited. Hospitals capture the dominant margin pool through formulary control and bundled reimbursement structures, though home care channels are expanding as ambulatory blood pressure management protocols evolve.
The FDA oversees New Drug Application requirements and Current Good Manufacturing Practice standards for sterile injectable antihypertensives, while the EMA enforces centralized marketing authorization and pharmacovigilance obligations across European Union member states. Both frameworks elevate barriers for non-compliant manufacturers and shape demand toward validated, traceable supply chains. Stakeholders must monitor evolving bioequivalence standards for generic intravenous formulations and assess sterile capacity investments against regional hospital procurement consolidation trends.
Market Dynamics
Sterile injectable manufacturing capacity has become the binding constraint reshaping competitive positioning in hypertensive emergency medications, as hospital formulary consolidation and FDA bioequivalence enforcement squeeze contract-dependent formulators out of high-margin channels.
Growth Catalysts
- Stroke Protocol Tightening:Hospital emergency departments in the United States are embedding rapid-acting intravenous antihypertensives into time-critical stroke pathways, creating protocol-driven demand that bypasses traditional physician preference variability.
- EMA Pharmacovigilance Obligations:Centralized marketing authorization requirements across European Union member states are elevating barriers for non-validated manufacturers and channeling procurement toward traceable supply chains with documented sterile production histories.
- Perioperative Crisis Management:Anesthesiology departments are expanding esmolol utilization for intraoperative blood pressure spikes, generating specialized formulation demand distinct from general emergency medicine applications.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Backward integration into calcium channel blocker API supply anchors competitive position for integrated manufacturers, leaving contract formulators exposed to input cost volatility and allocation rationing during supply shocks.
- Sterile Capacity Scarcity:The manufacturing capability gap between fully integrated parenteral drug producers and dependent formulators is collapsing as fill-finish lines reach utilization ceilings across North American and European production networks.
- Generic Intravenous Bioequivalence:FDA bioequivalence standards for generic intravenous formulations create regulatory friction that delays market entry and preserves incumbent pricing power in hospital channels.
Strategic Opportunities
- Pre-Hospital Sublingual Formulations:Emergency medical services and transitional care settings with limited vascular access represent the fastest-growing administration route category, opening white space beyond traditional ICU and emergency department capture.
- Home Care Channel Expansion:Ambulatory blood pressure management protocol evolution is extending medication administration beyond hospital walls into monitored home environments, creating new reimbursement and distribution configurations.
- Formulation Standardization:FDA updated guidance on acute blood pressure management is accelerating demand for standardized concentrations and delivery systems that reduce compounding error risk and simplify nursing workflow.
Industry Challenges
- Current Good Manufacturing Practice Compliance:Sterile injectable production requires sustained capital deployment into environmental monitoring, media fill validation, and container-closure integrity testing that strains mid-scale manufacturing operations.
- Hospital Procurement Consolidation:Integrated delivery networks and group purchasing organizations are compressing vendor panels, forcing smaller manufacturers to navigate complex qualification timelines and sole-source risk assessments.
- Legacy System Integration:Smart infusion pump interoperability and electronic health record connectivity requirements impose technical validation burdens that delay product launch and increase ongoing maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypertensive Emergency Medications Market |
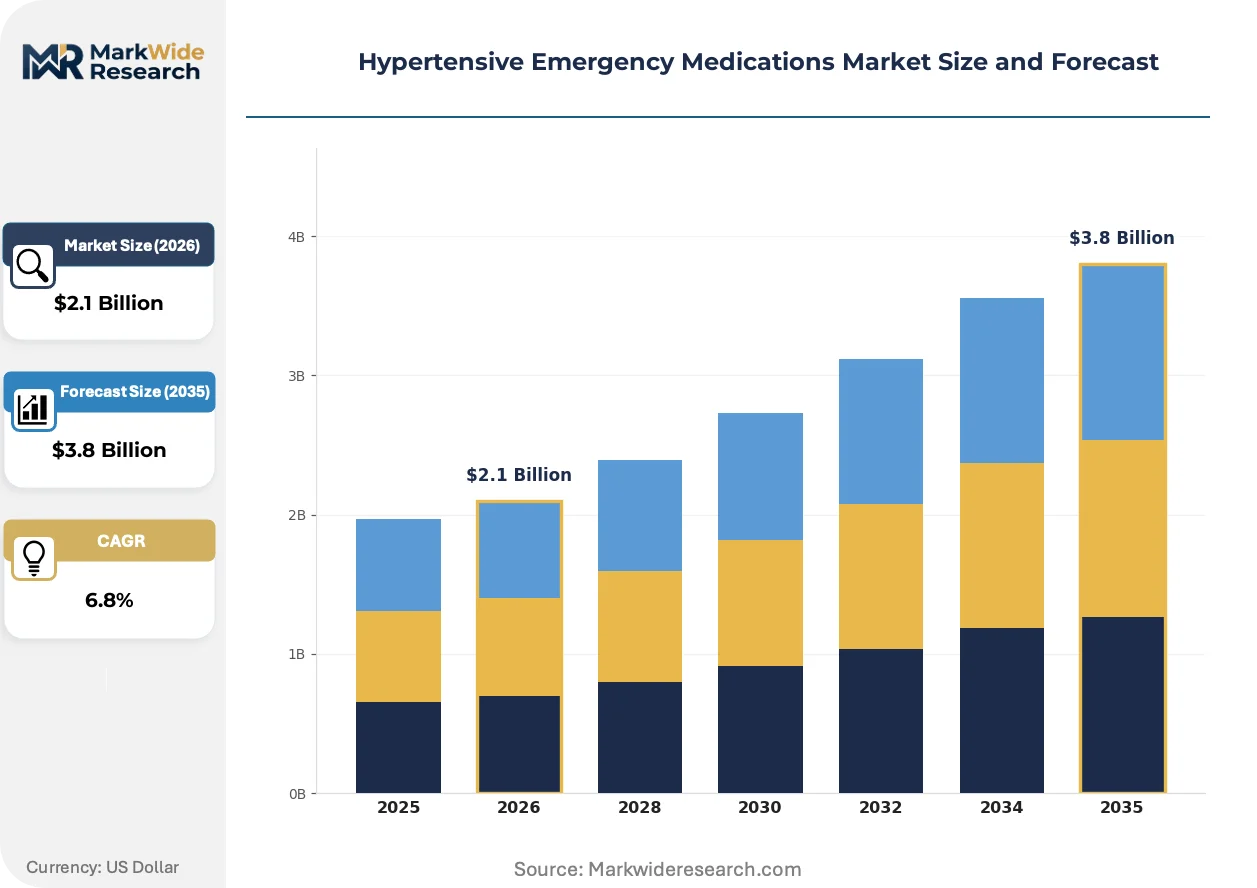
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medication Type: Labetalol, Nitroprusside, Nicardipine, Esmolol Administration Route: Intravenous, Oral, Sublingual, Inhalation End User: Hospitals, Emergency Departments, Clinics, Home Care Therapeutic Category: Vasodilators, Beta Blockers, Calcium Channel Blockers, ACE Inhibitors |
| Companies Covered | Novartis AG, Pfizer Inc., Boehringer Ingelheim International GmbH, Sanofi, Merck & Co., Inc., Johnson & Johnson Services, Inc., Baxter Laboratories Pty Ltd., Daiichi Sankyo Company Limited, Nexus Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypertensive Emergency Medications Market Evolving Landscape
Formulation science and delivery mechanism engineering are actively reshaping how hypertensive emergency medications reach patients, with particular emphasis on speed-to-control, administration flexibility, and error reduction in high-stress clinical environments.
Ready-to-use premixed intravenous bags with extended stability profiles are supplanting traditional vial-and-diluent compounding workflows in emergency departments and ICUs. Hospital pharmacy directors are accelerating adoption to reduce preparation time and eliminate calculation errors during critical events. This shift is compressing demand for traditional vial presentations and rewarding manufacturers with validated aseptic filling capacity for large-volume parenterals.
Current Good Manufacturing Practice enforcement by the FDA has intensified scrutiny of sterile injectable production facilities, with recent inspection trends elevating data integrity and environmental monitoring to primary compliance focus areas. Manufacturers with documented quality management system maturity are capturing disproportionate share of hospital formulary approvals. The consequence is accelerating facility investment and quality headcount expansion among suppliers seeking sustained channel access.
Hospital pharmacy directors are consolidating antihypertensive purchasing through therapeutic class standardization programs that designate single preferred agents per pharmacologic category. This behavioral shift is displacing fragmented multi-source procurement and concentrating volume with manufacturers offering comprehensive formulary compliance support. The United States exhibits the most pronounced concentration, where integrated delivery network scale enables aggressive vendor reduction initiatives.
Hypertensive Emergency Medications Market Segmentation
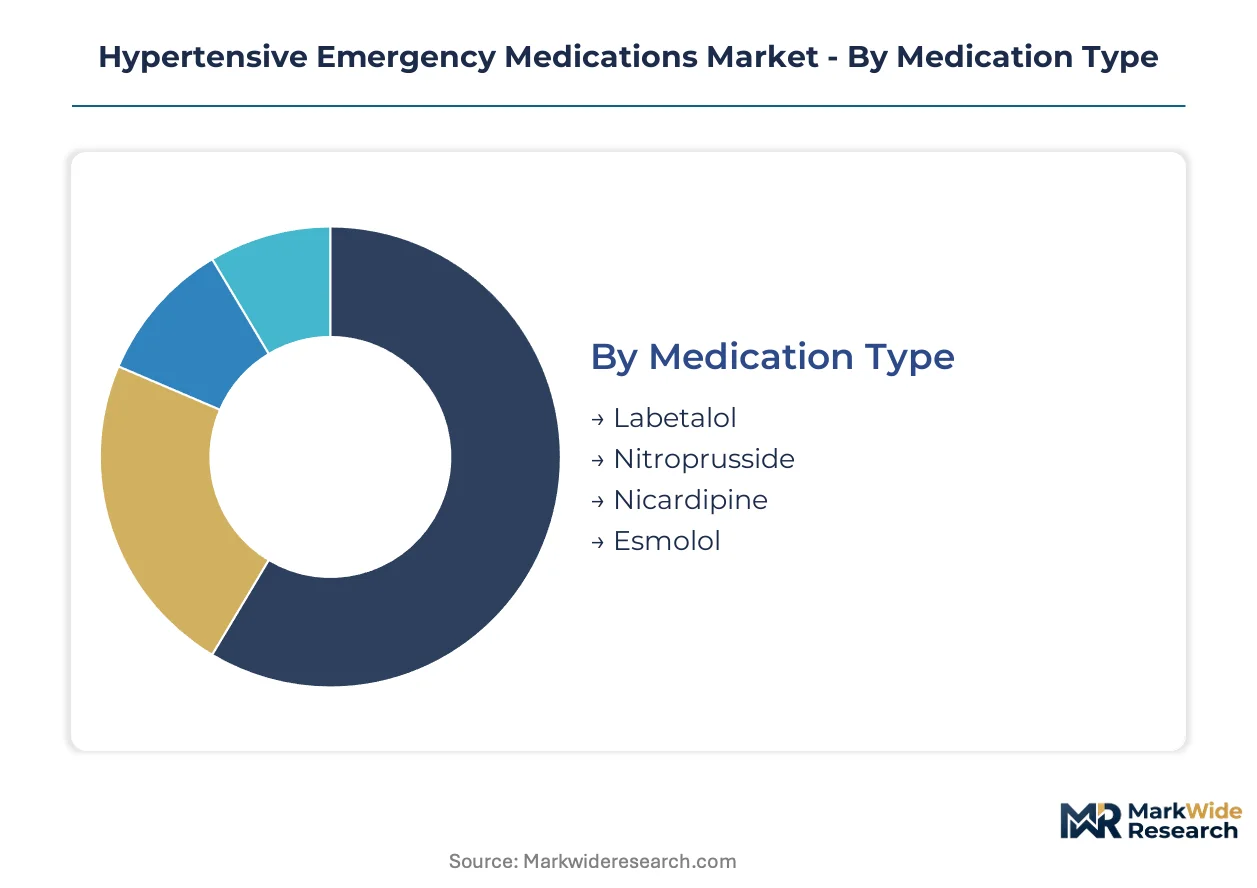
Segmentation in hypertensive emergency medications reveals how regulatory pathways, clinical protocols, and reimbursement structures concentrate demand across specific formulations and delivery channels. Understanding these divisions exposes where sterile manufacturing investments and formulary positioning yield sustainable competitive advantage.
Medication Type:
FDA bioequivalence standards and EMA pharmacovigilance obligations create divergent approval timelines and post-market surveillance burdens across molecular categories, channeling procurement toward validated supply chains.
- Labetalol:Combined alpha- and beta-adrenergic antagonist administered intravenously for rapid blood pressure reduction without reflex tachycardia. Demand concentrates in United States emergency departments where stroke protocols mandate titratable control; FDA formulation standardization accelerates adoption of premixed presentations.
- Nicardipine:Dihydropyridine calcium channel blocker delivering precise dose titration through continuous infusion. Intensive care units in Germany and France favor this agent for perioperative management; EMA centralized authorization requirements favor manufacturers with documented sterile production histories.
- Nitroprusside:Direct-acting vasodilator requiring light-protected administration and cyanide toxicity monitoring. Reserved for refractory hypertensive crises in tertiary referral centers with toxicology support.
- Esmolol:Ultra-short-acting beta-1 selective blocker with rapid onset and offset. Anesthesiology departments in Japan utilize this agent for intraoperative blood pressure spikes requiring minute-to-minute control.
Established volume favors labetalol; emerging adoption favors esmolol.
Administration Route:
Cost tier differentiation separates capital-intensive sterile injectable infrastructure from lower-barrier oral and sublingual formulations.
- Intravenous:Requires validated aseptic filling capacity, environmental monitoring, and container-closure integrity testing. Hospital emergency departments and ICUs generate protocol-driven demand that bypasses physician preference variability; bundled reimbursement structures capture dominant margin pools.
- Sublingual:Rapid buccal absorption without vascular access enables pre-hospital and transitional care deployment. Emergency medical services in the United States are expanding adoption as field protocols evolve; this route is expanding most quickly among administration categories.
- Oral:Extended-release formulations for step-down therapy following acute stabilization. Outpatient clinics and home care channels utilize these presentations for ambulatory blood pressure management.
- Inhalation:Experimental and limited clinical use; pulmonary delivery mechanisms remain under investigation for specific hypertensive crisis subtypes.
Margin concentration sits with intravenous; access expansion favors sublingual.
End User:
Customer type determines procurement authority, formulary control, and reimbursement configuration.
- Hospitals:Integrated delivery networks and group purchasing organizations compress vendor panels, concentrating volume with manufacturers offering comprehensive formulary compliance support and validated sterile supply chains.
- Emergency Departments:Time-critical stroke and cardiovascular protocols drive protocol-driven medication use; pharmacy directors standardize purchasing through therapeutic class designation programs.
- Clinics:Outpatient facilities manage step-down therapy and blood pressure monitoring; procurement autonomy varies with affiliation to larger health systems.
- Home Care:Ambulatory protocol evolution extends administration beyond hospital walls; reimbursement and distribution configurations remain under development.
Procurement authority concentrates in hospitals; channel expansion favors home care.
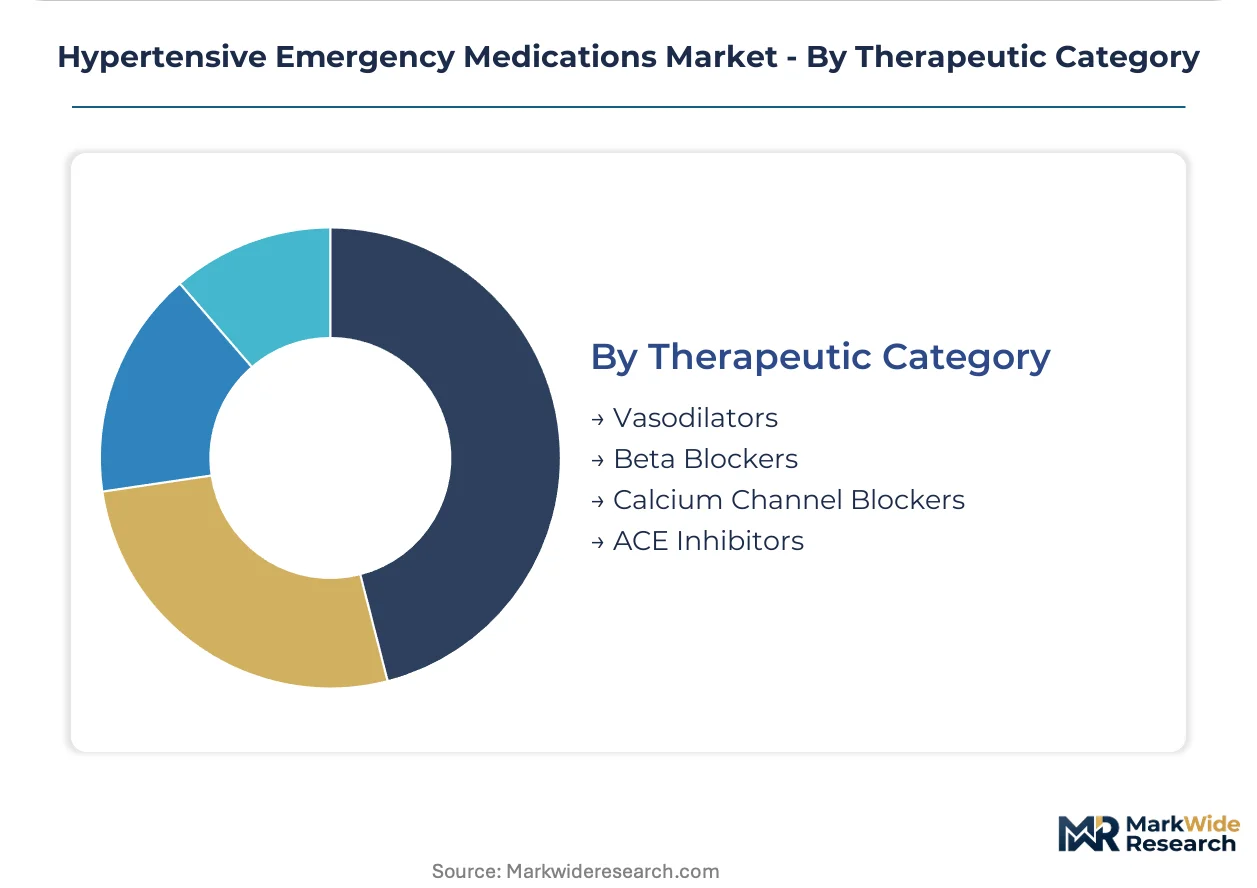
Therapeutic Category:
Supply concentration and API backward integration shape competitive position across pharmacologic mechanisms.
- Vasodilators:Direct arterial and venous relaxation agents including nitroprusside and hydralazine derivatives. Tertiary centers with toxicology monitoring capabilities generate specialized demand.
- Beta Blockers:Esmolol and labetalol dominate this category with distinct kinetic profiles. Manufacturers with captive API supply or backward integration into active pharmaceutical ingredient production anchor competitive position.
- Calcium Channel Blockers:Nicardipine and clevidipine formulations require precise infusion control. FDA bioequivalence standards for generic intravenous presentations delay market entry and preserve incumbent pricing power.
- ACE Inhibitors:Limited acute emergency use due to delayed onset; primarily reserved for oral step-down therapy in stable patients transitioning to outpatient management.
API control favors beta blockers; regulatory friction preserves calcium channel blocker margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation in the United States extracts deeper price concessions than European formulary negotiations permit, creating a pricing-power asymmetry that favors integrated manufacturers with captive sterile capacity over contract-dependent suppliers.
United States
Integrated delivery networks in Texas and Florida compress vendor panels through therapeutic class standardization programs that designate single preferred antihypertensives per pharmacologic category. FDA bioequivalence enforcement for generic intravenous formulations delays market entry and preserves incumbent pricing power in hospital channels. The Greater Boston cluster anchors specialized tertiary stroke centers with toxicology monitoring capabilities for nitroprusside utilization.
Germany
Perioperative management protocols in Bavarian university hospitals favor nicardipine continuous infusion for precise blood pressure titration during cardiac surgery. EMA centralized marketing authorization requirements channel procurement toward manufacturers with documented sterile production histories and pharmacovigilance systems. The North Rhine-Westphalia industrial corridor concentrates fill-finish capacity for large-volume parenterals serving Central European hospital networks.
Japan
Anesthesiology departments in Tokyo and Osaka metropolitan areas expand esmolol utilization for intraoperative blood pressure spikes requiring minute-to-minute kinetic control. PMDA enforcement of GMP standards for sterile injectables elevates barriers for non-validated manufacturers and concentrates procurement with established domestic suppliers. The Kansai region hosts specialized formulation facilities for ultra-short-acting beta-blocker production.
United Kingdom
Emergency medical services in London and Southeast England pilot sublingual antihypertensive protocols for pre-hospital blood pressure management where vascular access remains limited. MHRA alignment with EMA pharmacovigilance obligations reinforces traceable supply chain requirements across NHS procurement frameworks. The Midlands region concentrates hospital pharmacy consolidation initiatives that standardize purchasing through group purchasing organization contracts.
India
CDSCO accelerated approval pathways for essential medicines expand domestic manufacturing of intravenous labetalol for public hospital supply. State-level tendering in Maharashtra and Gujarat concentrates volume with manufacturers demonstrating backward integration into active pharmaceutical ingredient production. The Hyderabad-Visakhapatnam corridor anchors contract research and manufacturing organizations developing sterile injectable capacity for export markets.
Hypertensive Emergency Medications Market Competitive Landscape
Concentration sits with fully integrated pharmaceutical manufacturers possessing captive sterile injectable capacity and backward integration into active pharmaceutical ingredient supply. Hospital formulary consolidation and FDA bioequivalence enforcement squeeze contract-dependent formulators out of high-margin channels, compressing the vendor base toward validated production networks. Three archetypes dominate: multinational integrated manufacturers with global sterile networks, regional specialists with therapeutic category focus, and API-integrated generic suppliers with cost-positioned offerings. Competitive moves center on sterile capacity expansion and therapeutic class standardization partnerships with integrated delivery networks.
Among the integrated multinational tier, Novartis AG and Pfizer Inc. occupy positions defined by global manufacturing scale and hospital channel dominance across North American and European markets. Daiichi Sankyo Company Limited exemplifies the regional specialist archetype with concentrated presence in Asia-Pacific perioperative applications. These named entities anchor industry-level patterns of sterile capacity investment and formulary compliance positioning without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| Sanofi |
| Merck & Co., Inc. |
| Johnson & Johnson Services, Inc. |
| Baxter Laboratories Pty Ltd. |
| Daiichi Sankyo Company Limited |
| Nexus Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
Sterile fill-finish capacity utilization above 85% across North American and European networks anchors pricing power for integrated manufacturers while squeezing contract-dependent formulators toward commodity margins. Hospital group purchasing organization consolidation in the United States extracts deeper concessions than EMA-governed procurement frameworks permit, creating a geographic asymmetry where captive API supply and validated aseptic infrastructure defend premium positioning.
Pricing Analysis
The customization-premium spread separates standard premixed intravenous bags from configured-to-order concentrations requiring pharmacy compounding support. Three-tier pricing structure across premixed standard, pharmacy-configured, and specialized perioperative formulations reflects sterile validation depth and FDA bioequivalence tier. Pricing pressure stems from integrated delivery network therapeutic class standardization programs that designate single preferred agents per pharmacologic category. Emergency departments exhibit lowest price sensitivity due to protocol-driven formulary control; home care channels face highest sensitivity as reimbursement frameworks mature.
Supply Chain Analysis
API synthesis concentration in India and China for labetalol and nicardipine intermediates creates single-source vulnerability during regulatory inspection cycles or export restriction events. Sterile injectable manufacturing draws from specialized container-closure systems, light-protected nitroprusside administration sets, and temperature-validated cold chain infrastructure. Tariff exposure on Chinese-sourced starting materials elevates input cost volatility for non-integrated formulators. Distribution runs through hospital pharmacy central distribution centers and specialized emergency medical service supply depots serving pre-hospital deployment protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from biosimilar esmolol formulations and regional generic intravenous entrants exploiting FDA abbreviated approval pathways. Defense requires anchoring formulary position through sterile capacity depth rather than molecule exclusivity alone.
For Market Incumbents: Shield hospital channel dominance through backward integration into calcium channel blocker API supply and expansion of validated aseptic filling lines in the North Rhine-Westphalia corridor. Counter generic intravenous entrants by embedding smart infusion pump interoperability that raises technical switching costs for pharmacy directors. Prioritize therapeutic class standardization partnerships with Texas and Florida integrated delivery networks to compress vendor panels before rivals qualify.
For New Entrants and Emerging Players: Lead with sublingual formulation development targeting United Kingdom emergency medical services pilot programs and United States transitional care settings where vascular access limitations create white space beyond ICU capture. Exploit CDSCO accelerated approval pathways for essential medicines to establish cost-positioned intravenous labetalol supply for Indian public hospital tenders. Anchor initial commercial traction through perioperative crisis management protocols in Japanese anesthesiology departments where esmolol minute-to-minute control requirements favor specialized kinetic profiles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-integrated sterile manufacturers with documented pharmacovigilance systems and EMA centralized authorization histories over pure-play formulators facing bioequivalence friction. Long-term viability hinges on captive fill-finish capacity rather than molecule portfolios alone. Target acquisition archetypes include regional specialists with therapeutic category concentration in Asia-Pacific perioperative applications. Monitor FDA inspectional observation trends as inflection indicator for supply chain requalification costs that reshape competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Sterile Capacity Expansion | Validated aseptic filling lines in Germany and United States defend hospital formulary position against bioequivalence-delayed generics. |
| API Backward Integration | Captive labetalol and nicardipine intermediate production insulates margin from Indian and Chinese export restriction volatility. |
| Pre-Hospital Formulation Development | Sublingual presentations for United Kingdom emergency medical services open fastest-growing administration route beyond ICU capture. |
| Smart Infusion Pump Interoperability | Electronic health record connectivity raises technical validation burdens that delay rival product launch and increase switching costs. |
| Therapeutic Class Standardization Partnership | Single-preferred-agent designation with Texas and Florida integrated delivery networks compresses vendor panels and concentrates volume. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, anesthesiology department heads, emergency medicine protocol leads, and sterile manufacturing quality officers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 483 inspection databases, EMA centralized marketing authorization records, and hospital procurement databases. Bottom-up segmentation modeling triangulated with top-down therapeutic class demand aggregation.
Sensitivity analysis across API cost volatility scenarios and sterile capacity utilization thresholds informed projection robustness. Segmentation dimensions modeled include medication type, administration route, end user archetype, and regional regulatory cluster. CAGRs derived from protocol adoption curve analysis and hospital infrastructure investment patterns. Forecast inputs incorporated stroke pathway standardization timelines and perioperative crisis management protocol expansion rates.
Forecasts assume regulatory continuity in FDA bioequivalence enforcement and EMA pharmacovigilance obligations; material policy shifts would require re-modeling. Specific risks include generic intravenous approval acceleration, hospital procurement consolidation beyond current integrated delivery network scale, and sterile manufacturing quality enforcement intensification. Practitioners should keep alternative scenarios live as reimbursement framework evolution for home care channels and pre-hospital deployment protocols mature.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Sulfonylureas Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market