
 Conjunctivitis Treatment Market | 2026-2036
Conjunctivitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Conjunctivitis Treatment Market Intelligence
Hospital outpatient departments is recalibrating their procurement priorities toward preservative-free formulations for chronic conjunctivitis patients. Novartis AG leverages its ophthalmology franchise depth to sustain formulary access across European hospital networks. Alcon anchors the premium artificial tears segment through direct-to-practitioner channel control. Bausch & Lomb Incorporated competes on manufacturing scale, operating high-throughput sterile filling lines that supply retail pharmacy chains across North America.
Conjunctivitis treatment encompasses pharmacological and non-pharmacological interventions targeting inflammation of the bulbar and palpebral conjunctiva, with topical formulations requiring pH-balanced, isotonic delivery systems between 7.0 and 7.4 to preserve corneal epithelial integrity. The primary purpose is rapid symptom resolution, pathogen clearance, and prevention of corneal complication progression in acute and chronic presentations. Antibiotics occupy the largest revenue pool due to bacterial conjunctivitis prevalence in contact lens wearers, while antihistamines represent the fastest-expanding category as seasonal allergic cases climb in urban pollution corridors. The ophthalmic delivery mode dominates unit volume, though homecare end users are shifting toward multi-dose preservative-free systems that reduce dosing frequency and improve adherence.
The FDA enforces Current Good Manufacturing Practice for ophthalmic preparations under 21 CFR Part 211, with sterility assurance and particulate matter limits dictating facility capital requirements for entrants. EMA's Guideline on Quality of Ophthalmic Medicines imposes additional stability testing protocols that extend development timelines for European market authorization. Stakeholders must monitor how FDA draft guidance on microbiological quality of aqueous-based drug products reshapes validation standards before committing to capacity expansion.
Market Dynamics
FDA sterility mandates under 21 CFR Part 211 are forcing facility upgrades across ophthalmic manufacturing, compressing margins for mid-scale producers while advantaging capital-heavy incumbents with validated aseptic filling infrastructure.
Growth Catalysts
- Allergic Disease Prevalence:Urban pollution corridors in the United States and India are amplifying seasonal allergic conjunctivitis caseloads, expanding the addressable patient pool for antihistamine and mast-cell stabilizer formulations.
- EMA Stability Protocols:The Guideline on Quality of Ophthalmic Medicines is accelerating adoption of advanced barrier packaging systems that extend shelf life and reduce cold-chain dependency for European distribution.
- Contact Lens Wear:Silicone hydrogel lens adoption is elevating bacterial conjunctivitis incidence among daily wearers, sustaining antibiotic prescription volumes through ophthalmology clinics and optometric practices.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for fluoroquinolone antibiotics concentrates in Chinese bulk chemical manufacturers, exposing formulators to tariff volatility and geopolitical supply interruptions.
- Preservative Toxicity Limitations:Benzalkonium chloride sensitivity among chronic dry-eye patients restricts multi-dose bottle retention, forcing faster patient migration to higher-cost preservative-free alternatives.
- Generic Erosion:Patent expirations on branded antihistamine combinations are compressing realized prices in retail pharmacy channels, narrowing branded portfolio contribution margins.
Strategic Opportunities
- Pediatric Formulary Expansion:Underpenetrated demand in Indian and Brazilian pediatric ophthalmology clinics offers whitespace for age-appropriate dosing formulations and taste-masked delivery systems.
- Homecare Channel Innovation:Direct-to-patient subscription models for chronic allergic conjunctivitis management are bypassing traditional pharmacy intermediaries, capturing recurring revenue streams in United States metropolitan markets.
- Biologic Convergence:Integration of monoclonal antibody platforms with topical ophthalmic delivery is opening severe vernal keratoconjunctivitis segments previously managed only with systemic immunosuppression.
Industry Challenges
- Aseptic Processing Talent Scarcity:Validated sterile filling operators and quality assurance microbiologists command premium compensation, constraining capacity expansion timelines for emerging manufacturers.
- Compliance Capital Intensity:FDA microbiological quality draft guidance is mandating isolator technology and continuous monitoring systems that require eight-figure facility investments with seven-year depreciation horizons.
- Legacy System Integration:Paper-based batch records and standalone manufacturing execution systems in established plants impede real-time release testing and continuous process verification adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conjunctivitis Treatment Market |
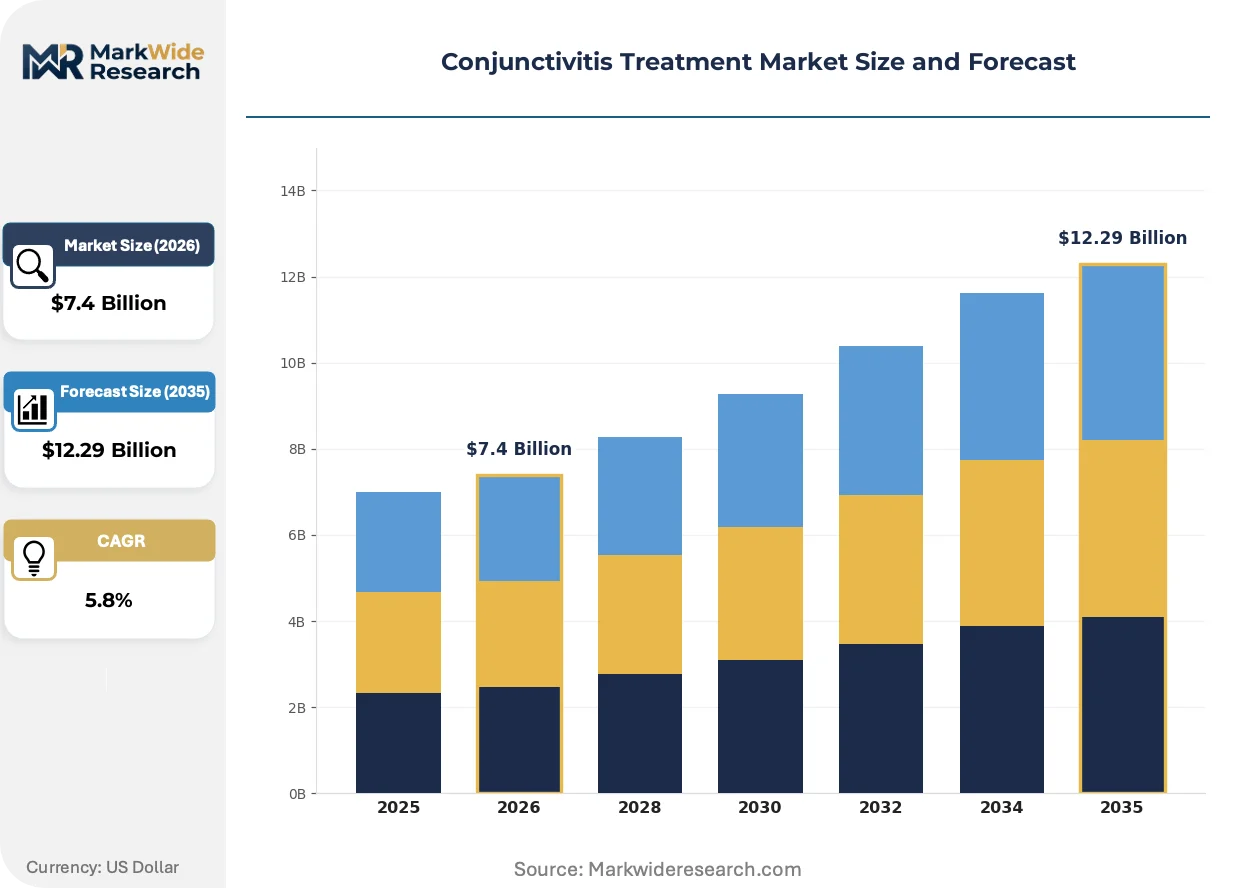
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Antibiotics, Corticosteroids, Artificial Tears Delivery Mode: Topical, Oral, Injectable, Ophthalmic Patient Demographic: Adults, Children, Infants, Elderly End User: Clinics, Hospitals, Homecare, Pharmacies |
| Companies Covered | Allergan, Novartis AG, Alcon, Santen Pharmaceutical, Bausch & Lomb Incorporated, Eyevance Pharmaceuticals, AbbVie Inc., Akorn, Nicox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conjunctivitis Treatment Market Strategic Shifts & Innovations
Novel drug delivery platforms are compressing dosing frequency from four-times-daily to once-daily regimens, reshaping patient adherence economics and formulary positioning strategies across ambulatory eye care settings.
Preservative-free multi-dose bottle technology is rewriting the chronic conjunctivitis treatment paradigm by eliminating benzalkonium chloride exposure while retaining the cost structure of conventional multi-dose packaging. Hospital outpatient departments and integrated eye care networks in Germany and the United States are adopting these systems at accelerating pace for their glaucoma-conjunctivitis comorbid populations. The shift is compressing demand for single-use vials and forcing contract manufacturers to retool filling lines for novel elastomeric pump mechanisms.
REACH Annex XVII restrictions on microplastic-containing leave-on products are compelling European formulators to reformulate ophthalmic emulsions and suspensions with biodegradable viscosity modifiers. The ECHA regulatory pressure is extending reformulation timelines by eighteen to twenty-four months for products seeking renewed authorization. Manufacturers serving the French and Italian hospital markets are prioritizing cellulose-derived alternatives to carbomer-based gelling agents ahead of enforcement deadlines.
Contact lens wearers are consolidating purchasing decisions through integrated vision insurance platforms that bundle diagnostic services, therapeutic products, and replacement lens subscriptions into single annual contracts. This channel consolidation is displacing independent pharmacy dispensing for acute bacterial conjunctivitis episodes in United States metropolitan corridors. Optometric practice groups in California and Texas are capturing patient loyalty through these bundled arrangements, redirecting antibiotic prescription flows away from retail chains.
Conjunctivitis Treatment Market Segmentation
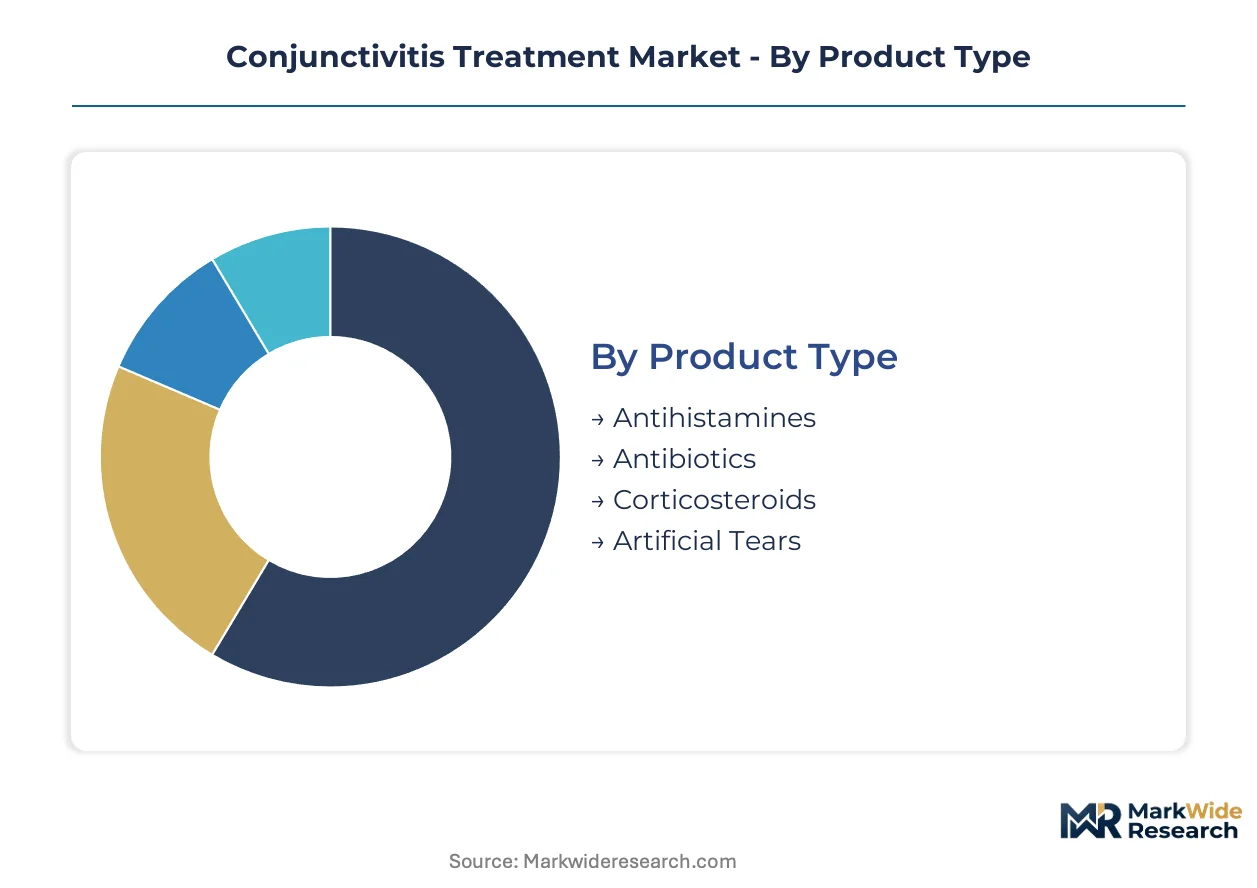
Conjunctivitis treatment segments diverge sharply across acute versus chronic management pathways. Product formulators must align sterile manufacturing capabilities with distinct dosing frequency requirements and reimbursement structures.
Product Type:
Volume concentration tilts toward mass-market antibiotic formulations, while premium capture concentrates in chronic-care segments with extended dosing cycles.
- Antihistamines:Second-generation H1 receptor antagonists formulated as topical drops or combination products with mast-cell stabilizers. Demand clusters in United States urban corridors with elevated pollen and particulate pollution, where seasonal prescription volumes spike during spring and fall peaks. Alcon and Novartis AG dominate formulary positioning through direct-to-practitioner channels.
- Antibiotics:Fluoroquinolone and macrolide classes targeting bacterial pathogens in contact lens-associated infections. Hospital outpatient departments and ambulatory surgical centers in Germany and the United States drive procurement volumes for post-operative prophylaxis and acute presentations.
- Corticosteroids:Potent anti-inflammatory agents reserved for severe allergic or autoimmune-mediated presentations requiring specialist oversight.
- Artificial Tears:Lubricating formulations spanning preserved multi-dose bottles to preservative-free single-use vials for chronic dry-eye comorbidities.
Today's leader: Antibiotics. Tomorrow's challenger: Antihistamines.
Delivery Mode:
Route selection hinges on infection severity, patient compliance capacity, and corneal penetration requirements.
- Topical:Eye drops and ointments delivering active agents directly to the conjunctival sac. Pediatric ophthalmology clinics in India and Brazil are expanding age-appropriate topical formulations with reduced stinging profiles.
- Ophthalmic:Specialized ocular delivery systems including punctal plugs and sustained-release inserts. Integrated eye care networks in Texas and California are adopting these for chronic vernal keratoconjunctivitis requiring continuous medication levels.
- Oral:Systemic antihistamines and antibiotics for refractory cases or patients with poor topical compliance.
- Injectable:Subconjunctival or intravitreal administration reserved for sight-threatening complications with corneal involvement.
Ophthalmic delivery commands the steepest expansion trajectory as sustained-release technologies mature.
Patient Demographic:
Age-stratified dosing demands shape formulation development priorities and regulatory submission pathways.
- Adults:Working-age patients managing seasonal allergic episodes alongside contact lens wear. United States metropolitan markets show concentration in integrated vision insurance platforms bundling diagnostic and therapeutic services.
- Children:School-age populations with high contagious potential for viral and bacterial forms. Brazilian pediatric clinics represent underpenetrated whitespace for taste-masked delivery systems.
- Infants:Neonatal conjunctivitis requiring prophylactic antibiotic protocols at birth.
- Elderly:Chronic presentations complicated by dry-eye syndrome and polypharmacy interactions in long-term care settings.
Adults generate current volume concentration. Children offer the most rapid addressable pool expansion.
End User:
Channel control determines pricing realization and patient adherence monitoring capabilities.
- Clinics:Ophthalmology and optometric practices capturing bundled vision care contracts. California and Texas practice groups are displacing retail pharmacy dispensing through integrated diagnostic-therapeutic-subscription arrangements.
- Homecare:Direct-to-patient models for chronic allergic conjunctivitis management. Subscription services in United States metropolitan corridors bypass traditional intermediaries.
- Hospitals:Inpatient and emergency department presentations of severe or complicated cases.
- Pharmacies:Retail chains facing margin compression from generic antibiotic erosion and channel consolidation.
Clinics anchor current revenue capture. Homecare channels are gaining share fastest through adherence-focused subscription economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as capital-intensive producers migrate toward jurisdictions with harmonized sterility standards but lower facility operating costs, while demand concentration remains anchored in high-reimbursement markets with stringent compliance requirements.
United States
Integrated eye care networks in Texas and California are consolidating procurement for preservative-free formulations, driving formulary standardization across ambulatory surgical centers. FDA sterility mandates under 21 CFR Part 211 are compressing margins for mid-scale domestic producers lacking validated aseptic infrastructure. The Boston metropolitan corridor hosts specialized ophthalmic contract manufacturers retooling filling lines for novel elastomeric pump mechanisms.
Germany
Hospital outpatient departments in Bavaria and North Rhine-Westphalia are accelerating adoption of advanced barrier packaging systems that extend shelf life and reduce cold-chain dependency. EMA stability protocols under the Guideline on Quality of Ophthalmic Medicines are extending development timelines for European market authorization. The Frankfurt-Rhine-Main cluster concentrates sterile formulation expertise serving hospital networks across Central Europe.
India
Pediatric ophthalmology clinics in Maharashtra and Karnataka represent underpenetrated whitespace for age-appropriate dosing formulations with reduced stinging profiles. CDSCO tightened manufacturing practice requirements are elevating compliance costs for domestic bulk chemical producers. The Hyderabad-Visakhapatnam pharmaceutical corridor is expanding high-throughput sterile filling capacity to serve export markets in Southeast Asia and Africa.
Japan
Contact lens wearers in the Tokyo-Osaka corridor are consolidating purchasing decisions through integrated vision insurance platforms bundling diagnostic and therapeutic services. PMDA post-market surveillance requirements for ophthalmic preparations are intensifying pharmacovigilance obligations for sustained-release delivery systems. The Kansai region maintains specialized manufacturing clusters for silicone hydrogel lens care solutions with therapeutic adjunct positioning.
Brazil
School-age populations in São Paulo and Minas Gerais with high contagious potential for viral and bacterial forms are expanding the addressable pool for taste-masked delivery systems. ANVISA import substitution policies are incentivizing local production of active pharmaceutical ingredients for fluoroquinolone antibiotics. The Campinas pharmaceutical hub is attracting contract manufacturing investment targeting pediatric formulation gaps in Latin American markets.
Conjunctivitis Treatment Market Key Industry Players
Capacity expansion dominates the current landscape as incumbents with validated aseptic infrastructure extend manufacturing scale advantages. The vendor base concentrates around capital-heavy multinational pharmaceutical groups with ophthalmology franchise depth, mid-scale regional formulators competing on manufacturing flexibility, and specialized contract manufacturers serving niche delivery system requirements. Strategic archetypes include integrated eye care platform operators, sterile manufacturing specialists, and biologic convergence aspirants. M&A activity and facility upgrade cycles represent the dominant competitive moves as FDA draft guidance on microbiological quality reshapes validation standards.
Among Swiss and Irish-domiciled pharmaceutical conglomerates with ophthalmology franchise breadth, Novartis AG and Allergan exemplify integrated platform operators leveraging direct-to-practitioner channel control. Alcon occupies a position within the premium artificial tears and device-adjacent therapeutic segment, anchoring formulary access through practitioner-level relationships. These three entities represent distinct archetypes: the diversified pharmaceutical group with ophthalmology vertical, the device-therapeutic hybrid, and the pure-play eye care specialist.
| Leading Market Players |
|---|
| Allergan |
| Novartis AG |
| Alcon |
| Santen Pharmaceutical |
| Bausch & Lomb Incorporated |
| Eyevance Pharmaceuticals |
| AbbVie Inc. |
| Akorn |
| Nicox |
| Others |
Cost & Logistics Intelligence
Fluoroquinolone API price indices from Chinese bulk chemical manufacturers cascade through ophthalmic formulation supply chains into three distinct pricing tiers: premium preservative-free systems for chronic care, standard multi-dose formulations for acute bacterial cases, and economy generics for retail pharmacy substitution. Hospital outpatient departments in Germany and ambulatory surgical centers in Texas concentrate procurement power, compressing margins for mid-scale producers lacking validated aseptic infrastructure while rewarding capital-heavy incumbents with formulary lock-in.
Pricing Analysis
Direct-to-practitioner channel margins dominate ophthalmic therapeutic pricing, with Alcon and Novartis AG capturing premium realization through formulary control in integrated eye care networks. Three-tier pricing structure across preservative-free premium, benzalkonium chloride-preserved standard, and generic fluoroquinolone economy levels stratifies by sterility assurance grade and dosing frequency innovation. Pricing pressure stems from generic antibiotic erosion in retail pharmacy channels, where Indian and Brazilian buyers exhibit highest price sensitivity while German hospital networks prioritize compliance certification over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from FDA-inspected formulators concentrate active pharmaceutical ingredient procurement across China, India, and selected European specialty chemical producers to mitigate tariff volatility and geopolitical interruption exposure. Sterile filling operations hinge on elastomeric pump mechanisms, pharmaceutical-grade water systems, and barrier isolator technology sourced from validated equipment vendors. Single-source vulnerability concentrates in Chinese fluoroquinolone intermediate manufacturers, while distribution runs through hospital procurement consortia, specialty pharmacy networks, and direct-to-patient subscription platforms serving chronic allergic conjunctivitis populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conjunctivitis treatment market represents a late-cycle quality story as patient and prescriber demand migrates decisively toward preservative-free formulations with extended stability profiles and reduced dosing frequency.
For Market Incumbents: To counter generic erosion in retail antibiotic segments, prioritize backward integration into active pharmaceutical ingredient sourcing for fluoroquinolone classes and accelerate capacity addition in Hyderabad-Visakhapatnam corridor sterile filling facilities. FDA sterility mandate compliance investments in isolator technology and continuous monitoring systems will consolidate manufacturing scale advantages against mid-scale competitors. For New Entrants and Emerging Players: Pediatric ophthalmology clinics in Maharashtra and São Paulo represent the most penetrable whitespace for taste-masked delivery systems and age-appropriate dosing formulations with reduced stinging profiles. Direct-to-patient subscription models for chronic allergic conjunctivitis management in United States metropolitan corridors offer viable go-to-market angles bypassing traditional pharmacy intermediaries. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized contract manufacturers possessing validated aseptic infrastructure and elastomeric pump mechanism filling expertise. Long-term viability centers on acquisition targets serving biologic convergence in severe vernal keratoconjunctivitis segments. The signal to watch is FDA draft guidance finalization on microbiological quality standards, which will trigger facility upgrade cycles and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Expansion | Captures formulary preference in German hospital outpatient departments and Texas integrated eye care networks. |
| Pediatric Dosing Development | Addresses underpenetrated demand in Brazilian and Indian pediatric ophthalmology clinics with age-appropriate systems. |
| Direct-to-Patient Subscription Launch | Bypasses retail pharmacy intermediaries in United States metropolitan chronic allergic conjunctivitis management. |
| EMA Stability Protocol Compliance | Accelerates European market authorization through advanced barrier packaging adoption. |
| Biologic Delivery Platform Integration | Opens severe vernal keratoconjunctivitis segments previously managed with systemic immunosuppression. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, and ClinicalTrials.gov records; and customs trade data — were reconciled through bottom-up and top-down triangulation. Formulary database analysis and CMS Medicare reimbursement patterns provided demand-side calibration for volume estimation.
Historical prescription volume trajectories were cross-referenced against expert panel assessments of regulatory timeline acceleration and channel consolidation patterns across the projection horizon. Segmentation modeling incorporated treatment line, dosage form, patient demographic stratification, and regional regulatory cluster dimensions. CAGRs were derived from epidemiological trend analysis, pricing realization patterns, and capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA sterility guidance finalization, API tariff regime shifts, and biologic convergence timeline acceleration. Deviation in EMA stability protocol enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Exophthalmos Treatment Market