
 Global Diabetic Macular Edema Market | 2026-2036
Global Diabetic Macular Edema Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Macular Edema Market Foresight
North American pharmaceutical manufacturing capacity is reshaping supply dynamics for anti-VEGF biologics used in diabetic macular edema treatment. Regeneron Pharmaceuticals anchors its position through captive monoclonal antibody production and vertical control over aflibercept supply chains. Roche Holding AG leverages its diagnostics division to pair OCT imaging with ranibizumab therapy decisions, creating integrated care protocols that sustain its competitive position.
Diabetic macular edema is a retinal thickening condition caused by fluid accumulation in the macula due to compromised blood-retinal barrier integrity from hyperglycemia-induced vascular endothelial growth factor overexpression; its primary clinical purpose is the preservation of central visual acuity and prevention of irreversible photoreceptor damage in diabetic patients. Anti-VEGF drugs occupy the dominant revenue position due to established efficacy in center-involved DME and broad payer coverage, while sustained-release implants represent the fastest-expanding technology segment as physicians seek reduced injection burden for chronic DME cases. Intravitreal injections remain the volume backbone across ophthalmology clinics, though drug delivery systems are gaining traction in specialty hospitals that manage complex recurrent DME presentations.
The FDA's ophthalmic biologics review standards and the EU MDR's tightened requirements for combination drug-device products create divergent compliance pathways that manufacturers must navigate simultaneously. Japan's PMDA maintains distinct pharmacovigilance reporting thresholds for intravitreal therapies that influence post-market study commitments. Stakeholders must monitor how reimbursement authorities in Germany, France, and the United States calibrate access decisions for emerging sustained-release formulations against established anti-VEGF benchmarks.
Market Dynamics
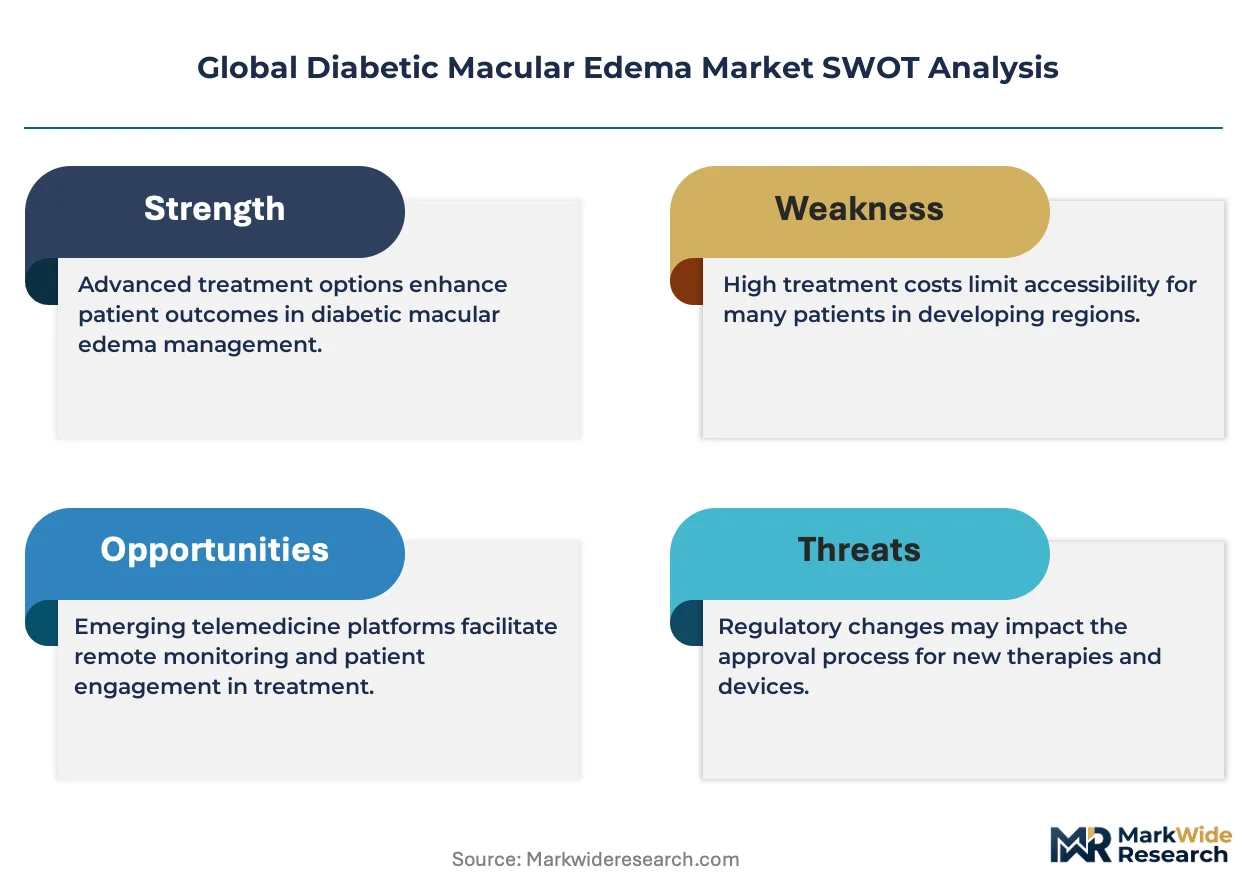
The anti-VEGF injection burden is reshaping clinical workflows across ophthalmology practices, with physicians prioritizing sustained-release alternatives that reduce treatment frequency for chronic diabetic macular edema patients. This structural pressure is accelerating development timelines for long-acting drug delivery systems while compressing margins on conventional intravitreal therapies.
Growth Catalysts
- Japan's PMDA pharmacovigilance thresholds:Streamlined post-market study commitments for intravitreal therapies accelerate approval timelines for novel sustained-release formulations entering the Japanese market.
- Center-involved DME reimbursement frameworks:Payer coverage expansion in Germany and the United States prioritizes visual acuity preservation therapies, pulling demand toward clinically validated anti-VEGF benchmarks.
- Hyperglycemia-induced VEGF overexpression prevalence:Rising diabetic populations in urban clinical catchment areas expand the addressable patient base for macular edema interventions.
Market Restraints
- Combination drug-device MDR compliance:The EU's tightened technical documentation requirements extend development timelines and elevate certification costs for sustained-release implant manufacturers.
- Biologics manufacturing concentration:Captive monoclonal antibody production in North American facilities creates supply vulnerability for aflibercept and ranibizumab active pharmaceutical ingredients.
- Anti-VEGF biosimilar substitution pressure:Accelerated FDA approval pathways for reference biologics threaten pricing power of originator therapies across commercial and government payer segments.
Strategic Opportunities
- Underpenetrated sustained-release adoption:Specialty hospitals in France and the United Kingdom present expansion potential for intravitreal implants managing recurrent DME presentations.
- OCT imaging integration protocols:Diagnostic-therapeutic pairing creates stickier care pathways as clinics bundle imaging with treatment decisions.
- Reduced injection burden value propositions:Physician preference for chronic disease management tools opens pricing headroom for long-acting formulations against quarterly injection schedules.
Industry Challenges
- Vitreoretinal surgeon training capacity:Intravitreal injection technique specialization limits practice expansion velocity in secondary and tertiary care markets.
- Drug-device combination sterilization validation:Polymeric implant shelf-life stability requirements complicate manufacturing scale-up and cold chain logistics.
- Cross-jurisdiction dossier divergence:Simultaneous FDA biologics review and EU MDR technical file preparation strains regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetic Macular Edema Market |
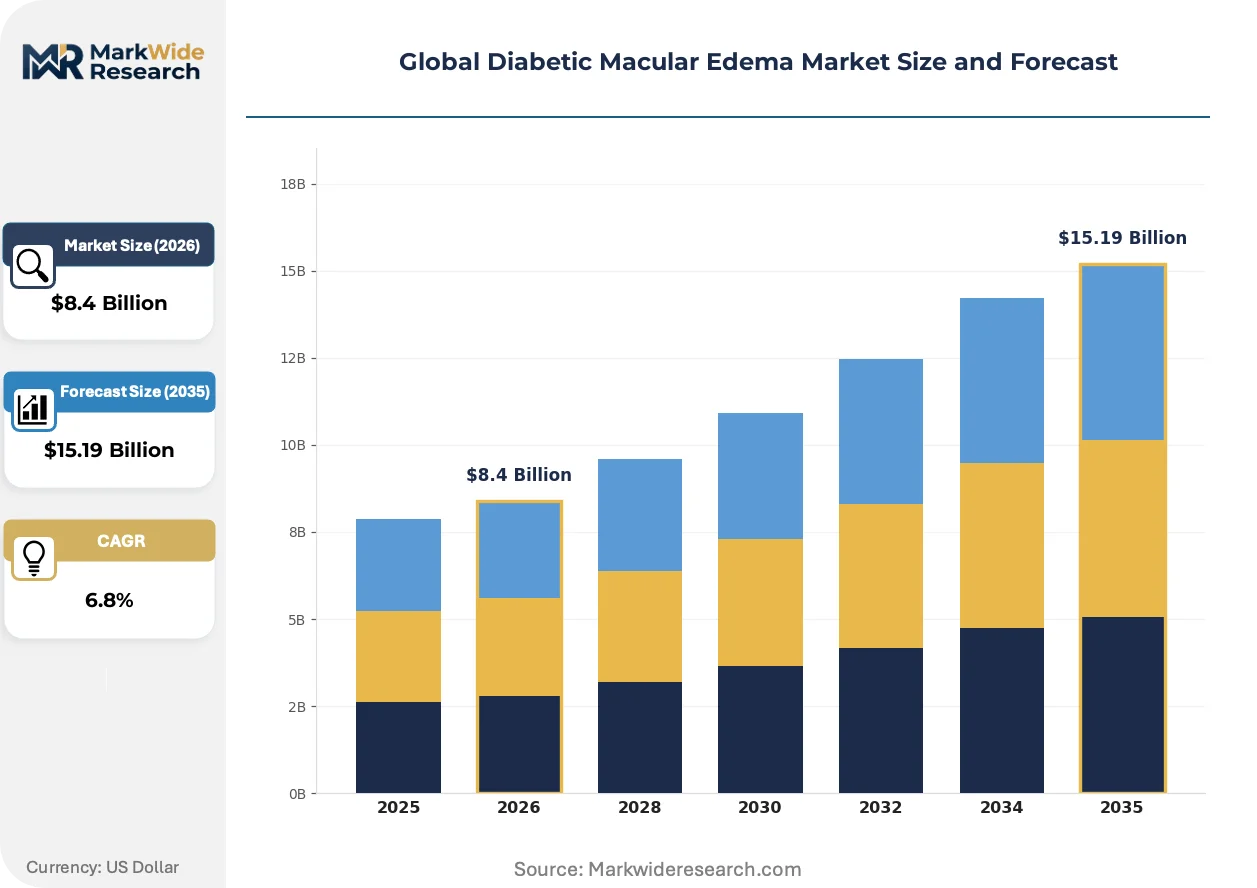
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Drugs, Corticosteroids, Combination Therapies, Laser Photocoagulation Therapy Area: Center-Involved DME, Non-Center-Involved DME, Chronic DME, Recurrent DME Care Setting: Ophthalmology Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Diagnostic Centers Treatment Technology: Intravitreal Injections, Sustained-Release Implants, Laser Therapy, Drug Delivery Systems |
| Companies Covered | Regeneron Pharmaceuticals, Bausch & Lomb, Roche Holding AG, Topcon Corporation, Allergan plc, Bayer AG, Carl Zeiss Meditec AG, Santen Pharmaceutical Co. Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Macular Edema Market Shifts & Advancements
Drug delivery technology is compressing treatment intervals for chronic retinal disease management, with sustained-release platforms challenging the dominance of frequent intravitreal injections. These shifts are redrawing competitive boundaries between biologic manufacturers and specialty device developers.
Port delivery systems with refillable reservoirs are migrating from experimental protocols toward standard-of-care consideration in high-volume retina practices. Academic medical centers in the United States and Germany are piloting these implants for treatment-naive patients, reducing injection frequency from monthly to semi-annual intervals. This migration from acute intervention models toward chronic disease management infrastructure is reallocating physician capacity and clinic scheduling resources.
The FDA's accelerated approval pathway for ophthalmic biosimilars is compressing exclusivity windows for reference anti-VEGF products. Manufacturers must now defend market position through formulation differentiation rather than patent protection alone. Ranibizumab and aflibercept originators are responding with sustained-release line extensions and device-combination filings to maintain access tier preference.
Retina specialists are unbundling diagnostic services from therapeutic administration, creating discrete reimbursement capture for OCT imaging and injection procedures. This fragmentation is visible in United States ophthalmology clinics where physicians separately code imaging interpretation, intravitreal injection, and post-operative evaluation. The shift pressures integrated care protocols and creates procurement complexity for practice administrators negotiating device and drug contracts.
Global Diabetic Macular Edema Market Segmentation
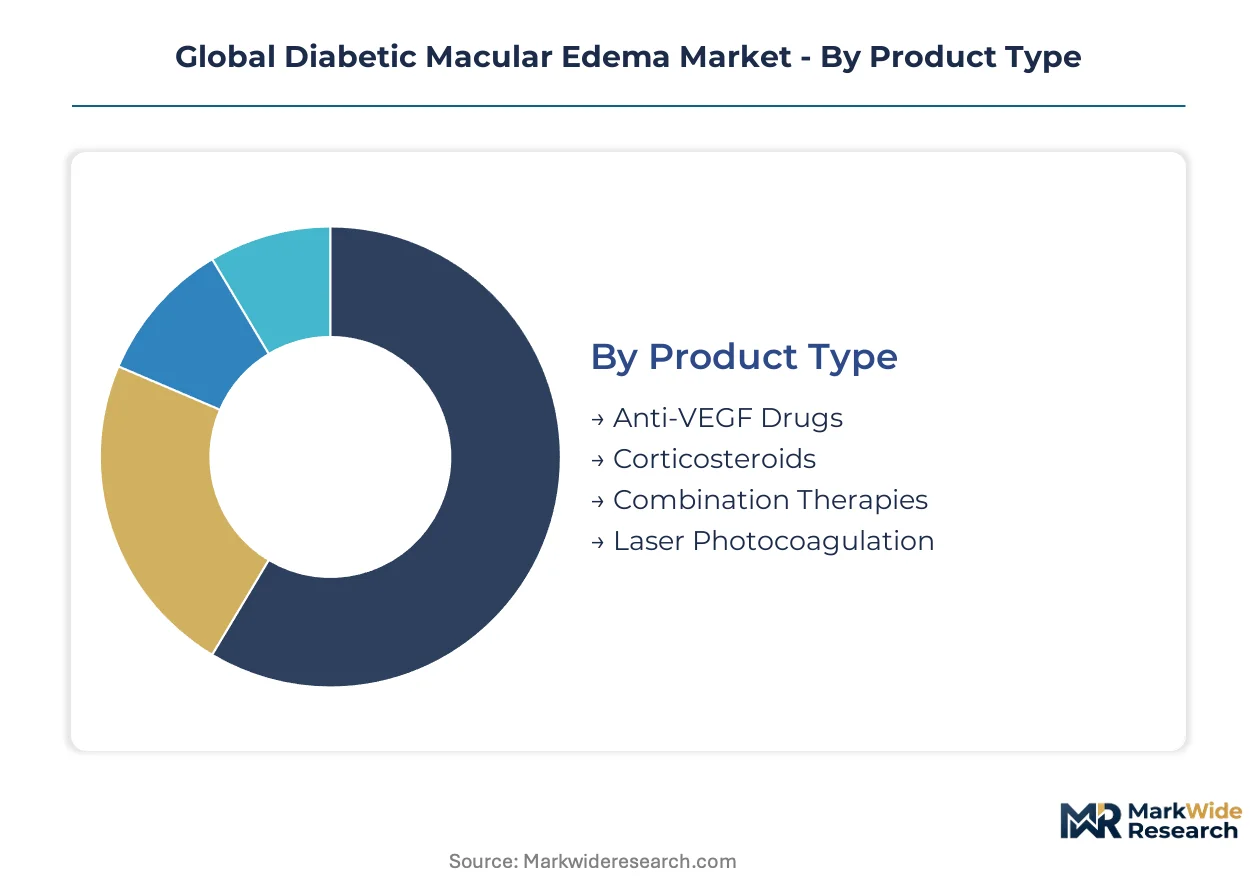
Diabetic macular edema treatment pathways diverge sharply across disease phenotype, care infrastructure, and pharmacological mechanism. Understanding these segmentation boundaries clarifies where sustained-release technologies displace conventional injection paradigms and which patient subpopulations drive premium pricing power.
Product Type:
Anti-VEGF drugs anchor the revenue base through established efficacy in center-involved presentations, while corticosteroids and combination formats carve distinct niches in treatment-resistant populations.
- Anti-VEGF Drugs:Monoclonal antibodies and fusion proteins that neutralize vascular endothelial growth factor isoforms to restore blood-retinal barrier integrity. Demand concentrates in the United States and Germany where payer formularies prioritize visual acuity preservation benchmarks established by pivotal clinical trials.
- Corticosteroids:Intravitreal and periocular steroid formulations targeting inflammatory mediators in chronic DME with significant macular thickening. Japanese ophthalmology clinics favor these agents for pseudophakic patients with persistent edema following anti-VEGF failure, driven by PMDA reimbursement carve-outs for steroid-refractory cases.
- Combination Therapies:Simultaneous or sequential anti-VEGF and corticosteroid protocols addressing mixed-mechanism disease.
- Laser Photocoagulation:Focal and grid laser applications for non-center-involved DME with discrete leakage patterns.
The dominant share belongs to Anti-VEGF Drugs, while Sustained-Release Implants (within Combination Therapies) is closing the gap fastest.
Therapy Area:
Disease anatomical classification determines reimbursement eligibility and treatment intensity, with center-involved status serving as the primary gateway for biologic coverage.
- Center-Involved DME:Macular thickening extending to the foveal center with measurable vision impairment; this phenotype commands the highest treatment priority and payer investment.
- Non-Center-Involved DME:Peripheral macular edema sparing the central 1mm zone; observation protocols dominate in France and the United Kingdom where treatment thresholds remain conservative.
- Chronic DME:Persistent edema beyond 12 months despite optimized therapy; sustained-release implants gain traction here as physicians seek to reduce injection burden.
- Recurrent DME:Re-emergence of macular thickening following initial treatment response; specialty hospitals in Germany manage these cases with combination drug-device protocols.
Center-Involved DME captures the majority of pharmaceutical expenditure, though Chronic DME is expanding most quickly as an addressable population.
Care Setting:
Site-of-service economics and procedural complexity shape where different technologies achieve adoption velocity.
- Ophthalmology Clinics:High-volume retina practices performing intravitreal injections under local anesthesia with same-day discharge.
- Specialty Hospitals:Academic medical centers managing complex recurrent cases and hosting port delivery system implantation procedures.
- Ambulatory Surgical Centers:Outpatient facilities capturing bundled reimbursement for laser photocoagulation and select injection services.
- Diagnostic Centers:Standalone imaging sites providing OCT monitoring that feeds treatment decisions across referral networks.
Ophthalmology Clinics retain the dominant procedural volume, while Specialty Hospitals are scaling fastest for implant-based interventions.
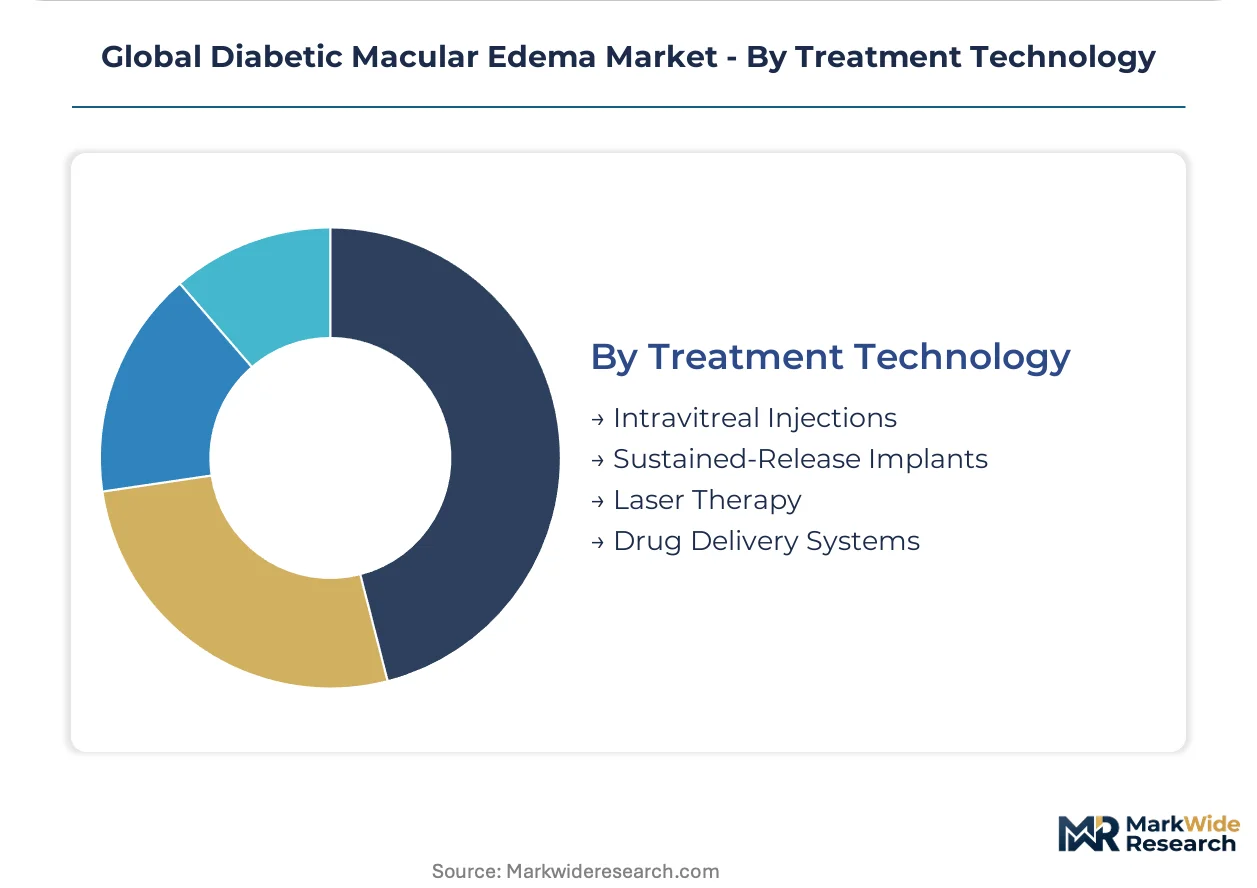
Treatment Technology:
Delivery mechanism innovation is compressing treatment intervals and redrawing competitive boundaries between pharmaceutical and device manufacturers.
- Intravitreal Injections:Direct anti-VEGF or corticosteroid administration into the vitreous cavity via pars plana puncture; monthly to quarterly dosing schedules dominate current practice patterns.
- Sustained-Release Implants:Biodegradable or non-biodegradable reservoirs releasing therapeutic agents over 6-36 months; United States academic centers pilot these for treatment-naive patients seeking reduced clinic visit burden.
- Laser Therapy:Photocoagulation targeting microaneurysms and areas of diffuse leakage.
- Drug Delivery Systems:Refillable port devices and alternative administration routes under clinical investigation.
Intravitreal Injections maintain procedure volume leadership, yet Sustained-Release Implants are gaining share fastest as chronic disease management infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States and Germany favor sustained-release implants for chronic cases, while Japan maintains distinct pharmacovigilance protocols that shape post-market commitments for intravitreal therapies.
United States
Ophthalmology clinics in Boston and New York Metro are expanding port delivery system pilots for treatment-naive patients. The FDA's accelerated approval pathways for anti-VEGF biosimilars are compressing exclusivity windows for reference products. Academic medical centers in California are pioneering refillable reservoir implants that reduce injection frequency from monthly to semi-annual intervals.
Germany
Specialty hospitals in Bavaria and North Rhine-Westphalia manage complex recurrent DME with combination drug-device protocols. The EU MDR's tightened technical documentation requirements for combination products extend certification timelines for implant manufacturers. Retina practices in Berlin-Brandenburg are unbundling diagnostic OCT imaging from therapeutic administration to optimize reimbursement capture.
Japan
Japanese ophthalmology clinics favor corticosteroids for pseudophakic patients with persistent edema following anti-VEGF failure. PMDA pharmacovigilance reporting thresholds for intravitreal therapies influence post-market study commitments for novel formulations. Tokyo and Osaka medical centers are piloting sustained-release alternatives to reduce clinic visit burden for aging diabetic populations.
United Kingdom
Observation protocols dominate for non-center-involved DME in London and Southeast England, where treatment thresholds remain conservative. The National Institute for Health and Care Excellence calibrates access decisions for emerging sustained-release formulations against established anti-VEGF benchmarks. Midlands retina specialists are adopting diagnostic-therapeutic pairing to create stickier care pathways.
India
Urban clinical catchment areas in Maharashtra and Karnataka are expanding the addressable patient base for macular edema interventions as diabetic populations rise. CDSCO regulatory pathways for ophthalmic biologics are streamlining as domestic manufacturing capacity for active pharmaceutical ingredients scales. Hyderabad and Mumbai ophthalmology chains are investing in vitreoretinal surgeon training programs to address injection technique specialization gaps.
Global Diabetic Macular Edema Market Competitive Landscape
Capability concentration sits with integrated biologics manufacturers; scale advantage sits with diversified pharmaceutical conglomerates. The market exhibits tiered structure with originator anti-VEGF developers defending position through formulation differentiation, while device-specialist entrants capture value on delivery innovation. Two archetypes dominate: captive monoclonal antibody producers with vertical supply control, and diagnostic-therapeutic integrators bundling imaging with therapy decisions. Competitive moves center on sustained-release line extensions and strategic partnerships combining drug reservoirs with refillable port technologies.
Within the integrated biologics tier, Regeneron Pharmaceuticals and Roche Holding AG exemplify divergent defensive strategies. Regeneron anchors its position through captive aflibercept production and supply chain verticality. Roche occupies a position as diagnostic-therapeutic integrator, pairing OCT imaging infrastructure with ranibizumab therapy protocols. Among diversified device-pharma hybrids, Bausch & Lomb and Carl Zeiss Meditec AG represent the convergence of ophthalmic equipment manufacturing with therapeutic delivery system development.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| Bausch & Lomb |
| Roche Holding AG |
| Topcon Corporation |
| Allergan plc |
| Bayer AG |
| Carl Zeiss Meditec AG |
| Santen Pharmaceutical Co. Ltd. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
North American captive monoclonal antibody production concentrates margin pools with integrated biologics manufacturers who command premium positioning for anti-VEGF originators, while biosimilar entrants compress pricing power in commercial payer segments through accelerated FDA approval pathways.
Pricing Analysis
Long-term offtake agreements between ophthalmology clinic networks and biologics manufacturers anchor pricing stability for reference anti-VEGF products, while spot procurement for corticosteroid alternatives introduces volatility. Three-tier pricing structure across originator biologics, biosimilars, and corticosteroid alternatives reflects FDA certification tier and volume commitment scale. Cost compression in the biosimilar tier intensifies as FDA accelerated pathways expand substitution eligibility. Government payers exhibit highest price sensitivity; specialty hospitals managing complex recurrent cases demonstrate lowest sensitivity due to bundled reimbursement capture.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for sustained-release implant manufacturers navigating EU MDR certification timelines. Active pharmaceutical ingredient production concentrates in the United States, Switzerland, and Japan for monoclonal antibody biologics; polymeric reservoir components draw from Germany and the United States. Single-source vulnerability persists for aflibercept fusion protein cell lines held in captive North American facilities. Distribution runs through cold-chain logistics networks serving ophthalmology clinics and specialty hospital pharmacy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diabetic macular edema market is recovering from biosimilar-driven pricing compression as sustained-release technologies reset value benchmarks and physician preference shifts toward chronic disease management infrastructure.
For Market Incumbents: Build diagnostic-therapeutic integration moats by bundling OCT imaging protocols with anti-VEGF therapy decisions to create stickier clinic relationships and defend against biosimilar substitution pressure. Deepen backward integration into sustained-release implant manufacturing to capture device margins and differentiate originator portfolios beyond patent protection alone. Prioritize EU MDR technical documentation investment to accelerate combination product certification timelines. For New Entrants and Emerging Players: Build out underpenetrated specialty hospital channels in France and the United Kingdom where recurrent DME case volumes exceed current sustained-release implant adoption. Target corticosteroid-refractory patient populations in Japanese ophthalmology clinics where PMDA reimbursement carve-outs create accessible entry points. Pursue go-to-market partnerships with academic medical centers piloting port delivery systems to leverage clinical validation infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward device-pharma hybrids possessing both ophthalmic equipment manufacturing expertise and therapeutic delivery system development capabilities across the medium-term investment horizon. Acquisition candidates with refillable reservoir technology and established surgeon training programs present strongest defensive positioning. Monitor FDA ophthalmic biosimilar approval velocity as inflection indicator for originator pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Sustained-Release Line Extension | Originator manufacturers extend anti-VEGF franchises through 6-36 month implant formulations reducing injection burden. |
| EU MDR Combination Product Certification | Implant manufacturers navigate tightened technical documentation requirements to access German and French hospital markets. |
| OCT Imaging Protocol Integration | Diagnostic-therapeutic bundling creates stickier care pathways in United States retina practices and academic centers. |
| Port Delivery System Pilot Expansion | Academic medical centers in California and Bavaria test refillable reservoir implants for treatment-naive patient cohorts. |
| Biosimilar Accelerated Approval Pathway | FDA review standards compress exclusivity windows and force formulation differentiation strategies among originators. |
Research Methodology
A spread of perspectives from vitreoretinal surgeons, biologics manufacturing executives, hospital pharmacy directors, and payer formulary managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA biologics licensing filings, EMA marketing authorization submissions, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation anchored volume and value estimates.
Demand-supply balance dynamics across anti-VEGF originators, biosimilars, and sustained-release alternatives structured the analytical framework over the projection horizon. Segmentation dimensions modeled include treatment technology, disease phenotype, care setting, and regional regulatory cluster. CAGRs were derived from patient population growth trajectories, therapy penetration curves, and pricing evolution assumptions. Forecast inputs incorporated diabetic prevalence projections, ophthalmologist injection capacity constraints, and reimbursement policy calibration patterns.
Stress conditions across biosimilar substitution rates, sustained-release adoption velocity, and EU MDR certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about physician preference evolution and payer access decisions. Macroeconomic contraction, regulatory pathway disruption, or sustained-release implant safety signals would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Synoptophore Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Dacryocystitis Market