
 Excimer and Femtosecond Ophthalmic Lasers Market | 2026-2036
Excimer and Femtosecond Ophthalmic Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Excimer and Femtosecond Ophthalmic Lasers Market Foresight
The split between premium femtosecond platforms and commodity excimer configurations is realigning procurement patterns across eye care networks. Carl Zeiss Meditec AG leverages its integrated diagnostics-to-surgery workflow to dominate high-end cataract and refractive segments. Alcon Inc. competes through its broad ophthalmic portfolio that anchors hospital system contracts. NIDEK Co., Ltd. specializes in excimer technology that occupies a defensible position in cost-sensitive clinics across Asia.
Excimer and femtosecond ophthalmic lasers generate ultraviolet or ultrafast infrared pulses to reshape corneal tissue or create precise lenticular cuts without thermal damage, operating at wavelengths near 193 nm for excimers and 1030-1055 nm for femtosecond systems with pulse durations below 500 femtoseconds. Their primary commercial purpose centers on vision correction procedures including LASIK, SMILE, and femtosecond-assisted cataract extraction that demand sub-micron tissue accuracy. Femtosecond laser systems command the highest margin pools as cataract surgery adoption accelerates in ambulatory settings, while excimer platforms retain volume leadership in refractive surgery across independent eye care practices. Wavefront-optimized technology differentiates premium offerings as topography-guided systems gain traction among surgeons seeking personalized ablation profiles.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern commercial entry for these devices, with both frameworks demanding rigorous clinical validation of optical safety and tissue interaction profiles. The EU AI Act introduces emerging compliance dimensions for software-integrated laser platforms that incorporate real-time imaging guidance. Stakeholders must monitor how regulatory divergence between US and European conformity assessment timelines reshapes product launch sequencing and geographic revenue mix.
Market Dynamics
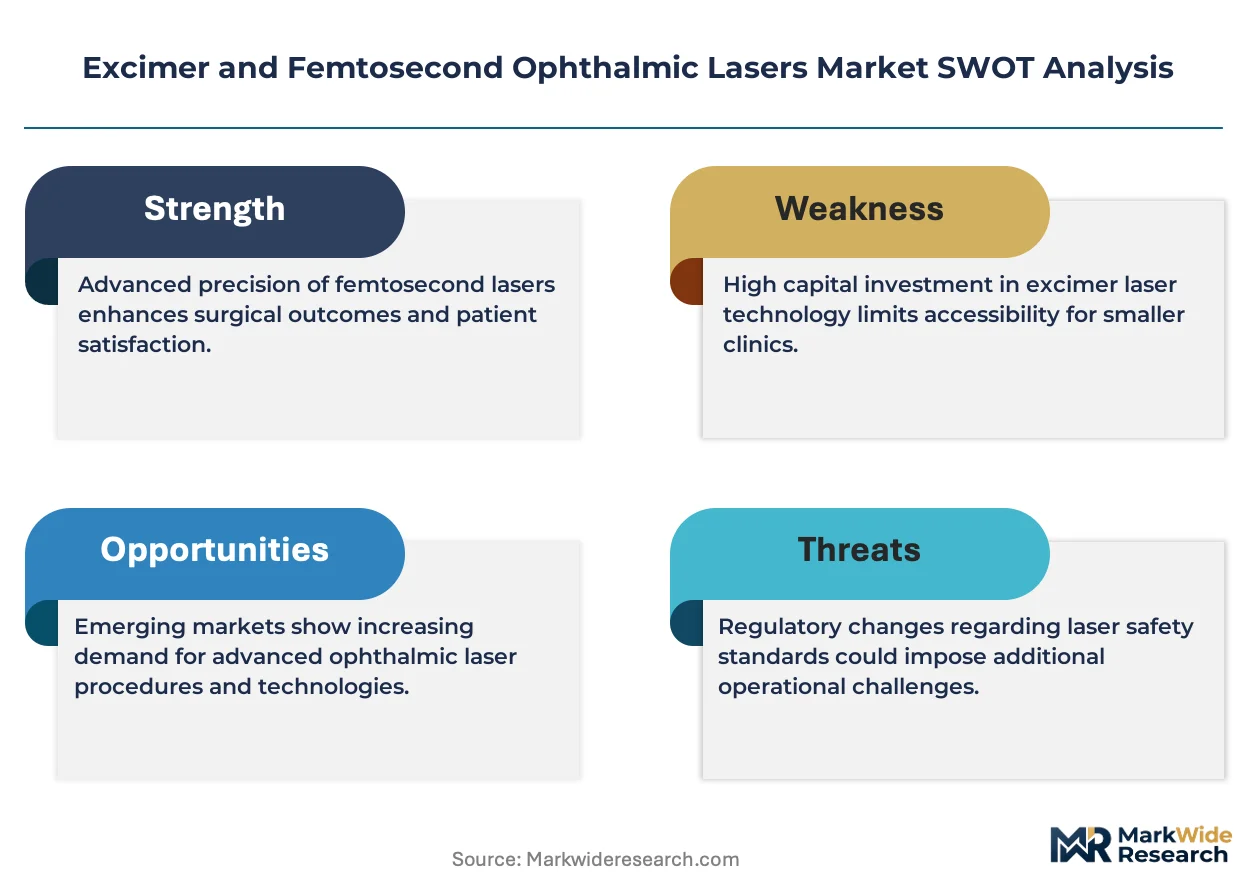
Femtosecond laser platforms are compressing excimer system margins as ambulatory surgical centers consolidate procurement around integrated diagnostic-surgical workflows. This technology displacement is restructuring competitive positioning across premium and mid-tier ophthalmic laser segments.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating CE marking renewals for software-integrated laser platforms are capturing hospital system contracts ahead of competitor recertification lags.
- SMILE procedure adoption:Small-incision lenticule extraction in independent eye care practices is driving femtosecond laser placements that displace traditional LASIK workflows.
- Japan's aging demographic:Cataract surgery volume concentration in metropolitan Tokyo and Osaka clusters is sustaining premium femtosecond platform demand despite capital expenditure pressures.
Market Restraints
- Capital intensity barriers:Femtosecond laser systems requiring seven-figure USD investments restrict independent practice adoption to consolidated eye care networks with balance sheet capacity.
- German component supply concentration:Precision optical subsystems from Stuttgart and Munich manufacturing clusters create single-source vulnerability for non-integrated laser OEMs.
- Excimer wavelength limitations:193 nm ultraviolet ablation constraints on stromal tissue thickness restrict treatment eligibility for high-myopia patient segments.
Strategic Opportunities
- India's tier-two city expansion:Underpenetrated refractive surgery markets in Hyderabad and Chennai present first-mover positioning for cost-optimized excimer configurations.
- AI-guided ablation convergence:Real-time topography integration with wavefront-optimized lasers enables personalized treatment protocols that command premium pricing.
- Outcome-based reimbursement pilots:Medicare Advantage vision benefit expansions in Florida and Texas are testing value-based cataract surgery models favoring femtosecond precision outcomes.
Industry Challenges
- Femtosecond engineer scarcity:Ultrafast laser physics specialization shortages in Boston and San Diego clusters constrain OEM R&D scaling and field service network buildout.
- FDA 510(k) timeline compression:Software-as-medical-device classification uncertainties for AI-integrated guidance systems are extending premarket notification review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excimer and Femtosecond Ophthalmic Lasers Market |
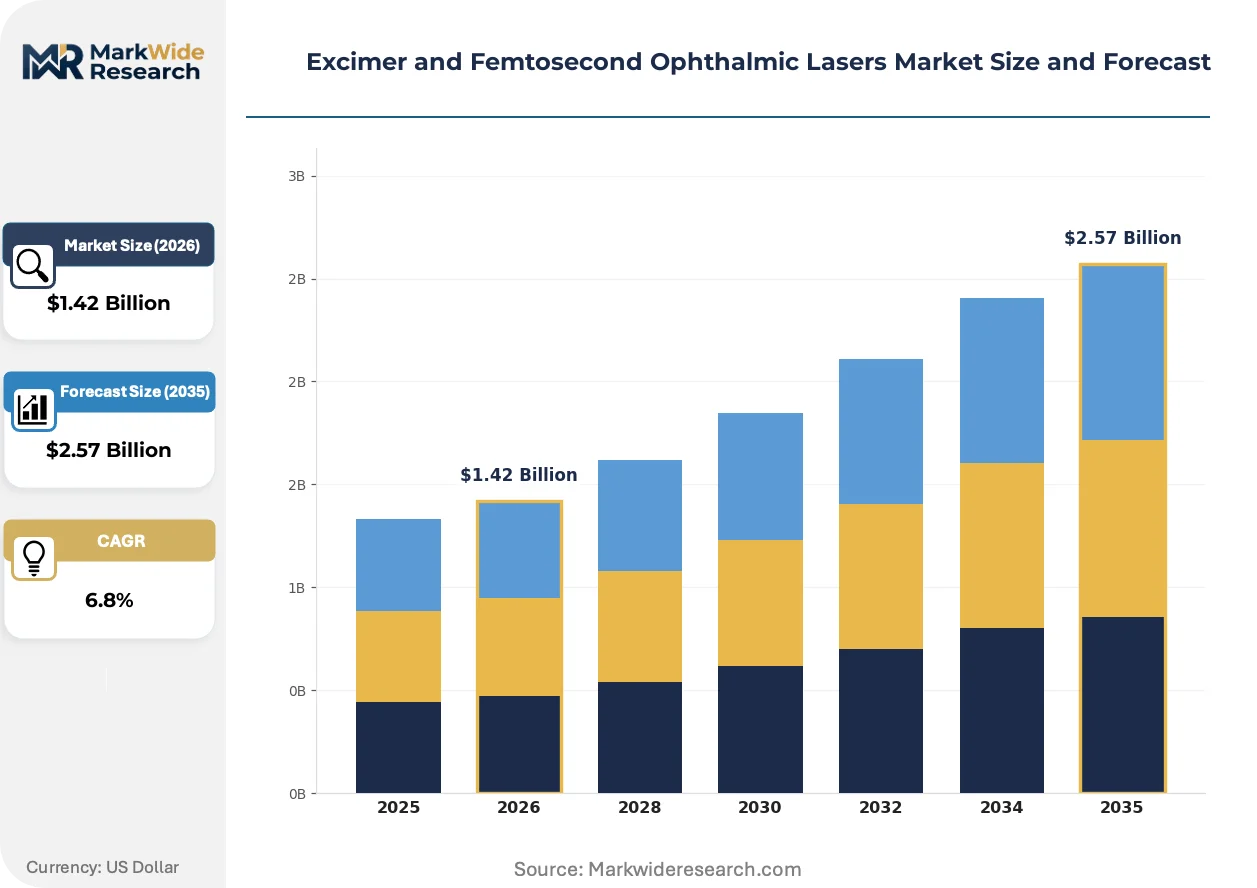
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
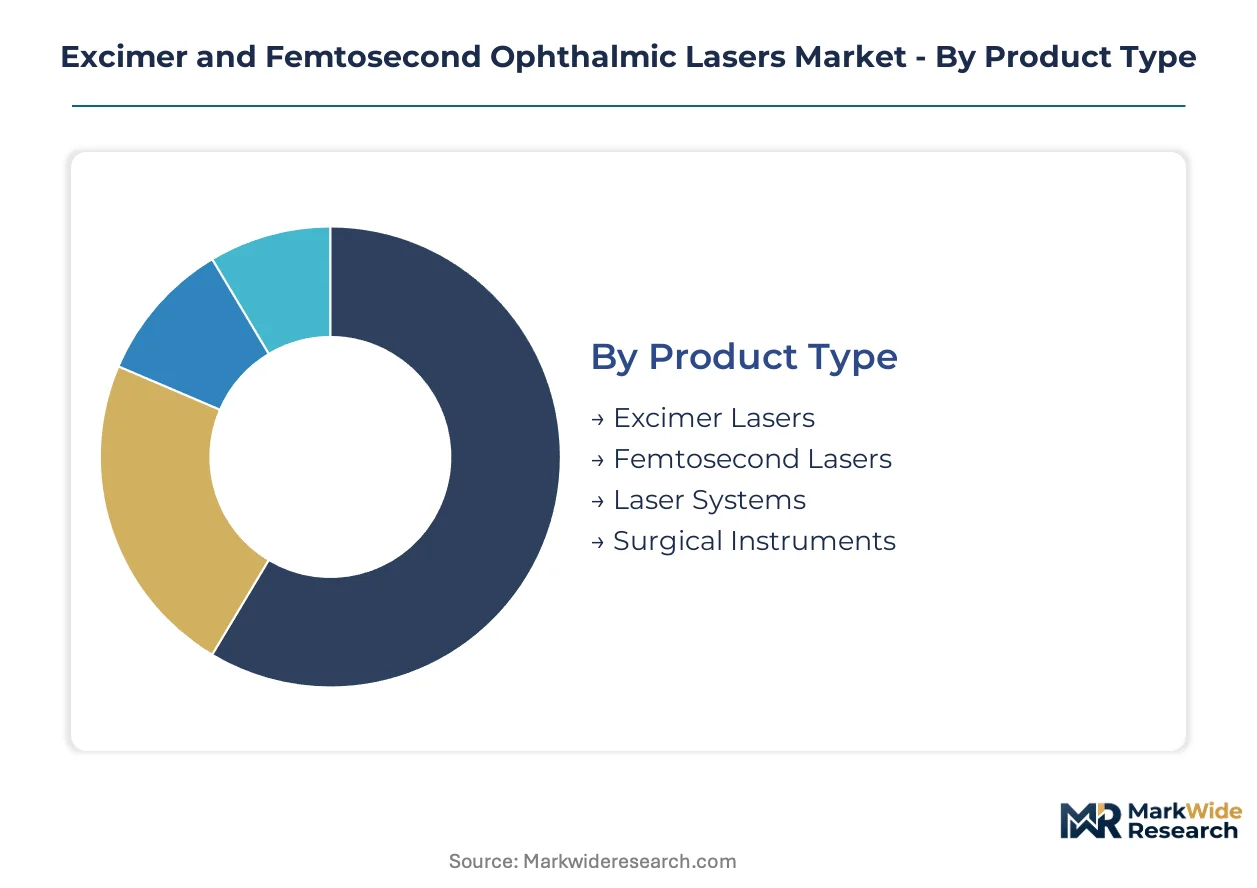
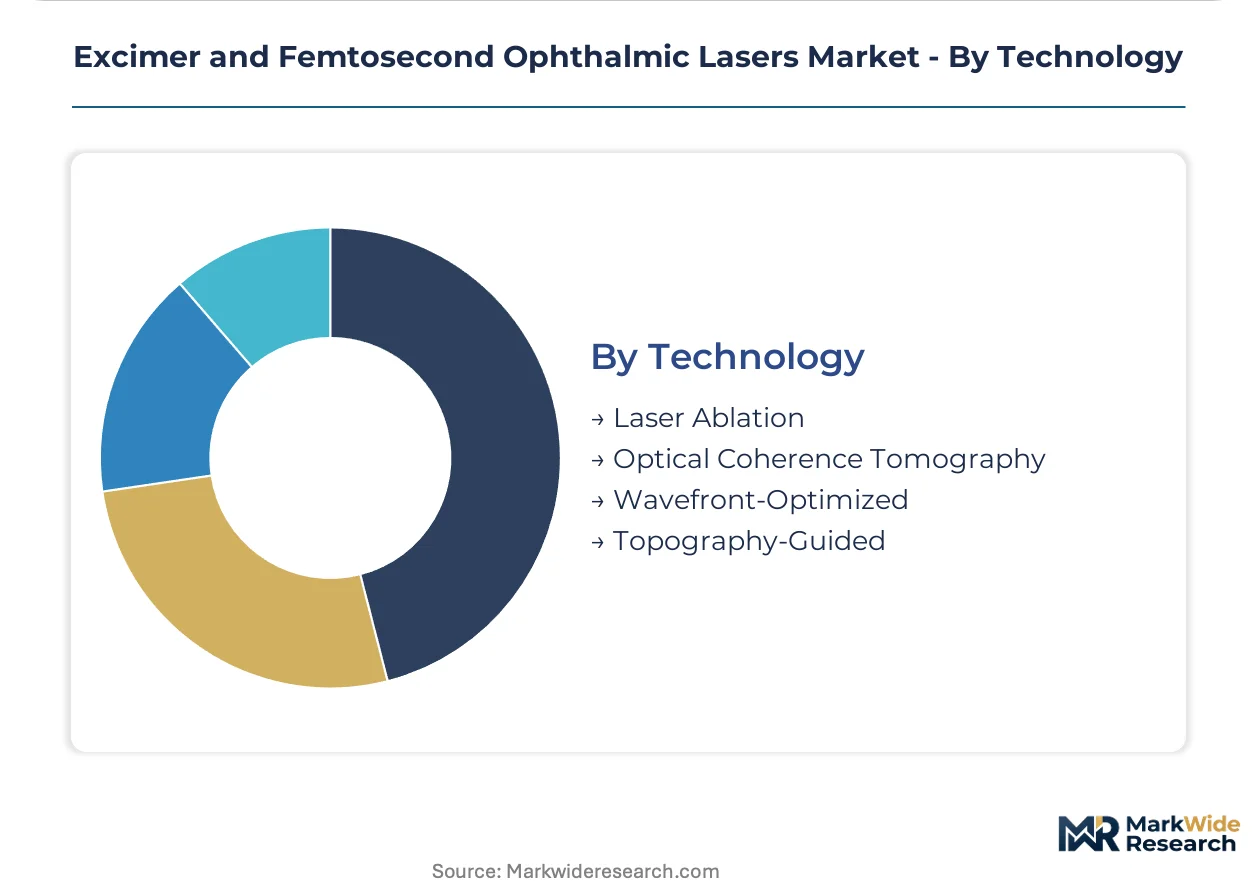
| Segmentation | Product Type: Excimer Lasers, Femtosecond Lasers, Laser Systems, Surgical Instruments End User: Hospitals, Clinics, Ambulatory Surgical Centers, Independent Eye Care Practices Application: Refractive Surgery, Cataract Surgery, Corneal Procedures, Therapeutic Applications Technology: Laser Ablation, Optical Coherence Tomography, Wavefront-Optimized, Topography-Guided |
| Companies Covered | Carl Zeiss Meditec AG, Alcon Inc., NIDEK Co., Ltd., Bausch + Lomb, Ziemer Ophthalmic Systems AG, SCHWIND eye-tech-solutions, iVis Technologies, Topcon Corporation, Ellex Medical Lasers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excimer and Femtosecond Ophthalmic Lasers Market Shifts & Advancements
Diagnostic-surgical platform integration is collapsing standalone laser procurement cycles. Surgeons now expect seamless topography-to-ablation workflows that compress operating room time and reduce manual alignment errors.
Topography-guided ablation mapping is overtaking wavefront-optimized systems in premium refractive segments. Academic medical centers in the United States and university hospitals in Germany are adopting these platforms for complex corneal irregularity cases. This precision capability is compressing revision surgery rates and extending equipment depreciation schedules.
EU AI Act risk classification for real-time surgical guidance software is reshaping conformity assessment pathways. Laser OEMs must now document algorithmic transparency and clinical validation datasets for CE marking renewals. Femtosecond platforms with embedded anterior segment imaging face the steepest compliance cost escalations.
Hospital system procurement consolidation is displacing independent practice purchasing autonomy. Integrated delivery networks in California and Texas are negotiating enterprise femtosecond contracts that bundle diagnostics, lasers, and maintenance. This channel concentration is marginalizing regional distributors and compressing price negotiation leverage for standalone clinics.
Excimer and Femtosecond Ophthalmic Lasers Market Segmentation
Procurement patterns across ophthalmic laser markets diverge sharply by product configuration and care setting. Capital deployment decisions, reimbursement pathways, and surgeon training requirements create distinct demand profiles that reshape competitive positioning within each segment cluster.
Product Type:
Supply concentration in femtosecond platforms favors integrated OEMs with captive optical component production, while excimer sourcing fragments across independent subsystem vendors.
- Femtosecond Lasers:Ultrafast infrared pulse systems operating at 1030-1055 nm with sub-500 femtosecond durations enable precise lenticular cuts without thermal damage. Demand concentrates in ambulatory surgical centers across the United States and Germany where cataract surgery volume justifies seven-figure capital investments. SMILE procedure adoption in independent Tokyo and Osaka eye clinics sustains premium platform placements despite reimbursement compression.
- Excimer Lasers:Ultraviolet ablation systems at 193 nm reshape corneal stroma through photochemical decomposition rather than thermal burning. Volume leadership persists in cost-sensitive independent eye care practices across India and Southeast Asia where LASIK remains the dominant refractive workflow. German precision optical subsystems from Stuttgart manufacturing clusters create single-source vulnerability for non-integrated OEMs.
- Laser Systems:Integrated diagnostic-surgical platforms bundle imaging, planning, and ablation hardware into unified capital purchases.
- Surgical Instruments:Consumable and reusable adjunct devices including patient interfaces, suction rings, and disposables.
Today's leader: Femtosecond Lasers. Tomorrow's challenger: Excimer Lasers.
End User:
Customer type determines procurement scale, with consolidated networks extracting volume discounts that standalone practices cannot match.
- Ambulatory Surgical Centers:Freestanding facilities specializing in same-day ophthalmic procedures command the steepest femtosecond laser adoption curves. California and Texas integrated delivery networks negotiate enterprise contracts bundling diagnostics, lasers, and maintenance, compressing price negotiation leverage for independent clinics. Outcome-based reimbursement pilots through Medicare Advantage vision benefit expansions test value-based cataract surgery models.
- Hospitals:Academic medical centers and university hospitals in the United States and Germany adopt topography-guided platforms for complex corneal irregularity cases. EU MDR compliance deadlines for software-integrated laser platforms are capturing hospital system contracts ahead of competitor recertification lags. Precision capability compresses revision surgery rates and extends equipment depreciation schedules.
- Independent Eye Care Practices:Solo and small-group ophthalmology clinics drive excimer laser volume through LASIK workflows.
- Clinics:Multi-specialty outpatient facilities with limited ophthalmic service lines.
Procurement gravity centers on Ambulatory Surgical Centers. Volume expansion is climbing the fastest in Independent Eye Care Practices.
Application:
Margin structure varies by procedure complexity, with refractive surgery commanding premium pricing and cataract surgery driving installed base expansion.
- Refractive Surgery:LASIK, PRK, and SMILE procedures correct myopia, hyperopia, and astigmatism through corneal reshaping. Wavefront-optimized technology differentiates premium offerings as topography-guided systems gain traction among surgeons seeking personalized ablation profiles. Japan's aging demographic sustains procedure volume despite capital expenditure pressures.
- Cataract Surgery:Femtosecond laser-assisted capsulotomy and lens fragmentation demand sub-micron tissue accuracy. FDA 510(k) clearance pathways govern commercial entry with rigorous clinical validation of optical safety and tissue interaction profiles. Real-time anterior segment imaging integration faces steep EU AI Act compliance cost escalations.
- Corneal Procedures:Therapeutic and reconstructive interventions including cross-linking and transplant preparation.
- Therapeutic Applications:Glaucoma and retinal laser treatments extending platform utilization beyond anterior segment surgery.
Revenue concentration favors Refractive Surgery. Cataract Surgery is gaining share fastest through ambulatory setting consolidation.
Technology:
Software-hardware integration intensity determines regulatory pathway complexity and compliance cost structure across technology tiers.
- Topography-Guided:Corneal surface mapping enables personalized ablation profiles based on individual elevation data rather than wavefront measurements alone. Academic medical centers in Germany and the United States adopt these platforms for complex irregularity cases. EU AI Act risk classification for real-time surgical guidance software reshapes conformity assessment pathways with algorithmic transparency documentation requirements.
- Wavefront-Optimized:Aberration-corrected ablation profiles reduce induced optical distortions compared to conventional treatments. FDA 510(k) timeline compression for software-as-medical-device classification uncertainties extends premarket notification review cycles for AI-integrated guidance systems. Established reimbursement codes support broad commercial deployment.
- Laser Ablation:Core tissue removal mechanisms spanning excimer photochemical and femtosecond photodisruption approaches.
- Optical Coherence Tomography:Real-time imaging guidance integrated into surgical planning and intraoperative monitoring.
Clinical validation concentration favors Wavefront-Optimized. Topography-Guided represents the steepest expansion trajectory through precision differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium femtosecond platform placements through Stuttgart precision optics clusters, while India's cost-sensitive markets sustain excimer volume leadership across Hyderabad and Chennai refractory surgery networks.
United States
Medicare Advantage vision benefit expansions in Florida and Texas test outcome-based cataract surgery models favoring femtosecond precision. FDA 510(k) clearance pathways govern commercial entry with rigorous optical safety validation requirements. Boston and San Diego ultrafast laser physics clusters constrain OEM R&D scaling through specialist engineer scarcity.
Germany
University hospitals in Munich and Heidelberg adopt topography-guided platforms for complex corneal irregularity cases. EU MDR compliance deadlines for software-integrated laser platforms capture hospital system contracts ahead of competitor recertification lags. Stuttgart precision optical subsystems create single-source vulnerability for non-integrated laser OEMs.
Japan
Metropolitan Tokyo and Osaka cataract surgery volume clusters sustain premium femtosecond platform demand despite capital expenditure pressures. METI standards coordination shapes domestic procurement specifications for anterior segment imaging integration. Kanto region aging demographics concentrate procedure demand in urban tertiary centers.
India
Hyderabad and Chennai tier-two city expansion presents first-mover positioning for cost-optimized excimer configurations. CDSCO medical device registration pathways govern import licensing for ultraviolet ablation systems. Tamil Nadu and Telangana independent eye care practices drive LASIK workflow volume through capital-efficient procurement.
China
Yangtze River Delta metropolitan hospital networks consolidate procurement around integrated diagnostic-surgical workflows. NMPA medical device approval timelines shape product launch sequencing against CE marking and FDA clearance benchmarks. Shanghai ophthalmology centers adopt femtosecond-assisted cataract extraction at accelerating rates.
Excimer and Femtosecond Ophthalmic Lasers Market Competitive Landscape
Top-tier vendors anchor integrated diagnostics-to-surgery workflows, while mid-tier specialists compete on cost-optimized excimer configurations for independent practices. The market structure concentrates around optical subsystem integration capabilities and hospital system contract bundling. Three archetypes dominate: integrated platform OEMs with captive component production, standalone laser specialists with regional distribution depth, and diversified ophthalmic portfolio holders anchoring multi-product contracts. Competitive moves center on diagnostic-surgical platform convergence and ambulatory surgical center enterprise contract consolidation.
Among Germany-based precision optics fabricators, Carl Zeiss Meditec AG and SCHWIND eye-tech-solutions occupy positions within the integrated workflow tier. Swiss-domiciled Alcon Inc. exemplifies the diversified portfolio archetype through broad ophthalmic product anchoring. Japan-based NIDEK Co., Ltd. represents the excimer specialization segment with defensible positioning across Asia-Pacific cost-sensitive clinics. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive vectors in ophthalmic laser markets.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Alcon Inc. |
| NIDEK Co., Ltd. |
| Bausch + Lomb |
| Ziemer Ophthalmic Systems AG |
| SCHWIND eye-tech-solutions |
| iVis Technologies |
| Topcon Corporation |
| Ellex Medical Lasers |
| Others |
Supply & Pricing Matrix
Femtosecond laser platform integration with real-time imaging guidance simultaneously compresses per-procedure cost economics and concentrates procurement leverage within integrated delivery networks. This diagnostic-surgical convergence reshapes how capital equipment vendors structure bundled service contracts and component sourcing strategies.
Pricing Analysis
Bundled diagnostic-surgical workflows versus standalone laser purchases split procurement economics across buyer segments. Three-tier pricing structure across premium, standard, and economy levels separates femtosecond platforms with embedded OCT guidance from excimer configurations with basic wavefront optimization. Price differentiation hinges on software certification tier under FDA 510(k) and EU MDR pathways, plus after-sales service bundling intensity. Pricing pressure stems from ambulatory surgical center consolidation negotiating enterprise contracts. Independent eye care practices exhibit highest price sensitivity, while academic medical centers prioritize precision outcomes over capital cost.
Supply Chain Analysis
Precision optical subsystems rest on German specialty manufacturing clusters in Stuttgart and Munich, with secondary sourcing from Swiss and Japanese precision optics fabricators. Ultrafast laser oscillators, deformable mirrors, and ultraviolet-grade fused silica optics constitute critical component dependencies. Single-source vulnerability concentrates in excimer laser optical trains where Stuttgart suppliers dominate. Distribution runs through regional medical device distributors serving hospital systems, with direct OEM relationships commanding ambulatory surgical center enterprise contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as aging demographics in developed economies sustain cataract surgery volume growth. Procedure demand exhibits low cyclicality and strong reimbursement anchoring.
For Market Incumbents: Anchor hospital system contracts through EU MDR compliance acceleration ahead of competitor recertification lags. Deepen captive production of precision optical subsystems to offset Stuttgart supply concentration risk. Defend against SMILE procedure displacement of traditional LASIK by integrating topography-guided ablation into premium femtosecond platforms. For New Entrants and Emerging Players: The gap between seven-figure femtosecond investments and sub-six-figure excimer configurations creates entry space for cost-optimized ultraviolet ablation systems. Target India's tier-two city expansion in Hyderabad and Chennai where LASIK volume runs through capital-constrained independent practices. Pursue CDSCO registration pathways for import licensing acceleration. For Investors and Strategic Acquirers: Valuations sit cheapest among excimer-specialist OEMs with Asia-Pacific distribution depth and software-integrated platform upgrade roadmaps. Five-to-ten year viability hinges on femtosecond platform adoption curves in ambulatory settings. Watch Medicare Advantage vision benefit expansion rates in Florida and Texas as inflection signals for outcome-based reimbursement traction.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | CE marking renewals for software-integrated platforms capture hospital contracts ahead of laggard competitors. |
| Diagnostic-Surgical Platform Integration | Seamless topography-to-ablation workflows compress operating room time and reduce manual alignment errors. |
| Backward Integration into Precision Optics | In-house production of ultraviolet-grade fused silica reduces Stuttgart supply concentration vulnerability. |
| SMILE Procedure Training Network Buildout | Surgeon certification programs in Tokyo and Osaka sustain premium femtosecond platform placements. |
| India Tier-Two City Distribution Partnership | Regional distributor alliances in Telangana and Tamil Nadu unlock cost-sensitive excimer volume. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered femtosecond laser physicists, ambulatory surgical center procurement directors, hospital biomedical engineers, GPO contracts managers, and refractive surgery clinic owners. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare procedure volume data, and NMPA medical device approval records. Bottom-up installed base modeling and top-down procedure volume estimates triangulated market sizing.
Historical reference periods anchored the projection horizon through backward extrapolation of femtosecond platform placement rates and excimer system replacement cycles. Segmentation dimensions spanned product type, end-user facility scale, application complexity, and technology integration intensity. CAGRs derived from procedure volume growth curves weighted by reimbursement pathway stability. Forecast inputs incorporated aging demographic trajectories and regulatory compliance deadline impacts.
Caveats apply where EU AI Act risk classification revisions or FDA software-as-medical-device guidance shifts could materially shift the outlook. Assumptions reflect current reimbursement coding and regulatory pathway stability. A small set of named triggers warrants ongoing watch: Medicare Advantage vision benefit expansion rates, EU MDR recertification bottleneck severity, and femtosecond engineer scarcity in Boston and San Diego clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market