
 Europe Dry Eye Syndrome Market | 2026-2036
Europe Dry Eye Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dry Eye Syndrome Market Intelligence
Ophthalmic specialist staffing is rotating toward dry eye subspecialties across European hospital systems, creating localized capacity bottlenecks in France and Italy. Alcon leverages its surgical and pharmaceutical portfolios to dominate device-based delivery corridors. AbbVie Inc (Allergan) sustains brand loyalty among prescribing ophthalmologists through its established immunomodulatory franchise. Santen Pharmaceutical Co Ltd anchors its position via dedicated ocular surface disease expertise and targeted clinician education programs.
Dry eye syndrome denotes a multifactorial disorder of the tear film characterized by tear hyperosmolarity, ocular surface inflammation, and instability of the lipid, aqueous, or mucin layers, typically quantified through osmolarity testing above 308 mOsm/L or corneal staining scores. Its primary purpose is to restore homeostasis to the ocular surface, prevent epithelial damage, and preserve visual function in patients with aqueous deficiency, evaporative loss, or mixed mechanisms. Artificial Tears and Prescription Medications together occupy the core of the European revenue pool, though lipid-based formulations are gaining fastest as meibomian gland dysfunction recognition spreads among optometrists. Device-Based delivery, including intense pulsed light and thermal pulsation systems, is carving out premium positioning in high-volume clinic settings where reimbursement pathways have stabilized.
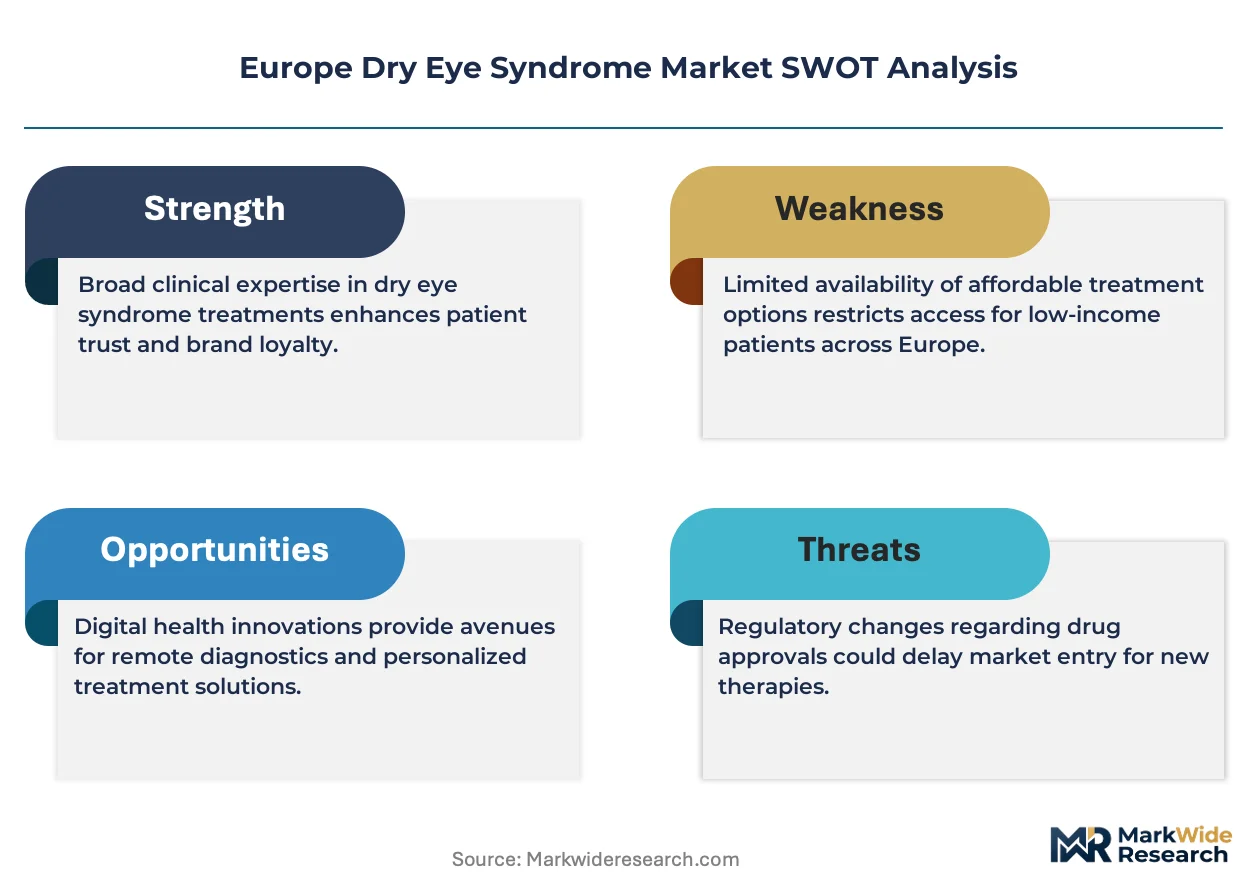
The EU Medical Device Regulation and EMA centralized marketing authorization procedures shape product entry timelines and clinical evidence requirements for invasive therapies across member states. Germany's national reimbursement body, the G-BA, alongside France's HAS, determines access speed for novel prescription medications and surgical interventions in the two largest national markets. Stakeholders must monitor evolving HTA convergence between France, Germany, and Italy, as divergent evidence thresholds will fragment commercialization strategies regardless of unified CE marking status.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing market entry timelines for invasive therapies while simultaneously fragmenting reimbursement pathways across national health technology assessment bodies. This regulatory tightening is forcing manufacturers to front-load clinical evidence generation and localize commercialization strategies.
Growth Catalysts
- Meibomian gland dysfunction recognition:Optometrists across France and Germany are screening for evaporative dry eye subtypes, expanding the addressable patient pool for lipid-based therapeutics.
- EMA centralized marketing authorization:Streamlined pathways for prescription medications accelerate cross-border commercialization once Germany's G-BA establishes reimbursement precedent.
- Ophthalmology clinic consolidation:Metropolitan hospital networks in Berlin and Paris are building dedicated dry eye service lines, concentrating demand for premium device-based therapies.
Market Restraints
- CE marking cost escalation:The EU MDR's enhanced clinical evidence requirements for punctal plugs and thermal devices have doubled notified body review timelines.
- Reimbursement fragmentation:France's HAS maintains divergent evidence thresholds from Germany's G-BA, forcing parallel health technology assessment submissions.
- Active pharmaceutical ingredient concentration:Cyclosporine and lifitegrast supply chains cluster among contract manufacturers in Switzerland and Ireland, creating single-source vulnerabilities.
Strategic Opportunities
- Italy's underpenetrated cornea specialty networks:Northern Italian hospital systems lack dedicated ocular surface disease units, presenting first-mover positioning for device-based therapy providers.
- Teleophthalmology integration:Remote tear osmolarity monitoring combined with AI-driven severity scoring enables patient triage before clinic referral.
- HTA convergence lobbying:Industry coalitions are pressing for aligned evidence standards between France, Germany, and Italy to reduce commercialization friction.
Industry Challenges
- Ocular surface disease specialist scarcity:Fellowship-trained cornea specialists are rotating toward surgical subspecialties, leaving dry eye management to general ophthalmologists with limited therapeutic familiarity.
- Device-service integration complexity:Thermal pulsation and intense pulsed light systems require technician training protocols that clash with existing clinic workflows in Spain and Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dry Eye Syndrome Market |
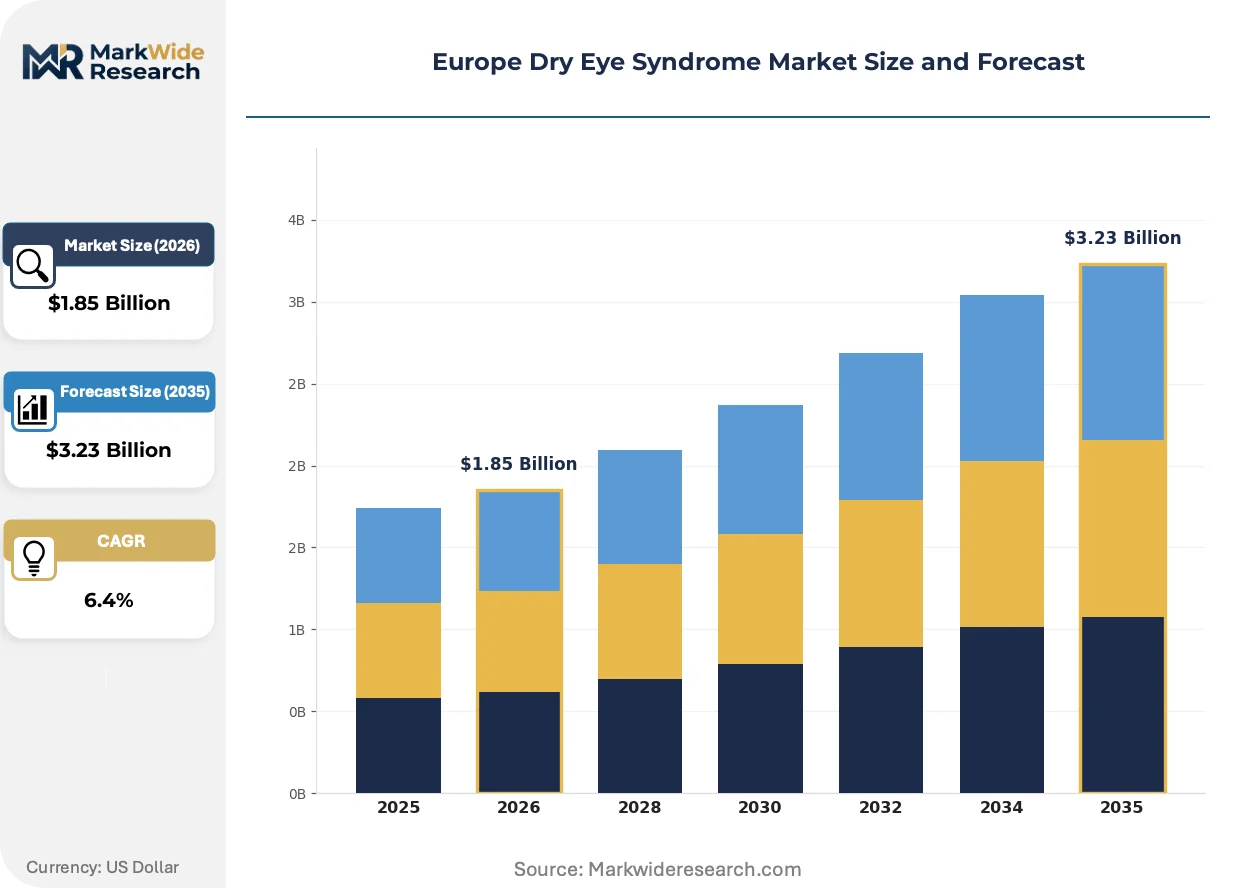
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Prescription Medications, Punctal Plugs, Lipid-Based Drops Delivery Mode: Topical, Injectable, Surgical, Device-Based User Type: Ophthalmologists, Optometrists, Clinicians, Home Care Providers End Use: Hospital, Clinic, Homecare, Research Labs |
| Companies Covered | Alcon, Bausch & Lomb, AbbVie Inc (Allergan), Otsuka Pharmaceutical Co Ltd, Sun Pharmaceutical Industries, Novartis AG, Johnson & Johnson, OASIS Medical, Santen Pharmaceutical Co Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dry Eye Syndrome Market Strategic Shifts & Innovations
Digital diagnostic platforms and point-of-care testing devices are compressing the gap between symptom onset and targeted therapy selection. These technologies are enabling severity stratification that matches treatment intensity to disease mechanism.
Point-of-care tear osmolarity measurement is decomposing the traditional referral pathway from optometrist to ophthalmologist. Primary eye care providers in the Netherlands and Belgium are adopting handheld osmolarity meters to triage patients before specialist consultation. This capability is decomposing the historical gatekeeper role of hospital-based cornea units and shifting prescription initiation toward community practice.
EMA's tightened post-market surveillance requirements under the EU MDR are extending evidence obligations for punctal plug manufacturers. Device makers must now submit periodic safety update reports with real-world performance data. High-volume ophthalmology clinics in Germany are responding by consolidating purchasing around suppliers with established post-market clinical follow-up programs.
After-sales service unbundling is disrupting the traditional capital equipment model for thermal pulsation systems. French clinic networks are negotiating device placement with per-procedure fees rather than outright purchase, transferring utilization risk to manufacturers. This shift is most visible in Paris and Lyon, where hospital procurement offices are standardizing performance-based contracting for outpatient ophthalmic devices.
Europe Dry Eye Syndrome Market Segmentation
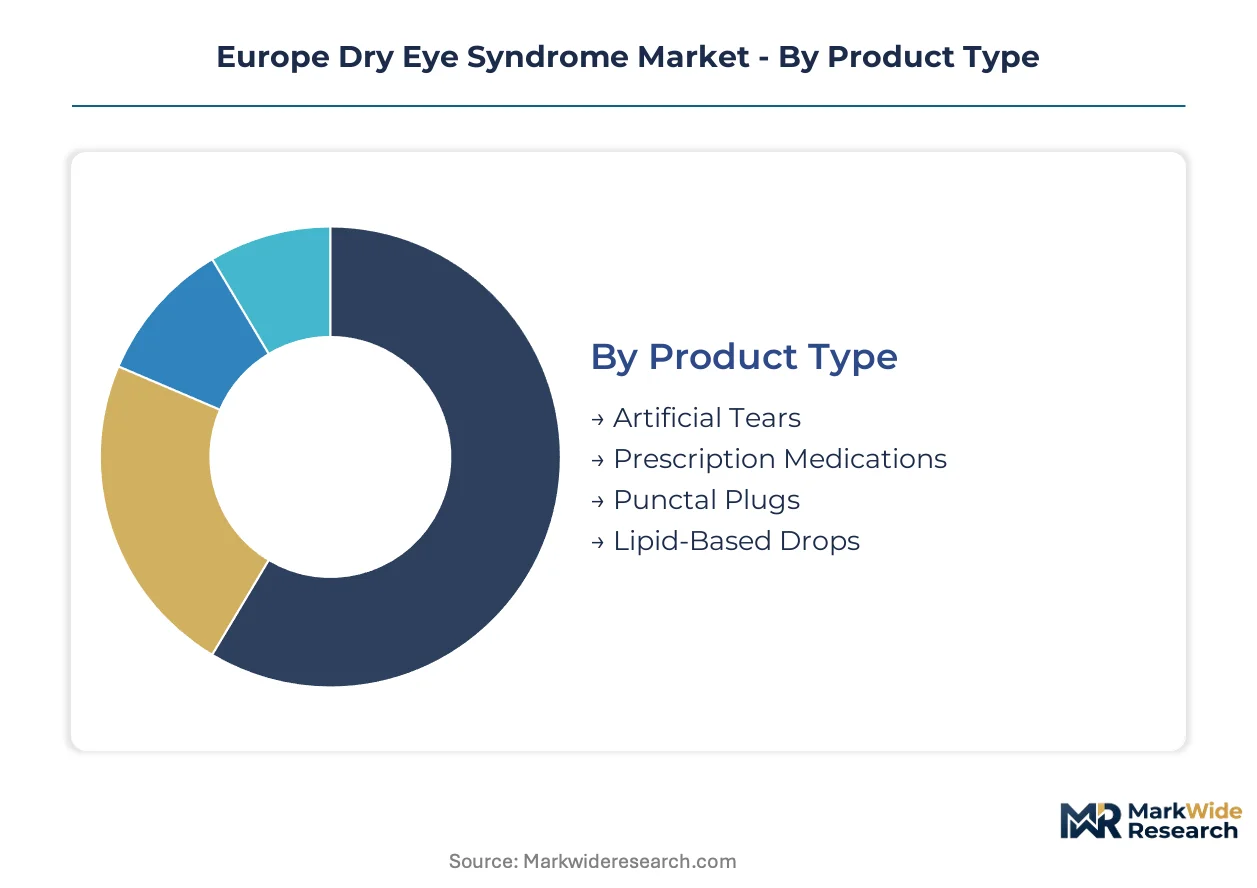
Disease mechanism heterogeneity across European patient populations demands precise segment alignment. Product formulations, delivery modalities, and care settings each carry distinct regulatory pathways and reimbursement profiles that shape commercial viability.
Product Type:
Artificial Tears and Prescription Medications dominate domestic consumption across Germany and France, while Lipid-Based Drops and Punctal Plugs show stronger cross-border trade dynamics into Southern Europe.
- Artificial Tears:Polymer-based lubricants and electrolyte solutions address mild-to-moderate aqueous deficiency. Demand concentrates in German pharmacy retail chains where self-medication rates exceed specialist-referred prescriptions. CE marking under EU MDR has streamlined pan-European distribution for established formulations.
- Prescription Medications:Cyclosporine emulsions and lifitegrast ophthalmic solutions target ocular surface inflammation. French hospital formularies drive volume through HAS-approved reimbursement codes, though G-BA negotiations in Germany create twelve-to-eighteen month access delays.
- Punctal Plugs:Silicone and collagen-based lacrimal occluders for severe aqueous deficiency. Italian cornea specialists increasingly specify temporary plugs before permanent placement.
- Lipid-Based Drops:Emulsion formulations targeting meibomian gland dysfunction. Spanish optometry chains are building dedicated dry eye corners with lipid-specific screening protocols.
Artificial Tears commands the established base. The steepest expansion runs through Lipid-Based Drops.
Delivery Mode:
Topical administration absorbs the highest patient touchpoint volume, while Device-Based and Surgical modalities concentrate margin capture in metropolitan tertiary centers.
- Topical:Eye drops and gels administered via standard dispensers. Community pharmacies across the Netherlands and Belgium process the majority of refill prescriptions without specialist oversight.
- Injectable:Intracanalicular depot formulations and biologic agents. Nordic hospital systems are piloting subconjunctival corticosteroid protocols for refractory cases.
- Surgical:Punctal cautery and salivary gland transplantation for end-stage disease. French university hospitals in Paris and Lyon maintain the deepest surgical queues.
- Device-Based:Thermal pulsation systems and intense pulsed light for meibomian gland expression. German clinic networks in Berlin and Munich are consolidating purchasing around suppliers with technician training programs.
Topical formulations anchor volume throughput. Device-Based delivery is climbing the fastest as clinic infrastructure matures.
User Type:
Ophthalmologists retain prescription authority for immunomodulatory therapies, while Optometrists are capturing triage and maintenance segments through expanded scope-of-practice reforms.
- Ophthalmologists:Fellowship-trained cornea specialists managing severe or mixed-mechanism disease. France's hospital-based specialists control access to biologic therapies through restricted prescribing lists.
- Optometrists:Primary eye care providers conducting point-of-care diagnostics. British optometry practices are integrating tear osmolarity meters to reduce ophthalmology referral backlogs.
- Clinicians:General practitioners and emergency department staff managing acute presentations. Italian primary care networks are receiving EMA-guided diagnostic training modules.
- Home Care Providers:Nurses and caregivers administering drops for elderly or mobility-limited patients. German long-term care insurance funds are reimbursing domiciliary eye care for severe dry eye.
Ophthalmologists defend the premium therapeutic tier. Optometrists are gaining share fastest through diagnostic technology adoption.
End Use:
Hospital settings concentrate device-based therapy adoption, while Homecare segments expand through teleophthalmology-enabled remote monitoring.
- Hospital:Tertiary cornea units performing advanced diagnostics and surgical intervention. Germany's metropolitan hospital networks are building dedicated dry eye service lines with bundled reimbursement.
- Clinic:Outpatient ophthalmology and optometry practices. French clinic networks in Lyon and Marseille are negotiating performance-based contracts for thermal device placement.
- Homecare:Patient-managed therapy with remote monitoring support. Dutch insurers are piloting tear osmolarity home testing kits with AI-driven severity scoring.
- Research Labs:Academic centers conducting clinical trials and biomarker studies. Swiss university hospitals are leading EMA-compliant post-market surveillance for novel punctal plug designs.
Hospital settings anchor premium therapy adoption. Homecare is expanding most quickly through digital diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes prescription medications and device-based therapies at higher per-capita rates than Mediterranean markets, where artificial tears dominate pharmacy retail. France concentrates surgical interventions in tertiary centers, while Italy and Spain rely more heavily on optometrist-led triage. The Netherlands and Belgium are pioneering remote monitoring integration.
Germany
Metropolitan hospital networks in Berlin and Munich are building dedicated dry eye service lines with bundled reimbursement from statutory health insurers. The G-BA determines access speed for novel prescription medications, creating twelve-to-eighteen month delays for immunomodulatory therapies. North Rhine-Westphalia's cornea specialists are consolidating purchasing around thermal device suppliers with established technician training programs.
France
Hospital-based ophthalmologists in Paris and Lyon control access to biologic therapies through restricted prescribing lists maintained by ANSM. The HAS maintains divergent evidence thresholds from Germany's G-BA, forcing parallel health technology assessment submissions for punctal plug manufacturers. Île-de-France clinic networks are negotiating performance-based contracts for intense pulsed light systems with per-procedure fee structures.
Italy
Northern Italian hospital systems lack dedicated ocular surface disease units, presenting first-mover positioning for device-based therapy providers targeting Lombardy and Veneto. The Italian Medicines Agency (AIFA) regulates prescription medication reimbursement through regional formularies with significant north-south variation. Emilia-Romagna's optometry chains are expanding lipid-based drop distribution through dedicated dry eye corners.
Spain
Spanish optometry chains are building dedicated dry eye corners with lipid-specific screening protocols targeting meibomian gland dysfunction recognition. The Spanish Agency for Medicines and Health Products (AEMPS) oversees CE-marked device registration with regional autonomy in reimbursement decisions. Catalonia's Barcelona clinic clusters are piloting technician training protocols for thermal pulsation systems.
Netherlands
Dutch insurers are piloting tear osmolarity home testing kits with AI-driven severity scoring to reduce ophthalmology referral backlogs. The Dutch Healthcare Authority (NZa) regulates teleophthalmology reimbursement codes for remote patient monitoring. Randstad optometry practices are integrating handheld osmolarity meters to decompose the traditional gatekeeper role of hospital-based cornea units.
Europe Dry Eye Syndrome Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the European dry eye syndrome market. The upper tier combines pharmaceutical portfolios with surgical device capabilities to capture cross-selling opportunities in hospital networks. The specialist tier concentrates on single-modality excellence in lipid formulations or point-of-care diagnostics. Dominant competitive moves include portfolio diversification into adjacent ocular surface disease indications and geographic expansion through distributor partnerships in underpenetrated Southern European markets.
Within the integrated pharmaceutical-device tier, Alcon and AbbVie Inc (Allergan) exemplify the convergence strategy. Alcon leverages its surgical and pharmaceutical portfolios to dominate device-based delivery corridors, while AbbVie sustains brand loyalty among prescribing ophthalmologists through its established immunomodulatory franchise. Santen Pharmaceutical Co Ltd anchors the dedicated ocular surface disease specialist position via targeted clinician education programs. These three represent distinct archetypes: diversified eye care conglomerate, immunology-backed pharmaceutical incumbent, and focused ocular therapeutics specialist.
| Leading Market Players |
|---|
| Alcon |
| Bausch & Lomb |
| AbbVie Inc (Allergan) |
| Otsuka Pharmaceutical Co Ltd |
| Sun Pharmaceutical Industries |
| Novartis AG |
| Johnson & Johnson |
| OASIS Medical |
| Santen Pharmaceutical Co Ltd |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between German hospital networks and thermal device suppliers lock in both supply access and price visibility for premium device-based therapies, insulating procurement offices from spot-market volatility while committing capital to technician training programs.
Pricing Analysis
Performance-based contracting dominates device placement in French clinic networks, with per-procedure fee structures transferring utilization risk to manufacturers. Price differentiation rests on after-sales service bundling and HTA approval status across Germany's G-BA and France's HAS. Pricing pressure stems from EU MDR compliance cost escalation for punctal plug notified body reviews. General ophthalmologists exhibit highest price sensitivity, while metropolitan cornea units prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Inventory lead times for cyclosporine and lifitegrast active pharmaceutical ingredients stretch across contract manufacturers in Switzerland and Ireland. Supply concentrates among these single-source API producers, with lipid excipient sourcing extending into the Netherlands and Belgium. Single-source vulnerability pervades the immunomodulatory pipeline. Distribution runs through hospital procurement consortia in Berlin and Paris for device-based therapies, while pharmacy retail chains handle artificial tears across Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized ocular surface disease expertise represents the scarcest capability across European ophthalmology networks, constraining adoption velocity for mechanism-targeted therapies regardless of reimbursement status.
For Market Incumbents: Consolidate technician training infrastructure to defend device placement contracts against emerging competitors with leaner service models. Deepen backward integration into lipid excipient sourcing to offset API concentration risk in Switzerland. Capture G-BA precedent-setting opportunities in North Rhine-Westphalia before HAS divergence hardens. For New Entrants and Emerging Players: Lead with point-of-care diagnostic platforms to bypass established hospital gatekeeper relationships in Italy's underpenetrated Lombardy and Veneto markets. Target optometry-led triage segments in Spain where lipid-specific screening protocols are expanding fastest. Deploy teleophthalmology-enabled remote monitoring as the primary go-to-market angle to reduce direct sales force requirements. For Investors and Strategic Acquirers: Dedicated ocular surface disease education platforms with established clinician academy programs represent the most defensible acquisition archetype. Long-term viability hinges on HTA convergence momentum between France, Germany, and Italy over the next decade. Watch for EMA MDR enforcement consistency as the critical inflection signal for device manufacturer margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance timelines determine competitive entry sequencing for punctal plug and thermal device manufacturers. |
| Hospital System Partnership | Bundled reimbursement negotiations with Berlin and Munich metropolitan networks concentrate demand for premium therapies. |
| Software Companion Development | AI-driven tear osmolarity severity scoring enables optometrists to initiate therapy before specialist referral. |
| Reimbursement Strategy | G-BA precedent in Germany accelerates cross-border HAS and AIFA access for prescription medications. |
| Clinician Education Program | Targeted ocular surface disease training builds prescribing loyalty among cornea specialists and general ophthalmologists. |
Research Approach
Initial hypotheses were tested against primary input from ophthalmology clinic directors, hospital procurement managers, regulatory affairs specialists at EMA-notified bodies, and optometry practice owners, then refined against secondary validation from EMA centralized marketing authorization databases, G-BA benefit assessment dossiers, HAS transparency committee opinions, and ClinicalTrials.gov ocular surface disease protocols. Bottom-up prescription volume modeling and top-down device installation tracking were triangulated to constrain estimate variance.
Variance decomposition across the projection horizon isolates contributions from disease mechanism recognition rates, HTA approval velocity, and clinic infrastructure buildout. Segmentation dimensions span product formulation type, delivery modality, prescriber specialty, and care setting tier. CAGRs were derived from iterative convergence between patient pool expansion assumptions and therapy penetration curves. Forecast inputs incorporate EU MDR implementation pace and teleophthalmology reimbursement code adoption.
The analysis sits within stated boundaries; outcomes outside sustained HTA dialogue or accelerated MDR enforcement would require recalibration. Forecasts reflect documented assumptions regarding clinician workforce expansion and diagnostic technology diffusion. Regulatory divergence, API supply disruption, or reimbursement fragmentation represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market