
 SGLT2 Inhibitors Treatment Market | 2026-2036
SGLT2 Inhibitors Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
SGLT2 Inhibitors Treatment Market Outlook
The R&D-to-manufacturing capability gap between large pharmaceutical conglomerates and mid-tier developers is rotating competitive advantage toward integrated operators. AstraZeneca PLC leverages its cardiovascular outcomes trial infrastructure to sustain leadership in heart failure label expansion. Boehringer Ingelheim International GmbH anchors its position through captive API production and deep endocrinology channel relationships. Eli Lilly and Company differentiates via parallel development of combination therapies that pair SGLT2 inhibition with incretin-class agents.
SGLT2 inhibitors constitute a class of oral hypoglycemic agents that block sodium-glucose cotransporter-2 proteins in renal proximal tubules, producing glucosuria at plasma glucose thresholds above approximately 10 mmol/L while conferring cardiorenal protective effects independent of glycemic control. The empagliflozin and dapagliflozin product segments command the largest revenue pools due to established cardiovascular and renal outcome data, though ertugliflozin competes on cost positioning in price-sensitive markets. Among end users, hospital systems and specialty pharmacies capture the highest-margin dispensing volumes as site-of-care consolidation shifts infusion and monitoring services away from traditional clinics.
The FDA's label expansion framework and EMA's MDR compliance requirements for combination devices are elevating clinical evidence thresholds for market access, while Japan's PMDA accelerates reviews for agents with demonstrated heart failure benefit. These regulatory trajectories favor sponsors with existing outcomes trial infrastructure and integrated pharmacovigilance systems. Stakeholders must monitor evolving payer evidence requirements for chronic kidney disease monotherapy positioning versus standard-of-care combinations.
Market Dynamics
Cardiorenal outcome data is redirecting SGLT2 inhibitor demand from endocrinology toward cardiology and nephrology specialties, fragmenting traditional prescriber hierarchies and forcing formulary redesign across integrated delivery networks.
Growth Catalysts
- FDA label expansion framework:Accelerated cardiovascular and renal indication approvals are opening reimbursement pathways previously restricted to ACE inhibitors and ARBs.
- Hospital system consolidation:Integrated delivery networks in the United States and Germany are standardizing SGLT2 inhibitors across heart failure protocols, creating captive demand pools.
- Biomarker-guided patient selection:NT-proBNP and eGFR thresholds are sharpening prescriber confidence in non-diabetic populations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing clusters in India and China create single-source vulnerability for empagliflozin and dapagliflozin precursors.
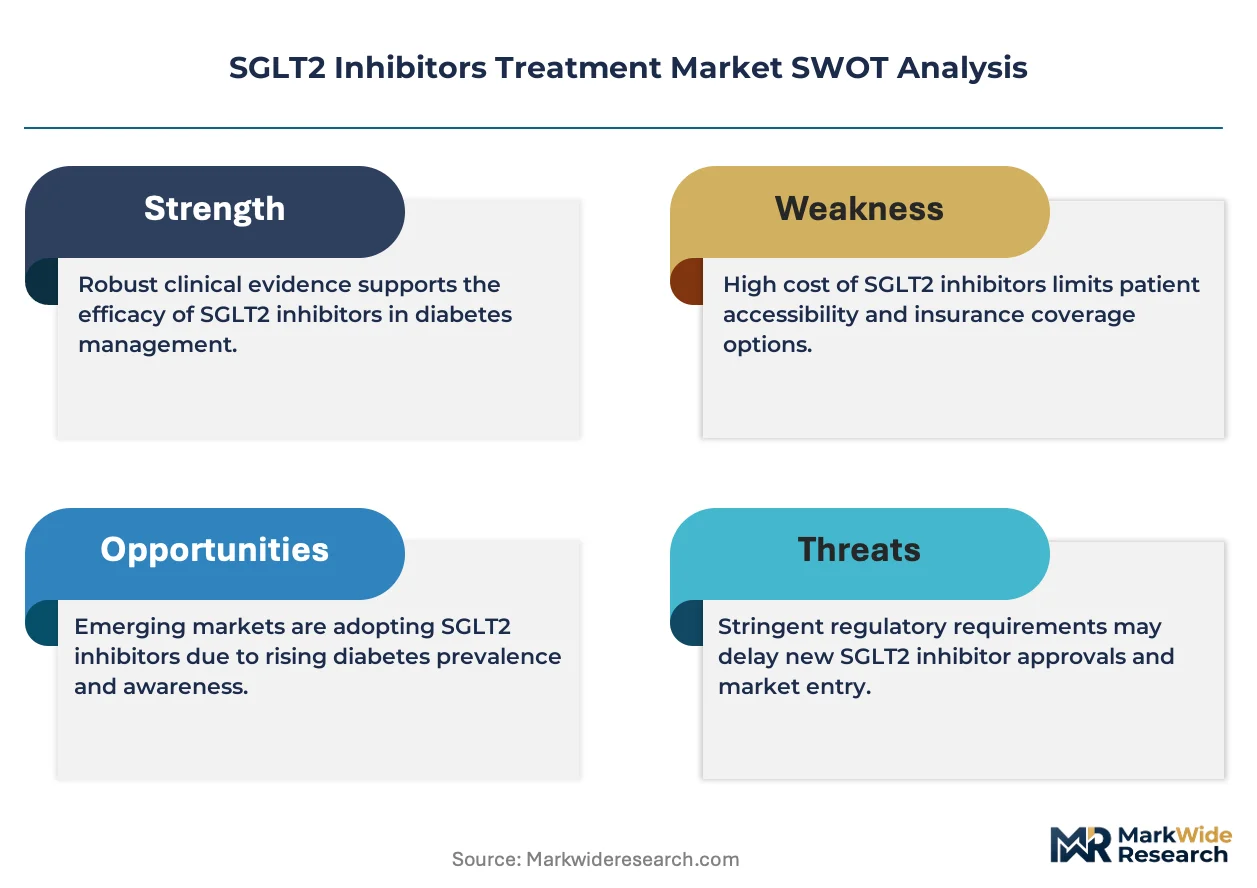
- Genital mycosis safety signal:Persistent adverse event reporting in real-world databases limits prescriber comfort in elderly female cohorts.
- Reimbursement compression:Medicare Part D redesign and European reference pricing are compressing net prices in the two largest revenue markets.
Strategic Opportunities
- Chronic kidney disease monotherapy positioning:Untapped potential exists in non-diabetic CKD populations where SGLT2 inhibitors compete against SGLT1/2 dual inhibitors.
- Fixed-dose combination development:Pairing with GLP-1 receptor agonists or finerenone is creating patent extension pathways and differentiation.
- Specialty pharmacy channel expansion:Limited distribution networks in the United States are capturing higher-margin dispensing and adherence monitoring revenue.
Industry Challenges
- Cardiovascular outcomes trial infrastructure:The capital intensity of large-scale renal and heart failure endpoint studies excludes mid-tier developers from label expansion competition.
- Pharmacovigilance system integration:EMA's MDR compliance and FDA's REMS requirements demand real-world evidence collection capabilities that strain legacy safety databases.
- Cross-specialty education gaps:Cardiologists and nephrologists require differentiated training on SGLT2 inhibitor initiation protocols compared to endocrinology-trained peers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SGLT2 Inhibitors Treatment Market |
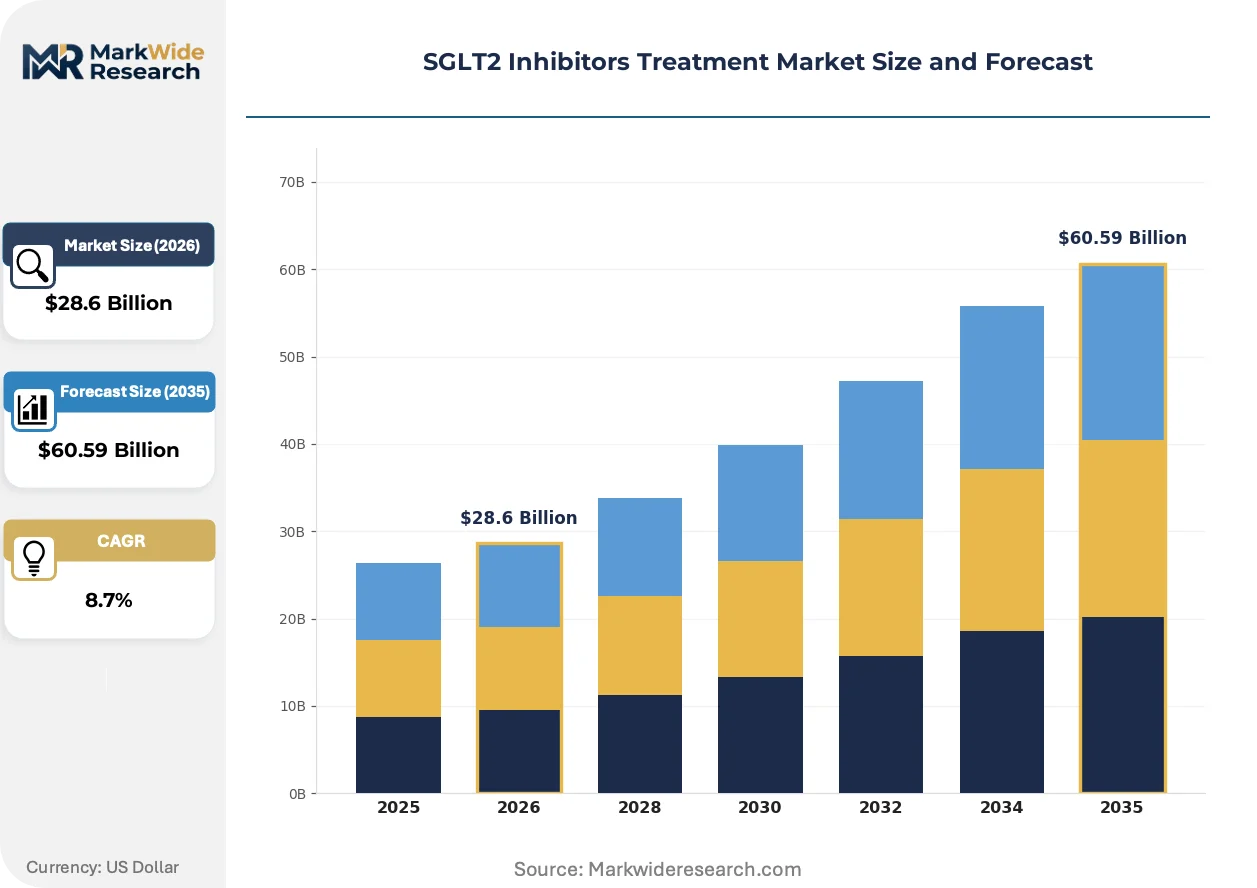
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dapagliflozin, Empagliflozin, Canagliflozin, Ertugliflozin End User: Hospitals, Clinics, Homecare, Specialty Pharmacy Delivery Mode: Oral Tablets, Injectable, Combination Therapy, Liquid Solution Indication: Type 2 Diabetes, Heart Failure, Chronic Kidney Disease, Weight Management |
| Companies Covered | Janssen Pharmaceuticals, Johnson & Johnson, AstraZeneca PLC, Bristol-Myers Squibb Company, Astellas Pharma, Boehringer Ingelheim International GmbH, Merck & Co., Inc., TheracosBio LLC, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SGLT2 Inhibitors Treatment Market Strategic Shifts
Evidence generation models are shifting from placebo-controlled superiority trials to active-comparator studies against standard-of-care combinations, compressing development timelines while raising evidentiary bars for market access.
Fixed-dose combination tablets pairing SGLT2 inhibitors with non-steroidal MRA or GLP-1 agonist components are bifurcating the market between single-agent purists and combination advocates. Large integrated health systems in Germany and Japan are piloting these formulations in heart failure pathways, forcing pure-play SGLT2 manufacturers to defend formulary position through outcomes-based contracts or risk exclusion from preferred tier placement.
EMA's Medical Device Regulation and FDA's evolving guidance on combination product classification are elevating clinical evidence thresholds for devices paired with SGLT2 delivery. Sponsors must now demonstrate bioequivalence and device reliability in parallel, extending regulatory timelines for novel administration formats. European notified bodies are applying stricter scrutiny to connected inhaler or injection systems proposed for combination therapies.
Prescriber purchasing behavior is consolidating around integrated care pathways that bundle SGLT2 initiation with remote patient monitoring and dietary counseling. United States-based accountable care organizations are displacing traditional fee-for-service dispensing with per-member-per-month cardiovascular risk management contracts. This shift concentrates volume within health systems capable of delivering wraparound services, marginalizing independent endocrinology practices lacking care coordination infrastructure.
SGLT2 Inhibitors Treatment Market Segmentation
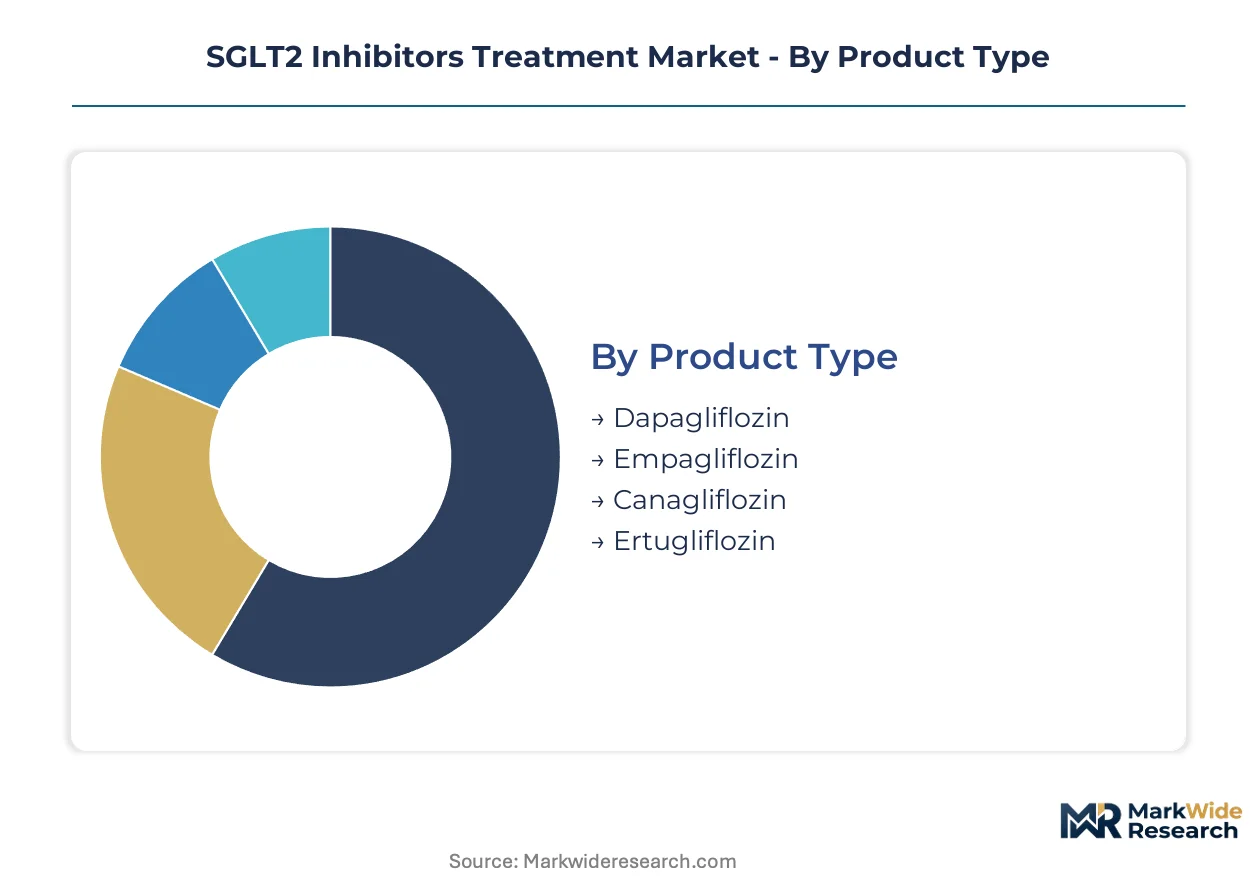
SGLT2 inhibitor market segmentation reveals how cardiorenal indication expansion is fragmenting traditional glycemic-focused demand pools. Product type and delivery mode categories face divergent substitution pressures from GLP-1 agonists and dual SGLT1/2 inhibitors.
Product Type:
Substitute pressure from SGLT1/2 dual inhibitors and GLP-1 agonists concentrates most intensely on the lower-cost segments where cardiovascular outcome differentiation remains weakest.
- Dapagliflozin:A selective SGLT2 inhibitor with established heart failure and chronic kidney disease indications beyond glycemic control. Demand concentrates in United States hospital systems where integrated delivery networks standardize heart failure protocols around its cardiovascular outcomes data.
- Empagliflozin:The most extensively validated agent for cardiovascular mortality reduction with dedicated renal outcome trials. German and Japanese payers prioritize its inclusion in chronic kidney disease pathways due to EMPA-KIDNEY trial evidence.
- Canagliflozin:Faces amputation risk signal constraints in United States prescribing guidelines. Remains viable in price-sensitive markets where renal outcomes data supports formulary inclusion despite safety labeling.
- Ertugliflozin:Competes primarily on acquisition cost in markets where cardiovascular outcomes data requirements are less stringent. Captures share in European markets with aggressive reference pricing.
Dapagliflozin anchors the volume base while empagliflozin gains share at the steepest rate.
End User:
Site-of-care consolidation is rotating dispensing volume toward channels capable of delivering wraparound monitoring services.
- Hospitals:Integrated delivery networks in the United States and Germany capture the highest-margin volumes through heart failure pathway standardization. Remote patient monitoring bundling creates captive demand pools.
- Specialty Pharmacy:Limited distribution networks concentrate adherence monitoring and outcomes data collection. United States accountable care organizations favor these channels for cardiovascular risk management contracts.
- Clinics:Traditional endocrinology practices face margin compression as cardiorenal indications shift prescribing toward hospital-affiliated specialists.
- Homecare:Emerging channel for stable patients on established therapy, constrained by reimbursement complexity for monitoring services.
Hospitals dominate current volume while specialty pharmacy climbs the fastest.
Delivery Mode:
Regulatory evidence requirements for combination products are elevating development costs and extending timelines for novel administration formats.
- Oral Tablets:The established standard with immediate-release and extended-release formulations. FDA bioequivalence pathways are well-characterized, supporting generic substitution dynamics.
- Combination Therapy:Fixed-dose pairings with GLP-1 agonists or finerenone are expanding in German and Japanese pilot programs. EMA Medical Device Regulation compliance demands parallel device reliability demonstration.
- Injectable:Limited to combination products where SGLT2 components accompany peptide therapeutics. Requires refrigerated supply chain infrastructure.
- Liquid Solution:Niche format for patients with swallowing difficulties, constrained by stability and dosing precision challenges.
Oral tablets anchor the volume base while combination therapy gains share at the steepest rate.
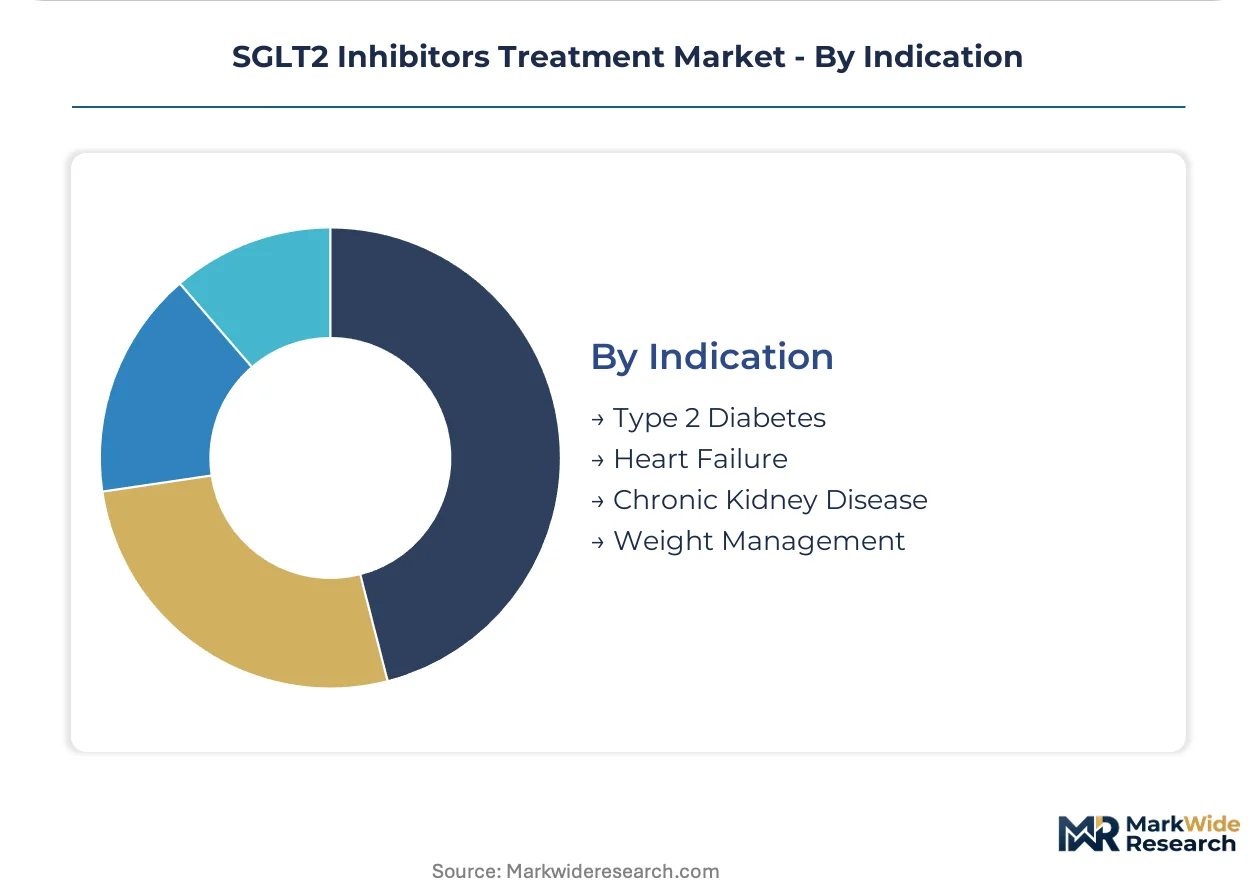
Indication:
Label expansion beyond glycemic control is fragmenting prescriber hierarchies and forcing cross-specialty education investments.
- Type 2 Diabetes:The original approved indication now faces GLP-1 agonist substitution in obese cohorts. Remains foundational for combination therapy positioning.
- Heart Failure:The fastest-expanding indication with reduced and preserved ejection fraction approvals. United States and German hospital systems standardize SGLT2 initiation across cardiology protocols.
- Chronic Kidney Disease:Non-diabetic populations represent untapped positioning against SGLT1/2 dual inhibitors. Japan's PMDA accelerates reviews for agents with demonstrated renal benefit.
- Weight Management:Emerging positioning constrained by GLP-1 agonist superiority in obesity outcomes. Requires dedicated cardiovascular safety trials for standalone approval.
Type 2 diabetes anchors the volume base while heart failure gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets where SGLT2 inhibitors anchor heart failure protocols versus those where glycemic control remains the primary entry point. Hospital system consolidation and payer integration determine whether cardiorenal indications translate into volume.
United States
Integrated delivery networks in the United States standardize SGLT2 initiation across heart failure pathways, with Medicare Part D redesign accelerating site-of-care consolidation. FDA label expansions for reduced and preserved ejection fraction indications opened reimbursement corridors previously restricted to ACE inhibitors. The Cleveland Clinic and Mayo Clinic health systems capture disproportionate dispensing volume through bundled cardiovascular risk contracts.
Germany
German statutory health insurers prioritize empagliflozin inclusion in chronic kidney disease pathways following EMPA-KIDNEY trial evidence, while hospital formulary committees enforce protocol standardization. EMA cardiovascular outcomes guidance shapes prescriber training requirements across Baden-Württemberg and Bavaria. Heidelberg and Berlin hospital clusters pilot fixed-dose combination therapies in integrated care pathways.
Japan
Japan's PMDA accelerates regulatory reviews for agents demonstrating heart failure benefit, compressing time-to-market for sponsors with existing outcomes data. METI reimbursement frameworks reward chronic kidney disease monotherapy positioning in elderly populations. Tokyo and Osaka medical centers concentrate specialist prescribing volume as regional hospitals defer to academic referral networks.
United Kingdom
NICE technology appraisals restrict SGLT2 access in type 2 diabetes to specific patient profiles, though heart failure indications bypass cost-effectiveness thresholds. NHS England integrated care boards in Greater Manchester and the West Midlands consolidate prescribing authority within hospital trusts. The MHRA post-Brexit regulatory pathway diverges from EMA timelines for combination product approvals.
India
Indian demand concentrates in private hospital chains where ertugliflozin cost positioning penetrates price-sensitive segments, while public procurement remains limited. CDSCO accelerated approval pathways for agents with demonstrated renal outcomes are expanding access in metropolitan centers. Mumbai and Delhi NCR hospital systems build cardiorenal specialist capacity faster than tier-two cities.
SGLT2 Inhibitors Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage rotating toward operators controlling cardiovascular outcomes trial infrastructure and captive API supply. The upper tier consolidates around sponsors with dedicated heart failure and renal endpoint study capabilities, while mid-tier developers compete on cost positioning in price-sensitive markets. Two strategic archetypes dominate: integrated pharmaceutical conglomerates with parallel combination therapy pipelines, and pure-play cardiorenal specialists leveraging regulatory acceleration pathways. Dominant competitive moves include fixed-dose combination development for patent extension and outcomes-based contracting with integrated delivery networks.
Among integrated pharmaceutical conglomerates, AstraZeneca PLC, Boehringer Ingelheim International GmbH, and Eli Lilly and Company exemplify the infrastructure-heavy archetype. AstraZeneca occupies a position anchored by cardiovascular outcomes trial capabilities, Boehringer Ingelheim represents captive API production integration, and Eli Lilly sits within the combination therapy development tier. These three entities illustrate how regulatory evidence generation scale and manufacturing control separate market participants.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| Johnson & Johnson |
| AstraZeneca PLC |
| Bristol-Myers Squibb Company |
| Astellas Pharma |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| TheracosBio LLC |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
FDA REMS compliance and EMA MDR certification requirements for combination products simultaneously gate API supplier qualification and create tiered price differentiation between validated and non-validated supply sources. Hospital systems and specialty pharmacies absorb compliance premiums through bundled contracting while price-sensitive markets gravitate toward unvalidated channels.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and manufacturers anchor the United States pricing structure, with Medicare Part D redesign compressing net prices in the largest revenue pool. Price differentiation rests on cardiovascular outcomes data depth and captive API production status, with empagliflozin and dapagliflozin commanding premiums over ertugliflozin. Cost compression in European reference pricing markets is intensifying as German statutory insurers apply aggressive tendering. Ertugliflozin buyers in India and price-sensitive European segments exhibit highest price sensitivity, while United States hospital systems with bundled cardiovascular risk contracts show lowest elasticity.
Supply Chain Analysis
India and China anchor empagliflozin and dapagliflozin precursor manufacturing, with United States and German facilities handling final formulation and packaging. Active pharmaceutical ingredient production draws from specialized chemical intermediates and fermentation-derived starting materials, with purity grades determining downstream qualification. Single-source vulnerability concentrates in Gujarat and Zhejiang manufacturing clusters exposed to environmental regulatory enforcement. Distribution runs through limited specialty pharmacy networks in the United States and hospital-centric procurement in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SGLT2 inhibitor market is entering a cyclical recovery phase as cardiorenal indication expansion redirects prescriber demand from mature diabetes segments toward heart failure and chronic kidney disease growth pools. FDA label acceleration and EMA cardiovascular outcomes guidance provide the cyclical impetus for volume repositioning.
For Market Incumbents: Compound cardiovascular outcomes trial capabilities through parallel renal endpoint studies that extend label protection against SGLT1/2 dual inhibitor substitution. Deepen backward integration into API production to defend margin position against Indian and Chinese supply concentration risks. Lock hospital system formulary position through outcomes-based contracting before GLP-1 agonist combination therapies achieve regulatory traction.
For New Entrants and Emerging Players: FDA accelerated approval pathways for heart failure indications offer the fastest regulatory entry point for sponsors with existing cardiorenal data packages. Target non-diabetic chronic kidney disease populations in Japan where PMDA review compression rewards demonstrated renal benefit. Pursue fixed-dose combination development with finerenone or established GLP-1 components to bypass pure-play SGLT2 commoditization.
For Investors and Strategic Acquirers: EMA MDR compliance deadlines for combination devices reshape the acquisition landscape toward targets with integrated pharmacovigilance infrastructure and device reliability capabilities. Five-to-ten year viability favors vertically integrated operators controlling cardiovascular outcomes trial scale and captive API supply. Watch for Medicare Part D redesign implementation signals as inflection indicators for United States pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcomes Trial Expansion | AstraZeneca's DAPA-HF infrastructure enables heart failure label extensions that command premium formulary placement. |
| Fixed-Dose Combination Development | Eli Lilly's parallel GLP-1 pairing programs create patent extension pathways against generic SGLT2 erosion. |
| Captive API Production Integration | Boehringer Ingelheim's in-house manufacturing insulates against Indian and Chinese supply concentration risks. |
| Specialty Pharmacy Channel Control | United States limited distribution networks capture adherence monitoring revenue and real-world evidence generation. |
| Regulatory Acceleration Pathway Exploitation | Japan's PMDA fast-track reviews compress time-to-market for agents with demonstrated cardiorenal benefit. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation converged on segment-level estimates. Cross-referencing of payer access specialist interviews with CMS Medicare data and GPO contracts established price realization assumptions.
Variance decomposition across product type, indication, delivery mode, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro healthcare expenditure trends. Modeled inputs included cardiovascular outcomes trial enrollment trajectories, label expansion probability assessments, and reference pricing regime evolution in European markets.
Decision-makers should treat outputs as directional under assumptions of continued FDA label expansion momentum and stable API supply from Indian and Chinese manufacturing clusters; material deviation in regulatory timelines or trade policy would warrant model refresh. Recalibration cycles align with material shifts in Medicare Part D redesign implementation, EMA MDR enforcement intensity, and PMDA review acceleration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Malaysia Diabetes Care Devices Market
Diabetes Care
Russia Diabetes Care Devices Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market