
 Intravenous Stopcock Market | 2026-2036
Intravenous Stopcock Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Stopcock Market Outlook
MDR compliance timelines are pivoting the cost-of-entry calculus for intravenous stopcock manufacturers targeting European distribution. Becton, Dickinson and Company leverages its vertically integrated polymer compounding capabilities to sustain margin control across high-volume hospital contracts. B. Braun Melsungen AG anchors its competitive stance through captive cleanroom manufacturing networks in Germany and Malaysia. ICU Medical differentiates via proprietary needle-free connector integration with stopcock manifolds, reducing bloodstream infection risk profiles.
An intravenous stopcock is a directional flow-control valve, typically molded from medical-grade polycarbonate or polypropylene with Luer-lock taper interfaces, designed to regulate or redirect infusion lines in pressurized fluid delivery systems. The device enables simultaneous access points for medication administration, blood product transfusion, and parenteral nutrition without line disconnection. Three-way stopcocks dominate current procurement volumes due to their versatility in anesthesia and critical care workflows, while four-way configurations are gaining traction in cardiac surgery settings requiring multiple concurrent infusions. Plastic materials command the largest material share given disposability mandates and cost structures, though composite variants incorporating ceramic-reinforced polymers are emerging for high-pressure contrast injection applications.
The US FDA 510(k) pathway governs market access for stopcocks as Class II medical devices, with ISO 80369 small-bore connector standards now mandatory for reducing misconnection hazards across infusion therapy. Europe's MDR technical documentation requirements and biocompatibility testing per ISO 10993 are extending certification cycles and consolidating supplier bases toward established manufacturers with notified body relationships. Japan's PMDA maintains distinct pharmaceutical affairs law interpretations for combination products incorporating stopcock manifolds with drug-eluting coatings. Stakeholders must monitor evolving regional divergence in sterilization validation requirements as ethylene oxide alternatives face regulatory pressure across multiple jurisdictions.
Market Dynamics
Integrated delivery networks in the United States are consolidating procurement authority across acute care facilities, compressing supplier margins while favoring manufacturers with captive polymer compounding and sterilization capabilities. This buyer concentration is reshaping competitive positioning toward vertically integrated producers capable of meeting standardized volume contracts.
Growth Catalysts
- ISO 80369 small-bore connector standards:The FDA's mandatory enforcement of ISO 80369-7 compliance is accelerating hospital system upgrades of legacy Luer-lock configurations. This creates replacement demand across anesthesia and critical care departments.
- Cardiac surgery volume expansion:Four-way stopcock configurations are gaining traction in open-heart procedures requiring simultaneous administration of cardioplegia, blood products, and vasoactive medications.
- Malaysia cleanroom manufacturing:German and Japanese manufacturers are expanding captive production in Malaysian free-trade zones to serve Asia-Pacific demand with reduced tariff exposure.
Market Restraints
- Medical-grade polycarbonate price volatility:Bisphenol-A supply constraints and energy costs in European polymer production are compressing margins for disposable stopcock manufacturers without backward integration into resin sourcing.
- Ethylene oxide sterilization regulatory pressure:EPA emission restrictions and state-level facility closures in the United States are constraining terminal sterilization capacity, extending lead times for high-volume hospital contracts.
- Needle-free connector substitution:Closed-system transfer devices and needle-free manifold technologies are displacing traditional stopcock access points in oncology and immunocompromised patient populations.
Strategic Opportunities
- India hospital infrastructure expansion:Government-funded tertiary care construction under the Ayushman Bharat program is creating first-time demand for multi-access stopcock manifolds in tier-2 and tier-3 cities.
- Ceramic-reinforced polymer convergence:Composite stopcock materials combining polypropylene with alumina nanoparticles are enabling high-pressure contrast injection applications in interventional radiology suites.
- Direct-to-hospital e-procurement channels:Group purchasing organizations are piloting digital procurement platforms that disintermediate traditional medical device distributors for standardized stopcock SKUs.
Industry Challenges
- MDR technical documentation backlog:European notified body capacity constraints are extending certification cycles for stopcock manufacturers seeking CE marking under the 2017/745 Medical Device Regulation.
- Polymer compounding talent scarcity:Specialized expertise in medical-grade resin formulation and biocompatibility testing is concentrating among a narrow cohort of polymer scientists in Germany and Switzerland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Stopcock Market |
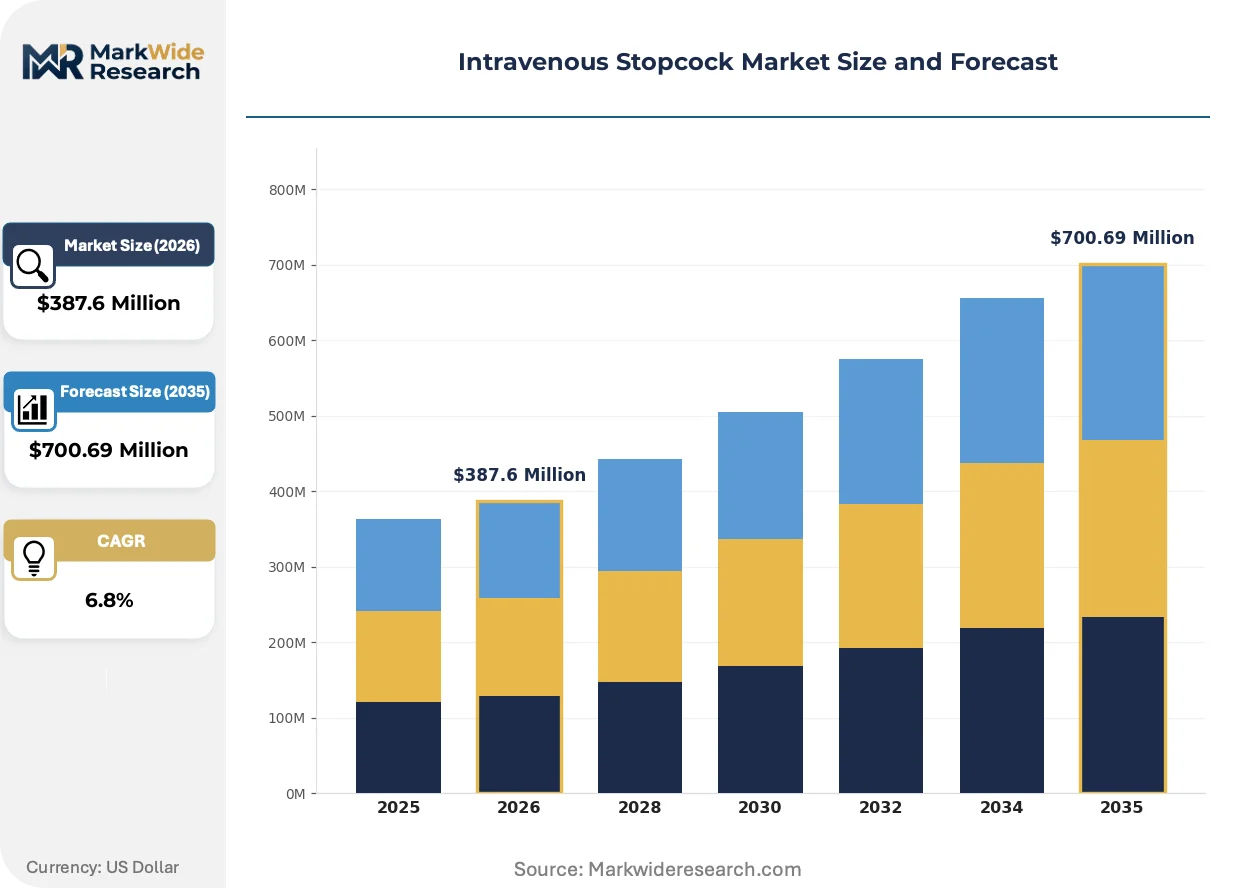
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Way Stopcocks, Three-Way Stopcocks, Four-Way Stopcocks, Multi-Access Stopcocks End User: Hospitals, Clinics, Home Healthcare, Ambulatory Surgery Centers Material: Plastic, Glass, Metal, Composite Application: Fluid Management, Drug Delivery, Blood Administration, Parenteral Nutrition |
| Companies Covered | Becton, Dickinson and Company, B. Braun Melsungen AG, ICU Medical, Terumo Corporation, Fresenius Kabi AG, Smiths Medical, Global Medikit Limited, SCW Medicath Ltd., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Stopcock Market Strategic Shifts
Stopcock technology is converging with infection control protocols and digital infusion management systems, creating pressure for manufacturers to integrate antimicrobial surfaces and flow-sensing capabilities into standard product lines.
Antimicrobial copper-alloy coatings deposited via physical vapor deposition are decentralizing infection risk management from central pharmacy protocols to the point-of-care device itself. Hospitals in the United States with elevated central line-associated bloodstream infection rates are piloting these surfaces in oncology and burn units. The coating technology is compressing the competitive advantage of standalone needle-free connectors by embedding protection directly into stopcock manifolds.
Europe's MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa devices including stopcocks. Manufacturers must now maintain electronic systems for traceability and periodic safety update reporting, extending compliance costs toward smaller competitors. German and Swiss producers with established quality management systems are absorbing these requirements faster than mid-tier competitors in Southern and Eastern Europe.
Hospital system value analysis committees are consolidating vendor lists for infusion accessories, replacing fragmented department-level purchasing with standardized formulary decisions. This concentration is visible most acutely in United States integrated delivery networks exceeding fifty acute care facilities, where procurement directors now mandate single-source contracts for stopcock manifolds across all anesthesia and critical care units.
Intravenous Stopcock Market Segmentation
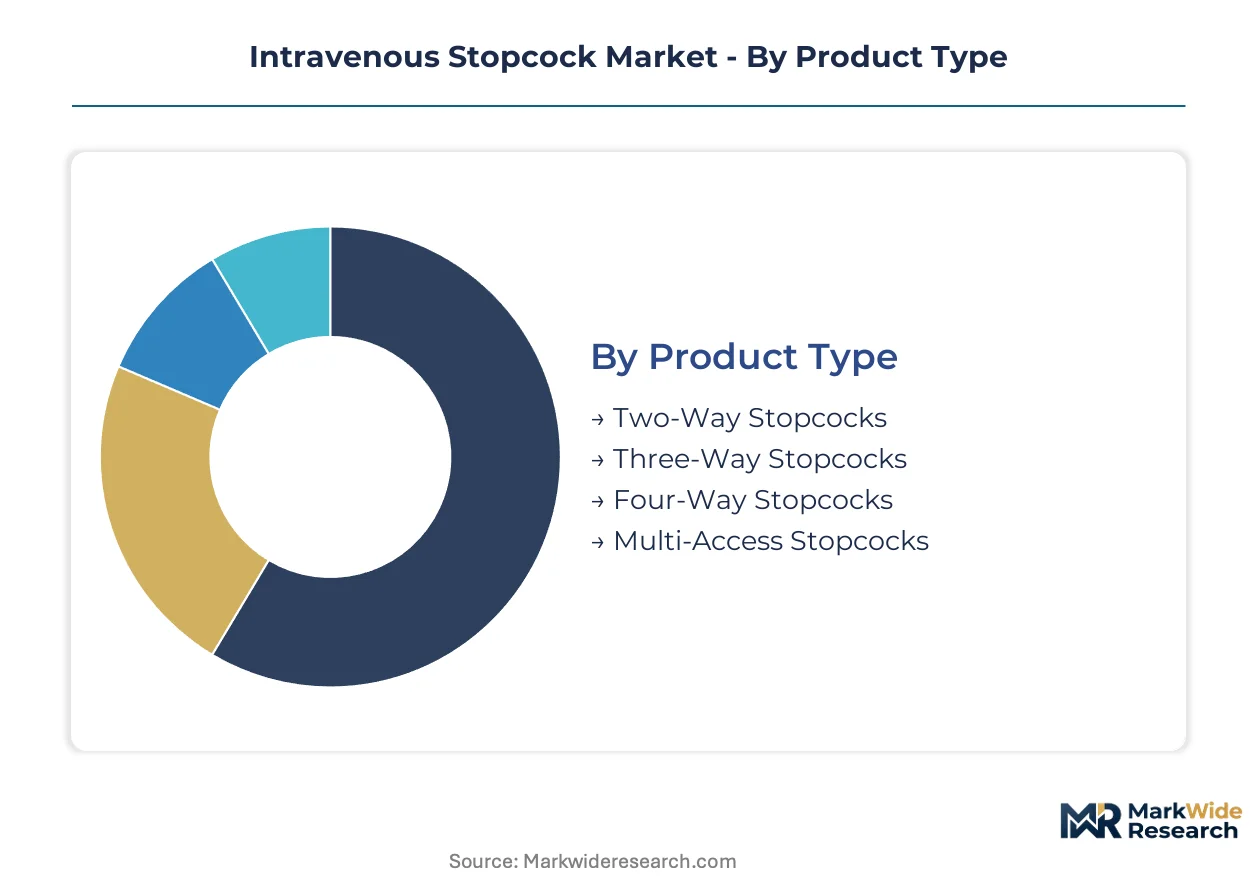
Stopcock procurement patterns diverge sharply across clinical settings and pressure requirements. Material selection and port configuration determine compatibility with specific infusion protocols and sterilization methods.
Product Type:
Port configuration dictates flow complexity and clinical utility across anesthesia and critical care workflows.
- Two-Way Stopcocks:Simple on/off flow control for single-line applications. Demand concentrates in outpatient infusion centers and ambulatory settings where cost minimization overrides functional complexity.
- Three-Way Stopcocks:Directional valve enabling simultaneous infusion and sampling without line disconnection. Hospital anesthesia departments and emergency medicine units drive procurement volumes for this configuration due to its versatility in rapid sequence intubation and trauma resuscitation.
- Four-Way Stopcocks:Multi-port manifold for concurrent administration of cardioplegia, blood products, and vasoactive agents. Cardiac surgery suites in tertiary hospitals are expanding adoption as open-heart procedure volumes recover.
- Multi-Access Stopcocks:Modular manifold systems with four or more ports for complex ICU polypharmacy. Pediatric intensive care and burn units require these configurations for patients with limited vascular access sites.
Mature deployment sits with Three-Way Stopcocks. Newer deployment is concentrated in Multi-Access Stopcocks.
End User:
Procurement authority and volume scale vary dramatically across facility types, reshaping supplier engagement models.
- Hospitals:Integrated delivery networks consolidate purchasing across anesthesia, critical care, and interventional radiology departments. Value analysis committees now mandate standardized stopcock formularies exceeding fifty acute care facilities.
- Clinics:Outpatient infusion centers and oncology day units require disposability-optimized configurations with reduced sterilization overhead. Group purchasing organization contracts dominate procurement channels.
- Home Healthcare:Patient-administered parenteral nutrition and antibiotic therapy demand simplified two-port designs with intuitive directional indicators. Medicare reimbursement codes influence product selection criteria.
- Ambulatory Surgery Centers:Fast-turnover facilities prioritize pre-assembled manifold kits to minimize setup time. Certificate-of-need regulations in certain US states constrain facility expansion.
Volume concentration rests with Hospitals. Margin expansion is strongest in Home Healthcare.
Material:
Biocompatibility requirements and pressure ratings determine resin selection and manufacturing location.
- Plastic:Medical-grade polycarbonate and polypropylene dominate disposable applications. Bisphenol-A supply constraints in European polymer production are compressing margins for manufacturers without captive resin sourcing.
- Glass:Borosilicate configurations for drug compatibility in chemotherapy compounding. Hospital pharmacies with USP 800 hazardous drug handling requirements specify glass for specific antineoplastic agents.
- Metal:Stainless steel stopcocks for reusable sterilization cycles in resource-constrained settings. Veterans Affairs medical centers and certain European public health systems maintain metal instrument reprocessing programs.
- Composite:Alumina-reinforced polymers enabling high-pressure contrast injection in interventional radiology. Composite variants are climbing the fastest as cardiac catheterization and peripheral vascular procedure volumes expand.
Disposable deployment centers on Plastic. Durable deployment persists with Metal.
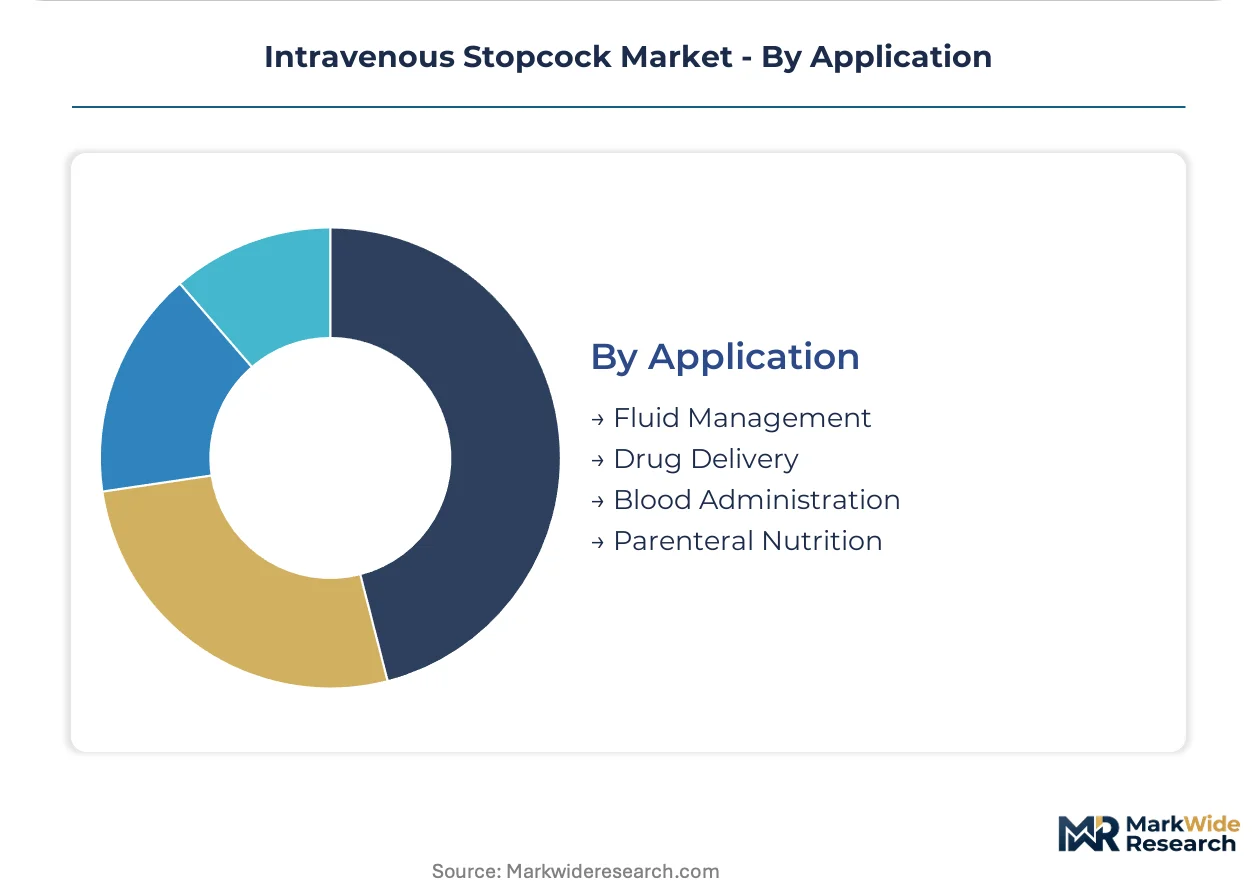
Application:
Clinical use case determines pressure rating, connector standard, and antimicrobial surface requirements.
- Fluid Management:Crystalloid and colloid administration in perioperative settings. Anesthesia departments specify ISO 80369-7 compliant connectors to reduce misconnection hazards.
- Drug Delivery:Multi-channel infusion of incompatible medications requiring dedicated lumens. ICU protocols for vasopressor and sedative co-administration drive four-way manifold adoption.
- Blood Administration:Filter-integrated stopcocks for red cell and platelet transfusion. Blood bank quality standards mandate specific flow rates and filtration specifications.
- Parenteral Nutrition:Lipid emulsion compatibility and light-protection requirements influence material selection. Home infusion providers prioritize all-in-one bag systems with integrated access ports.
Established deployment remains with Fluid Management. Emerging deployment is accelerating in Drug Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian free-trade zones concentrate German and Japanese manufacturing investment for Asia-Pacific distribution. Integrated delivery networks in the United States standardize procurement across fifty-plus acute care facilities. European MDR compliance timelines favor established producers with notified body relationships.
United States
Integrated delivery networks consolidate purchasing authority across anesthesia and critical care departments, compressing supplier margins toward vertically integrated manufacturers. The FDA's ISO 80369-7 enforcement accelerates hospital system upgrades of legacy Luer-lock configurations. Minneapolis-St. Paul hosts concentrated medical device engineering talent for stopcock manifold design.
Germany
Captive cleanroom manufacturing networks in Germany and Malaysia serve European and Asia-Pacific demand with reduced tariff exposure. The MDR technical documentation requirements extend certification cycles and consolidate supplier bases toward established manufacturers. The Stuttgart-Karlsruhe corridor anchors polymer compounding expertise for medical-grade resin formulation.
Japan
PMDA maintains distinct pharmaceutical affairs law interpretations for combination products incorporating drug-eluting coatings. The country's aging demographic expands cardiac surgery volumes requiring four-way stopcock configurations. The Kansai region concentrates precision molding capabilities for high-pressure contrast injection applications.
India
Government-funded tertiary care construction under the Ayushman Bharat program creates first-time demand for multi-access stopcock manifolds in tier-2 and tier-3 cities. The CDSCO regulates device registration with increasing alignment to international standards. Gujarat and Maharashtra host emerging domestic manufacturing clusters serving South Asian markets.
Malaysia
Free-trade zone incentives attract German and Japanese manufacturers expanding captive production for regional Asia-Pacific distribution. The country's central pharmaceutical regulator maintains streamlined device registration pathways for established multinational producers. Penang and the Klang Valley concentrate cleanroom assembly operations for high-volume hospital contracts.
Intravenous Stopcock Market Competitive Environment
United States producers anchor one tier; German specialists hold premium positioning through polymer compounding capabilities. The market structure concentrates among vertically integrated manufacturers with captive resin sourcing and sterilization capacity. Three archetypes dominate: integrated conglomerates with hospital system contracts, regional specialists with notified body relationships, and emerging Asian fabricators with cost-optimized configurations. Competitive moves center on M&A for polymer compounding assets and strategic partnerships with integrated delivery networks for standardized formulary placement.
Within the integrated conglomerate tier, Becton, Dickinson and Company and B. Braun Melsungen AG exemplify manufacturers with backward integration into medical-grade resin formulation. ICU Medical occupies a position among specialists differentiating through proprietary connector integration. These three anchors represent distinct competitive vectors: captive supply chain control, European regulatory navigation, and technology-driven infection risk reduction.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| ICU Medical |
| Terumo Corporation |
| Fresenius Kabi AG |
| Smiths Medical |
| Global Medikit Limited |
| SCW Medicath Ltd. |
| Teleflex Incorporated |
| Others |
Value Chain & Pricing Dynamics
Ethylene oxide emission restrictions in the United States and European Union are gating qualified sterilization capacity and segmenting manufacturers into premium-tier pricing access versus commodity spot suppliers without validated terminal sterilization pathways. Hospital procurement committees now demand documented sterilization compliance as a table-stakes qualifier, compressing margins for non-integrated producers while rewarding backward-integrated manufacturers with captive EtO or radiation alternatives.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard contract pricing as EPA facility closures constrain terminal sterilization throughput. Three-tier pricing structure across premium, standard, and economy levels separates ISO 80369-certified manifolds with antimicrobial coatings from basic polycarbonate configurations and unbranded Asian imports. Cost compression in economy tiers is intensifying because bisphenol-A supply constraints in European polymer production are elevating resin input costs. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare reimbursement pressure, while cardiac surgery suites in tertiary hospitals prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian free-trade zone concentration for German and Japanese manufacturers serving Asia-Pacific demand. Medical-grade polycarbonate resin draws from Germany, Saudi Arabia, and South Korea, while Luer-lock taper molds and precision molding equipment rest on Japanese and Swiss suppliers. Tariff exposure threatens margin stability as regional trade agreements shift duty treatment for finished devices versus component imports. Distribution runs through group purchasing organization contracts in the United States and hospital system direct procurement in Europe, with emerging e-procurement platforms disintermediating traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European MDR certification backlogs and sterilization capacity constraints are forcing mid-tier manufacturers toward exit or acquisition, consolidating viable supply around vertically integrated incumbents with notified body relationships and captive production assets.
For Market Incumbents: Extend polymer compounding capabilities through acquisition of specialized resin formulation assets in Germany or Switzerland to secure margin control against bisphenol-A price volatility. Expand Malaysian cleanroom capacity to serve Asia-Pacific hospital contracts with reduced tariff exposure. Needle-free connector substitution in oncology workflows threatens traditional stopcock volumes, requiring antimicrobial surface integration to defend manifold positioning. For New Entrants and Emerging Players: Ceramic-reinforced polymer convergence for high-pressure contrast injection applications offers technology-first wedge into interventional radiology suites underserved by incumbent product lines. Target tier-2 and tier-3 Indian cities under Ayushman Bharat infrastructure expansion where first-time demand for multi-access manifolds outpaces established supplier presence. Pursue direct-to-hospital e-procurement partnerships with emerging group purchasing organization digital platforms to bypass distributor margin extraction. For Investors and Strategic Acquirers: FDA 510(k) clearance delays exceeding eighteen months for new market entrants is the leading indicator that regulatory capability scarcity is deepening competitive moats for established manufacturers. The intravenous stopcock market reads as a five-to-ten year consolidation play where polymer compounding expertise and notified body relationships define acquisition value. Target mid-tier European manufacturers with CE marking but lacking backward resin integration, as MDR documentation backlogs force distressed positioning.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | European notified body relationships now gate market access for Class IIa devices under 2017/745 technical documentation requirements. |
| Captive Sterilization Capacity | In-house ethylene oxide or gamma radiation alternatives buffer EPA emission restrictions constraining third-party terminal sterilization. |
| Antimicrobial Surface Integration | Copper-alloy coatings via physical vapor deposition embed infection control directly into stopcock manifolds, displacing standalone needle-free connectors. |
| Malaysian Manufacturing Expansion | Free-trade zone production reduces tariff exposure for German and Japanese manufacturers serving Asia-Pacific hospital contracts. |
| Direct E-Procurement Partnerships | Group purchasing organization digital platforms disintermediate traditional distributors for standardized stopcock SKUs in United States integrated delivery networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this intravenous stopcock market assessment, combined with primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and polymer compounding technical directors. FDA 510(k) databases, EMA MDR submission trackers, and Asia-Pacific medical device import registries provided validation against bottom-up hospital procurement surveys and top-down resin consumption estimates from medical-grade polymer trade associations.
Reconciliation of shipment data, production capacity disclosures, and price realization patterns informed the analytical framework across the projection horizon. Segmentation modeling incorporated port configuration complexity, material pressure rating tiers, end-user facility scale, and regional regulatory cluster alignment. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns for ISO 80369 connector standards and four-way manifold penetration in cardiac surgery workflows.
Several conditions sit outside the modeled scope, including potential FDA reclassification of stopcocks to Class III devices, breakthrough substitution by closed-system transfer technologies in oncology, and geopolitical disruption to Malaysian free-trade zone operations. Forecasts reflect assumptions about MDR notified body capacity expansion, ethylene oxide sterilization regulatory stability, and cardiac surgery volume recovery trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Surgical Mesh Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Venturi Mask Market
Medical Devices
Global Insulin Pumps Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
US Contact Lenses Market
Medical Devices
Asia Pacific Hearing Aids Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
Global Breast Biopsy Devices Market