
 Global Retinal Vein Occlusion Market | 2026-2036
Global Retinal Vein Occlusion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Retinal Vein Occlusion Market Foresight
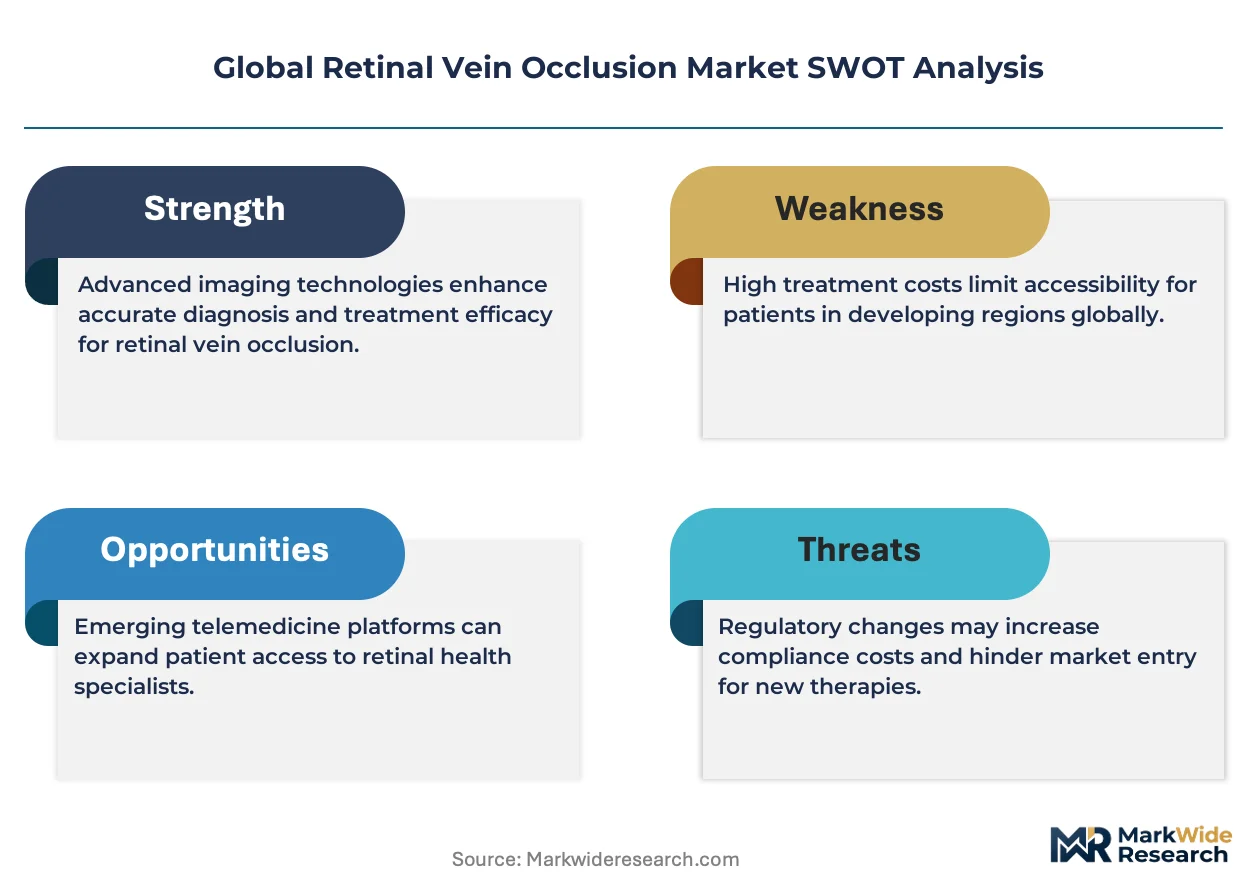
Ophthalmology clinic procurement is narrowing toward integrated therapy-delivery platforms that bundle diagnostic imaging with intravitreal injection workflows. Regeneron Pharmaceuticals leverages its Eylea franchise to anchor premium positioning across specialty eye hospitals in North America and Europe. F. Hoffmann-La Roche Ltd. sustains competitive pressure through sustained-delivery formulation research that could reduce injection frequency. Novartis AG navigates biosimilar competition by extending its Beovu label into broader retinal vascular indications.
Retinal vein occlusion denotes the blockage of venous outflow from the retina, typically arising from thrombus formation at arteriovenous crossings where hardened arteries compress the underlying vein, resulting in macular edema, retinal hemorrhage, and ischemic tissue damage that threatens central vision. The condition demands therapeutic intervention to restore vascular perfusion and suppress pathologic neovascularization. Anti-VEGF therapy dominates current clinical practice due to its established efficacy in resolving macular edema and improving visual acuity outcomes, while laser photocoagulation retains utility in ischemic branch presentations where anti-VEGF response proves incomplete. Combination therapies represent the fastest-growing treatment modality as physicians seek to extend injection intervals and reduce treatment burden for chronic patients. Surgical devices occupy a narrower margin pool given vitrectomy's reserve status for complicated cases.
The FDA governs ophthalmic biologic approvals through its Center for Drug Evaluation and Research, while the EU MDR reclassifies retinal laser devices under stricter conformity assessment procedures that extend time-to-market for new hardware entrants. Japan's PMDA maintains distinct pharmacovigilance requirements for intravitreal agents that shape post-market study obligations for manufacturers. Stakeholders must monitor how CMS reimbursement thresholds for office-based injections and EMA health technology assessments for combination regimens reshape prescribing economics across the major markets.
Market Dynamics
The retinal vein occlusion treatment landscape is restructuring around sustained-delivery formulation research that promises to reduce injection frequency and shift competitive advantage toward platform biologics with extended dosing intervals.
Growth Catalysts
- EU MDR Device Reclassification:The EU Medical Device Regulation's stricter conformity assessment for retinal laser devices is accelerating consolidation among established manufacturers with pre-certified quality systems, filtering out marginal hardware entrants.
- Specialty Eye Hospital Expansion:Integrated therapy-delivery platforms that bundle diagnostic imaging with intravitreal injection workflows are capturing procurement budgets across tertiary ophthalmology centers in the United States and Germany.
- Aging Demographics in Developed Markets:Japan's PMDA pharmacovigilance framework for intravitreal agents is shaping post-market study designs that manufacturers now front-load into clinical development, streamlining approval pathways for aging populations with high anti-VEGF therapy penetration.
Market Restraints
- Input Cost Concentration:Recombinant protein production for anti-VEGF biologics depends on mammalian cell culture capacity concentrated among contract manufacturers in Switzerland and the United States, exposing supply to facility contamination risks.
- Technical Limitation of Monotherapy:Incomplete response rates in ischemic branch retinal vein occlusion force continued reliance on laser photocoagulation, fragmenting treatment protocols and complicating outcomes-based contracting.
- Regulatory Friction from Biosimilar Pathways:The FDA's abbreviated approval framework for ophthalmic biologics is creating prescriber uncertainty around interchangeability, slowing uptake of follow-on agents despite price advantages.
Strategic Opportunities
- Underpenetrated Combination Regimens:Corticosteroid-anti-VEGF sequential therapy protocols represent whitespace in treatment guidelines across Spain and Italy, where reimbursement for combination approaches remains unsettled.
- Technology Convergence:Artificial intelligence-powered OCT analysis paired with automated injection planning systems is enabling same-visit diagnosis-to-treatment workflows that compress patient leakage between referral and intervention.
- Distribution Innovation via Office-Based Surgery Suites:Ambulatory surgical center licensing reforms in Texas and Florida are permitting retina specialists to capture facility fees previously directed to hospital outpatient departments.
Industry Challenges
- Vitreoretinal Surgeon Training Bottleneck:Fellowship program capacity in the United States and Japan is constraining the specialist pipeline needed to administer complex combination therapies and manage treatment-resistant cases.
- EU MDR Certification Timeline Compression:Retinal laser device manufacturers face extended notified body queue times that delay product launches and compress revenue windows before patent expiration of companion biologics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Retinal Vein Occlusion Market |
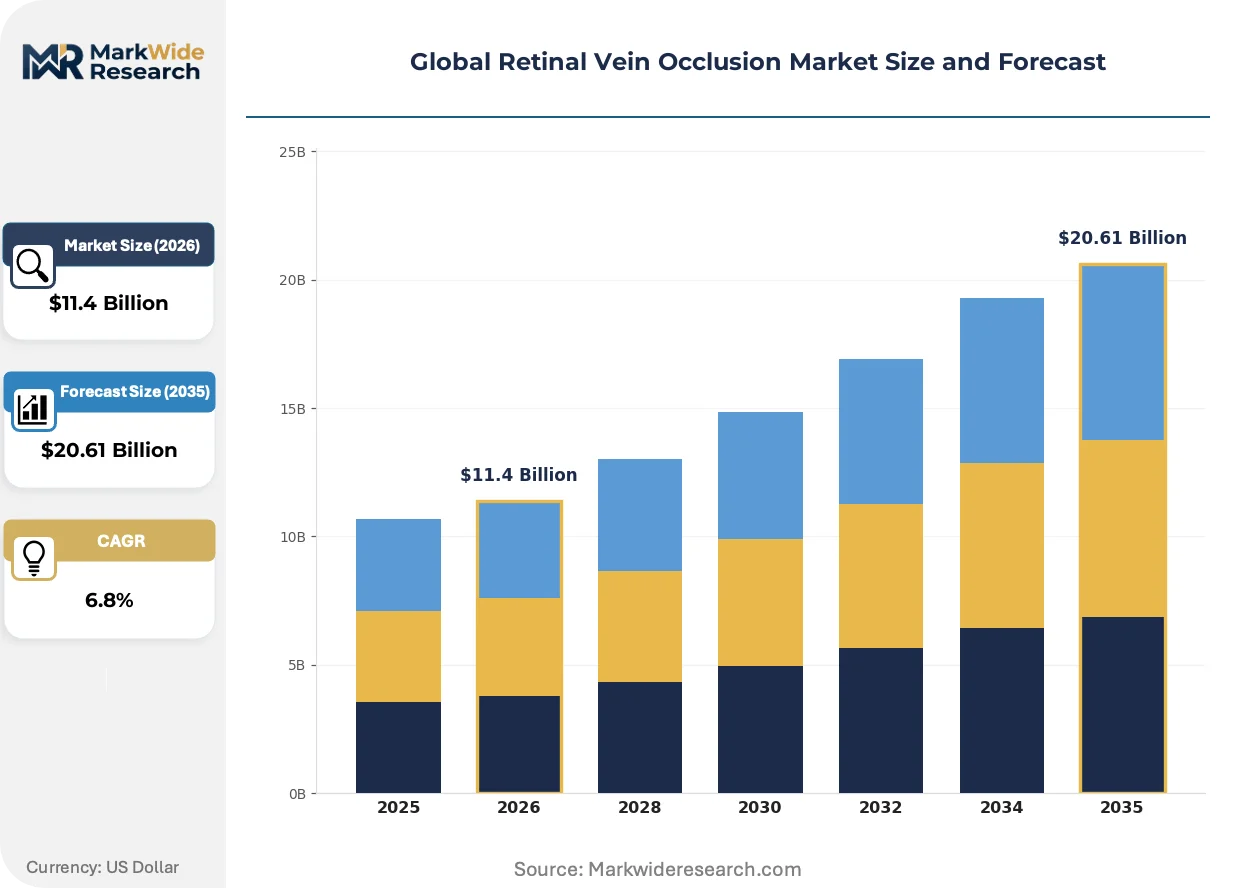
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Therapy, Corticosteroids, Laser Therapy, Surgical Devices Application: Macular Edema, Neovascularization, Ischemic Retinopathy, Visual Impairment End User: Ophthalmology Clinics, Specialty Eye Hospitals, Diagnostic Centers, Ambulatory Surgery Centers Treatment Modality: Intravitreal Injections, Laser Photocoagulation, Vitrectomy, Combination Therapies |
| Companies Covered | Regeneron Pharmaceuticals, F. Hoffmann-La Roche Ltd., Novartis AG, Bayer AG, AbbVie Inc., Allergan PLC, IRIDEX Corporation, Lumenis, Nidek Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Retinal Vein Occlusion Market Shifts & Advancements
Therapeutic modality preferences are fragmenting as physicians balance visual acuity outcomes against treatment burden, while regulatory frameworks on both sides of the Atlantic reshape commercialization economics for hardware and biologic entrants alike.
Sustained-release anti-VEGF implants are migrating from experimental status to standard-of-care consideration in chronic macular edema management. Retina specialists in Germany and the United Kingdom are piloting port-delivery systems that extend dosing intervals to six months. This migration from monthly injection schedules is compressing the addressable market for conventional intravitreal syringes while expanding the total treatable population by reducing clinic capacity constraints.
The FDA's Center for Drug Evaluation and Research is tightening pharmacovigilance requirements for novel sustained-delivery formulations through enhanced post-market cardiovascular monitoring. Manufacturers must now embed registry enrollment into commercial launch protocols. Sustained-release platform developers targeting branch retinal vein occlusion indications are responding by pre-emptively powering phase III trials for MACE endpoints that exceed prior anti-VEGF cardiovascular safety databases.
Hospital procurement committees are unbundling diagnostic imaging from injection services, forcing device manufacturers to demonstrate standalone cost-effectiveness for OCT angiography systems. Integrated platform vendors in North America are responding with per-scan pricing models that displace capital equipment purchases. This shift is most visible in United States multi-specialty ophthalmology groups consolidating under private equity ownership, where equipment utilization metrics now determine vendor selection.
Global Retinal Vein Occlusion Market Segmentation
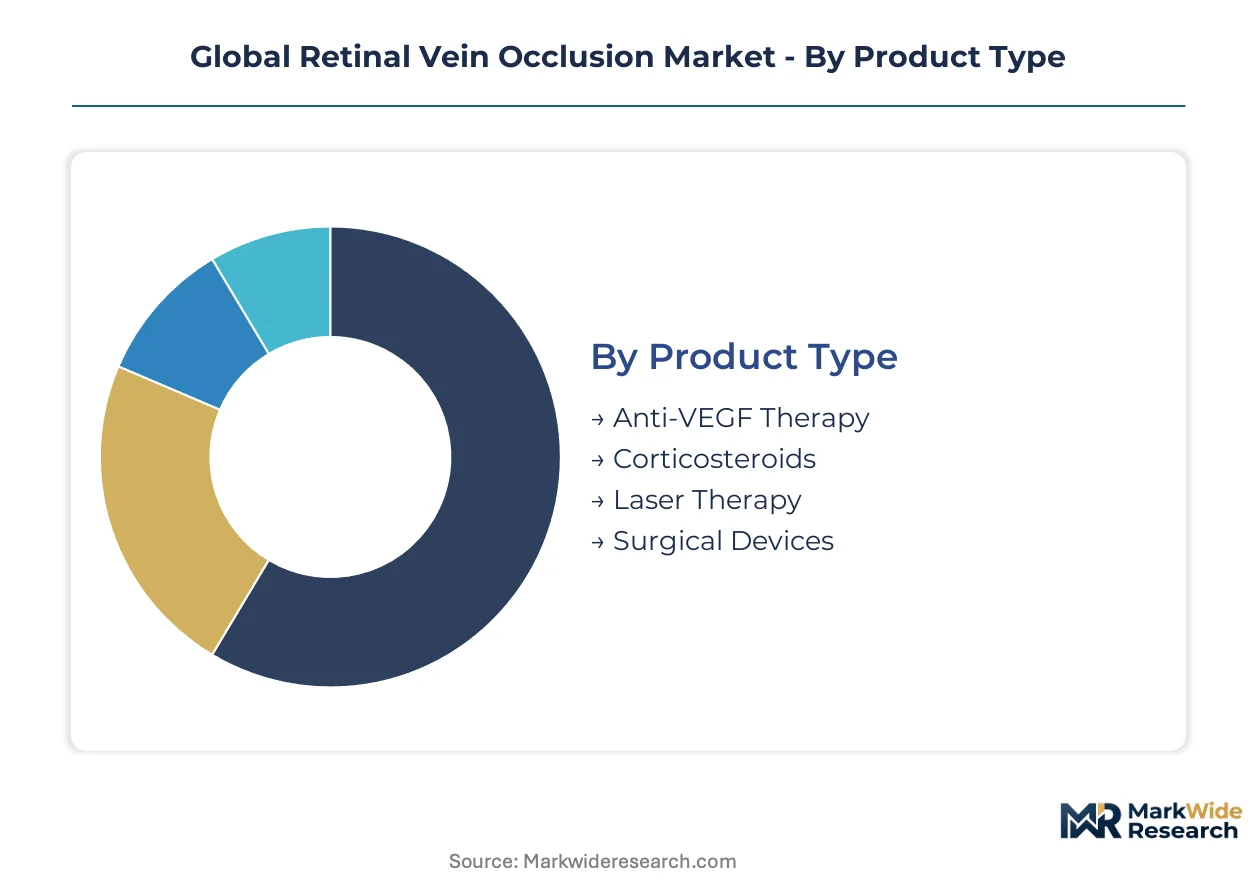
Therapeutic modality selection in retinal vein occlusion hinges on ischemic severity, macular edema persistence, and patient injection tolerance. Segmentation reveals where sustained-delivery formulations are displacing conventional dosing and which care settings capture the highest-value procedures.
Product Type:
Cost tier stratification separates premium biologics from commoditized hardware and generic alternatives, with reimbursement bandwidth determining accessible options across markets.
- Anti-VEGF Therapy:Recombinant protein agents that inhibit vascular endothelial growth factor signaling to resolve macular edema and suppress pathologic neovascularization. Demand concentrates in the United States and Germany where CMS and statutory health insurance cover monthly injection protocols without prior authorization barriers. Sustained-delivery formulation research is compressing addressable volume for conventional vials.
- Corticosteroids:Intraocular steroid implants and periocular injections targeting inflammatory mediators in refractory edema cases. Procurement in Japan's specialty eye hospitals is rising for patients with anti-VEGF contraindications or suboptimal response, driven by PMDA-approved dexamethasone implant labeling.
- Laser Therapy:Retinal photocoagulation systems delivering targeted thermal burns to ischemic zones and microaneurysms.
- Surgical Devices:Vitrectomy packs, illumination systems, and membrane peeling instruments for complicated tractional detachments.
Anti-VEGF therapy commands the established base. The steepest expansion runs through sustained-delivery corticosteroid platforms extending dosing intervals.
Application:
Clinical presentation severity dictates treatment intensity and reimbursement coding, with macular edema driving the majority of injectable volume.
- Macular Edema:Fluid accumulation in the central retina from compromised venous outflow, measured by central subfield thickness on spectral-domain OCT. United States ophthalmology clinics prioritize same-visit diagnosis-to-treatment workflows using AI-powered OCT analysis to compress referral-to-injection timelines.
- Neovascularization:Pathologic new vessel formation on the optic disc or retina from ischemic drive, threatening vitreous hemorrhage and tractional retinal detachment. Germany's statutory health insurance system reimburses anti-VEGF loading doses for proliferative presentations without step-therapy requirements.
- Ischemic Retinopathy:Retinal non-perfusion exceeding five disc diameters on fluorescein angiography.
- Visual Impairment:Functional vision loss quantified by ETDRS letter scores or Snellen equivalents.
Macular edema applications anchor current revenue. Neovascularization cases are climbing the fastest as screening protocols identify proliferative change earlier.
End User:
Customer type determines capital equipment requirements, staffing models, and facility fee capture, with vertical integration trends reshaping site-of-care economics.
- Specialty Eye Hospitals:Tertiary ophthalmology centers with dedicated retina services, surgical suites, and fellowship-trained specialists. Procurement in the United States is consolidating toward integrated therapy-delivery platforms bundling diagnostic imaging with intravitreal injection workflows.
- Ophthalmology Clinics:Private practice and group settings delivering outpatient medical retina care. Texas and Florida licensing reforms permitting office-based surgery suites are enabling facility fee capture previously directed to hospital outpatient departments.
- Diagnostic Centers:Imaging-focused facilities performing OCT, angiography, and electrophysiology.
- Ambulatory Surgery Centers:Licensed facilities for same-day surgical procedures including vitrectomy and laser.
Specialty eye hospitals command the established base. Ophthalmology clinics are gaining share fastest where regulatory reforms permit expanded procedure licensing.
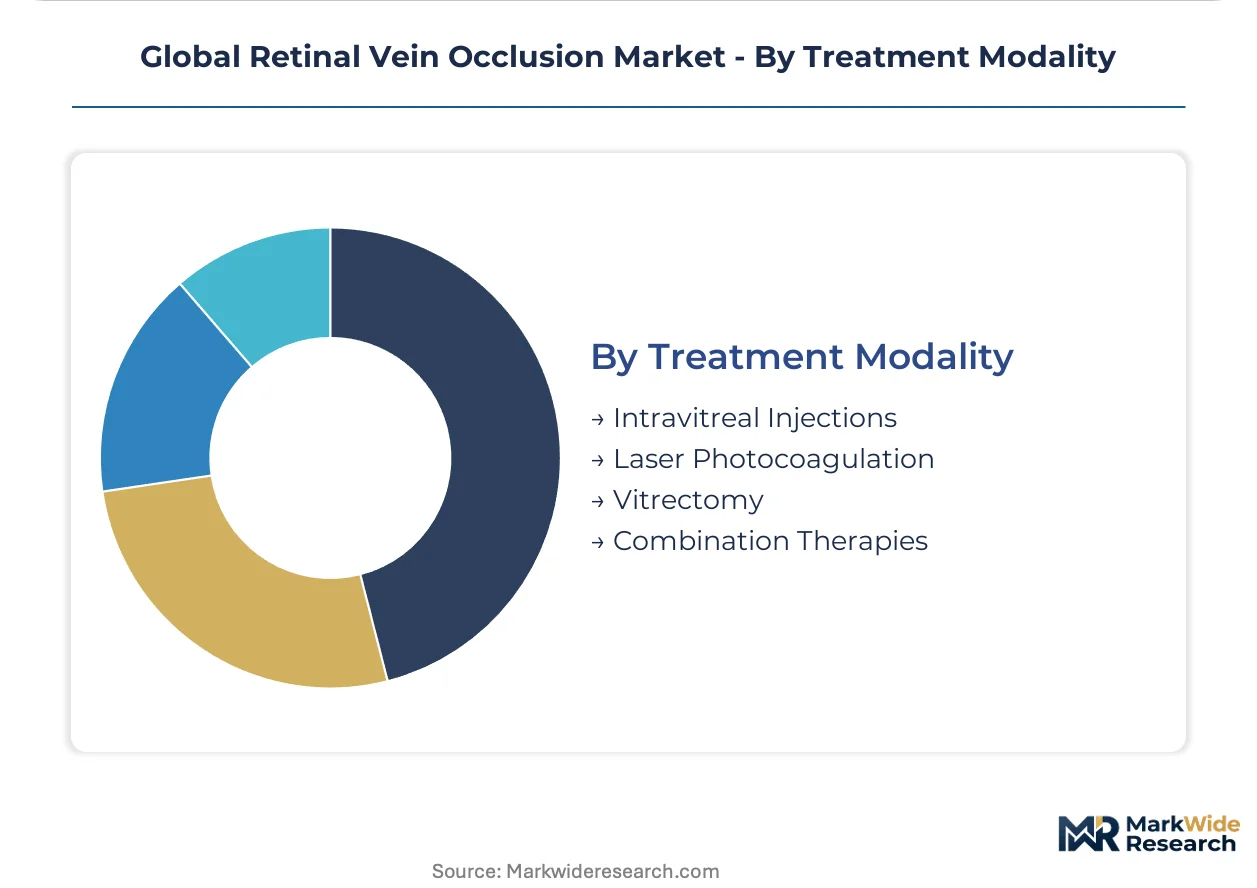
Treatment Modality:
Maturity curves separate established injection protocols from emerging combination approaches and reserve surgical interventions.
- Intravitreal Injections:Direct anti-VEGF or corticosteroid delivery into the vitreous cavity via pars plana needle insertion. Japan's PMDA pharmacovigilance framework shapes post-market study designs that manufacturers front-load into clinical development for aging populations with high therapy penetration.
- Combination Therapies:Sequential or concurrent anti-VEGF and corticosteroid protocols, or laser adjunct to pharmacotherapy. Spain and Italy represent whitespace where reimbursement for combination approaches remains unsettled despite clinical adoption.
- Laser Photocoagulation:Focal or pan-retinal photocoagulation for ischemic branch presentations.
- Vitrectomy:Pars plana vitrectomy with membrane peeling for tractional complications.
Intravitreal injections command the established base. Combination therapies are expanding most quickly as physicians seek to extend injection intervals and reduce treatment burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA ophthalmic drug approval pathways anchor United States market dynamics, while Japan's PMDA pharmacovigilance framework and Germany's statutory health insurance reimbursement rules shape commercialization timelines across the major developed markets.
United States
CMS reimbursement thresholds for office-based intravitreal injections and aging demographics drive anti-VEGF therapy penetration. The FDA's Center for Drug Evaluation and Research governs biologic approvals through enhanced post-market cardiovascular monitoring for sustained-delivery formulations. Retina specialists in Texas and Florida capture facility fees through office-based surgery suite licensing reforms.
Germany
Statutory health insurance covers anti-VEGF loading doses for proliferative presentations without step-therapy requirements. The EU MDR reclassifies retinal laser devices under stricter conformity assessment procedures that extend time-to-market. Tertiary ophthalmology centers in Baden-Württemberg and Bavaria consolidate procurement toward integrated therapy-delivery platforms.
Japan
PMDA pharmacovigilance requirements for intravitreal agents shape post-market study obligations that manufacturers front-load into clinical development. Dexamethasone implant labeling drives procurement in specialty eye hospitals for patients with anti-VEGF contraindications. Fellowship program capacity in the Kanto region constrains the specialist pipeline for complex combination therapies.
United Kingdom
NICE health technology assessments for combination regimens reshape prescribing economics alongside NHS England commissioning frameworks. Port-delivery systems piloted in London and Manchester extend dosing intervals to six months for chronic macular edema patients. Private equity-owned multi-specialty ophthalmology groups prioritize equipment utilization metrics in vendor selection.
Spain
Regional health service reimbursement for corticosteroid-anti-VEGF sequential therapy remains unsettled despite clinical adoption in Madrid and Barcelona. The EU MDR certification timeline compression affects retinal laser device launches before companion biologic patent expiration. Whitespace in treatment guidelines creates opportunity for combination protocol establishment.
Global Retinal Vein Occlusion Market Competitive Landscape
Platform biologic developers and sustained-delivery specialists split the market between conventional injection franchises and next-generation interval-extension technologies. Consolidation concentrates among large-cap pharmaceutical firms with established ophthalmology divisions, while mid-tier laser device manufacturers face EU MDR-driven attrition. Two strategic archetypes dominate: integrated therapy-delivery platform vendors bundling diagnostic imaging with injection workflows, and pure-play sustained-release formulation researchers. Competitive moves center on M&A for complementary device assets and strategic partnerships for AI-powered OCT analysis capabilities.
Within the platform biologic tier, Regeneron Pharmaceuticals exemplifies premium positioning across North American and European specialty eye hospitals. F. Hoffmann-La Roche Ltd. occupies a position emphasizing sustained-delivery formulation research. Novartis AG represents the biosimilar-navigation archetype through label extension strategies. These three pharmaceutical firms anchor the competitive structure while IRIDEX Corporation and Lumenis sit within the device manufacturer segment facing regulatory headwinds.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Bayer AG |
| AbbVie Inc. |
| Allergan PLC |
| IRIDEX Corporation |
| Lumenis |
| Nidek Co., Ltd. |
| Others |
Supply & Pricing Matrix
Single-source mammalian cell culture capacity in Switzerland and the United States determines both the premium commanded by sustained-delivery formulations and the vulnerability of conventional anti-VEGF vial pricing to facility contamination events. This concentration compresses margins for commoditized intravitreal syringes while amplifying pricing power for platform biologics with extended dosing intervals.
Pricing Analysis
The customization-premium spread between port-delivery systems and standard intravitreal vials runs through three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture value from six-month dosing intervals and bundled diagnostic-imaging workflows, while standard vials face cost compression from biosimilar entry and reimbursement coding pressure. Price differentiation hinges on formulation patent life and PMDA pharmacovigilance certification status. Price erosion runs through the standard tier as CMS tightens office-based injection reimbursement thresholds. Ophthalmology clinics in Texas and Florida show highest price sensitivity where facility fee capture depends on ASC licensing status.
Supply Chain Analysis
Export-control restrictions on recombinant protein production technology limit capacity expansion outside established manufacturing hubs. Active pharmaceutical ingredient production centers on Switzerland, the United States, and contract manufacturers in Singapore. Raw material dependencies include CHO cell lines, serum-free media formulations, and aseptic fill-finish components. Supply chain risk centers on single-source vulnerability for high-yield cell culture platforms. Distribution runs through cold-chain logistics networks serving specialty eye hospitals and consolidated ophthalmology group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where sustained-delivery formulation research is collapsing the addressable volume for conventional injection workflows while expanding treatable population through reduced clinic capacity constraints. Interoperability between AI-powered OCT analysis and automated injection planning systems is redefining procurement criteria.
For Market Incumbents: Build regulatory-data moats by embedding cardiovascular outcome registries into commercial launch protocols ahead of FDA pharmacovigilance tightening. Consolidate manufacturing capacity through captive supply of CHO cell culture platforms in Switzerland to insulate against contract manufacturer queue delays. Defend against biosimilar erosion by extending label indications into branch retinal vein occlusion subtypes where response heterogeneity complicates interchangeability. For New Entrants and Emerging Players: Pursue whitespace in corticosteroid-anti-VEGF sequential therapy protocols across Spain and Italy where regional health service reimbursement remains unsettled. Target ambulatory surgery center licensing reforms in Texas and Florida for facility fee capture models. Anchor go-to-market strategy through AI-powered OCT analysis partnerships that compress diagnosis-to-treatment workflows for same-visit intervention. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform biologic developers with sustained-delivery pipelines over hardware-dependent laser device manufacturers facing EU MDR attrition. Long-term viability hinges on interval-extension technology maturation and ophthalmology clinic consolidation under private equity ownership. Acquisition archetypes include mid-tier sustained-release formulation specialists with PMDA-frontloaded clinical data packages. Watch for EU MDR certification timeline compression as inflection signal for device manufacturer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Sustained-Delivery Formulation Development | Port-delivery systems extending dosing intervals to six months reduce clinic capacity constraints and expand treatable population in Germany and the United Kingdom. |
| AI-Powered OCT Integration | Automated injection planning systems paired with diagnostic imaging enable same-visit workflows that compress patient leakage between referral and intervention. |
| EU MDR Certification Acceleration | Retinal laser device manufacturers with pre-certified quality systems capture consolidation benefits as marginal entrants face extended notified body queue times. |
| Office-Based Surgery Suite Licensing | Texas and Florida regulatory reforms permit retina specialists to capture facility fees previously directed to hospital outpatient departments. |
| Biosimilar Interchangeability Strategy | FDA abbreviated approval framework creates prescriber uncertainty that originators exploit through indication extension into treatment-resistant subtypes. |
Research Methodology
A standing panel of retina specialists, formulary directors at statutory health insurers, hospital procurement managers, and regulatory affairs leads provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA Center for Drug Evaluation and Research filings, EMA health technology assessments, PMDA pharmacovigilance databases, and CMS Medicare reimbursement coding updates. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Scenario-bracketing around sustained-delivery formulation approval timelines and EU MDR certification compression shaped analytical framework development across the projection horizon. Segmentation dimensions modeled include therapeutic modality, clinical presentation severity, end-user facility type, and regional regulatory cluster. CAGRs derived from procedure volume trajectories and pricing tier migration patterns, with inputs from anti-VEGF injection frequency data and ophthalmology fellowship program capacity constraints.
Sensitivities concentrate around FDA pharmacovigilance tightening for cardiovascular outcomes and EU MDR notified body queue dynamics. Forecasts reflect assumptions on sustained-delivery platform adoption curves and biosimilar interchangeability prescriber acceptance. Material shifts in CMS office-based injection reimbursement thresholds or PMDA post-market study obligation expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Global Artificial Tear Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Retina Health Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market