
 Ophthalmic Disease Therapeutics Market | 2026-2036
Ophthalmic Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Disease Therapeutics Market Intelligence
The end-user focus for ophthalmic therapeutics is pivoting from general hospitals toward specialty eye clinics and ambulatory surgical centers. This shift favors specialized care models and targeted drug delivery. Regeneron Pharmaceuticals, Inc. leverages its strong position in retinal disorder drugs. Novartis AG sustains a broad portfolio, while AbbVie Inc. competes through its established dry eye disease franchise.
Ophthalmic disease therapeutics are pharmaceutical agents formulated to treat pathologies of the eye. These sterile preparations, including injectable biologics and topical solutions, are designed for targeted delivery to ocular tissues. Their purpose is to manage conditions like glaucoma and macular degeneration to preserve vision. Retinal disorder drugs for conditions such as diabetic retinopathy represent the highest-value segment, while anti-glaucoma agents form a mature category. Treatments for dry eye syndrome are expanding due to environmental and lifestyle shifts.
Market access depends on clearance from regulators like the US FDA and the European Medicines Agency (EMA). In China, the NMPA sets local clinical trial requirements. These agencies' mandates for safety and efficacy data govern product development timelines and costs. Success for drug developers will hinge on navigating complex reimbursement landscapes and adopting digital patient support platforms.
Market Dynamics
The central force shaping the ophthalmic therapeutics market is the ascendance of biologic drugs for retinal diseases. This shift from small molecules to complex, injectable proteins requires specialized manufacturing, cold chain logistics, and administration in clinical settings, fundamentally altering cost structures and care delivery models.
Growth Catalysts
- Demographic Pressures:An aging population in China is increasing the incidence of age-related macular degeneration, creating a concentrated source of demand for anti-VEGF therapies and other retinal treatments.
- Drug Delivery Innovation:The development of novel sustained-release devices, such as biodegradable implants and punctal plugs, enables less frequent dosing for chronic conditions like glaucoma and uveitis, improving patient adherence.
- Regulatory Incentives:The US FDA's Breakthrough Therapy Designation provides an expedited development and review pathway for drugs treating serious conditions, encouraging investment in novel treatments for rare ophthalmic diseases.
Market Restraints
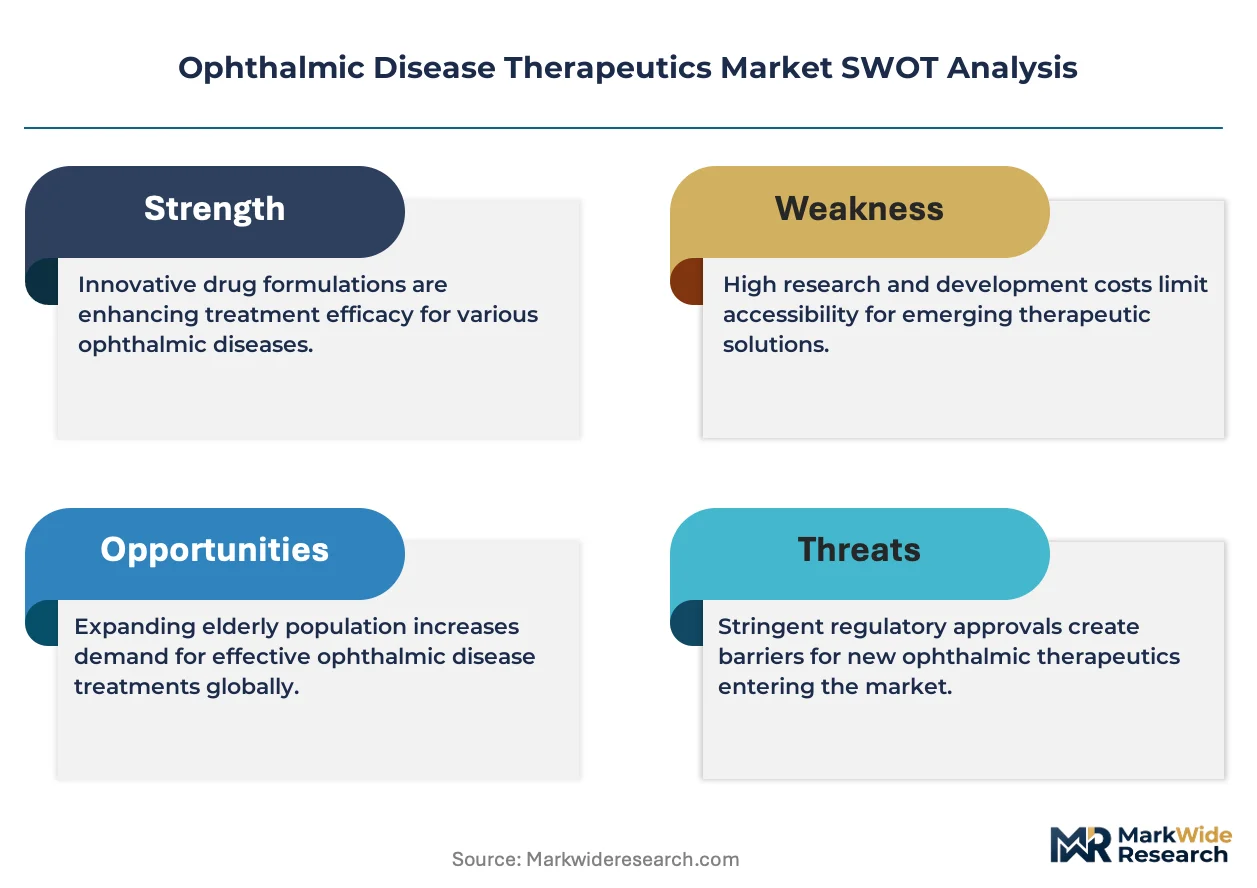
- High Development Costs:The research and manufacturing of biologic therapies, particularly gene therapies and monoclonal antibodies, involve substantial capital investment, creating high barriers to entry for smaller firms.
- Patent Expiration:The loss of market exclusivity for blockbuster small-molecule drugs, especially anti-glaucoma agents, leads to rapid price erosion from generic competition, pressuring revenue in mature segments.
- Stringent Clinical Endpoints:Regulators like the EMA and NMPA mandate rigorous, long-term clinical trials with specific visual acuity endpoints, making product development a costly and high-risk endeavor.
Strategic Opportunities
- Gene Therapy Development:Targeting monogenic inherited retinal diseases like retinitis pigmentosa with gene therapies offers a path to curative treatments and commands premium pricing, representing a significant area for value creation.
- Expansion in Southeast Asia:Growing healthcare expenditure and improving diagnostic infrastructure in countries like Vietnam and Thailand present an opportunity to introduce established therapies for diabetic retinopathy and glaucoma.
- Digital Health Integration:Developing digital platforms that connect with diagnostic devices and support patient monitoring can improve treatment outcomes and create new service-based revenue streams for therapy providers.
Industry Challenges
- Reimbursement Hurdles:Securing favorable reimbursement for high-cost therapies from national payers and private insurers is a major operational challenge, often delaying patient access after regulatory approval is achieved.
- Cold Chain Logistics:Maintaining the integrity of temperature-sensitive biologics from the factory to the clinic requires a complex and expensive cold chain, posing a significant logistical challenge, especially in emerging markets.
- Specialized Talent Scarcity:A shortage of retinal surgeons and clinical trial personnel proficient in administering and monitoring advanced therapies like cell and gene treatments can constrain market growth and research capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Disease Therapeutics Market |
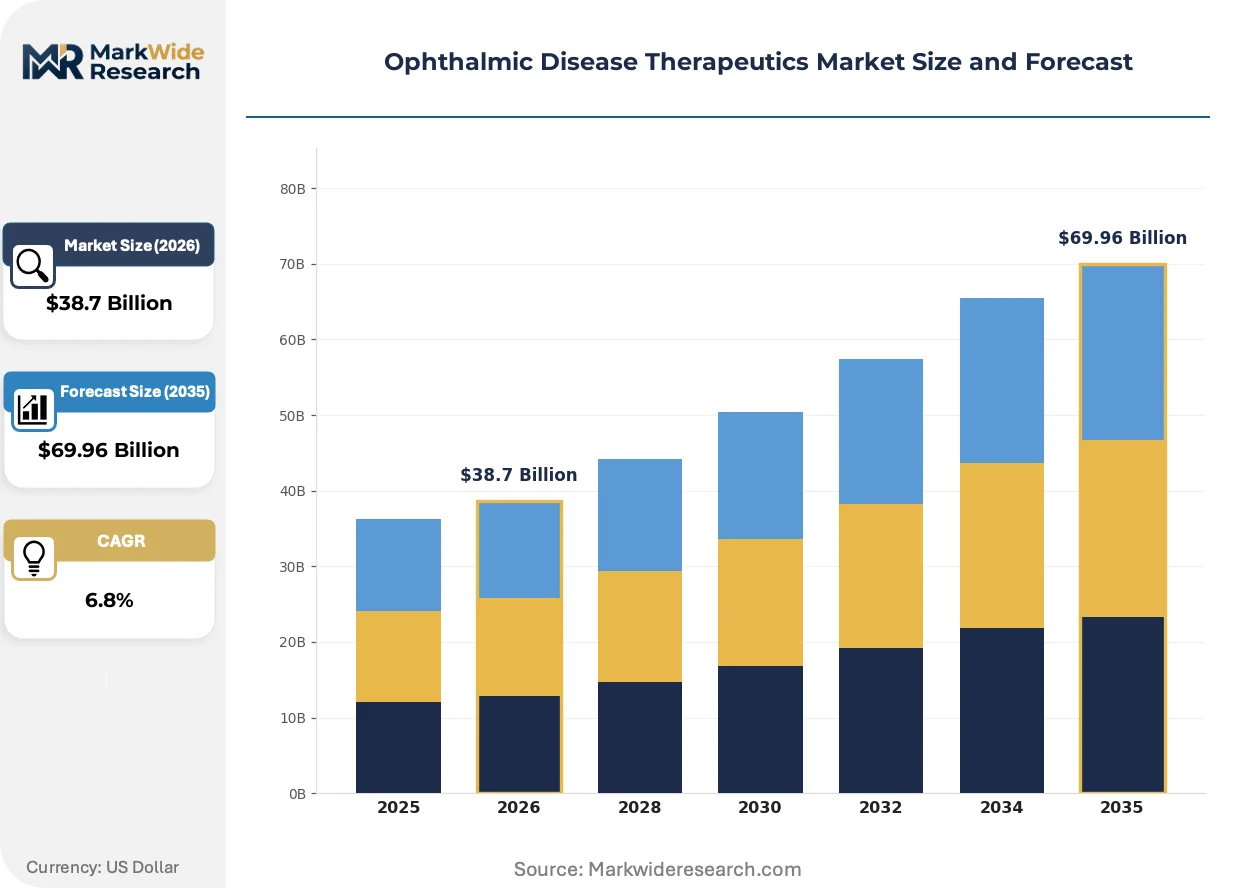
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Glaucoma Agents, Anti-Inflammatory Drugs, Anti-Infective Drugs, Retinal Disorder Drugs, Dry Eye Syndrome Treatments, Others Therapy Area: Glaucoma, Age-Related Macular Degeneration, Diabetic Retinopathy, Cataract, Uveitis, Corneal Diseases End User: Hospitals, Specialty Eye Clinics, Ambulatory Surgical Centers, Research Institutes, Home Care Providers Delivery Mode: Topical, Injectable, Oral, Implantable, Sustained Release Devices, Others |
| Companies Covered | Regeneron Pharmaceuticals, Inc., AbbVie Inc., Novartis AG, Bayer AG, F. Hoffmann-La Roche Ltd., Alcon, Bausch Health Companies Inc., Santen Pharmaceutical Co., Ltd., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Disease Therapeutics Market Strategic Shifts & Innovations
Biologic-driven innovation is redefining treatment protocols for chronic eye diseases. The market is moving toward therapies that offer longer duration of action, personalized efficacy, and integration with digital health ecosystems for improved management of patient outcomes.
Sustained-release drug delivery systems are becoming a cornerstone of next-generation therapeutics. These platforms, including intravitreal implants and drug-eluting contact lenses, are primarily adopted by specialty eye clinics to manage chronic conditions. This technology is automating the dosing regimen for diseases like wet AMD and diabetic macular edema, reducing the significant treatment burden associated with frequent injections.
Efforts by regulators to accelerate access to novel medicines are influencing development strategies. The European Medicines Agency's PRIME scheme, for example, offers early and enhanced support to developers of medicines that target an unmet medical need. This regulatory pathway particularly benefits companies developing gene therapies for rare inherited retinal dystrophies, potentially shortening their time to market in the EU.
Care delivery is shifting from general hospitals to specialized ambulatory surgical centers and private clinics. This decentralization is driven by patient preference for convenience and the specialized equipment required for administering advanced injectable and implantable therapies. The trend is most visible in North America, where these specialized centers capture a growing share of procedures for cataracts, glaucoma, and retinal disorders.
Ophthalmic Disease Therapeutics Market Segmentation
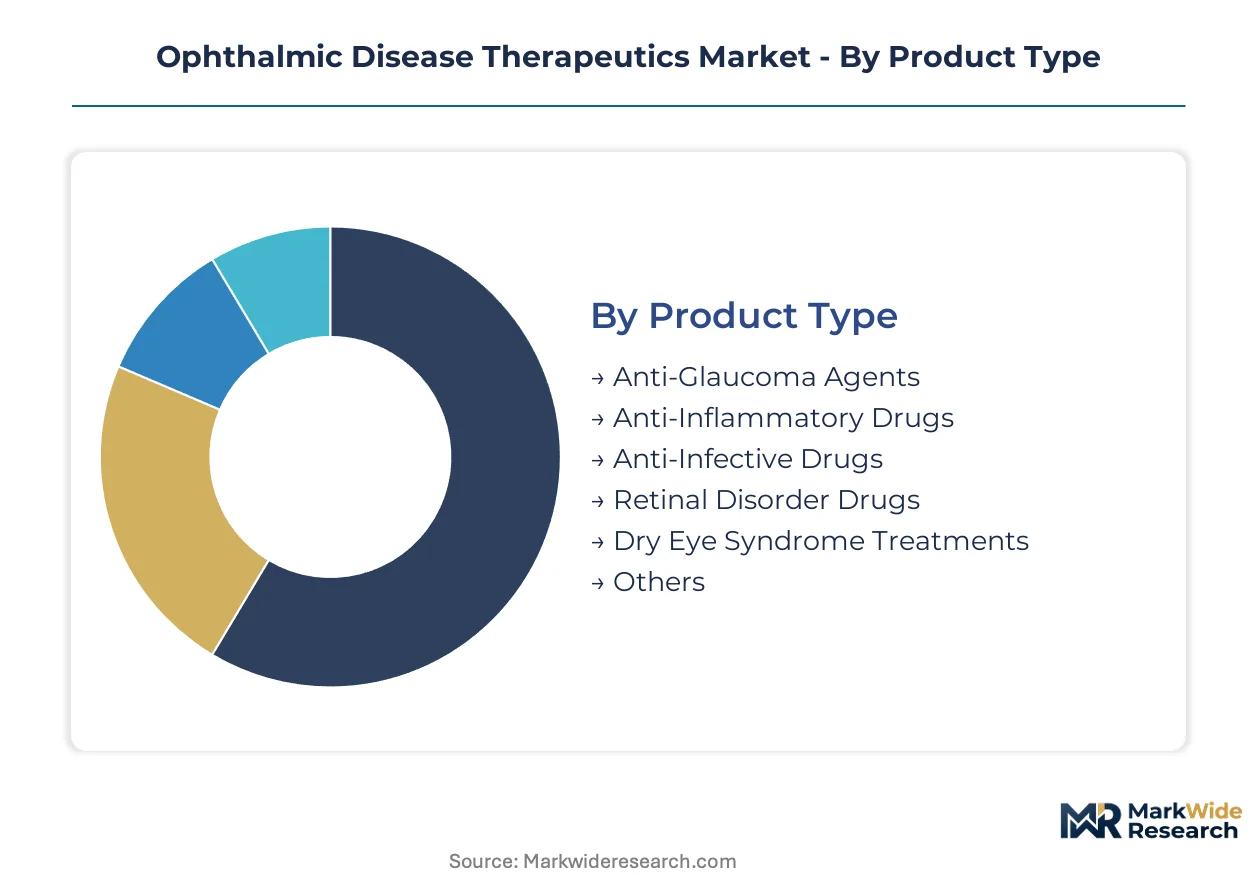
The ophthalmic disease therapeutics market is granularly segmented to reflect the diverse treatment modalities, disease targets, and patient care settings. This detailed classification helps stakeholders understand the specific drivers and constraints impacting each sub-segment, guiding strategic investment and product development.
Product Type:
The ophthalmic therapeutics market features a spectrum from highly standardized, broad-application products to highly specialized, patient-specific formulations.
- Retinal Disorder Drugs:These complex biologic agents, often anti-VEGF therapies, target conditions like diabetic retinopathy and age-related macular degeneration. Demand is particularly concentrating in China due to its aging population and increasing incidence of these diseases.
- Dry Eye Syndrome Treatments:Formulations include artificial tears, anti-inflammatory drops, and immunomodulators designed to alleviate symptoms and address underlying causes of ocular surface dryness. The market for these treatments is expanding due to environmental factors and lifestyle shifts globally.
- Anti-Glaucoma Agents:This category comprises various topical drops and oral medications that reduce intraocular pressure, including prostaglandins, beta-blockers, and alpha-agonists. These represent a mature segment with established treatment protocols.
- Anti-Inflammatory Drugs:These include corticosteroids and non-steroidal anti-inflammatory drugs (NSAIDs) used to manage inflammation post-surgery or for conditions like uveitis.
- Anti-Infective Drugs:Antibiotics, antivirals, and antifungals are formulated as topical drops or ointments to treat ocular infections affecting the cornea, conjunctiva, or eyelids.
- Others:This diverse segment includes diagnostic agents, nutritional supplements, and other niche therapeutic compounds for less common ophthalmic conditions.
Most installed capacity flows through Anti-Glaucoma Agents. Expansion is steepest in Retinal Disorder Drugs.
Therapy Area:
Demand volume for ophthalmic therapeutics varies significantly across different therapy areas, influenced by disease prevalence and treatment efficacy.
- Age-Related Macular Degeneration:Therapies, primarily anti-VEGF injectables, aim to slow disease progression and preserve central vision in older adults. China's demographic shifts are creating a concentrated source of demand for these treatments.
- Diabetic Retinopathy:This therapy area focuses on managing a complication of diabetes that damages retinal blood vessels, often treated with anti-VEGF agents or laser photocoagulation. Treatments for this condition represent a high-value segment due to its chronic nature and significant patient population.
- Glaucoma:This condition involves damage to the optic nerve, often due to high intraocular pressure, with treatments focused on reducing pressure to prevent vision loss.
- Cataract:While primarily treated surgically, this segment includes pre- and post-operative medications like anti-inflammatory and anti-infective drops to manage recovery.
- Uveitis:Treatments for this inflammatory condition affecting the uvea often involve corticosteroids or immunomodulatory drugs to control inflammation and prevent tissue damage.
- Corneal Diseases:This category covers a range of conditions affecting the transparent outer layer of the eye, treated with various drops, ointments, or specialized contact lenses.
Age-Related Macular Degeneration treatments demonstrate the most substantial market value. Glaucoma therapies continue to hold a significant, yet mature, share.
End User:
End-user preferences and specialized infrastructure requirements dictate the customer type segmentation in ophthalmic therapeutic delivery.
- Specialty Eye Clinics:These facilities offer focused diagnostic and treatment services for a range of ocular conditions, often equipped for advanced procedures like intravitreal injections. Growth is pronounced in this segment due to a pivot from general hospitals towards specialized care models.
- Ambulatory Surgical Centers:These centers provide outpatient surgical procedures, including cataract and glaucoma surgeries, offering convenience and cost-effectiveness compared to traditional hospitals. This shift favors specialized care models and targeted drug delivery.
- Hospitals:General hospitals provide comprehensive eye care, particularly for acute cases, complex surgeries, and patients with co-morbidities requiring broader medical support.
- Research Institutes:These entities focus on preclinical and clinical studies, developing new ophthalmic therapies and understanding disease mechanisms.
- Home Care Providers:This segment involves the administration of ophthalmic treatments, primarily topical drops, by patients or caregivers in a home setting.
Specialty Eye Clinics consistently capture a growing share of patient visits. Hospitals maintain a foundational role for complex surgical interventions.
Delivery Mode:
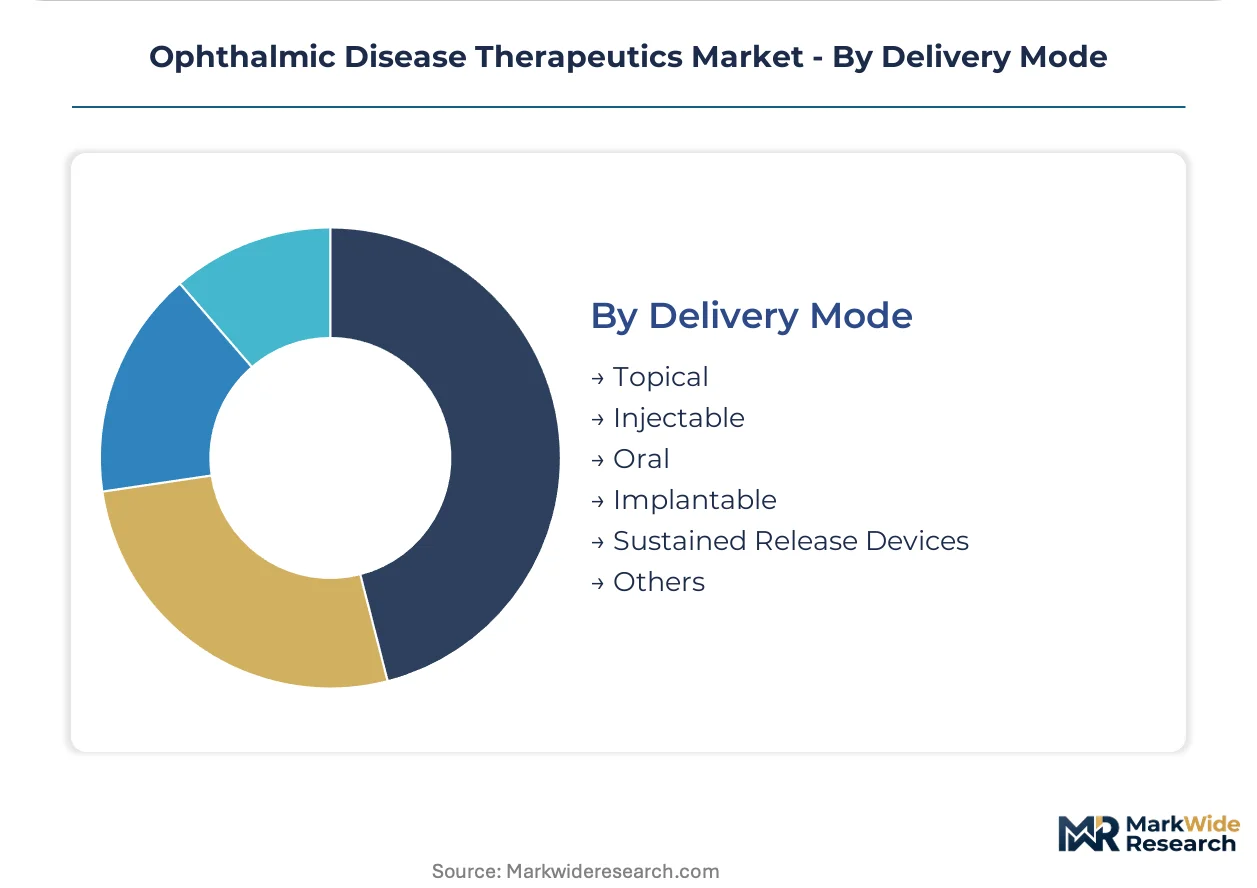
The maturity curve for ophthalmic drug delivery modes ranges from established topical solutions to cutting-edge sustained-release technologies.
- Sustained Release Devices:These innovative platforms, including implants and punctal plugs, offer prolonged drug delivery, reducing dosing frequency for chronic conditions. The introduction of novel sustained release devices is enabling new treatment paradigms.
- Injectable:This mode involves direct administration into the eye, primarily intravitreal injections for retinal diseases, requiring specialized clinical settings. The ascendance of biologic drugs for retinal diseases drives this segment.
- Topical:Eye drops and ointments represent the most common and least invasive delivery method for anterior segment conditions like dry eye and glaucoma.
- Oral:Systemic medications are sometimes used to treat ophthalmic conditions with systemic origins or to manage inflammation.
- Implantable:Biodegradable or non-biodegradable implants provide long-term drug release, often for chronic conditions like uveitis, reducing the need for frequent clinic visits.
- Others:This category encompasses emerging delivery methods such as gene therapy vectors, contact lenses, or iontophoresis.
Injectable therapies represent a large and expanding segment for retinal disorders. Sustained Release Devices are gaining share due to improved patient adherence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston-Cambridge biotech cluster drives significant ophthalmic innovation, attracting substantial investment in advanced therapies. This region, alongside other global hubs, shapes the market for specialized eye care solutions. Research and development activities are concentrated in these areas, influencing treatment paradigms worldwide.
United States
Demand for age-related macular degeneration and diabetic retinopathy therapies remains consistently high across the United States. The US FDA's Breakthrough Therapy Designation expedites development for novel treatments, encouraging investment in rare ophthalmic conditions. California's Silicon Valley attracts significant digital health integration initiatives for patient monitoring and diagnostics.
China
China's aging population creates a concentrated source of demand for anti-VEGF therapies. The NMPA mandates local clinical trial requirements, influencing product launch strategies for drug developers. The Yangtze River Delta region sees rapid expansion of specialized eye clinics equipped for advanced procedures.
Germany
Germany's established healthcare infrastructure supports the adoption of advanced biologic ophthalmic drugs. The EMA's PRIME scheme offers early support to developers targeting unmet medical needs within the European Union. Bavaria hosts a growing number of ophthalmic research institutions, driving innovation in gene therapy.
Japan
Japan's high elderly population emphasizes preventative care and long-term management of chronic eye diseases. The PMDA's accelerated review processes facilitate faster market access for innovative ophthalmic treatments. The Tokyo area is home to major pharmaceutical companies investing heavily in ophthalmic R&D.
India
India's expanding access to healthcare and rising disposable incomes drive demand for glaucoma and cataract treatments. The CDSCO's initiatives streamline drug approvals, supporting the introduction of new therapies. Hyderabad's Genome Valley is becoming a key hub for biosimilar and generic ophthalmic drug manufacturing.
Ophthalmic Disease Therapeutics Market Key Industry Players
Strategic partnerships dominate the current landscape, allowing companies to pool resources for complex R&D and market access. The market exhibits a tiered structure, with established pharmaceutical giants coexisting with specialized biotech innovators and device manufacturers. Archetypes include broad-portfolio players and niche developers focusing on specific retinal disorders or dry eye treatments. Key competitive moves include portfolio diversification, geographic expansion into emerging markets, and technology licensing agreements.
Within the established pharmaceutical archetype, Novartis AG and Bayer AG represent significant players with broad portfolios spanning various ophthalmic conditions and delivery modes. Regeneron Pharmaceuticals, Inc. exemplifies a specialized biotech innovator, anchoring its position in retinal disorder drugs, particularly anti-VEGF therapies. AbbVie Inc. occupies a strong position within the dry eye disease segment, leveraging its established franchise and expanding its therapeutic reach. These companies collectively influence treatment standards, drive innovation, and shape market access strategies across the global ophthalmic therapeutics landscape.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals, Inc. |
| AbbVie Inc. |
| Novartis AG |
| Bayer AG |
| F. Hoffmann-La Roche Ltd. |
| Alcon |
| Bausch Health Companies Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Merck & Co., Inc. |
| Others |
Cost & Logistics Intelligence
The **Cell Culture Media Index**, reflecting costs for biologic drug production, cascades through the ophthalmic therapeutics supply chain, influencing the final pricing tiers of advanced treatments. This index directly impacts the cost of goods for complex injectable proteins and gene therapies.
Pricing Analysis
Input-cost pass-through is a significant factor in ophthalmic therapeutics, particularly for biologic drugs requiring specialized manufacturing. Value-based pricing models dominate for novel, high-efficacy treatments like gene therapies, reflecting their long-term impact on vision preservation. Price differentiation stems from regulatory approval status, such as US FDA or EMA clearance, and the integration of specialized delivery systems. Pricing pressure stems from generic competition in mature segments, especially for anti-glaucoma agents. National payers and private insurers exhibit the highest price sensitivity for high-cost biologics, while specialty eye clinics prioritize clinical efficacy for patient outcomes.
Supply Chain Analysis
Regional distribution centers form the backbone of the ophthalmic therapeutics supply chain, enabling efficient delivery to specialized clinics. Geographic supply concentration for active pharmaceutical ingredients (APIs) includes India for biosimilars and China for generic ophthalmic compounds, while advanced biologics manufacturing centers in the United States and Europe. Raw material dependencies include specialized cell culture media, sterile excipients, and advanced packaging components. Cold chain logistics for temperature-sensitive biologics poses a significant structural risk, particularly across diverse geographies. Distribution runs through a dual model: direct-to-clinic for injectable biologics and pharmacy networks for topical solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage opportunity, leveraging lower clinical trial and manufacturing costs in regions like India against premium pricing in developed markets for innovative therapies.
For Market Incumbents: Deploy advanced R&D in gene therapy to secure future pipeline growth and address unmet medical needs in rare ophthalmic diseases. Diversify current portfolios by investing in sustained-release delivery platforms, which improve patient adherence and differentiate products from frequent-dosing regimens. Control specialized talent pools of retinal surgeons and clinical trial personnel, mitigating a critical industry challenge. This strategy defends against the threat of patent expiration for blockbuster small-molecule drugs.
For New Entrants and Emerging Players: Launch via digital health platforms that integrate diagnostic devices and patient monitoring, creating new service-based revenue streams. Target underpenetrated geographies in Southeast Asia for established therapies like those for diabetic retinopathy and glaucoma, leveraging improving diagnostic infrastructure. The home care provider segment for simpler topical treatments represents a penetrable entry point. Focus on niche inherited retinal diseases with orphan drug designations to gain expedited regulatory pathways.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized biotech innovators developing curative gene therapies for monogenic inherited retinal diseases. These companies offer significant long-term viability through premium pricing and transformative patient outcomes over a 5-10 year window. Identify acquisition targets with robust intellectual property and a clear path to regulatory approval. The signal to watch is the successful completion of Phase 3 clinical trials for novel gene therapies, particularly those with US FDA Breakthrough Therapy Designation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel biologics targeting chronic retinal conditions. |
| Regulatory Approval Pathway Optimization | Shortens time-to-market for innovative therapies through expedited programs like EMA PRIME. |
| Licensing Agreement for Sustained Release Devices | Enhances patient adherence and reduces treatment burden for chronic ophthalmic diseases. |
| Manufacturing Scale-Up for Biologics | Ensures consistent supply of complex injectable proteins to meet growing global demand. |
| Pipeline Diversification into Gene Therapy | Addresses high-value unmet needs for inherited retinal dystrophies with curative potential. |
Research Approach
Direct dialogue with ophthalmic surgeons, regulatory affairs specialists, hospital procurement managers, and pharmaceutical R&D executives provided critical qualitative insights. This primary research was rigorously validated through extensive secondary data analysis, including US FDA filings, EMA submissions, ClinicalTrials.gov, and national health registries. The approach incorporated both bottom-up and top-down triangulation to ensure comprehensive market sizing and segmentation across all defined parameters.
A bottom-up analysis, validated by top-down market sizing, formed the core of the forecast framework across the analysis window. Segmentation dimensions modeled included product type, therapy area, end user, delivery mode, and regional regulatory compliance. Compound annual growth rates were derived from historical data and projected market dynamics. Key industry-specific forecast inputs included the incidence rates of age-related macular degeneration and patent expiration schedules for established therapies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory changes or clinical trial failures. All projections reflect assumptions documented within this study. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Nystagmus Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Global Automated Ophthalmic Perimeters Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Astigmatism Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Global Tonometer Market