
 PVA Eye Spear Market | 2026-2036
PVA Eye Spear Market Size, Share, and Industry Trends Forecast 2026-2036
PVA Eye Spear Market Insights
China's Zhejiang province is reshaping regional supply dynamics through expanded polymer molding capacity for surgical consumables. Alcon Laboratories leverages integrated ophthalmology portfolios to sustain premium positioning across eye care settings. Beaver-Visitec International anchors North American distribution through specialized surgical instrument channels. Huizhou Foryou Medical Devices competes on cost-efficient sterile disposables for high-volume cataract procedures.
A PVA Eye Spear is a polyvinyl alcohol foam-tipped surgical instrument engineered to absorb fluids, manipulate delicate ocular tissues, and maintain structural integrity under saline irrigation at dimensions typically below 3mm diameter. The device serves ophthalmic surgeons requiring controlled fluid management during anterior segment procedures without leaving particulate residue. Disposable variants command the dominant revenue share due to infection control protocols and elimination of reprocessing logistics, while sterile pre-packaged configurations capture premium pricing in ambulatory settings. Diagnostic procedure applications represent the fastest-expanding segment as point-of-care eye examination protocols proliferate beyond traditional operating theaters.
FDA 510(k) clearance requirements govern US commercialization pathways for PVA Eye Spear devices, enforcing biocompatibility standards through ISO 10993 testing matrices. The EU Medical Device Regulation mandates notified body conformity assessments for European market access, elevating documentation burdens for polymer sourcing traceability. China's NMPA oversees domestic registration through clinical evaluation requirements that increasingly reference international standards. Stakeholders must monitor evolving sterilization validation protocols as gamma irradiation alternatives gain regulatory scrutiny across multiple jurisdictions.
Market Dynamics
Disposable sterile configurations now dominate procurement specifications across ambulatory surgical centers, compressing reprocessing economics and reshaping supplier qualification criteria for polymer sourcing and gamma sterilization validation.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for ophthalmic devices with predicate device references reduce time-to-market for incremental polymer foam innovations. US manufacturers leverage this mechanism for rapid line extensions.
- Cataract Procedure Volume Concentration:Ambulatory surgical centers in the United States handle rising anterior segment surgery loads, driving consumable throughput requirements and standardized instrument kit configurations.
- Rhineland Polymer Cluster Density:Germany's specialized medical device manufacturing corridor integrates precision molding with sterile packaging infrastructure, creating captive supply advantages for European distribution.
Market Restraints
- Medical-Grade PVA Resin Supply Concentration:Polymer feedstock production clusters in East Asia create geographic single-source exposure for Western device manufacturers.
- EU MDR Documentation Burden:Notified body conformity assessments for polymer traceability and biocompatibility testing matrices extend certification timelines and elevate compliance costs.
- Gamma Irradiation Capacity Constraints:Sterilization validation alternatives face regulatory scrutiny across multiple jurisdictions, limiting flexibility in contract sterilizer selection.
Strategic Opportunities
- Point-of-Care Diagnostic Penetration:Eye examination protocols outside traditional operating theaters create demand for sterile pre-packaged configurations in optometry clinics and primary care settings.
- China NMPA Harmonization:Domestic registration pathways increasingly reference ISO 10993 standards, reducing duplicative testing for international manufacturers seeking market access.
- Polymer Molding Automation Convergence:Integration of precision foam forming with robotic packaging systems enables scale economies in high-volume sterile disposable production.
Industry Challenges
- ISO 10993 Biocompatibility Testing Bottlenecks:Cytotoxicity and sensitization study backlogs at certified laboratories extend product development cycles for new polymer formulations.
- Sterile Barrier Validation Complexity:Accelerated aging protocols and seal integrity testing requirements demand specialized equipment investments that strain mid-tier manufacturer capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVA Eye Spear Market |
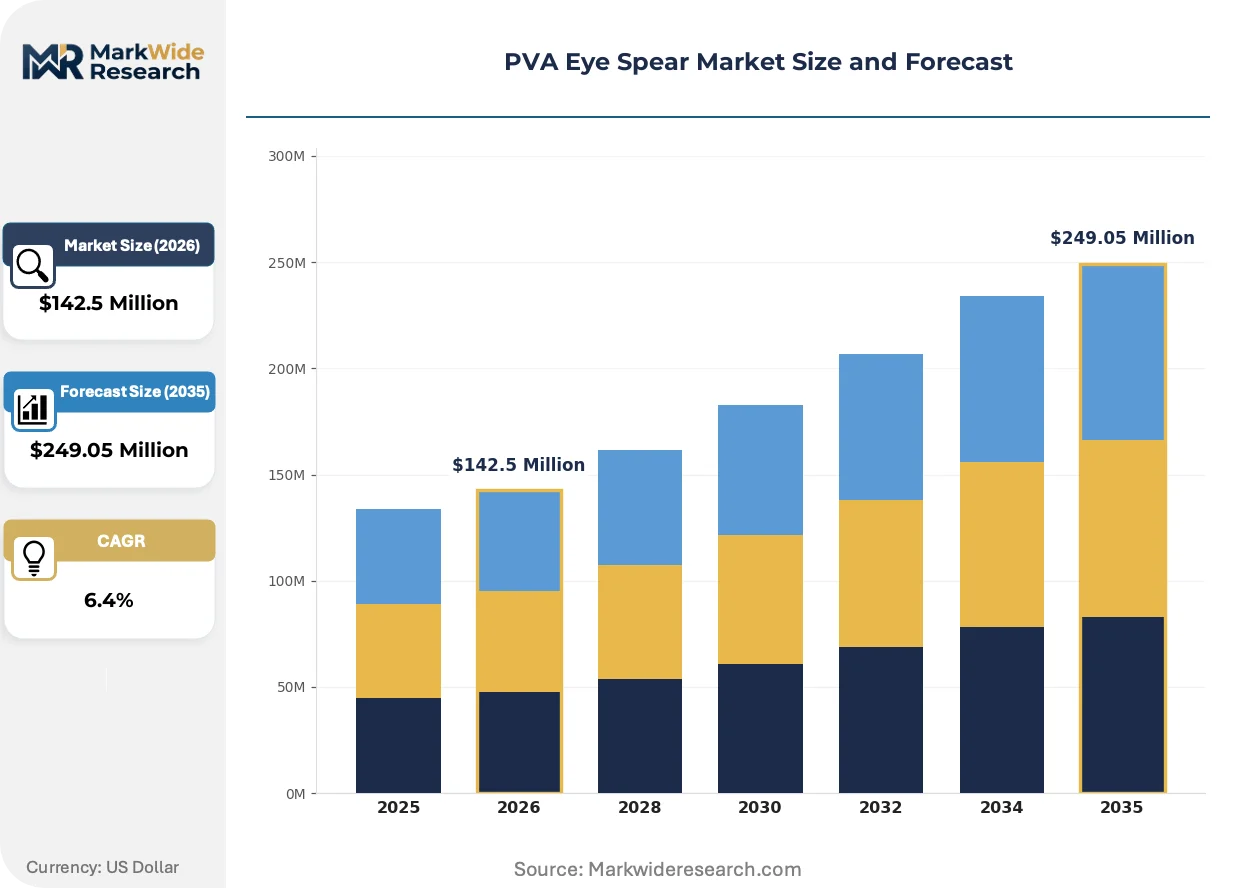
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Sterile, Reusable, Surgical Application: Ophthalmic Surgery, Diagnostic Procedures, Therapeutic Use, Emergency Care Material: PVA, Nylon, Polyester, Other End User: Hospitals, Clinics, Eye Care Centers, Research Institutions |
| Companies Covered | Sunmed Healthcare Pvt Ltd, EyeTech Optics, Hoya Corporation, Bausch & Lomb, Alcon Laboratories, Beaver-Visitec International, DeRoyal Industries, Huizhou Foryou Medical Devices, Innovia Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVA Eye Spear Market Trends and Innovations
Material science advances and sterilization protocol evolution are compressing product lifecycles while regulatory documentation requirements reshape competitive positioning across manufacturing tiers.
Absorbent polymer foam formulations are migrating from conventional hydroxyl-terminated PVA structures toward cross-linked variants with enhanced saline irrigation stability. Anterior segment surgeons in high-volume cataract settings adopt these materials for improved tissue manipulation precision. The technology shift is compressing margins on legacy foam specifications while rewarding integrated polymer research capabilities.
REACH polymer registration requirements in Europe are tightening traceability mandates for surgical consumable manufacturers. Industrial consequence includes mandatory disclosure of additive packages and processing aids in medical-grade foam production. Small-batch specialty manufacturers face disproportionate compliance burden compared to integrated chemical-device conglomerates with dedicated regulatory affairs infrastructure.
Consignment inventory arrangements are displacing traditional purchase-order procurement in ambulatory surgical center networks. Device suppliers absorb working capital requirements while gaining exclusive kit placement privileges. This restructuring concentrates most visibly in United States multi-site ophthalmology practice management organizations seeking to minimize sterile stockout risk.
PVA Eye Spear Market Segmentation
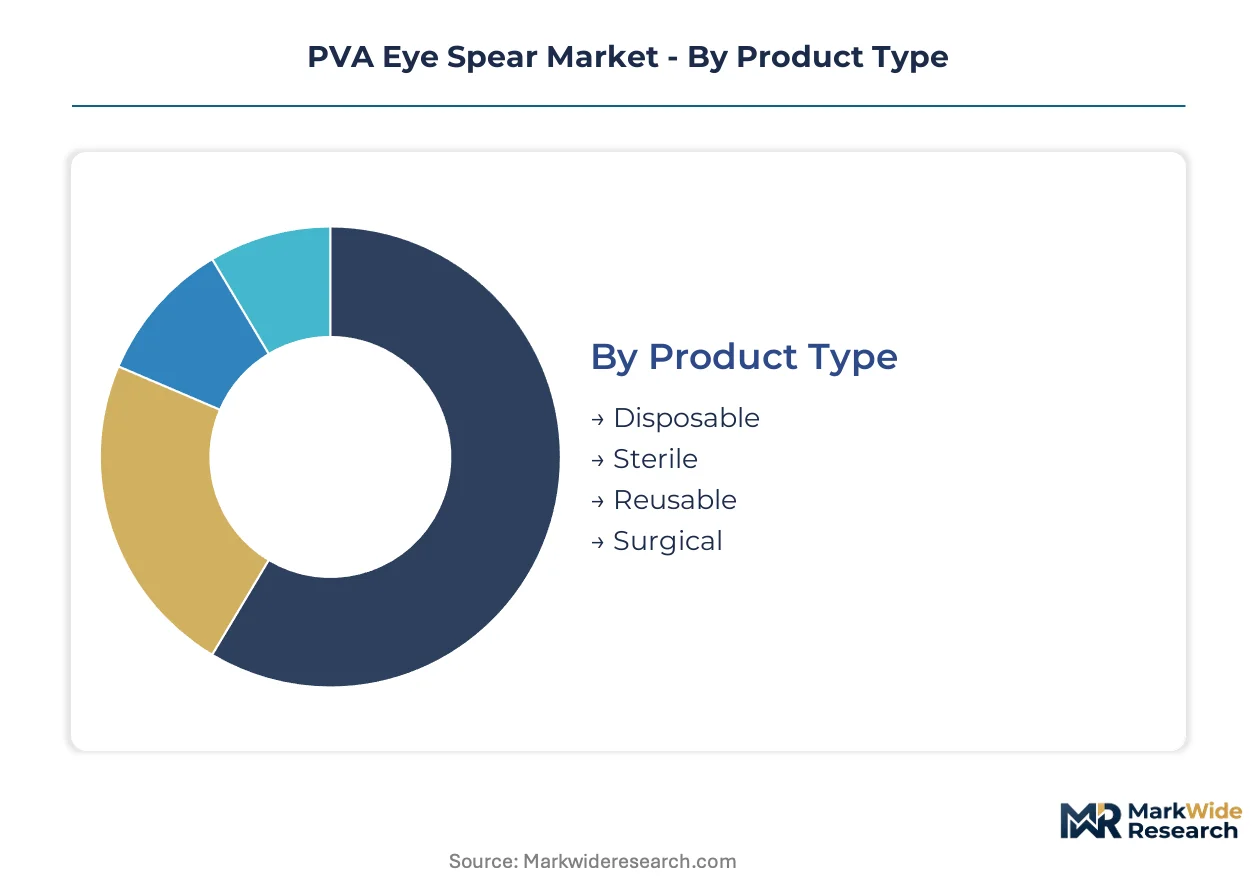
Segmentation in the PVA Eye Spear Market reveals how procurement specifications diverge across sterile protocol requirements, procedure settings, and institutional purchasing power. Manufacturers configure polymer foam specifications and packaging formats to match distinct clinical workflows and regulatory compliance tiers.
Product Type:
Cost tier differentiation separates single-use disposables from capital-intensive reusable systems, with sterile pre-packaged variants commanding premium positioning in ambulatory settings.
- Disposable:Polyvinyl alcohol foam tips are engineered for single-procedure absorption and tissue manipulation, then discarded under infection control protocols. Ambulatory surgical centers in the United States specify these configurations for cataract surgery kits to eliminate reprocessing logistics and sterilization validation overhead.
- Sterile:Pre-packaged gamma-irradiated variants undergo sealed barrier validation and accelerated aging protocols for extended shelf stability. Eye care centers in Germany's Rhineland cluster prefer these for point-of-care diagnostic applications where sterile field maintenance is non-negotiable.
- Reusable:Autoclavable polymer foam constructions withstand multiple steam sterilization cycles for cost-sensitive institutional buyers.
- Surgical:Specialized dimensions below 3mm diameter target anterior segment procedures requiring precision fluid management.
Disposable configurations hold installed capacity. Sterile pre-packaged variants are rotating up the share rankings as point-of-care protocols proliferate.
Application:
Procedure setting determines foam specification requirements, with operating theater standards diverging from examination room protocols on sterility assurance and dimensional precision.
- Ophthalmic Surgery:Anterior segment procedures demand hydroxyl-terminated PVA structures with cross-linked variants gaining traction for enhanced saline irrigation stability. High-volume cataract settings in the United States drive throughput requirements for standardized instrument kits.
- Diagnostic Procedures:Point-of-care eye examination protocols outside traditional operating theaters create demand for sterile pre-packaged configurations in optometry clinics and primary care settings. This segment is expanding most quickly as screening programs decentralize.
- Therapeutic Use:Medication delivery and ocular surface treatment applications require biocompatible foam compositions meeting ISO 10993 cytotoxicity standards.
- Emergency Care:Rapid deployment configurations prioritize immediate sterility assurance over extended shelf-life specifications.
Ophthalmic Surgery anchors current volume. Diagnostic Procedures is climbing the fastest as regulatory harmonization enables broader clinical deployment.
Material:
Polymer chemistry selection balances absorption capacity, structural integrity under irrigation, and regulatory documentation burdens for biocompatibility testing.
- PVA:Cross-linked polyvinyl alcohol variants dominate premium positioning through superior saline stability and particulate-free residue profiles. Manufacturers in China's Zhejiang province are expanding molding capacity to serve this specification tier.
- Nylon:Synthetic polymer alternatives offer mechanical durability for reusable instrument configurations in cost-constrained procurement environments.
- Polyester:Hydrophobic fiber constructions target specific fluid management requirements in therapeutic applications.
- Other:Experimental polymer formulations including cellulose derivatives and modified starches occupy niche research applications.
PVA commands formulation leadership. Nylon is gaining share fastest in emerging market procurement specifications.
End User:
Customer type determines purchasing modality, with consignment inventory arrangements displacing traditional purchase-order procurement in multi-site networks.
- Hospitals:Integrated health systems negotiate enterprise contracts for sterile disposable bundles, absorbing working capital requirements through consignment structures. FDA 510(k) clearance documentation supports group purchasing organization qualification.
- Clinics:Independent ophthalmology practices prioritize standardized kit configurations to minimize sterile stockout risk. Germany's Rhineland medical device cluster supplies these buyers through specialized distribution channels.
- Eye Care Centers:Dedicated ambulatory facilities concentrate anterior segment surgery volumes and drive consumable throughput requirements.
- Research Institutions:Investigational device exemptions and preclinical testing protocols demand small-batch specialty manufacturing with enhanced polymer traceability documentation.
Hospitals maintain procurement scale dominance. Eye Care Centers are rotating up the share rankings as procedure volume migrates from inpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes PVA Eye Spears predominantly through ambulatory surgical centers for high-volume cataract workflows, whereas Germany deploys them more heavily in point-of-care diagnostic settings outside traditional operating theaters.
United States
Ambulatory surgical centers in Florida, Texas, and California drive disposable sterile configuration demand through concentrated anterior segment surgery volumes. FDA 510(k) clearance pathways expedite market entry for polymer foam innovations with predicate device references. The Southeast surgical corridor, particularly the Tampa-Orlando metroplex, anchors kit standardization programs for multi-site ophthalmology networks.
Germany
Point-of-care eye examination protocols in optometry clinics and primary care settings create demand for sterile pre-packaged configurations beyond hospital procurement. EU Medical Device Regulation mandates notified body conformity assessments for polymer traceability and biocompatibility documentation. The Rhineland medical device cluster integrates precision molding with sterile packaging infrastructure, creating captive supply advantages for European distribution.
China
Domestic cataract screening program expansion and tiered hospital system upgrades drive consumable throughput requirements across provincial eye care networks. NMPA registration pathways increasingly reference ISO 10993 standards, reducing duplicative testing for international manufacturers. Zhejiang province is reshaping regional supply dynamics through expanded polymer molding capacity for surgical consumables.
Japan
Aging demographic profiles sustain elevated cataract procedure volumes through specialized eye care centers and university hospital networks. PMDA oversight enforces biocompatibility standards through clinical evaluation requirements aligned with international harmonization initiatives. The Kansai region, centered on Osaka, concentrates precision polymer processing capabilities for ophthalmic device manufacturing.
India
Expanding government-funded cataract elimination campaigns and private hospital chain networks drive demand for cost-efficient sterile disposables. CDSCO registration requirements govern domestic commercialization through quality management system audits and post-market surveillance protocols. Maharashtra and Gujarat host emerging medical device manufacturing corridors with growing polymer conversion capabilities for surgical consumables.
PVA Eye Spear Market Competitive Landscape
Capability concentration sits with integrated ophthalmology conglomerates possessing dedicated polymer research infrastructure; scale advantage sits with specialized surgical instrument manufacturers leveraging high-volume sterile disposable production. The market structure reflects a tiered segmentation where premium positioning demands combined device-chemical expertise, while mid-tier competition centers on gamma sterilization validation efficiency and consignment inventory arrangements. Three archetypes dominate: integrated eye care portfolios, specialized surgical instrument channels, and cost-efficient sterile disposable specialists. M&A activity targets polymer molding automation capabilities, while strategic partnerships concentrate on ambulatory surgical center network placement.
Among North American distributors, Beaver-Visitec International and DeRoyal Industries exemplify specialized surgical instrument channel archetypes with established ambulatory center relationships. Alcon Laboratories occupies a position representing integrated ophthalmology portfolio concentration, leveraging combined device and pharmaceutical expertise. Huizhou Foryou Medical Devices sits within the cost-efficient sterile disposable specialist tier, competing on high-volume production economics for standardized cataract procedure kits. Sunmed Healthcare and EyeTech Optics represent regional manufacturing and distribution configurations serving procurement specifications outside tier-one consolidated networks.
| Leading Market Players |
|---|
| Sunmed Healthcare Pvt Ltd |
| EyeTech Optics |
| Hoya Corporation |
| Bausch & Lomb |
| Alcon Laboratories |
| Beaver-Visitec International |
| DeRoyal Industries |
| Huizhou Foryou Medical Devices |
| Innovia Medical |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's expanded polymer molding capacity for surgical consumables is compressing margin structures for Western device manufacturers while amplifying pricing leverage for integrated chemical-device conglomerates with captive resin supply.
Pricing Analysis
Geographic price spreads between Rhineland-manufactured sterile pre-packaged configurations and Zhejiang-sourced disposable variants have widened as REACH polymer registration requirements tighten traceability mandates. Three-tier pricing structure across premium, standard, and economy levels separates gamma-irradiated sterile barriers with extended shelf validation from basic disposable foam tips. Pricing pressure stems from consignment inventory arrangements displacing traditional purchase-order procurement in United States ambulatory surgical center networks. Eye care centers in multi-site ophthalmology practice management organizations exhibit highest price sensitivity due to working capital absorption requirements, while Germany's specialized surgical instrument channels maintain lowest sensitivity through premium positioning.
Supply Chain Analysis
Contract sterilization capacity concentrates with Steris, Stryker's reprocessing divisions, and regional gamma irradiation facilities serving ophthalmic device manufacturers. Medical-grade PVA resin production clusters in East Asia, with polymer feedstock conversion capabilities concentrated in China, Japan, and South Korea. Raw material dependencies center on vinyl acetate monomer supply, medical-grade foam additive packages, and gamma irradiation cobalt-60 sourcing. Single-source vulnerability runs through East Asian polymer feedstock corridors subject to export licensing variability. Distribution runs through specialized surgical instrument channels and group purchasing organization contracts rather than direct-to-facility logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care diagnostic protocol proliferation outside traditional operating theaters represents a high-growth disruption justified by FDA 510(k) streamlining enabling rapid sterile pre-packaged configuration deployment.
For Market Incumbents: Entrench position through backward integration into medical-grade PVA resin supply and polymer molding automation capabilities in the Rhineland cluster. Alcon Laboratories and Beaver-Visitec International must defend against cost-efficient sterile disposable specialists from Zhejiang by securing exclusive kit placement privileges in United States ambulatory surgical center networks through consignment structures. Certification investment in ISO 10993 biocompatibility testing infrastructure creates defensive moats against mid-tier competitors facing laboratory backlog constraints. For New Entrants and Emerging Players: Diagnostic procedure applications in optometry clinics and primary care settings represent the most penetrable entry point given regulatory harmonization enabling broader clinical deployment. India's expanding government-funded cataract elimination campaigns and Maharashtra-Gujarat manufacturing corridor development offer secondary white-space targeting for cost-efficient sterile disposable production. Go-to-market execution should leverage NMPA registration pathway harmonization with ISO 10993 standards to reduce duplicative testing burdens. For Investors and Strategic Acquirers: Long-term, this sits as a specialty polymer-device convergence play because material science advances in cross-linked PVA formulations are compressing product lifecycles while rewarding integrated research capabilities. Acquisition targets should prioritize mid-tier manufacturers with gamma sterilization validation efficiency and established ambulatory surgical center relationships over pure distribution plays. The signal to watch is NMPA domestic registration timeline compression as international standard reference accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Molding Automation Investment | Integration with robotic packaging systems enables scale economies in high-volume sterile disposable production for cataract kits. |
| Gamma Sterilization Validation Expansion | Alternative sterilization protocol development addresses regulatory scrutiny across FDA, EU MDR, and NMPA jurisdictions simultaneously. |
| Consignment Inventory Partnership | Working capital absorption secures exclusive placement in United States multi-site ophthalmology practice management organizations. |
| ISO 10993 Biocompatibility Laboratory Capacity | In-house cytotoxicity and sensitization testing infrastructure circumvents certified laboratory backlogs extending product development cycles. |
| NMPA Registration Pathway Harmonization | Domestic China registration leveraging international standards reduces duplicative testing for cross-linked PVA foam innovations. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body conformity assessments, and NMPA domestic registration filings preceded structured interviews with ophthalmic surgeons, ambulatory surgical center procurement managers, biomedical engineers, and polymer research directors. Secondary validation drew from hospital procurement databases, group purchasing organization contract disclosures, and ISO 10993 testing laboratory capacity reports. Bottom-up demand modeling across sterile disposable configurations triangulated with top-down cataract procedure volume projections.
Assumptions held fixed include FDA 510(k) streamlining continuity, gamma irradiation capacity availability, and REACH polymer registration requirement stability, while variables included NMPA harmonization pace, point-of-care diagnostic protocol adoption rates, and polymer molding automation convergence timing. Segmentation dimensions modeled encompass product type tiers, application settings, material chemistry specifications, and end-user purchasing modalities. CAGRs were derived from installed base expansion rates and replacement cycle compression across the projection horizon, with industry-specific inputs including anterior segment surgery volume concentration and sterile barrier validation complexity.
Stress conditions across gamma irradiation regulatory scrutiny intensity, medical-grade PVA resin supply disruption scenarios, and EU MDR documentation burden escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with acknowledgment that ISO 10993 testing bottleneck resolution or abrupt sterilization protocol shifts could revise trajectory. Quarterly review of NMPA registration timeline trends, ambulatory surgical center network consolidation patterns, and polymer feedstock export licensing variability is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Japan Dry Eye Syndrome Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Blue Light Blocking Contact Lenses Market