
 Global Therapeutic Lenses Market | 2026-2036
Global Therapeutic Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Therapeutic Lenses Market Foresight
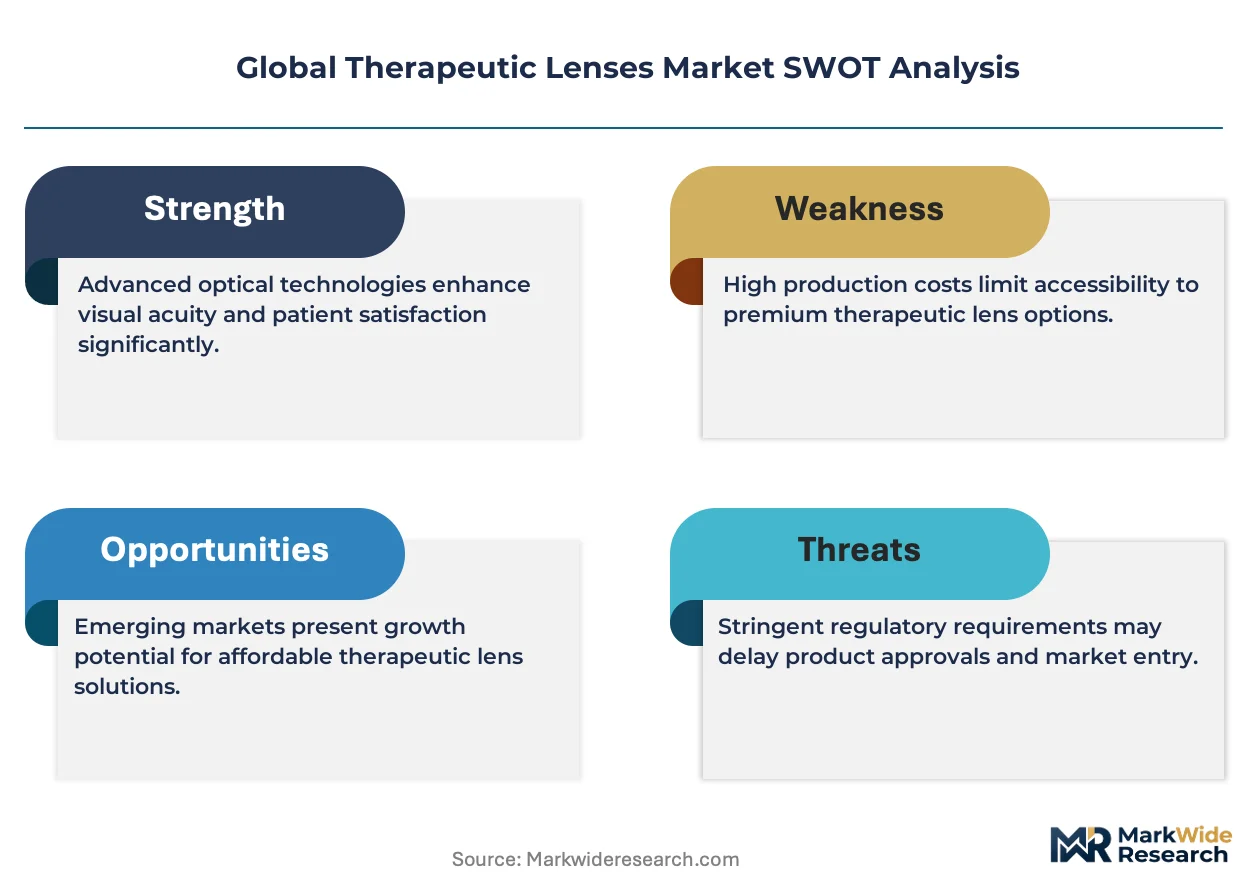
The capital-intensity gap between vertically integrated manufacturers and assembly-only competitors is collapsing as proprietary silicone hydrogel polymerization requires dedicated clean-room investments exceeding $50 million. Alcon Inc. leverages captive silicone monomer supply to sustain margin structures unavailable to smaller rivals. Bausch + Lomb Incorporated anchors its position through direct distribution into academic medical centers. Menicon Co. Ltd. specializes in custom lathe-cut rigid gas permeable designs for irregular corneas.
Therapeutic lenses are medical-grade optical devices manufactured from oxygen-permeable polymers such as silicone hydrogel or fluorosilicone acrylate, designed to protect, hydrate, or pharmacologically treat diseased corneas while maintaining visual function. Scleral lenses vault over the entire corneal surface and fill the gap with preservative-free saline, making them indispensable for severe keratoconus and post-graft ectasia. Soft therapeutic lenses dominate volume through bandage applications after photorefractive keratectomy, though drug-eluting lenses represent the fastest-growing delivery mode as ophthalmology clinics seek alternatives to frequent topical drops. Hybrid lenses occupy a narrow but defensible niche where rigid optics must interface with soft lens comfort for dry eye syndrome patients.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements govern material biocompatibility and clinical validation for therapeutic lens platforms. The EPA monitors perfluorinated compound discharge from fluoropolymer lens manufacturing facilities, adding compliance layers to US-based production. Japan's PMDA enforces JIS T 8147 standards for oxygen transmissibility that exceed baseline ISO 18369 thresholds. Stakeholders must monitor how drug-eluting lens pipelines align with evolving combination-product regulations at FDA and EMA before committing manufacturing scale.
Market Dynamics
Silicone hydrogel polymerization is consolidating production capacity among manufacturers capable of $50 million-plus clean-room investments, compressing margins for assembly-only competitors and reshaping competitive positioning across ophthalmology supply chains.
Growth Catalysts
- EU MDR Class IIa certification:Tightening biocompatibility standards for silicone hydrogel formulations is accelerating R&D investment in next-generation oxygen-permeable polymers among European manufacturers.
- Post-surgical healing protocols:Bandage lens applications after photorefractive keratectomy are expanding volume through specialty eye hospitals in the United States, Germany, and Japan.
- Drug-eluting platforms:Sustained-release therapeutic lenses are displacing frequent topical drop regimens in ophthalmology clinics seeking patient compliance improvements.
Market Restraints
- Captive silicone monomer supply:Vertically integrated manufacturers control upstream polymer inputs, creating procurement barriers for smaller lens assemblers lacking backward integration.
- EPA perfluorinated compound monitoring:Fluoropolymer manufacturing discharge compliance adds cost layers to US-based production of fluorosilicone acrylate lenses.
- ISO 18369 baseline thresholds:Japan's PMDA enforces JIS T 8147 oxygen transmissibility standards that exceed international benchmarks, fragmenting certification requirements.
Strategic Opportunities
- Combination-product alignment:Drug-eluting lens pipelines must navigate evolving FDA and EMA regulatory frameworks before manufacturing scale commitments, creating first-mover advantages for prepared filers.
- Scleral lens vaulting technology:Preservative-free saline-filled designs for severe keratoconus and post-graft ectasia remain underpenetrated outside academic medical centers.
- Direct-to-academic distribution:Bypassing traditional optical retail through specialty hospital channels captures higher-margin fitting protocols for custom lathe-cut rigid gas permeable designs.
Industry Challenges
- Clean-room capital intensity:Dedicated polymerization facilities exceeding $50 million investment requirements constrain mid-scale manufacturer expansion.
- Combination-product certification timelines:FDA and EMA alignment on drug-eluting lens classification extends regulatory validation cycles before commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Therapeutic Lenses Market |
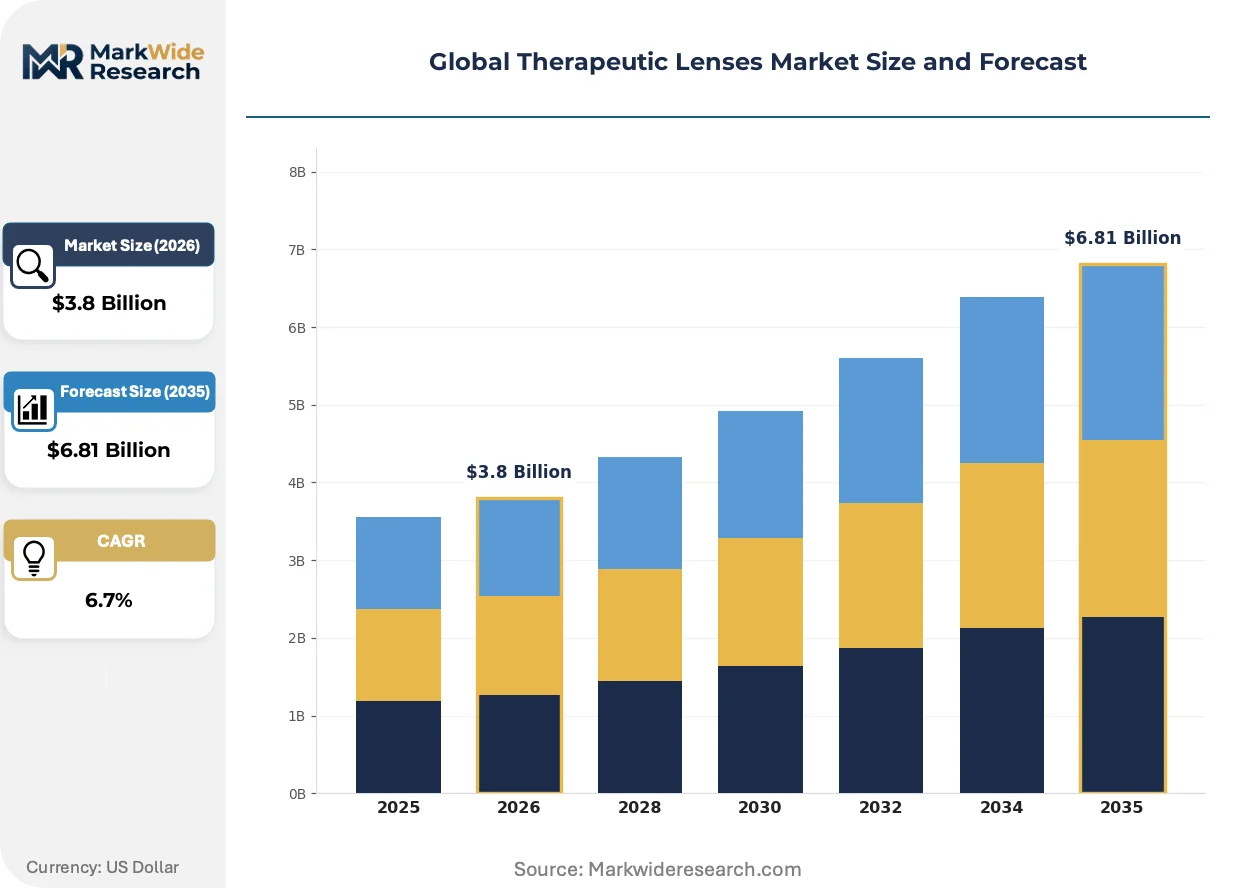
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Gas Permeable, Hybrid Lenses, Scleral Lenses, Soft Therapeutic Lenses Therapy Area: Keratoconus, Post-Surgical Healing, Dry Eye Syndrome, Corneal Ulcers End User: Ophthalmology Clinics, Vision Care Centers, Specialty Eye Hospitals, Optometrists Delivery Mode: Contact Lens, Bandage Lens, Drug-Eluting Lens, Custom-Made Lenses |
| Companies Covered | Alcon Inc., Bausch + Lomb Incorporated, Johnson & Johnson Vision Care Inc., CooperVision Inc., Hoya Corporation, Carl Zeiss Meditec AG, Contamac Ltd., Menicon Co. Ltd., X-Cel Specialty Contacts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Therapeutic Lenses Market Shifts & Advancements
Drug delivery mechanisms are decomposing traditional topical administration paradigms, while regulatory convergence and procurement centralization reshape how therapeutic lenses reach end-users.
Silicone hydrogel formulations with embedded pharmaceutical reservoirs are decomposing the frequent drop regimen model. Academic medical centers in the United States and Germany are piloting these platforms for glaucoma and anti-inflammatory protocols. The structural consequence is compression of pharmacy-dependent revenue streams in ophthalmology practices.
EU MDR material biocompatibility requirements are tightening validation protocols for silicone hydrogel imports. European notified bodies now demand extended cytotoxicity testing beyond prior CE marking thresholds. Asian manufacturers serving EU markets are restructuring quality management systems to maintain access.
Specialty eye hospitals are consolidating fitting authority previously dispersed across independent optometry practices. Germany's university hospital networks and Japan's JIS-certified clinics now control protocol standardization for complex corneal conditions. This concentration is visible most acutely in keratoconus and post-surgical ectasia patient flows.
Global Therapeutic Lenses Market Segmentation
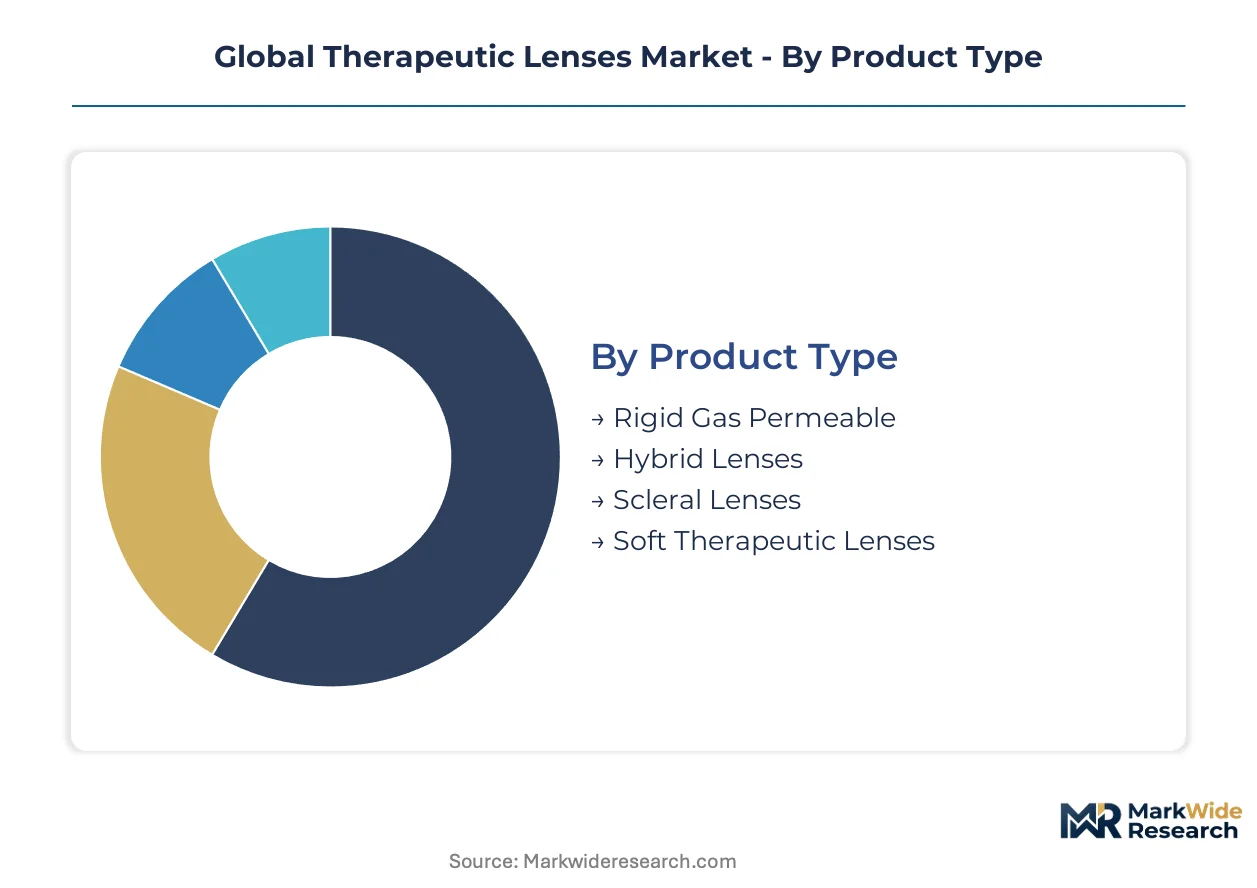
Therapeutic lens segmentation reveals how material science, clinical application, and distribution channel intersect to determine margin structures. Each category carries distinct regulatory pathways and capital requirements that reshape competitive entry barriers.
Product Type:
FDA 510(k) clearance timelines and EU MDR Class IIa biocompatibility testing differentiate polymer platforms by regulatory burden and clean-room investment scale.
- Soft Therapeutic Lenses:Manufactured from silicone hydrogel with embedded hydration reservoirs, these lenses dominate post-photorefractive keratectomy bandage applications. Demand concentrates in United States specialty eye hospitals where Medicare reimbursement protocols favor disposable soft platforms over reusable alternatives.
- Scleral Lenses:Vaulting designs filled with preservative-free saline create a fluid reservoir over the entire corneal surface. Germany's university hospital networks drive adoption for severe keratoconus and post-graft ectasia, where rigid gas permeable alternatives fail to achieve adequate fit stability.
- Rigid Gas Permeable:Lathe-cut fluorosilicone acrylate designs for irregular corneas require custom fitting protocols.
- Hybrid Lenses:Rigid optical centers bonded to soft silicone hydrogel skirts address dry eye syndrome patients needing visual acuity without comfort tradeoffs.
Established volume favors soft therapeutic lenses; emerging adoption favors scleral vaulting technology.
Therapy Area:
Reimbursement intensity and procedure volume separate conditions treated in academic medical centers from those managed in outpatient optometry settings.
- Post-Surgical Healing:Bandage lens protocols following photorefractive keratectomy and corneal transplantation generate recurring demand through standardized fitting algorithms. Japan's JIS T 8147 oxygen transmissibility requirements exceed ISO 18369 baselines, concentrating premium soft lens procurement in PMDA-certified ophthalmology clinics.
- Keratoconus:Progressive corneal thinning demands custom topography-guided designs with progressive fitting complexity. United States academic medical centers capture high-margin scleral and rigid gas permeable fittings through direct manufacturer relationships, bypassing retail optical channels.
- Dry Eye Syndrome:Sustained-release and moisture-retention designs target chronic lubrication deficits.
- Corneal Ulcers:Therapeutic lenses serve as protective barriers during antimicrobial therapy regimens.
Procedure standardization favors post-surgical healing; fitting complexity premiums favor keratoconus management.
End User:
Capital equipment ownership and specialist credentialing determine which channels control complex corneal condition workflows.
- Specialty Eye Hospitals:Germany's university hospital networks and Japan's JIS-certified clinics consolidate authority for keratoconus and post-surgical ectasia protocols. These institutions command direct distribution relationships with manufacturers, capturing margin that independent practices forfeit to distributor intermediaries.
- Ophthalmology Clinics:Drug-eluting lens pilot programs for glaucoma and anti-inflammatory therapy are expanding most quickly through United States metropolitan clinic networks seeking alternatives to pharmacy-dependent drop regimens.
- Vision Care Centers:High-volume soft lens fitting for routine post-surgical bandage applications.
- Optometrists:Primary care vision correction with limited access to custom therapeutic fitting protocols.
Margin concentration favors specialty eye hospitals; patient volume scaling favors ophthalmology clinics.
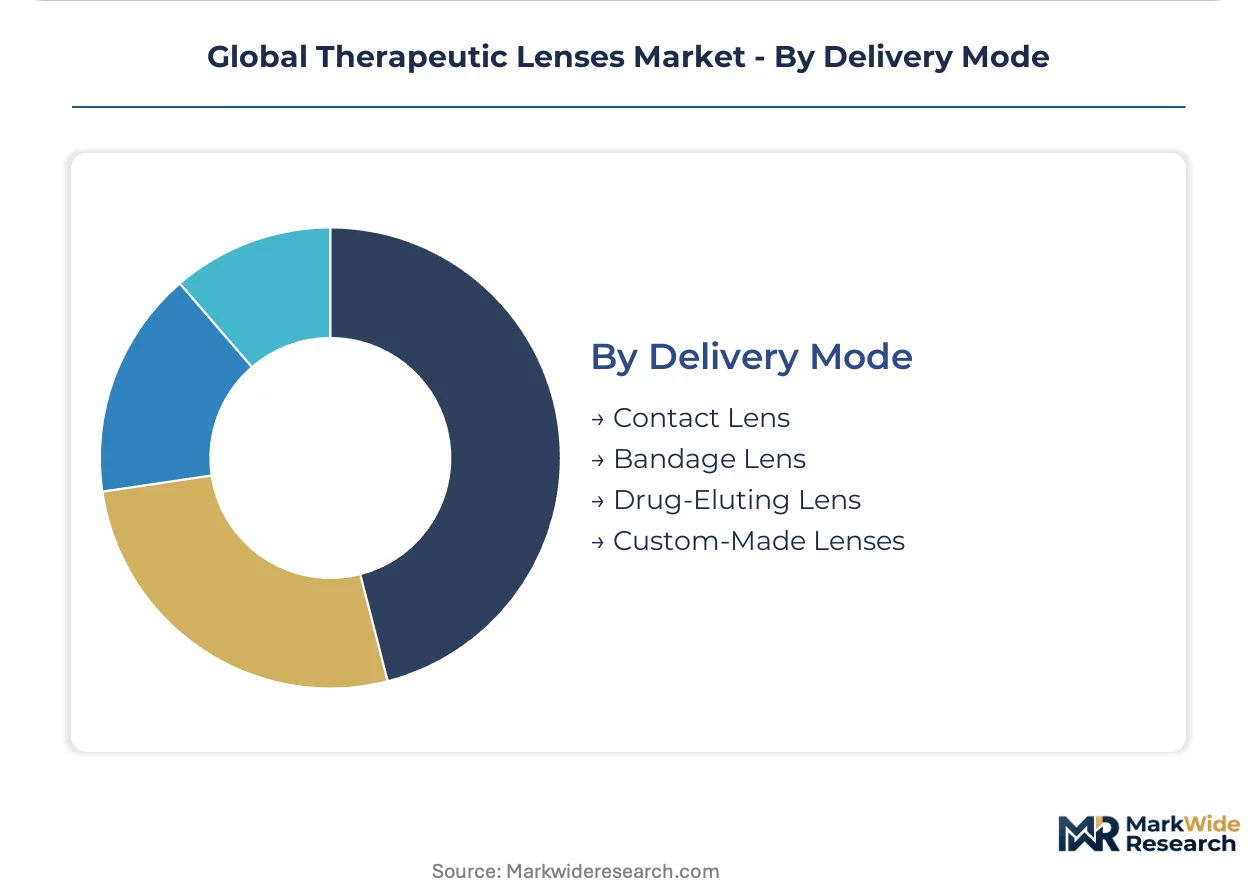
Delivery Mode:
Combination-product classification status at FDA and EMA separates regulated pharmaceutical devices from conventional optical appliances.
- Drug-Eluting Lens:Silicone hydrogel reservoirs embedding timolol, cyclosporine, or corticosteroid formulations are gaining share fastest as ophthalmology clinics pursue compliance improvements over frequent topical administration. Regulatory validation cycles at FDA and EMA extend timelines for filers unprepared for combination-product frameworks.
- Bandage Lens:Post-operative protective applications after photorefractive keratectomy represent the highest-volume deployment mode across United States, Germany, and Japan.
- Contact Lens:Standard therapeutic correction without pharmaceutical payload.
- Custom-Made Lenses:Topography-specific designs for irregular corneas requiring lathe-cut production.
Regulatory complexity favors drug-eluting platforms; volume scale favors bandage lens deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets emphasizing post-surgical bandage protocols and those prioritizing complex corneal disease management through specialty hospital networks.
United States
Medicare reimbursement structures favor disposable soft therapeutic lenses in post-photorefractive keratectomy protocols. FDA 510(k) clearance pathways govern silicone hydrogel biocompatibility standards. Academic medical centers in Boston and Baltimore direct high-margin fitting workflows for keratoconus and post-graft ectasia patients.
Germany
University hospital networks consolidate authority for scleral lens vaulting technology in severe keratoconus management. EU MDR Class IIa certification requirements tighten extended cytotoxicity testing for silicone hydrogel imports. The Rhine-Ruhr and Bavarian medical clusters host specialized fitting protocols that bypass traditional optical retail channels.
Japan
PMDA-enforced JIS T 8147 oxygen transmissibility standards exceed baseline ISO 18369 thresholds, concentrating premium procurement in certified ophthalmology clinics. Post-surgical healing applications expand through metropolitan clinic networks in Tokyo and Osaka. Specialty eye hospitals control protocol standardization for complex corneal conditions.
India
Vision care centers in Maharashtra and Karnataka scale high-volume soft lens fitting for routine post-surgical applications. CDSCO medical device regulations align with ISO 13485 quality management requirements for imported silicone hydrogel platforms. Hyderabad and Bengaluru clusters emerge as fitting protocol training hubs for South Asian markets.
Switzerland
Swissmedic certification requirements for combination-product drug-eluting lenses attract R&D investment from manufacturers seeking European market entry. Precision manufacturing traditions in Basel and Zurich support custom lathe-cut production for irregular cornea applications. Academic hospital networks pilot sustained-release pharmaceutical delivery platforms.
Global Therapeutic Lenses Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into silicone monomer supply separating margin-sustainable players from assembly-dependent competitors. Three archetypes define positioning: vertically integrated polymer producers controlling upstream inputs, academic medical center distributors capturing premium fitting margins, and custom lathe-cut specialists serving irregular cornea niches. Competitive moves concentrate on captive raw material sourcing and direct hospital channel bypass of optical retail intermediaries.
Among integrated manufacturers, Alcon Inc. and Bausch + Lomb Incorporated exemplify the tier commanding proprietary supply chain advantages. Menicon Co. Ltd. occupies a position within the custom fabrication specialist segment. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic archetype selection across ophthalmology supply chains.
| Leading Market Players |
|---|
| Alcon Inc. |
| Bausch + Lomb Incorporated |
| Johnson & Johnson Vision Care Inc. |
| CooperVision Inc. |
| Hoya Corporation |
| Carl Zeiss Meditec AG |
| Contamac Ltd. |
| Menicon Co. Ltd. |
| X-Cel Specialty Contacts |
| Others |
Supply & Pricing Matrix
Silicone hydrogel substitution for conventional hydrogel polymers simultaneously concentrates manufacturing geography in the United States, Germany, and Japan while compressing margin structures for assembly-only competitors lacking captive monomer supply.
Pricing Analysis
Fitting service contracts and replacement lens subscriptions generate lifetime value exceeding initial device margins. Three-tier pricing structure across premium, standard, and economy levels separates custom lathe-cut scleral designs from disposable soft bandage lenses. Cost compression in standard soft lens tiers is intensifying because vertically integrated manufacturers leverage backward integration into silicone monomer production. Academic medical centers demonstrate lowest price sensitivity for complex keratoconus fittings; vision care centers in high-volume markets exhibit highest sensitivity to per-unit procurement costs.
Supply Chain Analysis
Clean-room polymerization capacity chokepoints in the United States, Germany, and Japan constrain global supply elasticity for next-generation silicone hydrogel platforms. Production draws from fluorosilicone acrylate resins, precision lathe-cutting equipment, and preservative-free saline packaging components. Single-source vulnerability in silicone monomer supply creates procurement risk for mid-scale assemblers lacking backward integration. Distribution runs through direct manufacturer relationships with specialty eye hospitals and academic medical centers, bypassing traditional optical retail intermediaries for complex therapeutic fittings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Therapeutic lens fragmentation creates entry niches as drug-eluting platforms displace pharmacy-dependent drop regimens across ophthalmology clinic networks.
For Market Incumbents: Fortify margin structures by deepening captive silicone monomer supply and securing direct distribution contracts with Germany's university hospital networks. Accelerate EU MDR Class IIa certification investment to preempt Asian competitors from European market access. Priority lever: polymerization capacity expansion in JIS T 8147-compliant facilities.
For New Entrants and Emerging Players: Differentiate on scleral lens vaulting technology for severe keratoconus segments where academic medical center penetration remains incomplete outside Boston and Baltimore clusters. Target India's metropolitan vision care centers for high-volume soft lens fitting protocol partnerships. Go-to-market angle: CDSCO-aligned quality management systems enabling South Asian market entry.
For Investors and Strategic Acquirers: Capital is best deployed toward custom lathe-cut specialists with established topography-guided fitting workflows and direct hospital channel relationships. Long-term viability hinges on positioning for combination-product regulatory convergence at FDA and EMA. Signal to watch: drug-eluting lens pipeline advancement through Phase III-equivalent validation stages.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Extended cytotoxicity testing requirements reshape competitive access for Asian manufacturers serving European notified bodies. |
| Backward Integration into Silicone Monomer Supply | Captive polymer input control separates margin-sustainable integrated manufacturers from assembly-dependent competitors. |
| Academic Medical Center Partnership | Direct distribution into Boston and Baltimore hospital networks captures premium fitting margins for complex corneal conditions. |
| Drug-Eluting Lens Pipeline Advancement | Sustained-release timolol and cyclosporine formulations displace frequent topical drop regimens in ophthalmology clinics. |
| JIS T 8147 Compliance Investment | Oxygen transmissibility standards exceeding ISO 18369 baselines concentrate premium procurement in PMDA-certified Japanese clinics. |
Research Methodology
Cross-validation between primary interviews with ophthalmology clinic directors, biomedical engineers at specialty eye hospitals, GPO contracts managers, and silicone hydrogel manufacturing executives anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body databases, PMDA submission records, and CMS Medicare reimbursement data. Bottom-up demand modeling triangulates with top-down market sizing across polymer platform, therapy area, and delivery mode dimensions.
Sensitivity analysis tests forecast robustness across alternative regulatory approval timelines and silicone monomer supply scenarios throughout the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, and delivery mode, with additional granularity on oxygen transmissibility tier and combination-product classification status. CAGRs derive from procedure volume trajectories, reimbursement intensity shifts, and adoption curve analysis for drug-eluting platforms.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA regimes; material policy shifts in combination-product classification or perfluorinated compound discharge limits would require re-modeling. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and Japanese JIS T 8147 oxygen threshold evolution progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
North America Vision Care Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Amblyopia Treatment Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
3D Printed Ophthalmic Implants Market