
 Amblyopia Treatment Market | 2026-2036
Amblyopia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Amblyopia Treatment Market Analysis
Pediatric ophthalmology purchasing is realigning as hospital networks consolidate procurement decisions across multi-site eye care centers. Vivid Vision leverages proprietary virtual reality protocols to differentiate its digital therapy platform from conventional patching regimens. HOYA Vision Care anchors the optical correction segment through specialized lens designs for anisometropic amblyopia. Novartis sustains pharmacologic relevance with atropine sulfate formulations that compete against emerging device-based alternatives.
Amblyopia treatment encompasses interventions that correct visual cortex developmental deficits arising from abnormal binocular input during critical neuroplastic windows, typically involving occlusion therapy, optical penalization, or perceptual learning protocols delivered at 80-120 minute weekly intervals. The primary commercial purpose centers on restoring monocular and binocular visual function in patients aged three through twelve years before cortical plasticity diminishes. Vision therapy and digital therapy segments command expanding margin pools as reimbursement codes evolve to cover software-delivered interventions. Eye patches retain volume leadership in cost-sensitive markets though adherence limitations constrain clinical outcomes. Pharmacologic treatment through atropine drops occupies a stable niche where patching compliance proves unachievable.
The FDA's humanitarian device exemption pathway shapes pediatric ophthalmology innovation timelines, while the EMA's pediatric investigation plans influence European development priorities for amblyopia therapeutics. ISO 13485 certification requirements govern quality management for digital therapy manufacturers seeking multi-jurisdictional market access. Stakeholders must monitor evolving CPT code decisions for telehealth-delivered vision therapy and their impact on commercial model viability.
Market Dynamics
Pediatric ophthalmology networks are consolidating procurement decisions across multi-site eye care centers, compressing vendor selection cycles and favoring platform providers with integrated digital-physical therapy suites over single-modality suppliers.
Growth Catalysts
- Telehealth reimbursement expansion:CPT code evolution for software-delivered vision therapy is accelerating commercial model viability across United States pediatric networks.
- Neuroplasticity research:Extended critical period findings are widening addressable patient age brackets beyond traditional twelve-year cutoffs.
- EMA pediatric investigation plans:Structured development pathways are streamlining European regulatory timelines for novel amblyopia therapeutics.
Market Restraints
- Adherence limitations:Patching regimens face structural compliance failures in forty to sixty percent of pediatric cases, constraining real-world efficacy.
- Specialist concentration:Pediatric ophthalmology expertise clusters in major metropolitan medical centers, limiting rural and secondary market access.
- Device certification complexity:ISO 13485 quality management requirements impose multi-year compliance timelines for digital therapy manufacturers.
Strategic Opportunities
- Home-based digital platforms:Virtual reality perceptual learning protocols are penetrating previously underserved markets where clinic density is low.
- FDA humanitarian device exemption:Accelerated review pathways for pediatric populations are compressing time-to-market for novel interventions.
- Binocular therapy convergence:Dichoptic presentation technologies are displacing monocular occlusion as first-line intervention in premium reimbursement markets.
Industry Challenges
- Clinical validation timelines:Pediatric trial recruitment constraints and visual acuity measurement variability extend pivotal study durations.
- Interoperability gaps:Electronic health record integration for therapy adherence tracking remains fragmented across hospital network systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amblyopia Treatment Market |
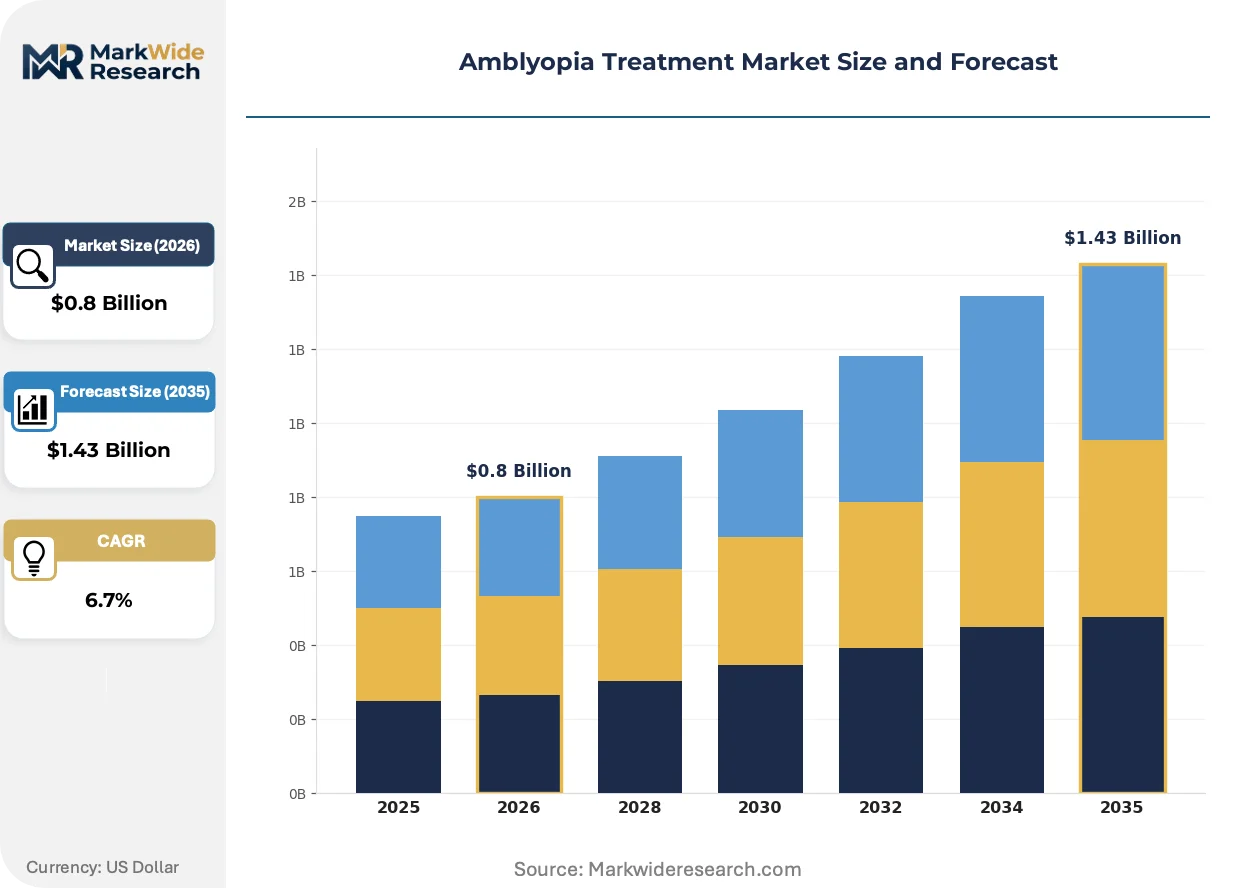
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.43 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Patches, Atropine Drops, Vision Therapy, Surgical Options Age Group: Pediatric, Adolescent, Adult, Senior Therapy Area: Orthoptics, Pharmacologic Treatment, Surgical Treatment, Visual Acuity Enhancement Technology: Digital Therapy, Traditional Therapy, Mobile Applications, Home-Based Solutions |
| Companies Covered | Vivid Vision, HOYA Vision Care, 3M, RevitalVision, Novartis, Johnson & Johnson, CooperVision, NovaSight, Santen Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amblyopia Treatment Market Emerging Trajectories
Digital therapy platforms are redefining treatment delivery modalities, shifting intervention locus from clinical settings to supervised home environments while regulatory frameworks scramble to adapt reimbursement structures.
Virtual reality perceptual learning systems deliver dichoptic visual stimulation that rebalances cortical input between amblyopic and fellow eyes. Pediatric ophthalmology clinics in the United States and Germany are piloting these platforms at accelerating rates. This technology is converging with cloud-based remote monitoring to enable asynchronous clinician oversight and real-time adherence verification.
The FDA's pediatric device innovation pathway compresses premarket review timelines for humanitarian-use devices targeting orphan indications. This regulatory mechanism is redirecting development resources toward amblyopia-specific hardware rather than repurposed consumer electronics. Device manufacturers are responding by embedding clinical-grade eye tracking and standardized acuity protocols into platform designs.
Hospital network procurement officers are bundling digital therapy licenses with traditional optical correction contracts, unbundling hardware from software subscriptions. Pediatric ophthalmology group purchasing organizations are consolidating vendor panels to three to five approved platforms. This pattern is most pronounced in United States integrated delivery networks where value-based care contracts incentivize adherence-monitoring capabilities.
Amblyopia Treatment Market Segmentation
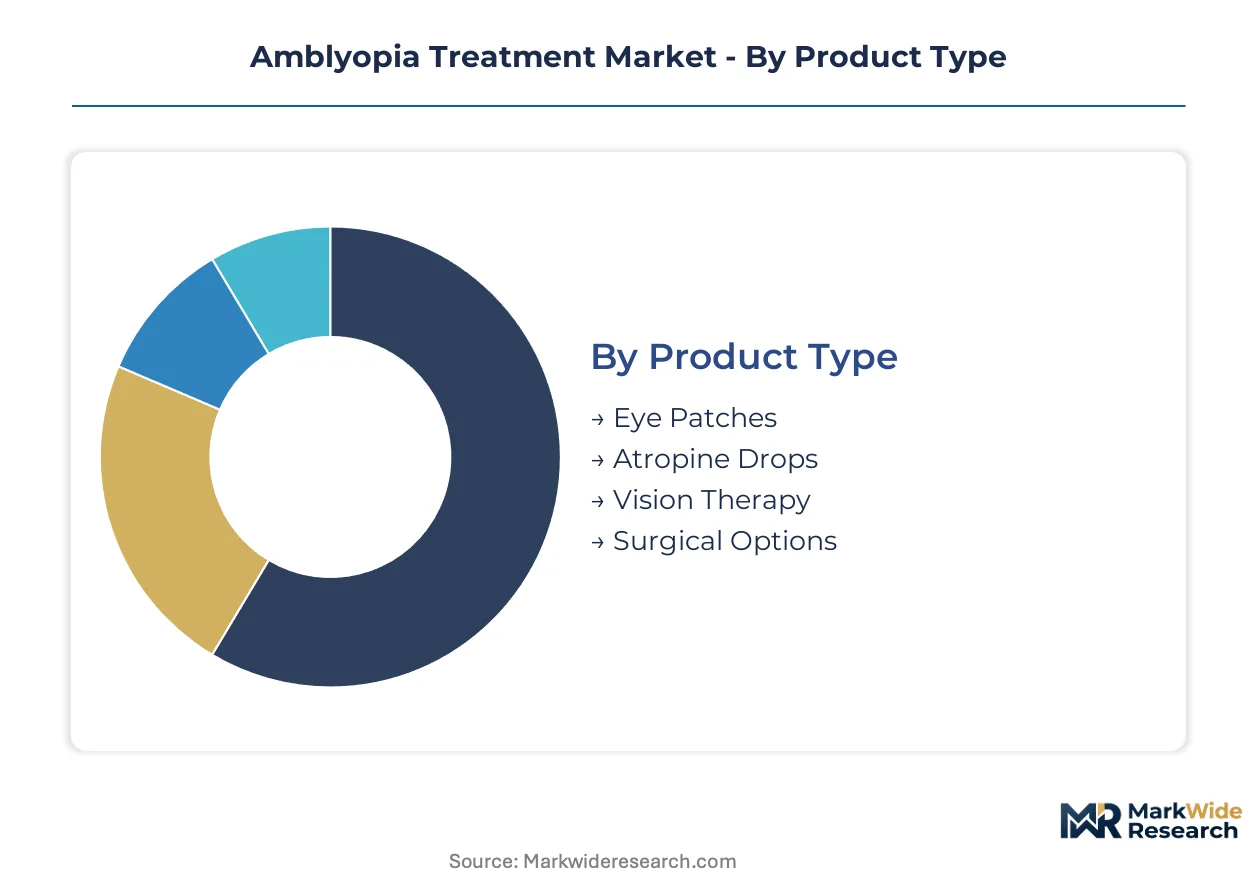
Amblyopia treatment modalities diverge sharply by patient compliance capacity, reimbursement pathway, and clinical setting infrastructure. Pediatric networks prioritize adherence-monitoring capabilities while adult segments demand portable solutions compatible with employment constraints.
Product Type:
Procurement officers differentiate suppliers by total cost of ownership spanning device acquisition, software licensing, and clinician training requirements.
- Eye Patches:Occlusive adhesive or fabric barriers applied to the fellow eye enforce monocular visual input. Volume concentrates in cost-sensitive Medicaid populations across United States rural counties where digital infrastructure remains underdeveloped.
- Atropine Drops:Pharmacologic penalization via cycloplegic agents blurs near vision in the dominant eye. Demand clusters in Germany and France where ophthalmology clinics report superior compliance versus patching in children under age five.
- Vision Therapy:Structured perceptual learning protocols delivered through in-clinic or telehealth supervision. Adoption accelerates in United States integrated delivery networks pursuing value-based ophthalmology contracts.
- Surgical Options:Strabismus correction and cataract extraction address organic amblyopia etiologies. Procedure volumes track pediatric ophthalmology specialist density in metropolitan hospital systems.
Eye patches lead volumes today; vision therapy is gaining share fastest.
Age Group:
Neuroplasticity windows constrain addressable populations while extended critical period research redefines commercial boundaries.
- Pediatric:Patients aged three through twelve years represent the traditional intervention window. Treatment protocols in United States academic medical centers now incorporate dichoptic digital platforms as first-line therapy.
- Adolescent:Thirteen through seventeen years presents diminished but clinically meaningful plasticity. European clinics in Sweden and Netherlands pilot intensive perceptual learning for this historically undertreated cohort.
- Adult:Eighteen through sixty-four years was previously excluded from active intervention. Perceptual learning software from Israeli and United States developers demonstrates measurable acuity gains in this expanding segment.
- Senior:Sixty-five years and above presents amblyopia detection incident to age-related macular degeneration screening. Medicare reimbursement ambiguity constrains commercial development for this demographic.
Pediatric segments dominate procedure counts; adult treatment represents the steepest expansion trajectory.
Therapy Area:
Clinical workflow integration determines vendor selection as hospital networks consolidate ophthalmology service lines.
- Orthoptics:Non-surgical eye movement and binocular vision rehabilitation delivered by specialized technicians. United Kingdom NHS orthoptic departments are standardizing digital workflow platforms across regional trusts.
- Pharmacologic Treatment:Atropine sulfate and similar agents for penalization therapy. Formulation stability requirements favor established pharmaceutical supply chains in Switzerland and Germany.
- Surgical Treatment:Strabismus correction, cataract extraction, and vitreoretinal procedures addressing organic causes. Volume correlates with pediatric ophthalmology fellowship program distribution across United States academic centers.
- Visual Acuity Enhancement:Perceptual learning and contrast sensitivity training protocols. Cloud-based remote monitoring capabilities differentiate platform vendors in Australian and Canadian pilot programs.
Orthoptics commands the largest installed base; visual acuity enhancement platforms are climbing the fastest.
Technology:
Reimbursement code evolution separates commercially viable platforms from experimental interventions.
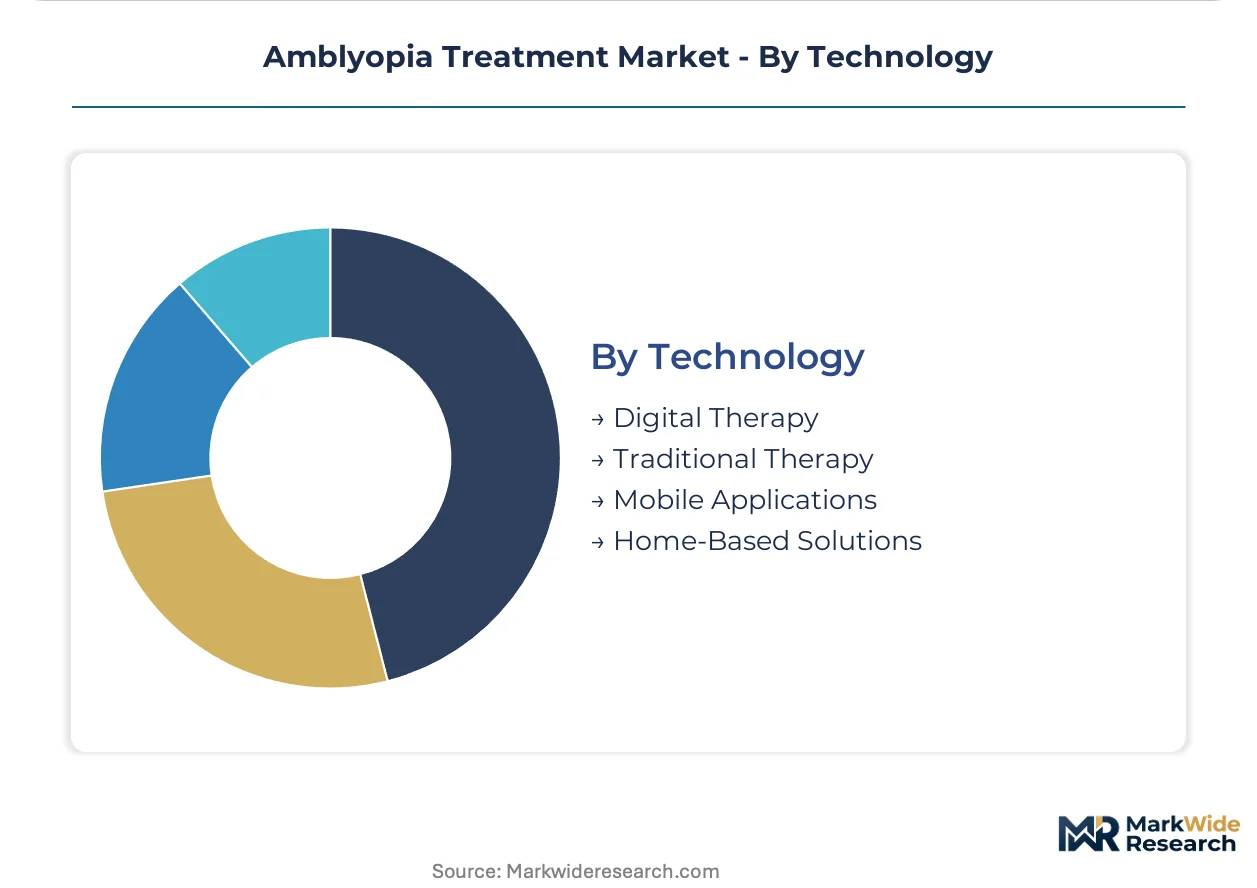
- Digital Therapy:Virtual reality and tablet-based dichoptic presentation systems with embedded eye tracking. FDA humanitarian device exemption approvals accelerate United States market entry for pediatric-specific hardware.
- Traditional Therapy:Patching, occlusion, and in-clinic orthoptic exercises without software components. Procurement persists in German statutory health insurance networks with conservative technology adoption profiles.
- Mobile Applications:Smartphone-delivered perceptual learning with asynchronous clinician oversight. Regulatory classification uncertainty in European markets delays commercial scaling.
- Home-Based Solutions:Supervised domestic treatment delivery reducing clinic visit burden. Parental adherence verification via cloud dashboards drives purchasing decisions in United States managed care organizations.
Traditional therapy retains volume leadership; digital therapy platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance networks maintain conservative technology adoption profiles for traditional patching, while the United States accelerates toward digital therapy platforms with expanding CPT code coverage for software-delivered interventions.
United States
Integrated delivery networks in metropolitan hospital systems are consolidating ophthalmology procurement across multi-site centers, favoring platform providers with adherence-monitoring capabilities. The FDA's pediatric device innovation pathway compresses premarket review timelines for humanitarian-use devices. Academic medical centers in Boston and Philadelphia pilot dichoptic digital platforms as first-line therapy for pediatric patients.
Germany
Orthoptic departments in statutory health insurance networks report superior compliance with atropine drops versus patching in children under age five. The EMA's pediatric investigation plans streamline development pathways for novel amblyopia therapeutics. University hospitals in Heidelberg and Tübingen concentrate specialized pediatric ophthalmology expertise with established atropine formulation supply chains.
United Kingdom
NHS orthoptic departments are standardizing digital workflow platforms across regional trusts to address rural service delivery gaps. MHRA guidance on software as a medical device shapes regulatory classification for tablet-based perceptual learning systems. London and Manchester academic centers lead clinical validation trials for cloud-based remote monitoring capabilities.
Japan
PMDA consultation procedures for pediatric medical devices influence development priorities for amblyopia-specific hardware rather than repurposed consumer electronics. METI funding for digital health innovation supports virtual reality perceptual learning research. Tokyo and Osaka metropolitan areas concentrate pediatric ophthalmology specialist density with emerging telehealth reimbursement frameworks.
Australia
Cloud-based remote monitoring capabilities differentiate platform vendors in pilot programs targeting low clinic density regions. The TGA's software as a medical device framework determines commercial scaling timelines for smartphone-delivered interventions. Sydney and Melbourne pediatric networks are bundling digital therapy licenses with traditional optical correction contracts.
Amblyopia Treatment Market Vendor Landscape
United States producers anchor the digital therapy platform tier; Japanese and European specialists hold positions in optical correction and pharmacologic segments. The vendor structure fragments across hardware manufacturers, pharmaceutical formulators, and software developers with minimal cross-archetype consolidation. Three strategic archetypes dominate: virtual reality platform developers, specialized lens designers, and established ophthalmic pharmaceutical suppliers. Competitive moves center on strategic partnerships between hardware and software developers, plus geographic expansion through hospital network procurement consolidation.
Within the digital therapy archetype, Vivid Vision and NovaSight represent platform developers leveraging proprietary virtual reality protocols. HOYA Vision Care and CooperVision occupy positions in optical correction segments through specialized lens designs. Novartis and Santen Pharmaceuticals anchor pharmacologic relevance with atropine sulfate formulations that compete against emerging device-based alternatives. Johnson & Johnson and 3M exemplify diversified healthcare conglomerates with ophthalmic product lines spanning multiple treatment modalities.
| Leading Market Players |
|---|
| Vivid Vision |
| HOYA Vision Care |
| 3M |
| RevitalVision |
| Novartis |
| Johnson & Johnson |
| CooperVision |
| NovaSight |
| Santen Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Backward integration into clinical-grade eye tracking hardware anchors pricing power for digital therapy developers competing against commoditized patching suppliers. United States manufacturers sourcing FDA-cleared components command premium positioning against German and Japanese competitors relying on outsourced optical subsystems.
Pricing Analysis
Capacity additions in United States digital health manufacturing are reshaping price floors for virtual reality perceptual learning systems. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and remote monitoring capability. Price differentiation hinges on ISO 13485 quality tier and embedded clinician dashboard functionality. Cost compression in economy eye patches intensifies as Asian textile suppliers expand automated adhesive production. Medicaid populations exhibit highest price sensitivity; academic medical centers with value-based contracts show lowest.
Supply Chain Analysis
Freight costs for temperature-sensitive atropine formulations from Swiss and German pharmaceutical plants constrain European distribution economics. Component sourcing draws from Taiwan for display panels, Japan for precision optics, and United States for cloud infrastructure. Raw material dependencies include cycloplegic active pharmaceutical ingredients, medical-grade adhesives, and lithium-ion batteries for portable devices. Single-source vulnerability concentrates in specialized VR lens grinding capacity. Distribution runs through hospital network GPOs and orthoptic department procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement code evolution favors premium digital platforms over commodity patching. Demand is shifting toward adherence-verified home-based solutions with cloud monitoring.
For Market Incumbents: Acquire remote monitoring software capabilities to defend against pure-play digital entrants eroding orthoptic service line contracts. Consolidate procurement relationships across United States integrated delivery networks before CPT code standardization freezes vendor panels. Capacity addition in FDA-registered manufacturing facilities represents the critical lever for humanitarian device exemption positioning. For New Entrants and Emerging Players: Smartphone-delivered dichoptic protocols penetrating Australian and Canadian rural markets offer the most penetrable white-space. Target adolescent and adult segments historically excluded from pediatric-focused incumbent portfolios. Go-to-market through telehealth reimbursement expansion in United States managed care creates asymmetric access versus clinic-dependent competitors. For Investors and Strategic Acquirers: Roll-up economics work for digital therapy platform consolidation because hospital network procurement officers are compressing approved vendor lists to three-to-five platforms. Five-to-ten year viability favors developers with embedded eye tracking hardware rather than software-only licensing models. Watch FDA pediatric device innovation pathway approval velocity as inflection indicator for platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Humanitarian Device Exemption Submission | Accelerated review timelines compress market entry for pediatric-specific VR hardware developers. |
| Hospital System Partnership | Integrated delivery network bundling agreements lock in multi-year digital therapy license revenues. |
| Software Companion Development | Cloud-based adherence dashboards differentiate platforms in United States value-based ophthalmology contracts. |
| CE Marking Pathway | EMA pediatric investigation plans streamline European regulatory timelines for novel amblyopia therapeutics. |
| Reimbursement Strategy | CPT code evolution for telehealth-delivered vision therapy determines commercial model viability across pediatric networks. |
Methodological Framework
Coverage spans United States, Germany, United Kingdom, Japan, and Australia, with primary inputs from each market's pediatric ophthalmology networks. Research combined primary interviews with clinicians, hospital purchasing committee members, GPO contracts managers, and biomedical engineers with secondary validation against FDA filings, EMA pediatric investigation plans, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up and top-down triangulation anchored volume estimates.
Rate-of-change decomposition across the analysis window segmented by treatment modality, patient age bracket, therapy delivery setting, and regulatory approval pathway. CAGRs derived from patient population epidemiology, procedure volume trends, and evolving reimbursement code coverage. Forecast inputs incorporated neuroplasticity research expansion, telehealth regulatory evolution, and hospital network consolidation patterns.
The model holds under stable FDA pediatric device review timelines and expanding CPT code coverage; deviation in reimbursement policy or regulatory backlog would shift commercial viability timelines. Forecasts reflect documented assumptions regarding neuroplasticity window extension and digital therapy adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Astigmatism Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Eye Melanoma Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Synoptophore Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Eye Care Surgical Market