
 Japan Ophthalmic Devices and Drugs Market | 2026-2036
Japan Ophthalmic Devices and Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Ophthalmic Devices and Drugs Market Foresight
Software-defined diagnostic features embedded in ophthalmic imaging platforms is pivoting device economics toward recurring revenue models. Nidek Co., Ltd leverages its domestic manufacturing footprint to control service margins on optical coherence tomography systems. Topcon Corporation anchors its competitive stance through integrated data analytics suites that lock in clinic loyalty. HOYA Corporation specializes in premium intraocular lens coatings that sustain pricing power against commoditized alternatives.
Ophthalmic devices and drugs encompass instruments, implants, and therapeutic agents designed for diagnosis, surgical intervention, and medical management of ocular diseases, typically operating within precision tolerances of micrometers for intraocular components and requiring sterile, biocompatible material formulations. Their primary commercial purpose centers on preserving or restoring visual acuity across progressive conditions such as cataracts, glaucoma, and retinal degeneration. Diagnostic Equipment commands established installed bases across Japan's eye care centers, while Intraocular Lenses capture concentrated margin pools tied to aging-driven cataract volumes. The Refractive Errors therapy area retains growth velocity through laser vision correction upgrades, whereas Retinal Disorders attracts escalating injectable drug development.
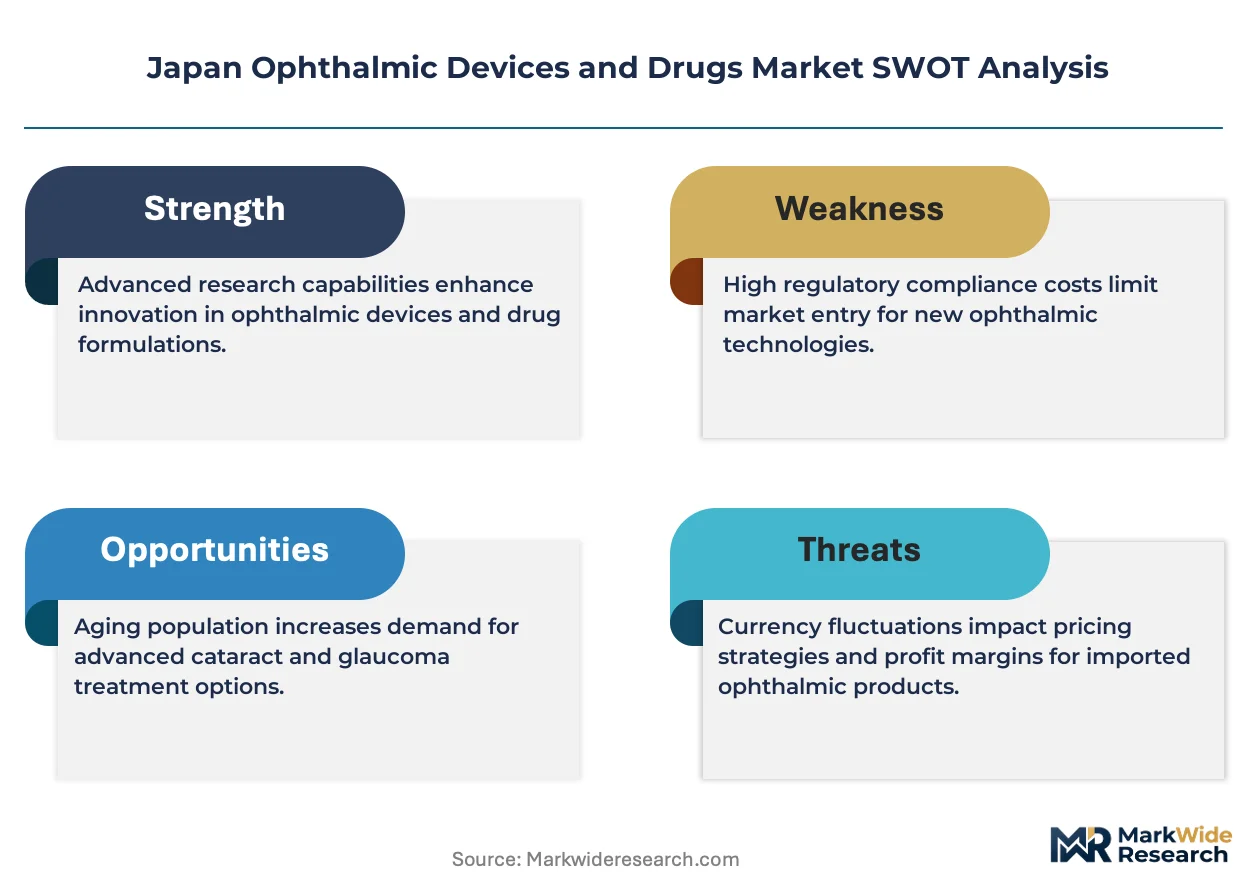
PMDA reviews govern premarket approvals for all ophthalmic devices and drugs in Japan, with JIS standards specifying optical performance and biocompatibility benchmarks that manufacturers must satisfy for market access. METI industrial policy channels funding toward domestic production of advanced diagnostic platforms, reinforcing local supply chain resilience for critical ophthalmic components. Stakeholders must monitor how PMDA's evolving digital health guidance intersects with AI-enabled diagnostic tools, as this regulatory boundary will determine which software-integrated devices secure accelerated pathways versus extended review cycles.
Market Dynamics
Japan's ophthalmic sector faces structural pressure from PMDA's accelerating digital health guidance, which is compressing approval timelines for AI-integrated diagnostic platforms while elevating compliance burdens for traditional hardware manufacturers.
Growth Catalysts
- Demographic transition:Japan's super-aged society generates sustained procedural volumes for cataract extraction and glaucoma filtration surgeries across prefectural hospital networks.
- PMDA Sakigake designation:The regenerative medicine and breakthrough therapy fast-track is condensing premarket review periods for sustained-release intravitreal implants.
- Spectral-domain OCT diffusion:Optical coherence tomography hardware upgrades in Tokyo and Osaka specialist clinics are driving replacement cycles and attached service contracts.
Market Restraints
- Silicone oil supply concentration:Vitreoretinal surgery depends on imported high-purity silicone oil, exposing Japanese manufacturers to freight cost volatility and currency fluctuation.
- Biocompatibility testing backlog:PMDA-mandated JIS T 0301 cytotoxicity protocols create 14-18 month validation queues for novel intraocular lens materials.
- Phakic IOL substitution:Advanced surface ablation techniques and small-incision lenticule extraction are capturing myopia correction volumes from implantable collamer lens procedures.
Strategic Opportunities
- Kyushu regional expansion:Fukuoka prefecture's underdeveloped specialist clinic density relative to Tokyo presents whitespace for diagnostic platform placement and surgeon training partnerships.
- Tele-ophthalmology integration:Remote screening protocols for diabetic retinopathy are opening reimbursement pathways that pair imaging hardware with cloud-based diagnostic workflows.
- METI smart medical device subsidy:Domestic production incentives for AI-enabled fundus cameras are offsetting capital equipment costs for regional health cooperatives.
Industry Challenges
- Vitreoretinal surgeon training pipeline:Fellowship completion rates lag procedural demand growth, constraining adoption of complex surgical platforms in secondary cities.
- Legacy EMR integration:Diagnostic imaging systems require custom HL7-FHIR middleware to connect with hospital information systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Ophthalmic Devices and Drugs Market |
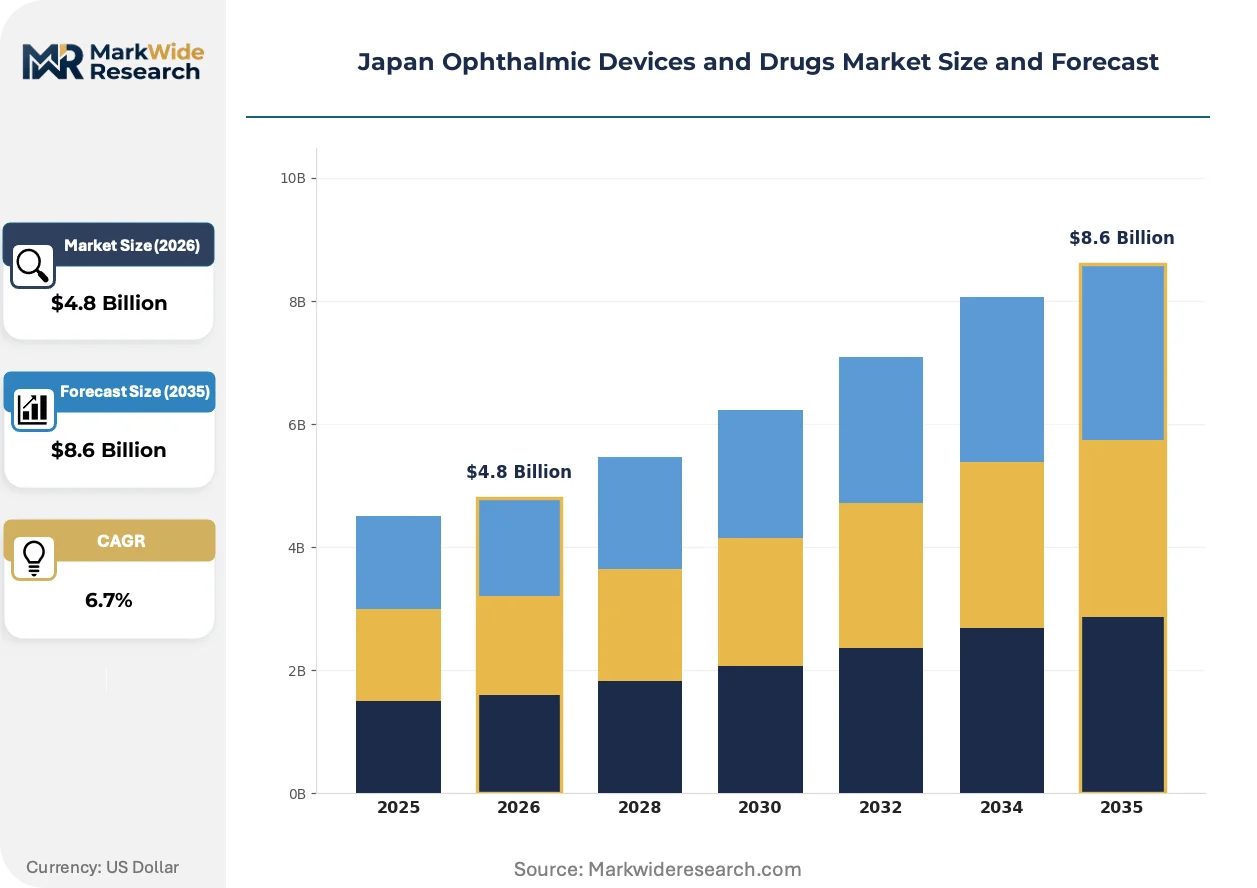
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Lenses, Intraocular Lenses, Surgical Instruments, Diagnostic Equipment Therapy Area: Glaucoma, Cataracts, Refractive Errors, Retinal Disorders End User: Hospitals, Clinics, Eye Care Centers, Home Care Delivery Mode: Topical, Injectable, Oral, Implantable |
| Companies Covered | Nidek Co., Ltd, Topcon Corporation, HOYA Corporation, Canon Medical Systems Corporation, Santen Pharmaceutical, Alcon Inc., Johnson & Johnson Vision Care, Kowa Company, Ltd, Otsuka Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Ophthalmic Devices and Drugs Market Shifts & Advancements
Software-defined functionality is reconfiguring value capture in Japanese ophthalmology, shifting revenue from capital equipment sales toward recurring diagnostic service fees and algorithm licensing.
Artificial intelligence-based fundus analysis is decentralizing diabetic retinopathy screening from centralized university hospitals to primary care clinics and pharmacy-based testing stations. Regional health cooperatives in Aichi and Hokkaido prefectures are deploying these platforms at 40-60 unit annual increments. The technology is compressing specialist referral bottlenecks while generating per-image diagnostic revenue streams that displace traditional consultation fees.
PMDA's 2023 guidance on machine learning-enabled medical devices is mandating locked algorithm versions and continuous performance monitoring for AI-integrated OCT systems. Manufacturers must submit real-world accuracy data quarterly, elevating post-market surveillance costs. Premium diagnostic segments are responding by segregating hardware from software licensing, allowing algorithm updates without full device re-registration.
Subscription-based equipment access is displacing outright purchase in independent Tokyo and Nagoya specialist clinics facing compressed reimbursement margins. Leasing consortia aggregate demand across 15-20 practice groups to secure volume discounts on excimer laser and femtosecond platforms. This shift is most visible in refractive surgery, where equipment utilization guarantees now determine contract pricing rather than capital depreciation schedules.
Japan Ophthalmic Devices and Drugs Market Segmentation
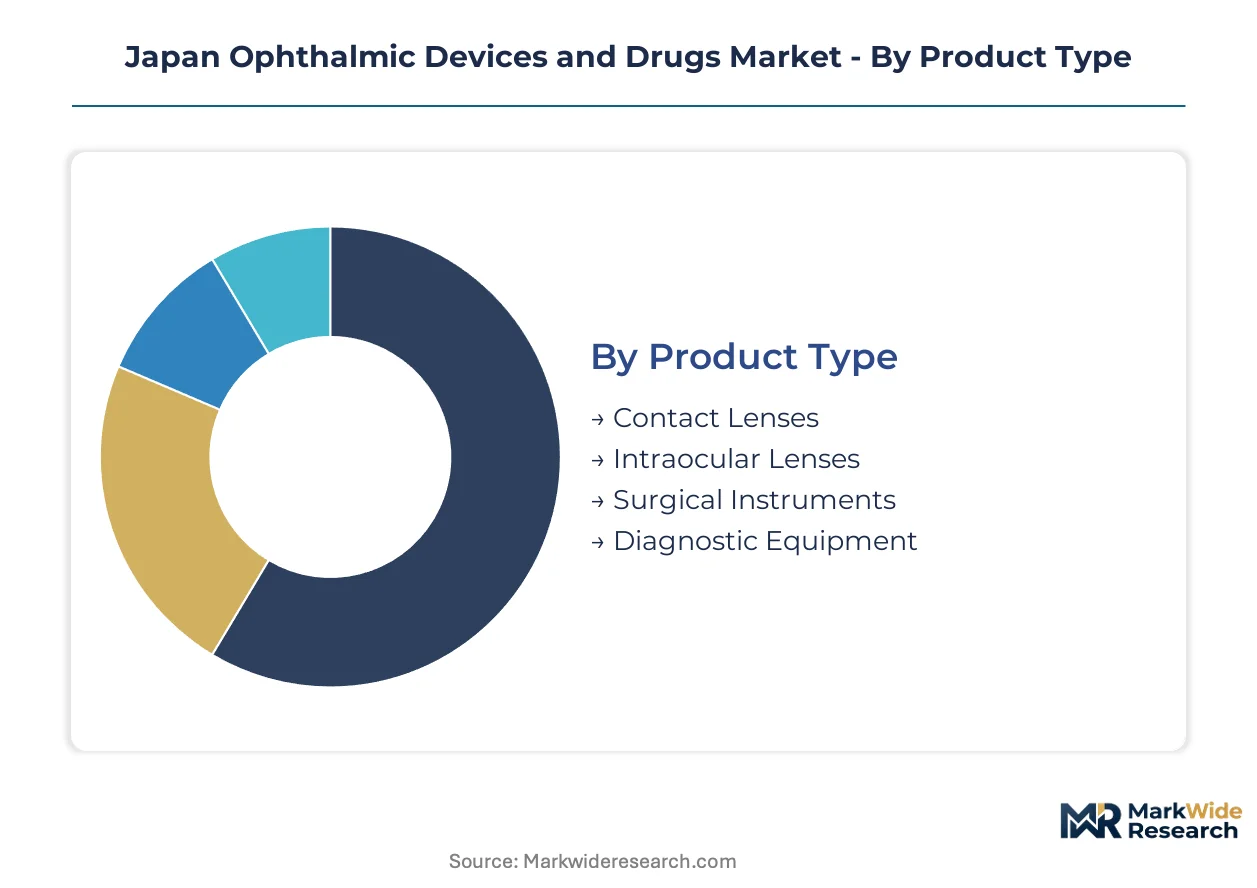
Segmentation in Japan's ophthalmic market reveals how procurement authority and reimbursement pathways concentrate demand across distinct customer clusters. Manufacturers calibrate their product portfolios and pricing architectures to match these structural divisions.
Product Type:
Supply concentration in Japanese ophthalmic manufacturing tilts toward intraocular and diagnostic platforms, with domestic producers holding captive positions in precision optics and coating technologies.
- Contact Lenses:Daily disposable silicone hydrogel formulations dominate prescription volumes through pharmacy and optical retail channels. Tokyo and Osaka urban corridors absorb the majority of premium toric and multifocal fittings, driven by aging presbyopes seeking spectacle independence.
- Intraocular Lenses:Hydrophobic acrylic platforms with square-edge design specifications prevent posterior capsular opacification in cataract procedures. Prefectural hospital networks in Aichi and Fukuoka are upgrading to extended depth-of-focus and toric variants, sustaining margin pools despite reimbursement compression on standard monofocal units.
- Surgical Instruments:Phacoemulsification handpieces and vitrectomy probes requiring sterile single-use or limited-reuse protocols.
- Diagnostic Equipment:Spectral-domain OCT and fundus autofluorescence systems with embedded AI analysis modules.
Intraocular Lenses absorbs the bulk of installed capacity; Diagnostic Equipment is expanding most quickly.
Therapy Area:
Cost tier differentiation separates chronic disease management from acute surgical intervention, with glaucoma and retinal therapies commanding sustained pharmaceutical expenditure against one-time device revenues in cataract and refractive segments.
- Glaucoma:Prostaglandin analogs and sustained-release bimatoprost implants target intraocular pressure reduction through trabecular meshwork and uveoscleral outflow enhancement. Specialist clinics in Kanagawa prefecture are adopting micro-invasive glaucoma surgery devices as adjuncts to pharmacologic therapy, shifting procedure economics toward device-anchored revenue.
- Cataracts:Phacoemulsification with monofocal or premium intraocular lens implantation constitutes the highest procedural volume category across Japan's aging demographic. Rural prefectures including Hokkaido and Tottori face surgeon availability constraints that limit premium lens adoption rates relative to urban centers.
- Refractive Errors:Laser vision correction and phakic intraocular lens procedures for myopia, hyperopia, and astigmatism correction.
- Retinal Disorders:Intravitreal anti-VEGF injections and sustained-release corticosteroid implants for diabetic macular edema and neovascular age-related macular degeneration.
Cataracts captures the dominant share of procedural throughput; Retinal Disorders is climbing the fastest on injectable therapy expansion.
End User:
Customer type fragmentation splits procurement authority between centralized hospital purchasing committees and independent specialist clinic owners, with divergent decision criteria on capital equipment versus consumable contracts.
- Hospitals:University-affiliated and prefectural medical centers with centralized biomedical engineering departments manage diagnostic platform standardization and surgical instrument sterilization protocols. METI smart medical device subsidies are accelerating AI-enabled fundus camera placement in regional hospitals serving aging catchment populations.
- Clinics:Independent ophthalmology practices and small group partnerships concentrate refractive surgery and premium cataract volumes in Tokyo, Nagoya, and Fukuoka metropolitan zones. Leasing consortia aggregate demand across 15-20 practice groups to secure volume discounts on excimer laser platforms.
- Eye Care Centers:Dedicated optical chains and vision correction facilities offering diagnostic screening and contact lens fitting services.
- Home Care:Self-administered topical therapies and monitoring devices for chronic glaucoma management.
Hospitals anchor capital equipment procurement; Clinics is gaining share fastest through refractive volume concentration.
Delivery Mode:
Maturity gradients separate established topical and oral administration from emerging implantable platforms requiring PMDA breakthrough therapy designations and specialized surgical training infrastructure.
- Topical:Eye drop formulations for glaucoma, dry eye, and allergic conjunctivitis deliver active agents through corneal penetration or conjunctival absorption. Generic prostaglandin competition has compressed pricing power, driving branded manufacturers toward preservative-free and fixed-dose combination formulations to defend formulary position.
- Injectable:Intravitreal anti-VEGF and corticosteroid injections for retinal disorders require sterile compounding and specialist administration in hospital or clinic settings. PMDA Sakigake fast-track designation is condensing premarket review periods for sustained-release intravitreal implants, accelerating product lifecycle transitions.
- Oral:Systemic carbonic anhydrase inhibitors and supplements for ocular surface disease management.
- Implantable:Sustained-release drug delivery systems and premium intraocular lenses positioned through surgical intervention.
Topical commands the largest prescription volume base; Implantable is expanding most quickly on sustained-release platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo dominates Japan's ophthalmic device procurement, with university-affiliated hospitals in the Kanto corridor driving spectral-domain OCT upgrades and premium intraocular lens adoption.
Kanto/Tokyo
Specialist clinics in Shinjuku and Shibuya wards concentrate refractive surgery volumes and diagnostic platform leasing. METI smart medical device subsidies accelerate AI-enabled fundus camera placement in regional hospitals serving aging catchment populations. The Tokyo-Osaka corridor maintains the highest density of ophthalmology fellowship programs.
Kansai/Osaka
Osaka prefecture anchors western Japan's cataract procedural throughput, with prefectural hospital networks upgrading to extended depth-of-focus lens variants. PMDA Sakigake fast-track designations for sustained-release implants streamline regulatory pathways for local clinical trial sponsors. The Osaka-Kobe industrial zone hosts precision optics manufacturing for diagnostic equipment components.
Chubu/Nagoya
Aichi prefecture's regional health cooperatives deploy tele-ophthalmology screening protocols for diabetic retinopathy, pairing imaging hardware with cloud-based diagnostic workflows. JIS T 0301 biocompatibility testing facilities in Nagoya create validation bottlenecks for novel intraocular lens materials. Independent practice groups in the metropolitan zone aggregate demand through leasing consortia.
Kyushu
Fukuoka prefecture presents whitespace for diagnostic platform placement and surgeon training partnerships relative to Tokyo's saturated specialist clinic density. Rural catchment areas in Saga and Kumamoto prefectures face vitreoretinal surgeon availability constraints that limit adoption of complex surgical platforms. METI industrial policy channels funding toward regional hospital AI-enabled diagnostic procurement.
Hokkaido
Hokkaido's dispersed population geography drives demand for mobile screening units and remote consultation infrastructure. Prefectural hospitals in Sapporo serve as referral hubs for retinal disorder management across the northern island. Silicone oil supply chain vulnerabilities expose vitreoretinal surgery programs to freight cost volatility and currency fluctuation.
Japan Ophthalmic Devices and Drugs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's ophthalmic sector. Domestic manufacturers with captive precision optics capabilities capture service margins on diagnostic platforms, while pharmaceutical specialists concentrate on sustained-release drug delivery formulations. Three archetypes dominate: integrated diagnostic-imaging houses, premium intraocular lens fabricators, and specialty pharmaceutical developers. Competitive moves center on software licensing unbundling from hardware sales and regional leasing consortia formation.
Within the integrated diagnostic tier, Nidek Co., Ltd and Topcon Corporation represent capital-intensive domestic producers with manufacturing footprints controlling service economics. HOYA Corporation exemplifies the premium lens fabrication archetype, occupying a position sustained by proprietary coating technologies. Among multinational pharmaceutical-device hybrids, Alcon Inc. and Johnson & Johnson Vision Care anchor the imported premium segment. Santen Pharmaceutical sits within the specialty pharmaceutical tier focused on ocular surface and glaucoma therapeutics.
| Leading Market Players |
|---|
| Nidek Co., Ltd |
| Topcon Corporation |
| HOYA Corporation |
| Canon Medical Systems Corporation |
| Santen Pharmaceutical |
| Alcon Inc. |
| Johnson & Johnson Vision Care |
| Kowa Company, Ltd |
| Otsuka Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between PMDA Sakigake-designated breakthrough therapies and standard generic formulations splits procurement budgets across Japanese ophthalmology, concentrating margin capture in premium intraocular lenses and AI-integrated diagnostic platforms while commoditizing topical prostaglandin analogs through pharmacy substitution pressures. This tier divergence feeds directly into supply chain configurations: premium device manufacturers maintain captive precision optics production in Osaka-Kobe industrial zones, whereas commodity drug distributors rely on consolidated import channels from Indian and Chinese API suppliers.
Pricing Analysis
Margin tightening in standard monofocal intraocular lenses reflects generic substitution pressures and prefectural hospital bulk procurement consolidation. The market operates on a hybrid structure combining capital equipment leasing for diagnostic platforms with per-unit transactional pricing for surgical consumables. Price differentiation hinges on JIS T 0301 biocompatibility certification tier and after-sales service bundling on OCT systems. Cost-down pressure on topical glaucoma therapies accelerates because pharmacy benefit managers favor preservative-free generic entries. Independent Tokyo specialist clinics exhibit lowest price sensitivity on premium toric and extended depth-of-focus lenses, while rural prefectural hospitals face acute budget constraints on capital equipment.
Supply Chain Analysis
Regional distribution centers in Osaka and Tokyo operate hub-and-spoke patterns feeding prefectural hospital networks and specialist clinic clusters. Manufacturing concentrates in Japan, Germany, and the United States for precision diagnostic optics and intraocular lens platforms, while active pharmaceutical ingredients draw from India and China. Raw material dependencies include high-purity silicone oil for vitreoretinal surgery, hydrophobic acrylic polymers for lens fabrication, and rare-earth elements for OCT laser sources. Single-source vulnerability in silicone oil imports exposes Japanese manufacturers to freight cost volatility. Distribution runs through authorized medical device distributors with sterile handling certifications and direct-to-hospital logistics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese ophthalmology is consolidating around software-integrated diagnostic platforms and sustained-release drug delivery systems, with PMDA's accelerating digital health guidance forcing capital-light competitors toward acquisition or exit.
For Market Incumbents: Deploy algorithm licensing unbundling from hardware sales to lock in recurring revenue streams against diagnostic equipment commoditization. Nidek and Topcon should deepen captive precision optics production in Osaka-Kobe to defend service margins on spectral-domain OCT replacement cycles. PMDA's quarterly real-world accuracy data requirements for AI-integrated devices elevate post-market surveillance costs that favor scaled players with dedicated regulatory affairs infrastructure. For New Entrants and Emerging Players: Launch via tele-ophthalmology screening partnerships with Aichi and Hokkaido regional health cooperatives, where METI smart medical device subsidies offset capital equipment barriers. Target Fukuoka prefecture's underdeveloped specialist clinic density for diagnostic platform placement and surgeon training consortia. The most penetrable segment is AI-enabled fundus cameras for diabetic retinopathy screening in primary care settings, bypassing saturated Tokyo-Osaka university hospital procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap diagnostic-imaging houses with locked hospital system relationships and software companion development capabilities. Long-term viability favors vertically integrated domestic manufacturers with captive coating technologies and PMDA Sakigake track records. Watch PMDA's evolving guidance on continuous learning algorithms as the inflection signal determining which AI-integrated platforms secure accelerated pathways versus extended review cycles.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Sakigake Fast-Track Pursuit | Condenses premarket review periods for sustained-release intravitreal implants and regenerative therapies. |
| Software Licensing Unbundling | Segregates hardware from algorithm revenue to enable updates without full device re-registration. |
| Regional Leasing Consortium Formation | Aggregates demand across 15-20 practice groups to secure volume discounts on excimer laser platforms. |
| Tele-Ophthalmology Infrastructure Partnership | Pairs imaging hardware with cloud-based diagnostic workflows for diabetic retinopathy screening reimbursement. |
| Captive Precision Optics Expansion | Reinforces domestic manufacturing control over spectral-domain OCT components and coating technologies. |
Research Methodology
Document review covered PMDA premarket approval filings, METI industrial policy white papers, and JIS standard specifications, complemented by interviews with regulatory affairs specialists at domestic manufacturers, biomedical engineering directors at prefectural hospitals, and procurement managers at regional health cooperatives. Secondary validation drew from hospital procurement databases, GPO contract repositories, and ophthalmology fellowship program completion records. Bottom-up demand modeling across product type, therapy area, and end-user segments was triangulated against top-down macroeconomic projections.
Historical shipment data for spectral-domain OCT systems and intraocular lens units was cross-referenced against panel input from equipment leasing consortia and surgeon training program directors. The analytical framework modeled segmentation across diagnostic versus surgical platforms, chronic versus acute intervention categories, and centralized hospital versus independent clinic procurement authority. CAGRs were derived from procedural volume trajectories tied to Japan's super-aged demographic transition and PMDA approval velocity for breakthrough therapy designations. Forecast inputs incorporated prefectural surgeon availability constraints and silicone oil supply chain exposure.
Regulatory timeline shifts, reimbursement compression on standard lenses, and vitreoretinal surgeon training pipeline bottlenecks are the dominant revision risks to demand projections. Forecasts reflect documented assumptions regarding PMDA digital health guidance evolution and METI subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Retinal Vasculitis Treatment Market
Ophthalmology
Diabetic Macular Edema Treatment Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Retinoblastoma Treatment Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Keratitis Treatment Market