
 Pediatric Vitrectomy Market | 2026-2036
Pediatric Vitrectomy Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Vitrectomy Market Analytics
The capital-intensity divergence between high-volume incumbents and specialized entrants is unwinding competitive dynamics in pediatric vitrectomy. Alcon leverages integrated manufacturing scale across vitrectomy machines and disposable packs. Carl Zeiss Meditec AG anchors its position through precision optics and intraoperative visualization systems. Synergetics USA Inc specializes in micro-instrumentation calibrated for pediatric anatomical constraints.
Pediatric vitrectomy denotes surgical removal of vitreous humor from a child's eye, typically performed with 23-gauge or 25-gauge instrumentation through transconjunctival sutureless ports to minimize tissue trauma in developing ocular structures. The procedure addresses retinal detachment, vitreous hemorrhage, and macular pathology in patients where anatomical scale and tissue compliance differ materially from adult populations. Instruments dominate current revenue as reusable forceps, cutters, and illuminators command premium pricing and replacement cycles. Minimally invasive technique categories are expanding fastest as surgeons adopt smaller-gauge systems that reduce operative time and postoperative inflammation in pediatric cases. Visualization systems concentrate margin pools because high-definition ophthalmic microscopes and wide-angle viewing systems require substantial capital outlay and recurring service contracts.
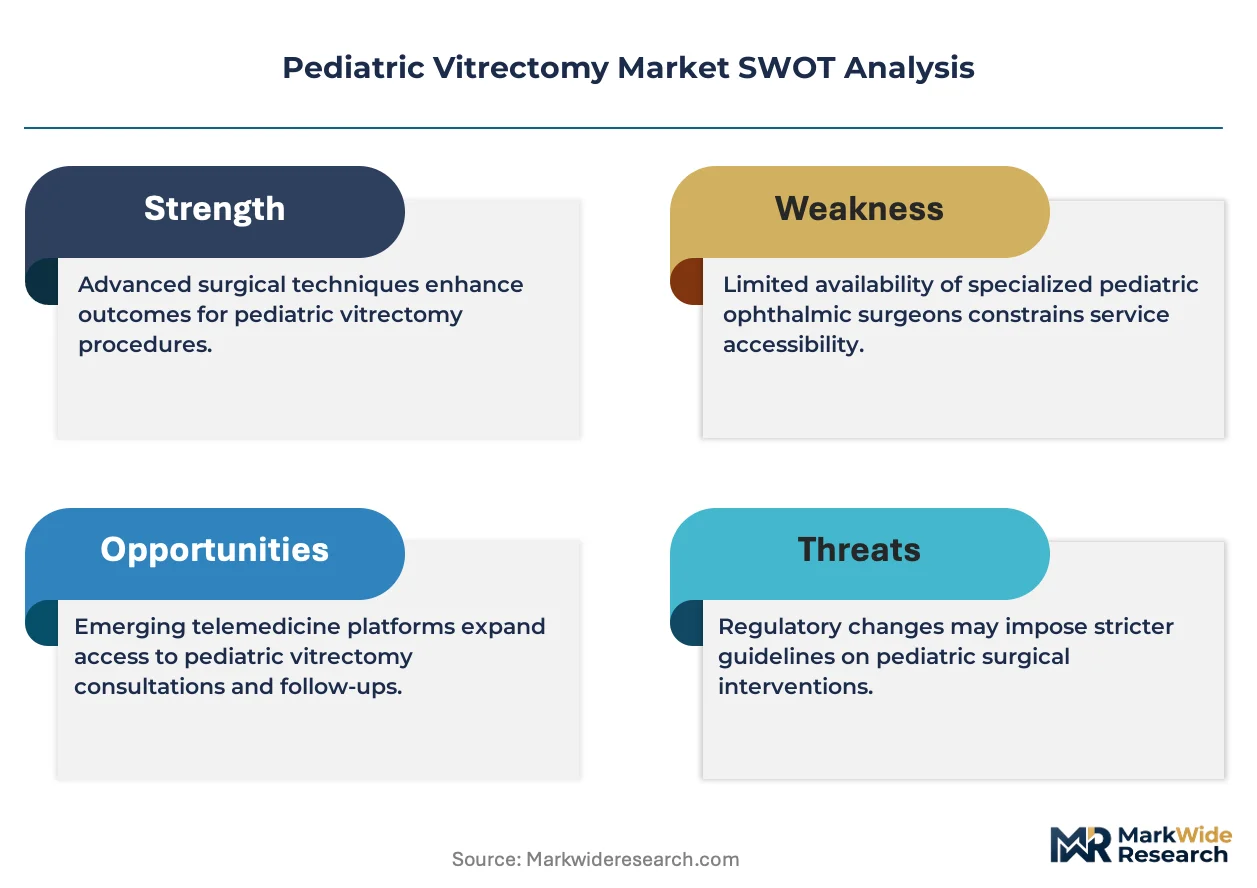
The FDA's humanitarian device exemption pathway shapes product development timelines for rare pediatric indications, while the EU MDR imposes stricter clinical evidence requirements on ophthalmic surgical devices entering European markets. ISO 13485 quality management standards govern manufacturing protocols for vitrectomy instruments across all major jurisdictions, with notified bodies scrutinizing biocompatibility of materials contacting immature ocular tissues. Stakeholders must monitor how regulatory divergence between the FDA's pediatric priority review and EMA's orphan device incentives reshapes geographic launch sequencing and clinical trial investment.
Market Dynamics
The FDA's pediatric device innovation pathway compresses regulatory timelines for miniature vitrectomy instruments while specialized pediatric ophthalmology centers concentrate demand around academic medical hubs in the United States.
Growth Catalysts
- Congenital retinal disorder prevalence:Pediatric hospitals are expanding surgical volumes for inherited conditions such as familial exudative vitreoretinopathy and persistent fetal vasculature.
- Humanitarian Device Exemption:The FDA pathway accelerates market access for rare pediatric indications, reducing clinical evidence burdens for device developers targeting small patient populations.
- 25-gauge instrumentation:Transconjunctival sutureless techniques reduce operative trauma in developing ocular structures, driving surgeon preference shifts toward smaller-gauge systems.
Market Restraints
- Silicone oil cost volatility:Tamponade agents face raw material price swings that compress margins on consumable-intensive procedures.
- EU MDR clinical evidence requirements:Stricter documentation mandates for ophthalmic surgical devices entering European markets extend launch timelines and inflate regulatory spend.
- Surgeon training pipeline constraints:Fellowship programs in pediatric vitreoretinal surgery produce limited annual graduates, capping procedure volume expansion regardless of instrument availability.
Strategic Opportunities
- India pediatric ophthalmology infrastructure:Government screening programs for retinopathy of prematurity create procedural demand that outpaces current vitrectomy machine deployment.
- Telemedicine-integrated postoperative monitoring:Remote fundus imaging protocols reduce travel burdens for families in rural catchment areas, expanding addressable patient pools.
- Orphan device incentives:EMA's regulatory framework offers fee reductions and protocol assistance for developers targeting ultra-rare pediatric retinal conditions.
Industry Challenges
- Pediatric-specific micro-instrumentation design:Calibrating cutter speeds and port geometries for immature scleral rigidity requires iterative prototyping that strains R&D budgets.
- Biocompatibility certification timelines:ISO 10993 testing for materials contacting developing ocular tissues extends preclinical phases beyond adult-equivalent device schedules.
- Supply chain reconfiguration for sterile single-use packs:Just-in-time manufacturing of customized instrument kits conflicts with pediatric case volume unpredictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Vitrectomy Market |
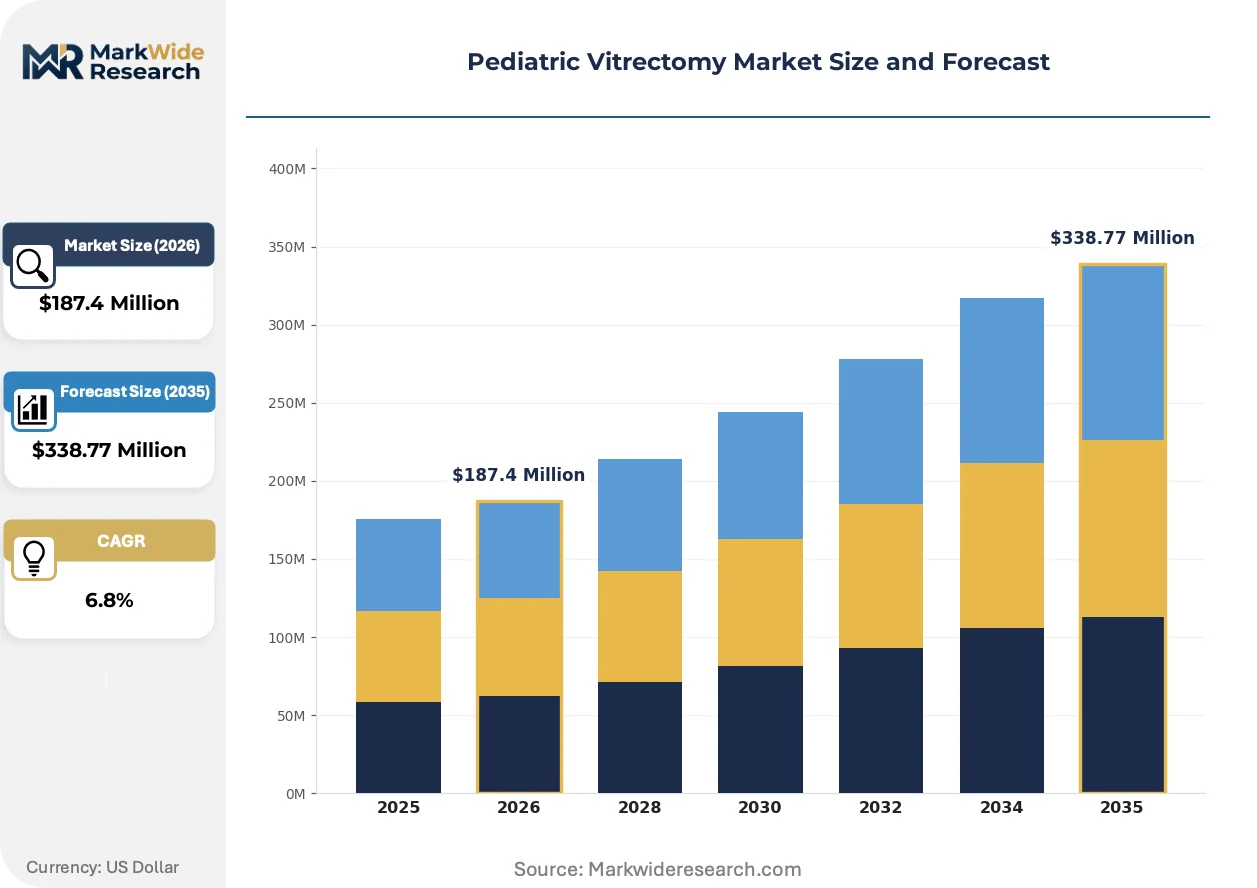
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Laser Systems, Surgical Supplies, Visualization Systems End User: Pediatric Hospitals, Eye Clinics, Research Institutions, Surgical Centers Technique: Conventional Vitrectomy, Minimally Invasive, Pneumatic Retinopexy, Scleral Buckling Application: Retinal Detachment, Vitreous Hemorrhage, Macular Hole, Diabetic Retinopathy |
| Companies Covered | Alcon, Bausch + Lomb, Carl Zeiss Meditec AG, Optos plc, Orion Medic, Lumenis Ltd, Synergetics USA Inc, Medone Surgical Inc, NIDEK Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Vitrectomy Market Evolving Landscape
Surgical visualization and instrument design are converging around pediatric anatomical constraints, with three distinct vectors reshaping competitive positioning in this specialized segment.
High-definition ophthalmic microscopes with integrated optical coherence tomography are miniaturizing intraoperative imaging capabilities for pediatric cases. Academic medical centers in Boston and Philadelphia are adopting these systems at replacement-cycle pace. The technology is miniaturizing the footprint of combined diagnostic-therapeutic platforms, compressing capital equipment budgets into single-purchase decisions.
The EU MDR imposes stricter clinical evidence requirements on ophthalmic surgical devices entering European markets. Manufacturers must generate pediatric-specific safety data rather than extrapolating from adult trials. Vitrectomy pack assemblers targeting European hospital purchasing consortia are responding by front-loading clinical study investments before CE marking applications.
Consolidated procurement by pediatric ophthalmology center networks is displacing individual surgeon preference-based purchasing. Hospital systems in Texas and California are standardizing on single-vendor vitrectomy platforms to secure volume discounts and unified service contracts. This concentration is most visible in the United States, where academic medical hub consolidation has reduced independent pediatric retina practice autonomy.
Pediatric Vitrectomy Market Segmentation
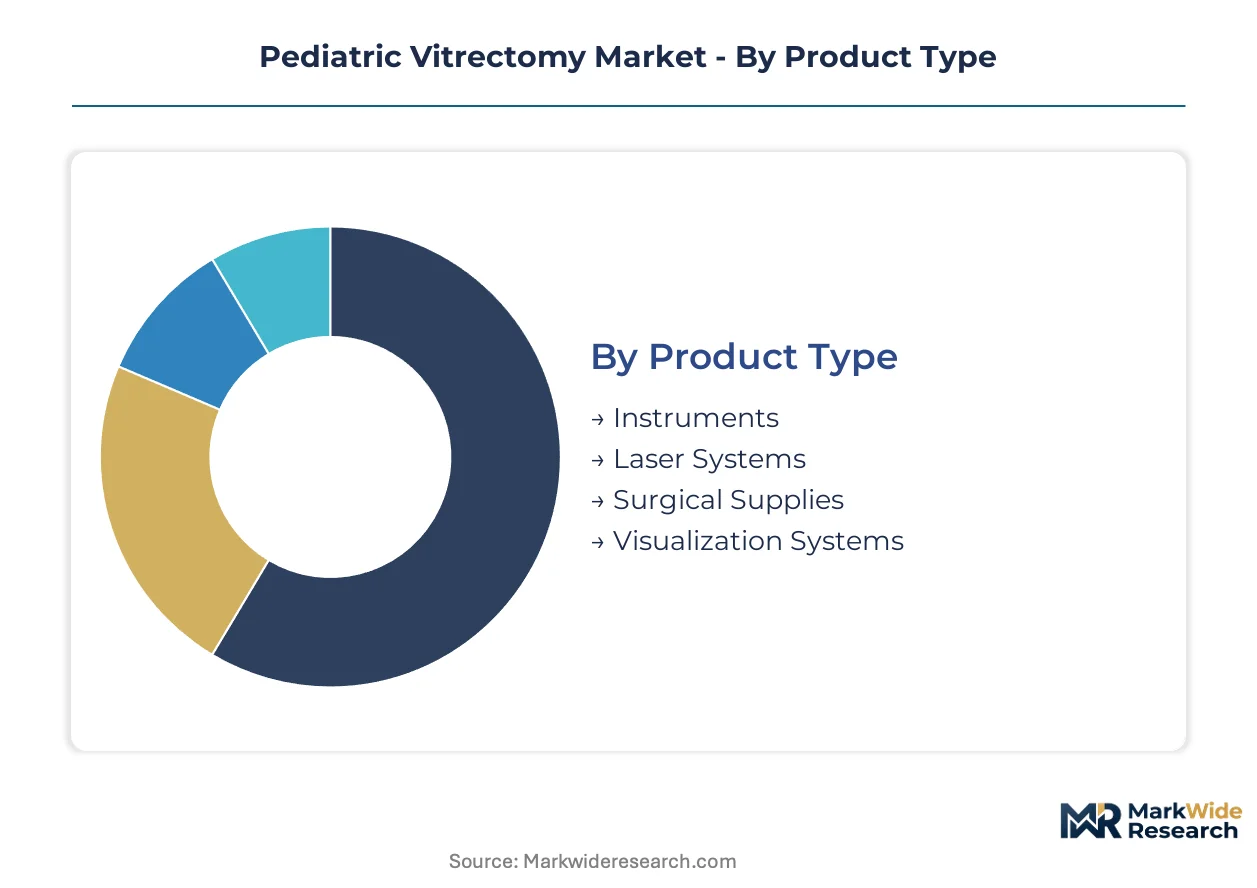
Pediatric vitrectomy segmentation reveals distinct margin architectures across product categories. Technique and product type divisions command premium pricing due to regulatory complexity, while end-user concentration around academic medical centers shapes procurement patterns.
Product Type:
Substitution pressure concentrates in surgical supplies as commoditized consumables face price compression from hospital group purchasing organizations.
- Instruments:Reusable forceps, vitrectomy cutters, and fiberoptic illuminators manufactured to 23-gauge and 25-gauge specifications for pediatric scleral rigidity. Demand clusters at academic medical centers in Boston and Philadelphia where replacement cycles accelerate with surgical volume expansion.
- Visualization Systems:High-definition ophthalmic microscopes with wide-angle viewing attachments and integrated optical coherence tomography. Procurement concentrates in pediatric ophthalmology networks standardizing on single-vendor platforms to secure unified service contracts.
- Laser Systems:Endolaser probes and indirect ophthalmoscope delivery systems calibrated for pediatric retinal tissue response.
- Surgical Supplies:Disposable packs combining infusion cannulas, silicone oil tamponade agents, and suture materials.
Instruments retain volume leadership; visualization systems hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital systems from outpatient facilities constrained by equipment budgets.
- Pediatric Hospitals:Academic medical centers with dedicated pediatric ophthalmology divisions performing high-complexity congenital cases. Volume concentrates at institutions clustered around Philadelphia, Boston, and Houston where fellowship-trained surgeons manage inherited retinal disorders.
- Surgical Centers:Ambulatory facilities equipped for routine pediatric vitrectomy procedures with reduced overnight admission requirements. Expansion accelerates in Texas and California where certificate-of-need restrictions loosen.
- Eye Clinics:Outpatient settings handling diagnostic staging and postoperative monitoring rather than primary surgery.
- Research Institutions:Clinical trial sites generating pediatric-specific safety data for regulatory submissions under FDA humanitarian device exemption pathways.
Pediatric hospitals retain volume leadership; surgical centers hold the steepest expansion curve.
Technique:
Application maturity varies sharply across technique categories, with established methods facing displacement from smaller-gauge innovations.
- Minimally Invasive:25-gauge transconjunctival sutureless approaches reducing operative trauma in developing ocular structures. Adoption concentrates at centers in the United States where surgeon training programs emphasize smaller-gauge proficiency for pediatric anatomical constraints.
- Conventional Vitrectomy:20-gauge instrumentation requiring scleral sutures and conjunctival dissection. Demand persists in resource-constrained settings and complex cases requiring instrument exchange flexibility.
- Pneumatic Retinopexy:Gas tamponade techniques for selected retinal detachments avoiding vitreous entry entirely.
- Scleral Buckling:External indentation procedures for primary retinal detachment repair without vitrectomy in appropriate pediatric candidates.
Conventional vitrectomy retains volume leadership; minimally invasive holds the steepest expansion curve.
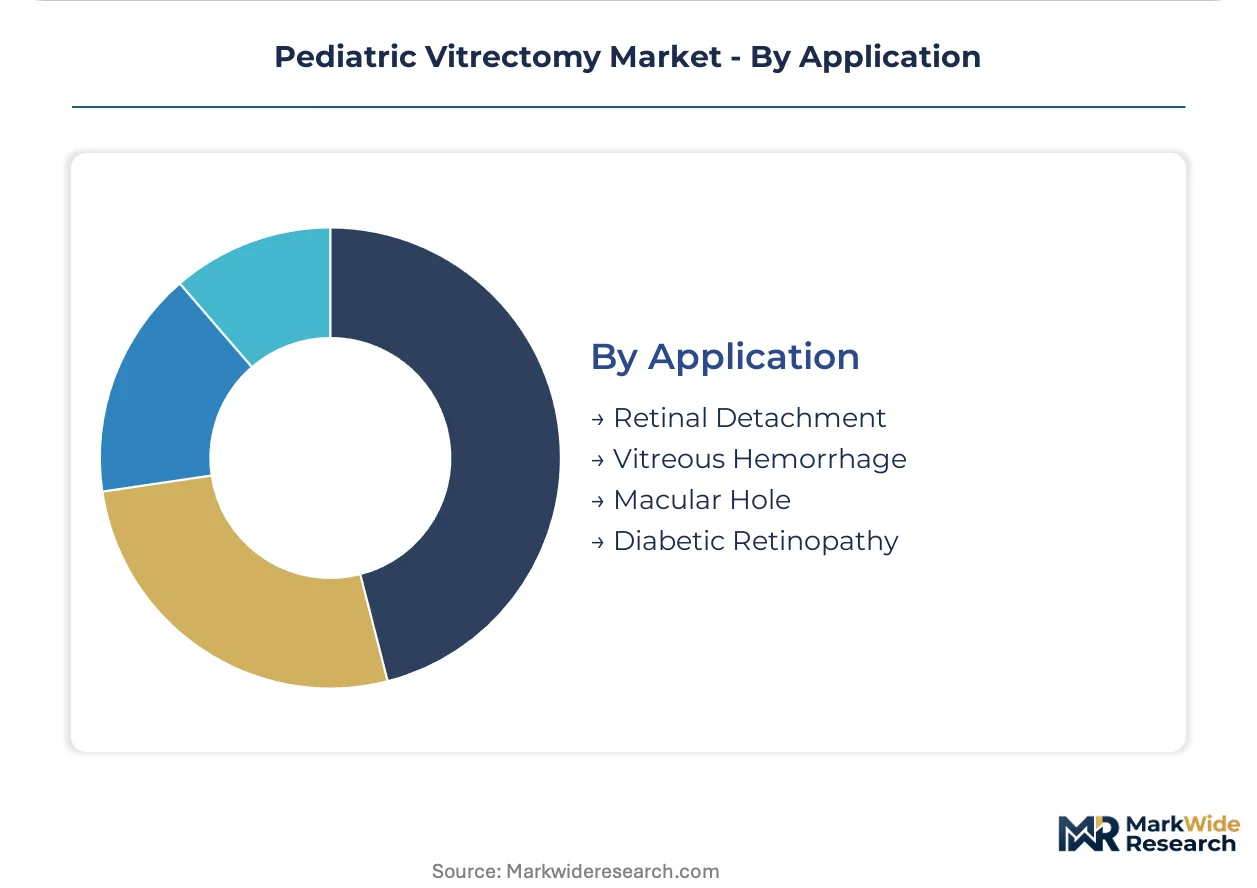
Application:
Geography of disease prevalence shapes application demand, with congenital conditions clustering differently than acquired pathology.
- Retinal Detachment:Repair of rhegmatogenous and tractional detachments in pediatric trauma and myopia cases. Volume concentrates at tertiary referral centers managing complex pediatric presentations.
- Vitreous Hemorrhage:Clearance of blood obscuring retinal visualization from trauma, vascular malformations, or postsurgical complications.
- Macular Hole:Surgical closure of full-thickness defects in the pediatric population, often secondary to trauma or high myopia.
- Diabetic Retinopathy:Vitrectomy for tractional detachment and vitreous hemorrhage in adolescent diabetic patients.
Retinal detachment retains volume leadership; macular hole holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature markets where academic medical centers drive complex congenital case volume and emerging economies where government screening programs for retinopathy of prematurity are expanding procedural access faster than surgical infrastructure deployment.
United States
Pediatric vitrectomy volume concentrates at tertiary referral centers managing familial exudative vitreoretinopathy and persistent fetal vasculature cases. The FDA's pediatric device innovation pathway accelerates regulatory access for miniature surgical instruments targeting rare indications. Philadelphia, Boston, and Houston anchor the highest surgical densities where fellowship-trained specialists cluster at academic medical hubs.
Germany
Precision optics manufacturing capabilities support domestic demand for high-definition ophthalmic microscopes with integrated intraoperative imaging. The EU MDR imposes stricter clinical evidence requirements on ophthalmic surgical devices, extending launch timelines for pediatric-specific instrument lines. The Baden-Württemberg corridor hosts concentrated medical device engineering expertise serving both domestic and export markets.
India
Government screening programs for retinopathy of prematurity generate procedural demand that substantially outpaces current vitrectomy machine deployment in pediatric ophthalmology units. CDSCO regulatory frameworks govern device registration while state-level health missions expand neonatal retinal screening infrastructure. Maharashtra and Karnataka lead surgical volume growth where private hospital chains are investing in dedicated pediatric retina units.
Japan
PMDA orphan device incentives support development of micro-instrumentation calibrated for pediatric anatomical constraints in ultra-rare retinal conditions. Aging demographics paradoxically sustain investment in pediatric subspecialties as academic medical centers preserve comprehensive service lines. The Tokyo-Osaka corridor maintains the highest concentration of fellowship-trained pediatric vitreoretinal surgeons.
Brazil
ANVISA regulatory pathways for ophthalmic surgical devices require pediatric-specific safety data rather than extrapolation from adult trials, inflating clinical study investments. Private hospital networks in São Paulo and Rio de Janeiro are deploying vitrectomy platforms for congenital retinal disorder cases previously referred abroad. Regional disparities in pediatric ophthalmology infrastructure concentrate surgical capacity in southeastern states.
Pediatric Vitrectomy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven manufacturers of complete vitrectomy platforms commanding procurement decisions at consolidated hospital networks while precision instrument developers capture margin in customized pediatric applications. The competitive terrain rewards backward integration into optical component manufacturing and captive supply of single-use consumables. Three archetypes dominate: diversified ophthalmology conglomerates with full-suite portfolios, precision optics specialists leveraging visualization system lock-in, and micro-instrumentation developers addressing anatomical constraints specific to pediatric cases. Consolidated procurement by pediatric ophthalmology center networks and strategic partnerships for regulatory navigation represent the dominant competitive vectors.
Within the diversified ophthalmology tier, Alcon and Bausch + Lomb occupy positions as integrated platform providers, while Carl Zeiss Meditec AG exemplifies the precision optics archetype through its visualization system specialization. Synergetics USA Inc represents the micro-instrumentation specialist tier focused on pediatric anatomical constraints. These three anchors demonstrate how competitive positioning stratifies across manufacturing scale, optical engineering depth, and subspecialty clinical focus.
| Leading Market Players |
|---|
| Alcon |
| Bausch + Lomb |
| Carl Zeiss Meditec AG |
| Optos plc |
| Orion Medic |
| Lumenis Ltd |
| Synergetics USA Inc |
| Medone Surgical Inc |
| NIDEK Co Ltd |
| Others |
Value Network & Pricing Analysis
Silicone oil substitution for gas tamponade in select pediatric cases simultaneously shifts supply geography toward pharmaceutical-grade chemical manufacturers in Germany and India while compressing consumable pricing power for traditional tamponade suppliers. This input substitution reshapes procurement economics as hospitals evaluate total procedure cost against clinical outcomes.
Pricing Analysis
Service contracts and extended warranty tiers on vitrectomy platforms drive lifetime value more than initial capital outlays. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with bundled service agreements from ambulatory surgical centers purchasing bare equipment. Price differentiation hinges on ISO 13485 certification tier and geographic delivery cost from German or Japanese optical component suppliers. Pricing pressure stems from consolidated procurement by pediatric hospital networks in Texas and California. Ambulatory surgical centers exhibit highest price sensitivity; academic medical hubs with dedicated endowments demonstrate lowest.
Supply Chain Analysis
Inventory lead times for customized 25-gauge pediatric instrument sets stretch unpredictably due to case volume volatility at specialized centers. Manufacturing concentrates in Germany, Japan, and the United States for precision optical components and vitrectomy machines. Raw material dependencies include medical-grade silicone for tamponade agents, fused silica for fiberoptic illuminators, and surgical stainless steel for forceps. Single-source vulnerability in miniature cutter motor assemblies creates supply risk. Distribution runs through hospital group purchasing organizations and specialized ophthalmology equipment distributors serving academic medical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as consolidated procurement by pediatric ophthalmology networks displaces individual surgeon preference, creating niches for specialized micro-instrumentation developers targeting anatomical constraints underserved by platform incumbents.
For Market Incumbents: Fortify service contract bundling to lock in pediatric hospital networks against emerging precision instrument specialists. Deepen backward integration into optical component manufacturing to defend margin position against supply cost volatility. Expand ISO 13485-certified production capacity in Baden-Württemberg to satisfy EU MDR documentation requirements without cross-border dependency.
For New Entrants and Emerging Players: Differentiate on pediatric-specific cutter speed calibration and port geometry optimization for immature scleral rigidity. Target ambulatory surgical centers in Texas and California where certificate-of-need restrictions loosen and equipment budgets constrain incumbent platform penetration. Pursue FDA humanitarian device exemption pathway for rare congenital indications to accelerate market access without full pivotal trial investment.
For Investors and Strategic Acquirers: Capital is best deployed toward micro-instrumentation specialists with captive biocompatibility testing capabilities and existing pediatric surgeon advisory relationships. Long-term viability centers on regulatory navigation expertise across FDA pediatric priority review and EMA orphan device frameworks. Watch for inflection when academic medical center procurement committees mandate pediatric-specific safety data rather than adult trial extrapolation.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric-Specific FDA Submission | Humanitarian device exemption pathway accelerates regulatory access for rare congenital retinal conditions. |
| Hospital System Partnership | Consolidated procurement by Texas and California pediatric networks demands unified service contract structures. |
| CE Marking Pathway | EU MDR pediatric-specific clinical evidence requirements extend timelines but create competitive moats. |
| Software Companion Development | Telemedicine-integrated postoperative monitoring expands addressable patient pools in rural catchment areas. |
| Reimbursement Strategy | Coding alignment with retinopathy of prematurity screening programs unlocks government-funded procedural volume. |
Research Methodology
Initial hypotheses were tested against primary input from pediatric vitreoretinal surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary research drew from FDA 510(k) filings, EMA orphan device designations, hospital procurement databases, and CMS Medicare procedural volume data. Bottom-up instrument shipment analysis triangulated against top-down spending estimates from academic medical center capital budgets.
Variance decomposition across technique adoption curves, product replacement cycles, and geographic expansion patterns anchored the analytical framework. Segmentation dimensions modeled include product type, end-user facility tier, surgical technique gauge, and application pathology across the projection horizon. CAGRs derived from surgeon procedure volume projections, equipment replacement elasticity estimates, and consumable utilization rates per case.
The analysis sits within stated boundaries; outcomes outside sustained fellowship program output, stable silicone oil pricing, and current FDA pediatric pathway structures would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline stability and hospital consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Ophthalmic Suspension Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Synoptophore Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Retina Health Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Astigmatism Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Ophthalmic Drugs and Devices Market