
 Europe Intraocular Lens Market | 2026-2036
Europe Intraocular Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intraocular Lens Market Foresight
Procurement from single-source contracts to multi-vendor arrangements is shifting as European hospital networks seek supply resilience for intraocular lenses. Alcon Inc. leverages its broad hydrophobic acrylic portfolio to sustain contracted volumes across German and French hospital chains. Carl Zeiss Meditec AG anchors its position through direct sales relationships with university eye clinics. Rayner Group specializes in premium toric designs that differentiate its offering in private ophthalmic clinics.
An intraocular lens is a biocompatible artificial implant, typically measuring 5.5–6.0 mm in optic diameter with haptic loops for capsular bag fixation, that replaces the eye's natural crystalline lens after cataract extraction or refractive lens exchange. Hydrophobic acrylic dominates material selection due to its low posterior capsular opacification rates and stable refractive outcomes. Monofocal lenses still occupy the largest volume share across European national health systems, though toric segments command superior margins where astigmatism correction is bundled into procedure pricing.
EMA coordination and the EU Medical Device Regulation shape clinical trial obligations and post-market surveillance for all implantable optics sold in member states. CE marking under MDR requirements is forcing manufacturers to rebuild technical documentation with stronger clinical performance data. The F-Gas Regulation indirectly affects lens manufacturing where fluorinated compounds appear in certain polishing or cleaning processes. Stakeholders must monitor how notified body capacity constraints delay MDR certifications and reshape competitive timelines for new product introductions.
Market Dynamics
The EU Medical Device Regulation is compressing competitive timelines for intraocular lens manufacturers, forcing wholesale rebuilding of technical documentation while notified body capacity constraints create certification bottlenecks that reshape market entry dynamics.
Growth Catalysts
- Aging demographics:Germany, France, and Italy face accelerating cataract prevalence as populations over 65 expand, driving procedural volumes through national health reimbursement frameworks.
- CE marking under MDR:Stricter clinical evidence requirements for implantable devices are elevating barriers for marginal competitors, consolidating volume around established manufacturers with robust post-market surveillance infrastructure.
- Hydrophobic acrylic material:Low posterior capsular opacification rates and refractive stability are pulling material selection away from silicone and hydrophilic alternatives in premium lens categories.
Market Restraints
- Notified body capacity constraints:Limited MDR-designated certification bodies in Germany and the Netherlands are extending approval timelines by 12-18 months for new lens designs.
- Input cost volatility:High-purity optical-grade acrylic resin prices fluctuate with petrochemical feedstock movements, squeezing margin stability for mid-tier manufacturers.
- Monofocal reimbursement ceilings:National health systems in Spain and Italy cap procedural payments, constraining uptake of higher-margin toric and multifocal alternatives.
Strategic Opportunities
- Private ophthalmic clinic expansion:Poland and Romania show underpenetrated premium lens penetration where out-of-pocket payment models bypass reimbursement constraints.
- Extended depth-of-focus convergence:Blending diffractive optics with wavefront-optimized surfaces creates differentiation in presbyopia-correcting segments where patient willingness-to-pay exceeds public system limits.
- CSRD alignment:Early adoption of supply chain carbon disclosure requirements positions manufacturers favorably with hospital procurement networks integrating sustainability criteria.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 9-14 month completion windows, delaying MDR submission readiness.
- Legacy ERP integration:Unique Device Identification traceability mandates under MDR Article 27 force mid-size manufacturers to reconfigure manufacturing execution systems for lot-level serialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intraocular Lens Market |
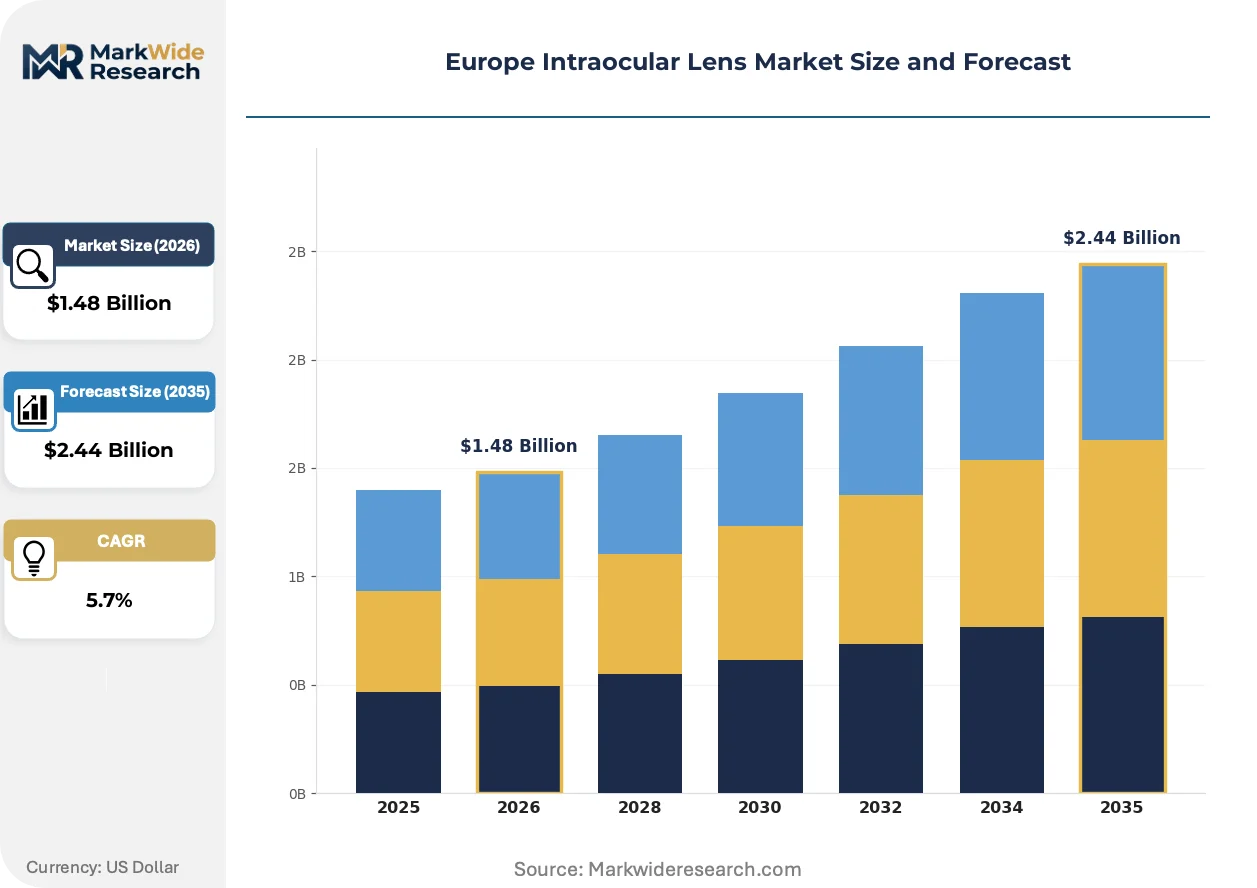
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofocal, Multifocal, Toric, Accommodative Material: Hydrophobic Acrylic, Hydrophilic Acrylic, Silicone, PMMA End User: Hospitals, Ophthalmic Clinics, Outpatient Surgery Centers, Ambulatory Surgical Centers Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | Alcon Inc., Bausch & Lomb Incorporated, Johnson & Johnson Vision Care, Inc., Carl Zeiss Meditec AG, HOYA Corporation, Rayner Group, STAAR Surgical, SIFI S.p.A, PhysIOL, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intraocular Lens Market Shifts & Advancements
Digital surgical planning platforms and femtosecond laser integration are reconfiguring how intraocular lens power calculations and toric alignment protocols are executed in European cataract practice.
Wavefront-optimized hydrophobic acrylic designs is overtaking conventional spherical optics in German and French university clinics, where refractive outcomes data drives referral patterns. Private ophthalmic chains in Switzerland and Austria are adopting these platforms fastest, compressing demand for basic monofocal inventory while expanding premium lens attach rates.
The F-Gas Regulation is restricting fluorinated compound use in lens polishing and cleaning processes, forcing manufacturers to validate aqueous or supercritical CO2 alternatives. German production facilities face the steepest compliance deadlines, with 2027 phase-down targets accelerating capital allocation toward green chemistry retrofits.
Hospital network consolidation is compressing vendor rosters from five-plus suppliers to two or three preferred partners per region. Nordic procurement alliances and French hospital group purchasing organizations are consolidating volume under framework agreements that bundle lenses with viscoelastic and phacoemulsification consumables, marginalizing standalone lens distributors.
Europe Intraocular Lens Market Segmentation
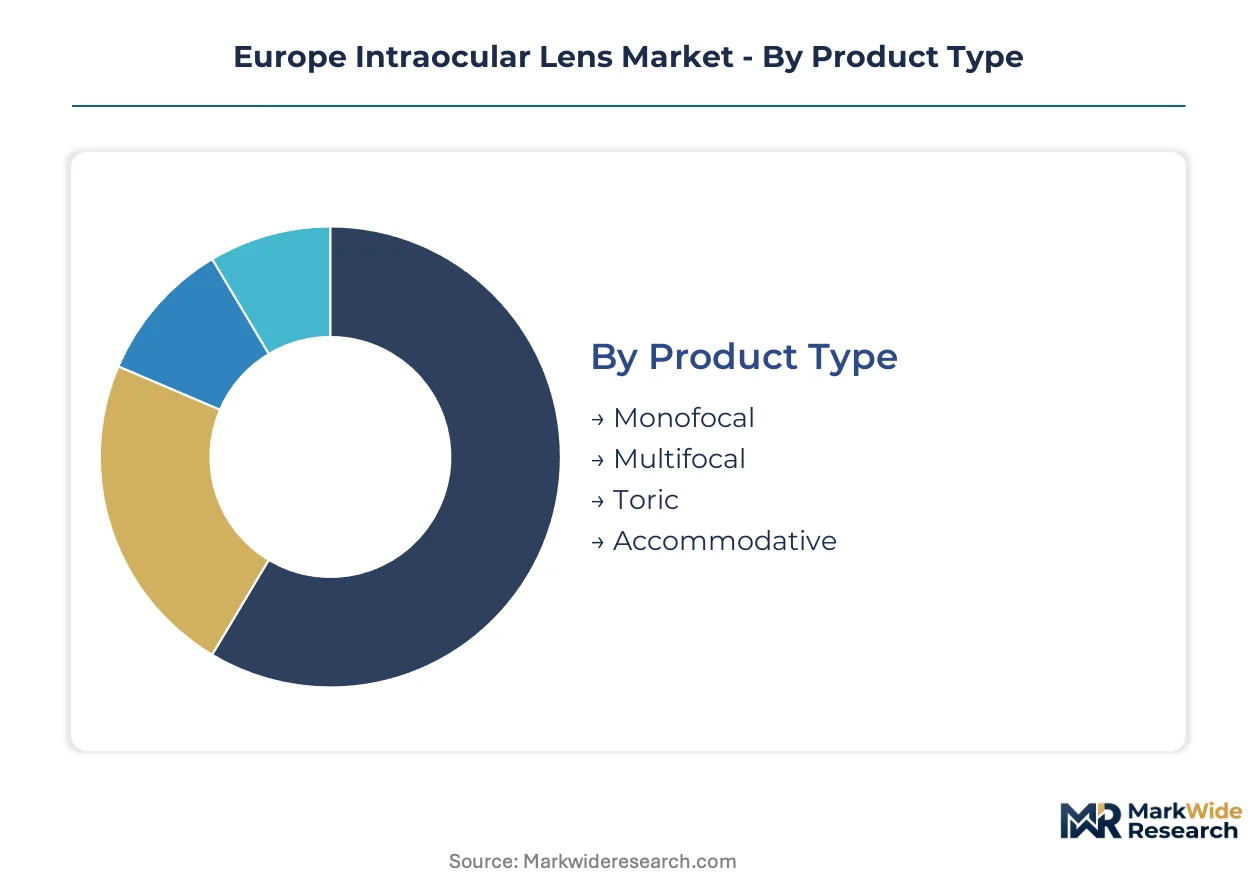
Intraocular lens segmentation in Europe reflects divergent capital requirements across manufacturing technologies and procurement pathways. Hydrophobic acrylic production demands precision polymerization infrastructure, while distribution channel selection determines working capital intensity and regulatory compliance burdens.
Product Type:
Capital intensity varies sharply across optical designs, with multifocal and toric platforms requiring substantially higher R&D investment than spherical alternatives.
- Monofocal:Single-focus optics with fixed spherical or aspheric curvature dominate procedure volumes across European national health systems. German and French hospital chains standardize on these designs for baseline cataract reimbursement tiers, constraining margin expansion despite scale advantages.
- Toric:Cylindrical correction integrated into hydrophobic acrylic platforms addresses pre-existing corneal astigmatism. Private ophthalmic clinics in Switzerland and Austria absorb premium pricing for these designs where out-of-pocket payment models bypass reimbursement ceilings.
- Multifocal:Diffractive optic zones enable simultaneous distance and near vision correction.
- Accommodative:Hinge-based designs attempt dynamic focal length adjustment through ciliary muscle action.
Monofocal designs absorb the bulk of installed manufacturing capacity; toric platforms are expanding most quickly across premium surgical settings.
Material:
Raw material selection determines biocompatibility testing timelines and post-implantation performance profiles under EMA surveillance frameworks.
- Hydrophobic Acrylic:Water-repelling polymer chains with low glass transition temperatures minimize posterior capsular opacification. German production facilities favor this chemistry for its refractive stability and compatibility with femtosecond laser-assisted delivery systems.
- Hydrophilic Acrylic:Higher water content permits injection through smaller incisions but elevates calcification risk in diabetic patients.
- Silicone:Elastomeric optics with high oxygen permeability persist in specific microincision applications.
- PMMA:Rigid polymethyl methacrylate remains confined to scleral-fixated secondary procedures and emerging market exports.
Hydrophobic acrylic commands the dominant production footprint; hydrophilic alternatives face contracting share amid MDR biocompatibility documentation requirements.
End User:
Procurement sophistication and reimbursement structure create distinct customer archetypes with divergent vendor relationship expectations.
- Hospitals:Integrated health networks in France and Italy negotiate multi-year framework agreements bundling lenses with viscoelastic and phacoemulsification consumables. These contracts demand extensive clinical evidence packages and dedicated field support teams.
- Ambulatory Surgical Centers:Standalone cataract facilities in Germany and the Netherlands optimize throughput through standardized lens inventories and just-in-time replenishment. Reimbursement stability supports predictable demand forecasting for contracted suppliers.
- Ophthalmic Clinics:Private practice settings concentrate premium lens adoption where patient co-payment models apply.
- Outpatient Surgery Centers:Intermediate facilities bridge hospital and clinic environments with mixed funding structures.
Hospitals anchor the majority of procurement volume; ambulatory surgical centers are gaining share fastest as cataract migration accelerates from inpatient settings.
Distribution Channel:
Channel selection shapes margin capture and regulatory traceability obligations under EU Medical Device Regulation Article 27 requirements.
- Direct Sales:Manufacturer-employed representatives engage university eye clinics and major hospital chains with technical consultation and surgical training. Carl Zeiss Meditec and Alcon maintain dedicated field organizations across German-speaking markets.
- Distributors:Regional wholesalers with MDR-compliant warehousing and lot-level serialization capabilities serve mid-tier manufacturers lacking captive logistics infrastructure.
- Wholesale:Aggregated purchasing cooperatives in Nordic countries consolidate volume for price leverage.
- Online Retail:Limited to accessory and consumable categories given implantable device traceability mandates.
Direct sales channels capture the predominant value flow; distributor relationships are deepening fastest among mid-size manufacturers seeking European market entry without field force investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical-grade acrylic resin production in the Netherlands anchors material supply chains for lens fabrication across Western Europe. German polymerization facilities convert these feedstocks into hydrophobic acrylic blanks that feed finishing operations in multiple jurisdictions.
Germany
Aging demographics and stable statutory health insurance reimbursement sustain the highest cataract procedural volumes in Europe. The EU Medical Device Regulation's notified body capacity constraints in Berlin and Munich extend certification timelines for new lens designs. The Rhine-Main cluster around Frankfurt concentrates manufacturing execution system retrofits for Unique Device Identification compliance.
France
Hospital group purchasing organizations consolidate procurement under framework agreements bundling lenses with viscoelastic consumables. ANSM oversight of post-market surveillance elevates documentation burdens for implantable optics. The Lyon-Grenoble corridor hosts university eye clinics driving adoption of wavefront-optimized designs.
Italy
Regional health system fragmentation creates procurement heterogeneity between Lombardy and southern regions. Monofocal reimbursement ceilings constrain premium lens uptake in public hospitals. The Emilia-Romagna manufacturing belt around Bologna maintains secondary finishing capacity for mid-tier European suppliers.
Switzerland
Private ophthalmic clinic density supports out-of-pocket payment models for toric and presbyopia-correcting segments. Swissmedic's alignment with EMA clinical evidence standards streamlines MDR certification pathways for manufacturers. The Basel-Zurich corridor concentrates surgical training centers influencing lens selection protocols.
Poland
Underpenetrated premium lens adoption creates expansion opportunities where private payment bypasses reimbursement constraints. National reimbursement frameworks lag Western European levels, channeling volume toward basic monofocal designs. The Warsaw-Kraków corridor shows fastest ambulatory surgical center growth as cataract migration accelerates from inpatient settings.
Europe Intraocular Lens Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and hospital contracting relationships. Market structure tilts toward consolidation as MDR certification costs marginalize mid-tier manufacturers lacking post-market surveillance infrastructure. Three archetypes dominate: diversified ophthalmic conglomerates with broad hydrophobic acrylic portfolios, precision optics specialists leveraging direct university clinic relationships, and regional champions concentrating on premium toric niches. Competitive moves center on multi-year framework agreement renewals with French and German hospital chains, alongside manufacturing execution system upgrades for Unique Device Identification traceability.
Among diversified ophthalmic conglomerates, Alcon Inc. and Johnson & Johnson Vision Care, Inc. occupy positions reflecting scale-driven procurement advantages across integrated health networks. Carl Zeiss Meditec AG exemplifies the precision optics specialist archetype through its embedded relationships with German-speaking university clinics. Rayner Group represents the regional champion model, anchoring premium toric differentiation within private ophthalmic settings. These three patterns illustrate how regulatory compliance depth and channel access stratify competitive positioning under tightened MDR requirements.
| Leading Market Players |
|---|
| Alcon Inc. |
| Bausch & Lomb Incorporated |
| Johnson & Johnson Vision Care, Inc. |
| Carl Zeiss Meditec AG |
| HOYA Corporation |
| Rayner Group |
| STAAR Surgical |
| SIFI S.p.A |
| PhysIOL |
| Others |
Supply & Pricing Matrix
Optical polymer chemist concentrations in the Netherlands and southern Germany create labor-cost differentials that widen pricing-tier spreads between premium hydrophobic acrylic platforms and economy-grade alternatives. CE marking under MDR compliance costs concentrate in higher-tier products, compressing mid-market positioning.
Pricing Analysis
Warranty and surgical training bundling separates premium toric and multifocal pricing from unbundled monofocal transactions in public hospital procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments under framework agreements. Cost compression in standard-tier hydrophobic acrylic is intensifying because notified body capacity constraints extend MDR approval timelines. Ambulatory surgical centers in Germany and the Netherlands show highest price sensitivity, while private ophthalmic clinics in Switzerland absorb premium markups.
Supply Chain Analysis
High-purity optical-grade acrylic resin supply rests on Dutch petrochemical producers and German polymerization specialists with captive optical monomer capabilities. Feedstocks draw from naphtha crackers in Rotterdam and Antwerp, with finishing operations sourcing precision-machined haptic loops from Swiss micro-component manufacturers. Single-source vulnerability concentrates in optical-grade monomer supply where two European producers dominate MDR-compliant material certification. Distribution runs through manufacturer-direct field organizations for hospital chains, supplemented by MDR-authorized distributors serving mid-tier manufacturers in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity bottlenecks in Berlin and Munich prop pricing for MDR-certified manufacturers, creating supply-constrained conditions that favor incumbents with established technical documentation.
For Market Incumbents: Anchor market position through backward integration into optical-grade monomer production, securing captive supply against feedstock volatility while extending certification timelines for competitors. Deepen hospital system partnerships in France and Italy through bundled viscoelastic-and-lens framework agreements that raise switching costs for procurement committees. For New Entrants and Emerging Players: Private ophthalmic clinics in Poland and Romania represent underserved buyer archetypes where out-of-pocket payment models bypass reimbursement ceilings constraining public hospital penetration. Target ambulatory surgical center expansion corridors with streamlined toric inventory and rapid replenishment logistics, leveraging distributor relationships to avoid field force investment. For Investors and Strategic Acquirers: Re-rating potential sits with precision optics specialists possessing embedded university clinic relationships given wavefront-optimized design adoption accelerating referral patterns. Long-term viability favors manufacturers with MDR-compliant post-market surveillance infrastructure and direct sales density in German-speaking markets. Watch notified body designation expansion as inflection indicator for competitive timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR certification under EMA coordination validates clinical evidence packages for implantable optics. |
| Hospital System Partnership | French GPO framework agreements bundle lenses with consumables, locking in multi-year volume commitments. |
| Backward Integration | Captive optical monomer production insulates margin stability from petrochemical feedstock volatility. |
| Software Companion Development | Digital surgical planning platforms differentiate toric alignment protocols in university clinic settings. |
| Reimbursement Strategy | Private payment model positioning in Poland bypasses national health system ceilings constraining premium uptake. |
Research Methodology
Multi-period observation of cataract procedural volumes, MDR certification timelines, and hospital procurement contract renewals anchored the trend analysis, supplemented by interviews with cataract surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from EMA medical device databases, ANSM post-market surveillance reports, national health reimbursement schedules, and SEC filings of listed ophthalmic manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, end user, and distribution channel dimensions.
Segment-weighting approaches applied differential growth assumptions to hydrophobic acrylic versus hydrophilic alternatives, and to ambulatory surgical center versus hospital procurement channels. CAGRs were derived from regression analysis of historical procedural volume trends against demographic projections, adjusted for reimbursement stability indices across member states. Forecast inputs incorporated notified body capacity constraints, F-Gas Regulation compliance deadlines, and CSRD supply chain disclosure requirements.
Revisions become necessary when notified body designation expansion accelerates, EMA tightens biocompatibility testing protocols, or national reimbursement frameworks shift premium lens coverage. Forecasts reflect assumptions about MDR implementation pacing and procurement consolidation trajectories. A small set of named triggers—regulatory capacity expansion, reimbursement tier adjustments, and green chemistry retrofit deadlines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Pen Needles Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Global Cardiac Resuscitation Device Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Trocars Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Vaginal Specula Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Medication Management System Market